
 AI in Media and Entertainment Market | 2026-2036
AI in Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Media and Entertainment Market Intelligence
The EU AI Act is repositioning the cost-of-entry calculus for media platforms deploying algorithmic curation across European markets. Google LLC leverages its foundation-model infrastructure to sustain dominance in generative video tooling. NVIDIA Corporation anchors high-performance compute supply for real-time rendering pipelines.
AI in media and entertainment encompasses machine-learning systems that process multimodal data streams—audio, visual, and textual metadata—to automate production workflows, personalize distribution, and optimize audience engagement metrics. These systems typically operate on transformer architectures with billions of parameters, trained on licensed content libraries to generate synthetic media or predict consumption patterns. Content creation tools currently lead investment flows, while recommendation engines concentrate margin pools through recurring SaaS contracts with streaming services. Computer vision applications in film production represent the fastest-expanding segment, driven by demand for automated visual-effects generation.
The Federal Communications Commission and the European Union's AI Act framework jointly shape market access conditions for automated content systems, with the former scrutinizing disclosure requirements for AI-generated political advertising and the latter mandating risk-classification protocols for recommendation algorithms. China's Cyberspace Administration imposes parallel content-review obligations on algorithmic distribution platforms. Stakeholders must monitor divergence between these regulatory regimes when architecting cross-border deployment strategies for synthetic media pipelines.
Market Dynamics
Transformer-based foundation models are compressing production timelines across synthetic media pipelines, forcing studios to restructure creative workflows around generative tooling or risk cost displacement by agile competitors.
Growth Catalysts
- EU AI Act risk-classification mandates:The regulation's transparency requirements for recommendation algorithms are accelerating vendor consolidation as platforms seek compliant infrastructure partners.
- Real-time rendering demand from gaming studios:Unreal Engine and Unity developers are integrating neural radiance fields to automate asset generation, reducing manual modeling hours.
- Synthetic voice localization:Dubbing houses in India and Brazil are deploying multilingual text-to-speech systems to bypass talent scarcity in regional content markets.
Market Restraints
- GPU supply concentration:Foundry capacity at TSMC and Samsung Foundry limits training cluster availability, creating 6-9 month procurement queues for media AI startups.
- Training data licensing friction:Copyright uncertainty around scraped visual content is raising indemnification costs for generative video platforms.
- Inference energy costs:Real-time diffusion models consume 10-40x compute per frame versus traditional rendering, pressuring margins at scale.
Strategic Opportunities
- India's theatrical localization gap:Regional language film markets lack automated subtitling infrastructure, creating white space for speech-to-text vendors.
- Neural codec convergence with 5G broadcast:AI-compressed video streams enable immersive formats without bandwidth infrastructure overhaul.
- France's tax rebate schemes for virtual production:The TRIP and video game tax credits are attracting volumetric capture stage investments near Paris.
Industry Challenges
- Prompt engineering talent scarcity:Creative technologists who bridge traditional directing and generative tooling command 3-4x standard VFX supervisor rates.
- Legacy pipeline integration:Studios with entrenched Autodesk and Adobe workflows face 18-24 month retooling cycles to embed AI-native tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Media and Entertainment Market |
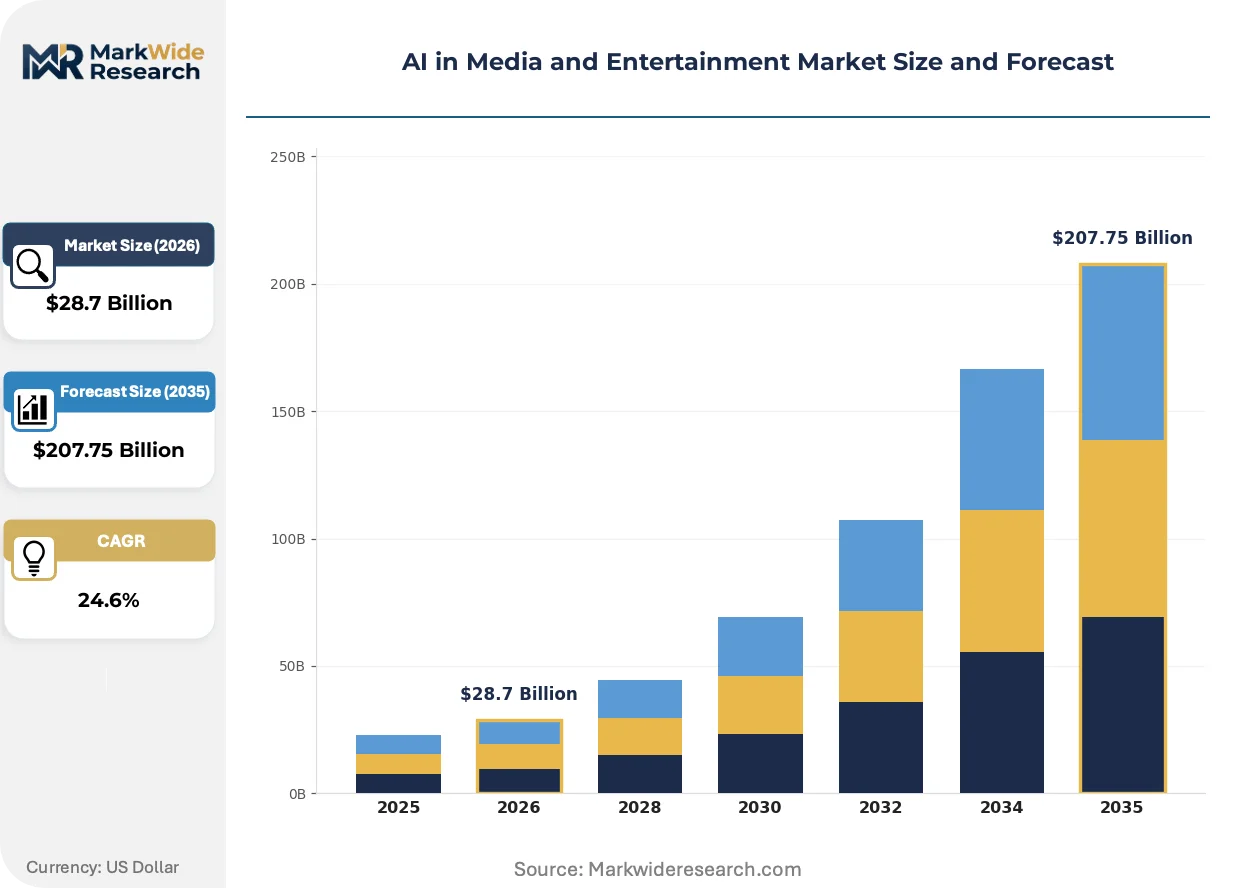
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $207.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Content Creation, Video Editing, Recommendation Engine, Analytics Tool Application: Streaming Services, Film Production, Advertising, Gaming End User: Media Companies, Advertising Agencies, Content Creators, Broadcasters Technology: Machine Learning, Natural Language Processing, Computer Vision, Deep Learning |
| Companies Covered | Amazon Web Services, Inc., IBM Corporation, Google LLC, Microsoft Corporation, NVIDIA Corporation, Adobe Inc., Veritone, Inc., Synthesia Ltd., GrayMeta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Media and Entertainment Market Strategic Shifts & Innovations
Neural rendering architectures are displacing conventional graphics pipelines, while regulatory frameworks in Brussels and Washington impose divergent compliance architectures on algorithmic distribution systems.
Diffusion-based video generation is electrifying previsualization workflows for film and television productions. Los Angeles-based production designers are adopting Midjourney and RunwayML for rapid mood-board iteration, compressing the concept-to-greenlight timeline from weeks to days. This acceleration is electrifying competitive positioning among mid-budget studios that lack legacy infrastructure sunk costs.
The EU AI Act's systemic risk designation for general-purpose AI models is mandating red-team testing and incident reporting for foundation model deployers. Media platforms operating across European markets must now maintain algorithmic audit trails for recommendation systems, increasing compliance overhead but creating moats against non-compliant entrants. Streaming services with European subscriber bases are restructuring data governance to satisfy both GDPR and the AI Act's overlapping transparency obligations.
Buyer procurement for content personalization engines is migrating from perpetual licenses to consumption-based SaaS contracts with performance guarantees. Streaming services in the Nordics and Southeast Asia are unbundling recommendation infrastructure from core platform builds, favoring best-of-breed vendors over vertically integrated stacks. This shift is most visible among second-tier platforms in South Korea and Indonesia seeking to match Netflix's engagement metrics without comparable R&D budgets.
AI in Media and Entertainment Market Segmentation
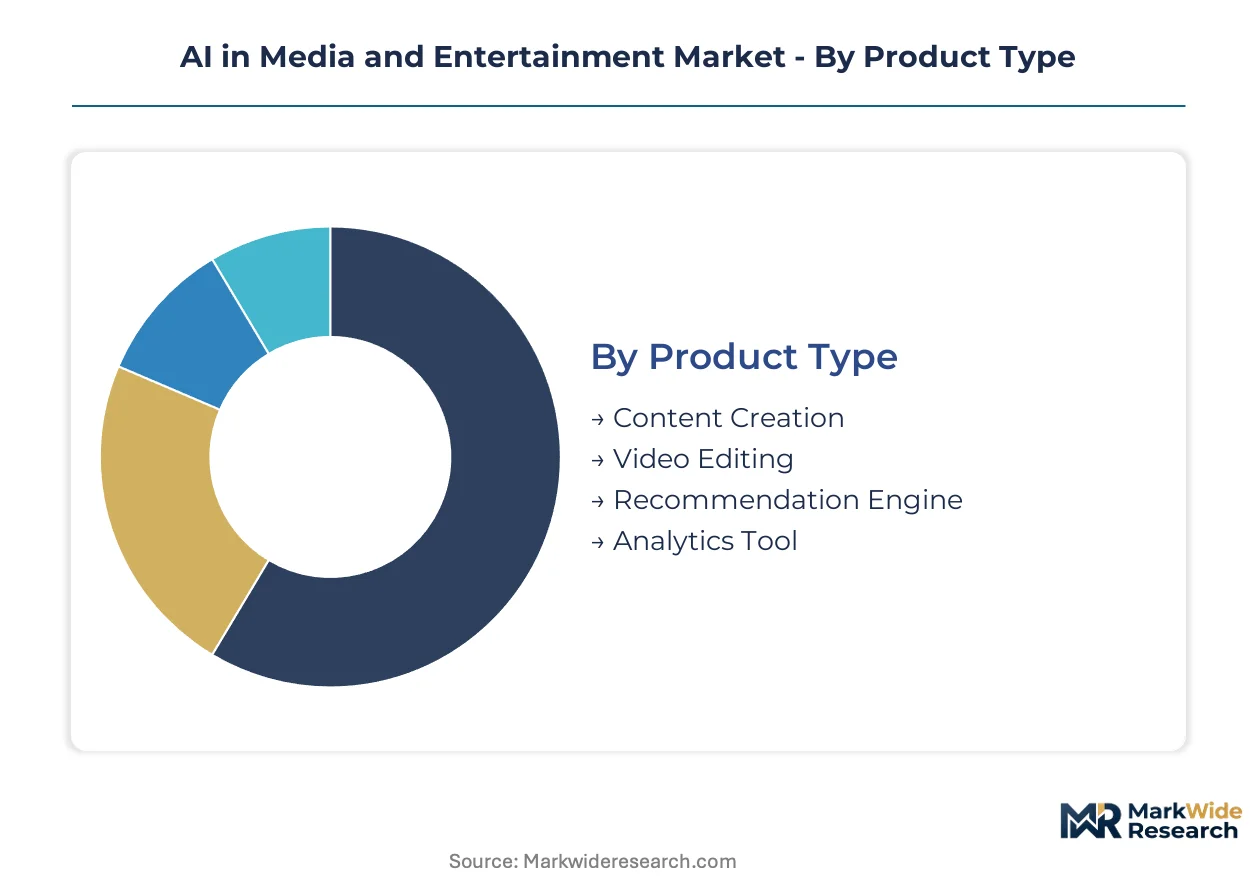
AI in media and entertainment fragments across four structural dimensions that determine deployment architecture and margin capture. Product type separates embedded workflow tools from standalone platforms. Application scope dictates whether systems serve real-time distribution or batch production cycles. These distinctions shape vendor pricing power and customer switching costs.
Product Type:
Integration depth varies sharply: standalone tools demand dedicated infrastructure while embedded modules fold into existing creative suites.
- Content Creation:Generative systems synthesize synthetic media from text prompts or reference assets, trained on licensed visual libraries. Film studios in Los Angeles and London deploy these for previsualization, cutting concept-to-greenlight timelines from weeks to days. Demand concentrates among mid-budget productions lacking legacy pipeline sunk costs.
- Recommendation Engine:Collaborative filtering and transformer architectures predict viewer preferences from behavioral signals. Streaming services in the United States and South Korea embed these as core subscriber retention infrastructure, with EU AI Act compliance now mandatory for European deployments.
- Video Editing:Automated assembly and neural-enhanced post-production tools accelerate rough-cut generation. YouTube creator economies and corporate video houses drive procurement.
- Analytics Tool:Engagement forecasting and content-performance prediction systems optimize acquisition spending. Advertising-funded platforms prioritize these for inventory pricing.
Recommendation engines lead volumes today; content creation is gaining share fastest.
Application:
Cost tier stratification separates high-infrastructure gaming deployments from lightweight advertising integrations.
- Film Production:Volumetric capture and neural rendering pipelines automate visual effects generation. Major studios in California and the United Kingdom invest heavily to compress post-production schedules.
- Streaming Services:Personalization infrastructure and content discovery systems dominate R&D budgets. Netflix, Disney+, and regional platforms in Indonesia and Brazil compete on algorithmic engagement metrics.
- Gaming:Real-time neural radiance fields and procedural asset generation reduce manual modeling hours. Unreal Engine and Unity developers in Japan and Poland integrate these for open-world environments.
- Advertising:Dynamic creative optimization and synthetic spokesperson generation enable rapid variant testing. Programmatic platforms prioritize speed-to-market over production polish.
Streaming services anchor current spending; gaming applications show steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, from enterprise media conglomerates to individual creator-operators.
- Media Companies:Vertically integrated studios deploy AI across production, distribution, and monetization stacks. Warner Bros. Discovery and Paramount Global maintain captive technology divisions.
- Content Creators:Independent YouTubers, podcasters, and TikTok producers access generative tools through SaaS subscriptions. This segment exhibits highest price sensitivity and churn rates.
- Advertising Agencies:Holding companies like WPP and Publicis Groupe build proprietary AI studios for client campaigns.
- Broadcasters:Legacy television networks in Germany, France, and India modernize playout and localization workflows.
Media companies command largest contract values; content creators represent fastest-growing user base.
Technology:
Supply concentration in foundation-model training creates dependency on NVIDIA hardware and cloud compute partnerships.
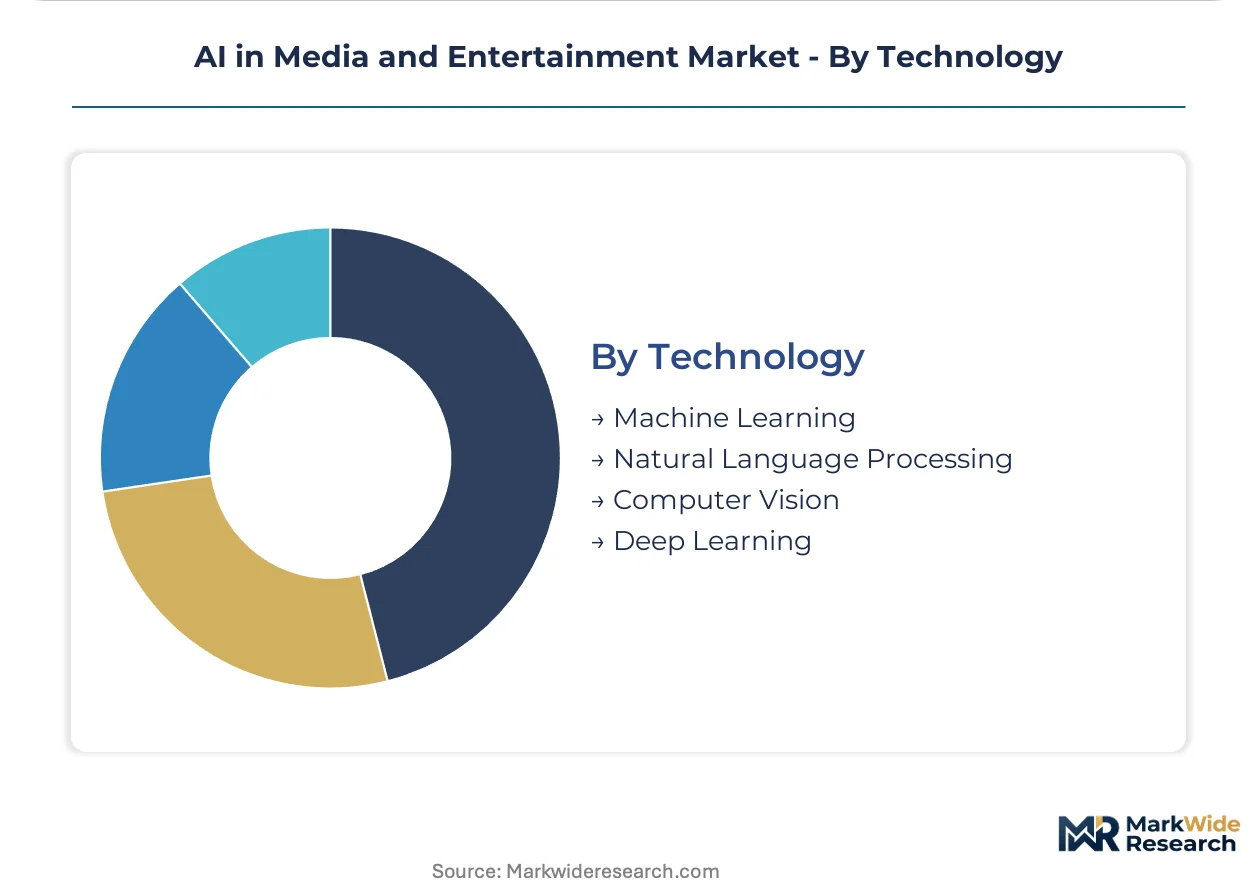
- Machine Learning:Supervised and unsupervised algorithms power recommendation and forecasting systems. These mature technologies concentrate in advertising optimization and content scheduling.
- Computer Vision:Object detection, motion tracking, and neural rendering transform production pipelines. Film and gaming studios in California, the United Kingdom, and Japan drive specialized hardware procurement.
- Natural Language Processing:Large language models automate script analysis, subtitling, and metadata tagging. Localization vendors in India and Brazil deploy multilingual systems for regional content markets.
- Deep Learning:Transformer and diffusion architectures enable generative video and audio synthesis. Training costs limit deployment to well-capitalized platforms.
Machine learning leads installed base; computer vision is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hollywood's studio system pioneered AI-assisted production workflows during the 2010s, establishing California as the industry's foundational geography before diffusion architectures democratized access across other production centers.
United States
Los Angeles production designers and Bay Area technology platforms drive parallel demand cycles for generative tooling and cloud infrastructure. The Federal Communications Commission scrutinizes disclosure requirements for AI-generated political advertising, creating compliance templates that cascade to entertainment applications. Volumetric capture stages cluster in Burbank and Culver City, where major studios deploy neural rendering for visual effects compression.
United Kingdom
London's post-production houses and Manchester's gaming studios anchor European demand for real-time rendering pipelines. The UK Information Commissioner's Office enforces GDPR-aligned transparency obligations for algorithmic recommendation systems. Pinewood Studios and Shepperton facilities integrate AI-native previsualization tools to compete with California-based production timelines.
Germany
Bavarian broadcasters and Berlin-based VFX boutiques procure automated localization and subtitling infrastructure. The EU AI Act's risk-classification mandates apply directly to German streaming platforms deploying recommendation algorithms. Hamburg's advertising technology cluster experiments with synthetic spokesperson generation for rapid creative variant testing.
India
Mumbai's theatrical distributors and Bengaluru's streaming platforms face acute talent scarcity in regional language content markets. The Telecom Regulatory Authority of India imposes content-review obligations on algorithmic distribution systems. Chennai's dubbing houses deploy multilingual text-to-speech systems to bypass voice actor bottlenecks in Tamil and Telugu markets.
Japan
Tokyo's gaming studios and Osaka's animation houses integrate neural radiance fields into Unreal Engine and Unity pipelines. The Ministry of Economy, Trade and Industry promotes AI adoption through R&D subsidies and standards harmonization. Kyoto's legacy animation studios face 18-24 month retooling cycles to embed generative tools alongside entrenched Adobe workflows.
AI in Media and Entertainment Market Key Industry Players
The competitive structure tilts toward hyperscale cloud providers with captive foundation-model infrastructure. Vendor consolidation accelerates as EU AI Act compliance costs disproportionately burden mid-tier platforms. Three archetypes dominate: vertically integrated technology conglomerates, specialized generative media startups, and legacy creative software vendors adapting to transformer architectures. M&A activity concentrates around talent acquisition for prompt engineering capabilities, while strategic partnerships proliferate between studios and compute providers to secure GPU allocation.
Among hyperscale infrastructure operators, Google LLC, Microsoft Corporation, and NVIDIA Corporation exemplify distinct positioning within the competitive matrix. Google anchors generative video tooling through foundation-model infrastructure. Microsoft leverages enterprise cloud relationships to embed media AI within productivity suites. NVIDIA occupies the supply-constrained layer, where foundry partnerships determine training cluster availability for downstream deployers.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| IBM Corporation |
| Google LLC |
| Microsoft Corporation |
| NVIDIA Corporation |
| Adobe Inc. |
| Veritone, Inc. |
| Synthesia Ltd. |
| GrayMeta |
| Others |
Cost & Logistics Intelligence
GPU foundry capacity at TSMC and Samsung Foundry feeds through to SaaS subscription tiers for generative video platforms, with procurement queues stretching 6-9 months and compressing margins for mid-tier vendors unable to secure allocation.
Pricing Analysis
Consumption-based SaaS contracts with performance guarantees dominate streaming service procurement, replacing perpetual licenses. Price differentiation rests on inference throughput tiers and EU AI Act compliance bundling. Pricing pressure stems from inference energy costs running 10-40x traditional rendering per frame. Independent content creators exhibit highest price sensitivity; major studios with captive infrastructure show lowest.
Supply Chain Analysis
Prompt engineering talent scarcity in California and London constrains deployment velocity for neural rendering pipelines. Hardware supply concentrates in Taiwan, South Korea, and the United States. Training clusters draw from NVIDIA H100 GPUs, high-bandwidth memory modules, and liquid cooling systems. Single-source vulnerability around TSMC's 4nm process node threatens cluster availability. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between the EU AI Act's compliance costs and India's TRAI content-review obligations creates geographic cost differentials for algorithmic distribution platforms.
For Market Incumbents: Cement dominance through backward integration into GPU allocation partnerships with foundry operators, insulating against 6-9 month procurement queues. Lock streaming services into multi-year SaaS contracts with EU AI Act compliance guarantees before mid-tier vendors achieve certification. The threat of agile competitors with lower legacy infrastructure sunk costs demands preemptive channel control.
For New Entrants and Emerging Players: Enter via India's regional language dubbing automation gap, where Tamil and Telugu markets lack multilingual text-to-speech infrastructure. Target second-tier streaming platforms in Indonesia and South Korea seeking to match Netflix engagement metrics without comparable R&D budgets. A best-of-breed recommendation engine positioned as EU AI Act-compliant from inception offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act compliance costs disproportionately burden mid-tier platforms without captive foundation-model infrastructure. Long-term viability favors hyperscale cloud providers with vertical integration into training clusters and enterprise distribution relationships. The signal to watch is GPU foundry allocation announcements, which determine downstream vendor survival.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Model Partnership | Google's infrastructure sustains generative video tooling dominance against specialized challengers. |
| GPU Allocation Securement | NVIDIA's foundry partnerships determine training cluster availability for downstream deployers. |
| EU AI Act Compliance Certification | Streaming services mandate algorithmic audit trails, creating moats against non-compliant entrants. |
| Regional Localization Infrastructure | India's theatrical distributors automate subtitling to bypass talent scarcity in regional markets. |
| Neural Codec Integration | AI-compressed video streams enable immersive formats without 5G bandwidth infrastructure overhaul. |
Research Approach
Direct dialogue with streaming platform CTOs, Los Angeles production VFX supervisors, Indian dubbing house operators, and EU regulatory affairs specialists grounded qualitative findings. Secondary validation drew from SEC filings of hyperscaler cloud providers, EU AI Act implementation guidance, TRAI content-review circulars, and NVIDIA datacenter revenue disclosures. Bottom-up and top-down triangulation cross-checked vendor pricing surveys against aggregate infrastructure spending patterns.
Bottom-up modeling aggregated individual platform deployments across streaming services, gaming studios, and advertising networks. Segmentation dimensions included product type, application scope, end-user archetype, and technology layer. CAGRs derived from curve-fitting historical infrastructure investment trajectories against projected content volume growth. Industry-specific inputs encompassed GPU foundry capacity expansion schedules and EU AI Act compliance timeline assumptions.
Inputs from hyperscaler capex disclosures and regulatory implementation guidance were available through the study window; gaps in private vendor contract terms introduce uncertainty bands around pricing tier estimates. Forecasts reflect documented assumptions regarding foundry yield rates and streaming subscriber growth. Material deviation in GPU allocation announcements or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market