
 Europe Immersive Entertainment Market | 2026-2036
Europe Immersive Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Immersive Entertainment Market Insights
Real-time spatial computing is reshaping how immersive entertainment systems are architected across Europe. Meta Platforms leverages its Reality Labs infrastructure to anchor headset development for European consumers. Sony dominates cinematic VR content pipelines through its PlayStation Studios network. Qualcomm positions its Snapdragon XR platforms as the reference silicon for low-latency rendering in regional device manufacturing.
Europe Immersive Entertainment encompasses digitally mediated experiences that blend physical and virtual environments through head-mounted displays, spatial audio arrays, and haptic feedback systems operating at sub-20ms motion-to-photon latency. These systems serve commercial venues, consumer households, and institutional training facilities by substituting or augmenting physical presence with computationally generated sensory stimuli. Virtual Reality leads product type deployment in location-based entertainment chains, while Mixed Reality captures expanding margin pools in corporate training budgets. Spatial Audio technology differentiates premium installations as venues compete on sensory fidelity rather than display resolution alone.
The EU AI Act, GDPR, and CE marking under the Machinery Directive collectively govern biometric data collection, algorithmic transparency, and hardware safety certification for immersive devices sold across member states. EMA guidelines on digital therapeutics and France's CNIL enforcement on eye-tracking data further constrain how healthcare and consumer applications process physiological signals. Stakeholders must monitor whether Brussels extends CSRD sustainability reporting to cover embodied carbon in XR hardware supply chains.
Market Dynamics
Spatial computing latency requirements below 20ms motion-to-photon are forcing venue operators to rebuild infrastructure around edge rendering nodes rather than cloud-streamed content. This technical threshold separates premium location-based entertainment from consumer-grade deployments.
Growth Catalysts
- EU AI Act biometric governance:Privacy-preserving eye-tracking architectures are becoming mandatory specifications for hardware vendors seeking CE marking approval across member states.
- Theme park capital deployment:German and French operators are retrofitting dark rides with haptic feedback floors and spatial audio arrays to extend dwell time per visitor.
- London creative cluster concentration:United Kingdom-based studios supply cinematic VR pipelines to continental venue chains, creating content export momentum.
Market Restraints
- GDPR physiological data friction:France's CNIL enforcement on gaze-vector retention limits real-time personalization in retail installations.
- XR silicon supply concentration:Snapdragon XR platform dependency creates single-source risk for regional device assemblers.
- Embodied carbon disclosure pressure:Anticipated CSRD extension to hardware supply chains threatens margin compression for headset manufacturers.
Strategic Opportunities
- Healthcare digital therapeutics pathway:EMA guidelines on VR-based rehabilitation create reimbursement tailwinds for clinical-grade immersive systems.
- Corporate training budget capture:Mixed Reality modules for hazardous environment simulation are displacing physical mockup construction in energy and aviation sectors.
- Spatial audio premium tiering:Wave-field synthesis installations differentiate high-end London and Paris venues competing on sensory fidelity metrics.
Industry Challenges
- Motion sickness mitigation engineering:Sub-20ms latency maintenance requires specialized optical engineers scarce across European labor markets.
- CE marking timeline compression:Machinery Directive conformity assessment delays hardware launches by 8-14 months versus consumer electronics cycles.
- Legacy AV infrastructure integration:Venue operators face cabling and power reconfiguration costs when retrofitting haptic systems into 1990s-era attraction shells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Immersive Entertainment Market |
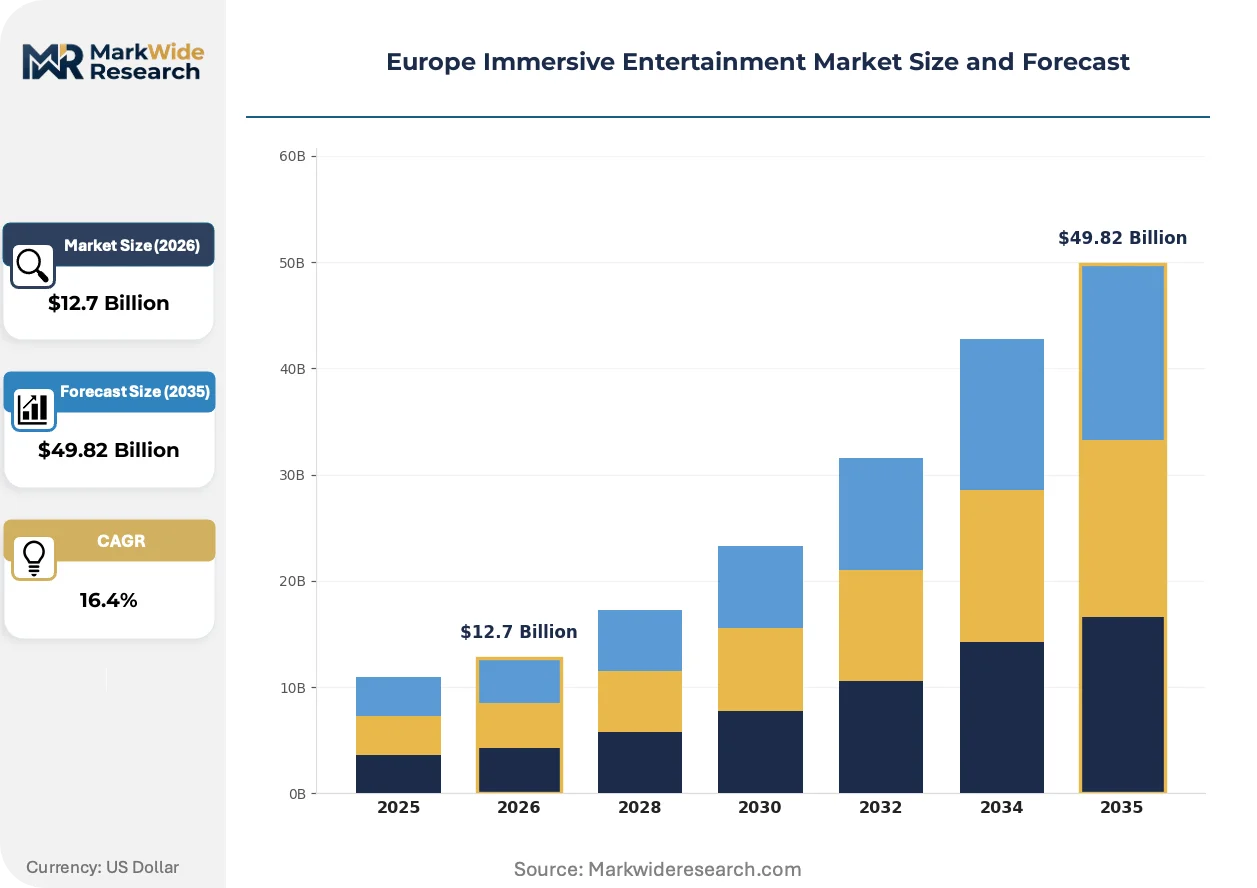
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $49.82 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Mixed Reality, 360-Degree Video End User: Gaming Industry, Education, Corporate Training, Healthcare Content Type: Films, Video Games, Simulations, Interactive Experiences Technology: Head-Mounted Displays, Motion Capture, Spatial Audio, Haptics |
| Companies Covered | Meta Platforms Inc, Microsoft Corporation, Sony Corporation, HTC Corporation, Barco NV, Samsung Electronics Co Ltd, Apple Inc, Qualcomm Incorporated, Unity Software Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Immersive Entertainment Market Trends and Innovations
Immersive entertainment architecture is pivoting from display-centric to sensory-fidelity-centric competition. Venues now differentiate through integrated haptic, olfactory, and spatial audio layers rather than resolution specifications alone.
Foveated rendering with dynamic resolution scaling is virtualizing high-fidelity visual experiences without proportional GPU cost escalation. Theme park operators in the United Kingdom and Germany are adopting this technique to maintain throughput while reducing per-station hardware investment. The technology is virtualizing the economics of premium immersive deployment, compressing the capital gap between flagship and mid-tier installations.
The EU AI Act's algorithmic transparency requirements are forcing biometric inference engines into on-device processing architectures. Hardware vendors must now certify that eye-tracking and facial analysis occur without cloud transmission to achieve CE marking. Healthcare applications under EMA digital therapeutics pathways face the strictest compliance burden, with France's CNIL already issuing enforcement precedents on gaze data retention limits.
Corporate training procurement is consolidating around outcome-validated immersive modules rather than per-seat licensing. Energy sector buyers in Germany and aviation operators in France now demand competency-verification metrics before contract renewal. This specification shift favors vendors with embedded assessment analytics, displacing content-only studios from enterprise accounts.
Europe Immersive Entertainment Market Segmentation
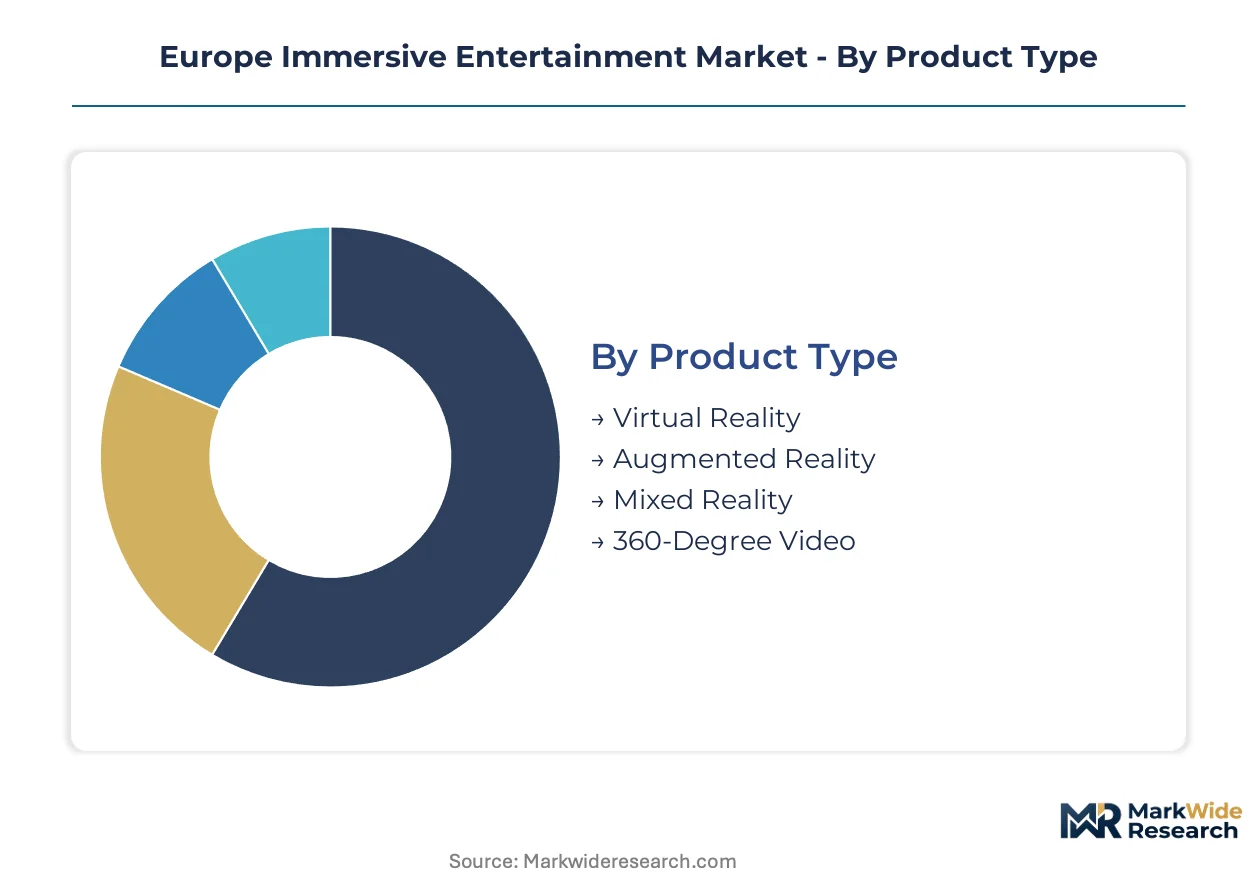
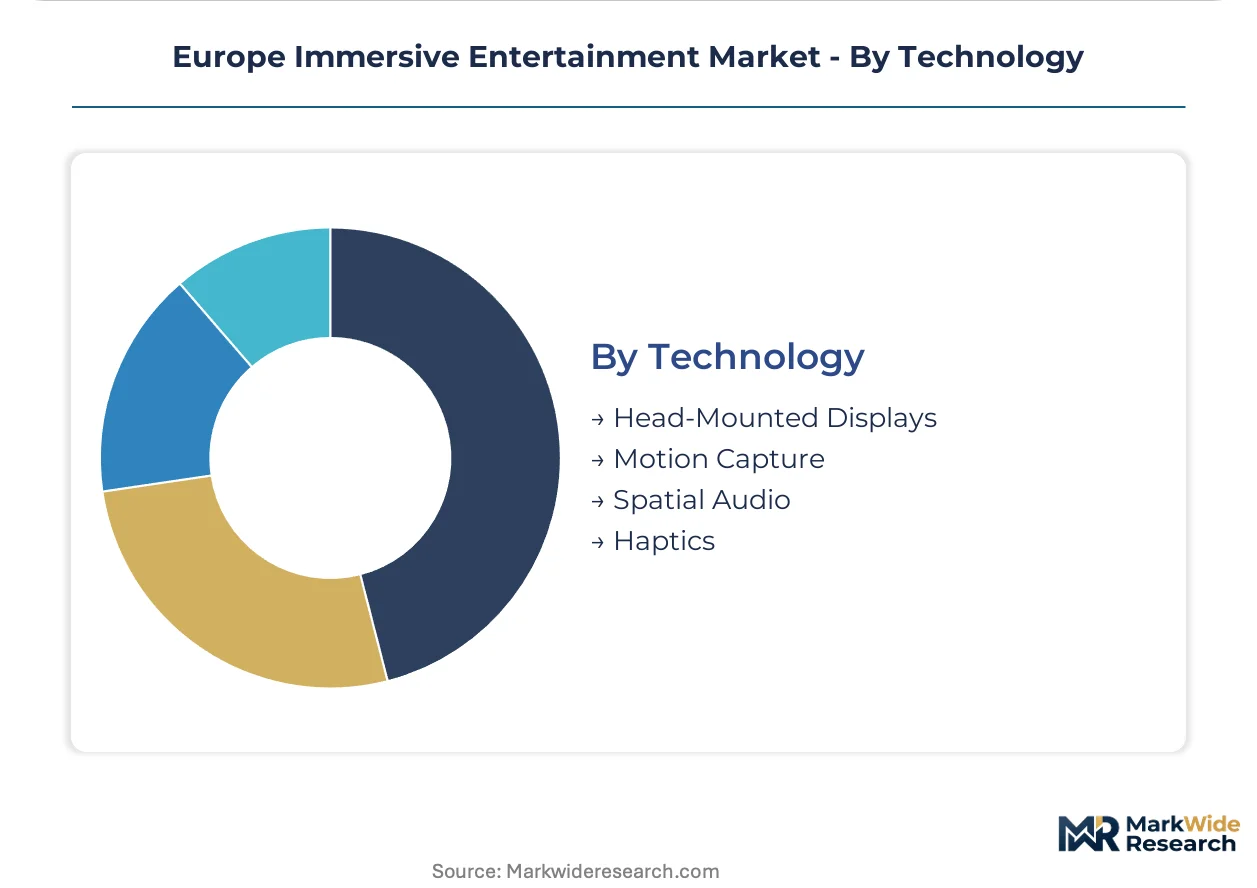
Segmentation in Europe's immersive entertainment market reveals how technical specifications, application contexts, and sensory modalities create distinct procurement patterns. Buyers across German theme parks, French healthcare systems, and UK creative studios prioritize different performance thresholds and compliance frameworks when selecting immersive systems.
Product Type:
Cost tier differentiation separates consumer-accessible hardware from enterprise-grade installations requiring specialized infrastructure.
- Virtual Reality:Fully enclosed head-mounted displays block ambient light to maximize presence. German location-based entertainment chains deploy VR in retrofitted dark rides to extend visitor dwell time per attraction.
- Mixed Reality:Passthrough cameras overlay digital content onto physical environments. Corporate training budgets in France and the United Kingdom favor MR for hazardous environment simulation where spatial awareness of real equipment matters.
- Augmented Reality:Smartphone and tablet-based overlays dominate retail and museum applications with lower hardware investment requirements.
- 360-Degree Video:Spherical capture formats serve cinematic distribution through venue-based panoramic screens rather than individual headsets.
Virtual Reality commands the established base. The steepest expansion runs through Mixed Reality.
End User:
Application context determines latency tolerance, biometric data handling requirements, and procurement authority structures.
- Gaming Industry:Location-based entertainment venues and home console ecosystems drive volume. UK studios supply cinematic VR content pipelines to continental European venue operators seeking differentiated attractions.
- Corporate Training:Energy sector buyers in Germany and aviation operators in France demand competency-verification metrics embedded within immersive modules. Outcome-based procurement is displacing per-seat licensing models.
- Education:Institutional budgets prioritize durable hardware with simplified content management systems for classroom deployment.
- Healthcare:EMA guidelines on digital therapeutics create reimbursement pathways for clinical-grade VR rehabilitation systems in France and Germany.
Gaming Industry absorbs the dominant share of hardware shipments. Healthcare registers the most rapid reimbursement tailwind acceleration.
Content Type:
Volume economics and production complexity create divergent margin structures across immersive media formats.
- Video Games:Interactive engines with real-time rendering requirements demand highest computational investment. UK-based developers anchor European supply for location-based multiplayer experiences.
- Simulations:Physics-accurate environments serve industrial training and defense applications with extended development cycles but multi-year contract renewals.
- Films:Pre-rendered spherical video offers lower interactivity but reduced per-user hardware requirements for venue operators.
- Interactive Experiences:Hybrid formats blending narrative direction with user agency occupy premium positioning in London and Paris cultural institutions.
Video Games sustain the largest installed base. Simulations capture the fastest margin expansion as corporate buyers consolidate procurement.
Technology:
Supply concentration in specialized components creates single-source risk for regional device assemblers.
- Head-Mounted Displays:Optical stack engineering and sub-20ms motion-to-photon latency define competitive performance. CE marking timelines under the Machinery Directive extend hardware launch cycles by 8-14 months versus consumer electronics norms.
- Spatial Audio:Wave-field synthesis arrays differentiate premium London and Paris venue installations competing on sensory fidelity rather than display resolution alone.
- Motion Capture:Optical and inertial tracking systems enable full-body avatar control in multiplayer location-based entertainment.
- Haptics:Force-feedback floors and wearable arrays extend immersion beyond visual and auditory channels in German theme park retrofits.
Head-Mounted Displays represent the dominant hardware investment category. Spatial Audio is climbing the fastest as venues compete on sensory differentiation metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Immersive entertainment content flows from London's creative cluster toward continental venue operators, creating a trade surplus in IP exports against hardware import dependency on Asian and American component suppliers.
United Kingdom
London anchors European content production for cinematic VR pipelines serving German and French venue chains. UK creative studios face GDPR compliance costs when exporting gaze-tracking analytics to continental clients. Manchester's MediaCityUK hosts specialized spatial audio engineering firms supplying wave-field synthesis arrays to Parisian cultural institutions.
Germany
Bavarian theme park operators retrofit dark rides with haptic feedback floors to extend visitor dwell time per attraction. CE marking under the Machinery Directive extends hardware launch cycles by 8-14 months versus consumer electronics norms. Berlin's startup ecosystem concentrates privacy-preserving eye-tracking architectures responding to EU AI Act biometric governance requirements.
France
Healthcare digital therapeutics create reimbursement pathways for clinical-grade VR rehabilitation systems under EMA guidelines. CNIL enforcement on gaze-vector retention limits real-time personalization in retail immersive installations. Parisian cultural institutions compete on sensory fidelity metrics through premium spatial audio tiering.
Netherlands
Randstad region hosts specialized optical engineering talent scarce across broader European labor markets for sub-20ms latency maintenance. Dutch regulators align with CE marking timelines while supporting cross-border content distribution through EU digital single market frameworks. Eindhoven's hardware ecosystem supplies edge rendering node components to UK venue operators.
Spain
Catalonia's location-based entertainment venues adopt foveated rendering techniques to maintain throughput while reducing per-station hardware investment. Spanish operators import cinematic VR content from UK studios rather than developing domestic pipelines. Barcelona's technology cluster focuses on 360-degree video capture for tourism applications.
Europe Immersive Entertainment Market Competitive Landscape
On the supply side, the industry is consolidating around platform holders controlling silicon reference designs and content distribution infrastructure. Three strategic archetypes dominate: headset-integrated ecosystem operators, component-level silicon suppliers, and specialized venue hardware fabricators. Competitive moves center on vertical integration into optical stack engineering and strategic partnerships with European content studios seeking GDPR-compliant processing architectures.
Within the ecosystem-operator tier, Meta Platforms Inc and Sony Corporation exemplify divergent geographic strategies. Meta leverages its Reality Labs infrastructure to anchor headset development for European consumers while navigating Brussels algorithmic transparency requirements. Sony dominates cinematic VR content pipelines through its PlayStation Studios network, exporting IP to continental venue chains. Microsoft Corporation occupies a position bridging enterprise Mixed Reality deployment with cloud-edge hybrid architectures for corporate training applications in France and Germany.
| Leading Market Players |
|---|
| Meta Platforms Inc |
| Microsoft Corporation |
| Sony Corporation |
| HTC Corporation |
| Barco NV |
| Samsung Electronics Co Ltd |
| Apple Inc |
| Qualcomm Incorporated |
| Unity Software Inc |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Frankfurt rail freight corridors carry Snapdragon XR chipsets from Dutch distribution hubs into German assembly plants, with per-unit logistics costs now representing 8-12% of landed hardware prices across consumer and enterprise tiers. This corridor's cost volatility directly amplifies price spreads between premium venue installations and mid-tier consumer headsets, while compressing margins for regional device assemblers locked into Qualcomm's silicon reference designs.
Pricing Analysis
Prior-generation VR headsets trade at 40-50% discounts against current-generation Mixed Reality units with passthrough camera arrays, while next-generation foveated rendering systems command 25-35% premiums for venue operators seeking throughput optimization. Pricing stratifies across premium, standard, and economy tiers where CE marking certification under the Machinery Directive adds 15-20% to compliant hardware versus consumer-grade imports. Cost compression in the standard tier is intensifying because German theme park operators now demand outcome-validated procurement with embedded assessment analytics. Gaming venues exhibit highest price sensitivity, while French healthcare systems under EMA digital therapeutics pathways accept premium positioning for clinical-grade rehabilitation systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for European headset assemblers sourcing optical waveguides and micro-OLED displays. Manufacturing concentrates in Taiwan for display panels, China for haptic actuator components, and South Korea for advanced semiconductor packaging. Raw material dependencies span rare earth elements for magnet arrays in motion tracking systems, gallium substrates for micro-LED backplanes, and specialized polymers for lightweight headset chassis. Single-source vulnerability runs through Qualcomm's Snapdragon XR platform monopoly for sub-20ms latency silicon. Distribution runs through Dutch logistics hubs serving German venue chains and UK creative studios with consolidated freight forwarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities abound as corporate training buyers displace per-seat licensing with outcome-validated procurement, creating niches for embedded analytics specialists. Venue operators' sensory-fidelity competition opens margin pools beyond display-centric hardware commoditization.
For Market Incumbents: Pre-empt cloud-rendering challengers by anching edge node deployments in UK and German venue chains before 5G latency improvements mature. Defensive consolidation should prioritize backward integration into optical stack engineering to reduce dependency on Asian waveguide suppliers. CE marking timeline acceleration through pre-submission engagement with notified bodies represents a certification lever against faster consumer electronics cycles.
For New Entrants and Emerging Players: Establish a beachhead in spatial audio engineering for London and Paris cultural institutions competing on sensory fidelity differentiation. White-space targets include privacy-preserving eye-tracking architectures responding to EU AI Act biometric governance, and haptic feedback floor retrofits for German dark ride operators. Go-to-market positioning should emphasize GDPR-compliant on-device processing to displace cloud-dependent incumbents in healthcare and retail installations.
For Investors and Strategic Acquirers: Optical engineering boutiques with sub-20ms latency specialization represent the most defensible acquisition archetype given talent scarcity across European labor markets. Long-term viability frames around 5-10 year windows where reimbursement tailwinds from EMA digital therapeutics guidelines institutionalize clinical-grade immersive systems. The signal to watch is CNIL enforcement precedent expansion beyond France into broader gaze-vector retention limitations.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Pre-submission engagement with Machinery Directive notified bodies compresses hardware launch cycles by 4-6 months. |
| Spatial Audio Tiering | Wave-field synthesis installations differentiate premium London and Paris venues competing on sensory fidelity metrics. |
| Privacy-Preserving Architecture | On-device eye-tracking processing achieves EU AI Act biometric compliance without cloud transmission risks. |
| Outcome-Based Procurement | Competency-verification analytics embedded in corporate training modules displace per-seat licensing models. |
| Edge Rendering Deployment | Localized processing nodes maintain sub-20ms latency for German theme park operators retrofitting dark rides. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with theme park operations directors, healthcare technology procurement leads at French hospital systems, UK creative studio technical directors, German corporate training buyers in energy and aviation sectors, and spatial audio engineering specialists in Manchester's MediaCityUK cluster. Secondary validation drew from EMA digital therapeutics guideline documents, CNIL enforcement precedents on biometric data retention, CE marking notification databases under the Machinery Directive, and venue operator capital expenditure disclosures. Bottom-up unit economics triangulated against top-down market sizing across hardware shipments and content licensing flows.
Calibration approaches anchored volume projections to disclosed retrofit timelines at Bavarian theme park operators and reimbursement pathway adoption curves under EMA guidelines. Segmentation dimensions modeled include product type tier, end-user application context, content format complexity, and technology component category across the analysis window. CAGRs derived from logistic diffusion curves fitted to venue operator adoption patterns and healthcare procurement cycle data. Industry-specific forecast inputs incorporated Snapdragon XR platform release cadences and EU AI Act implementation phase timelines.
Sensitivities concentrate around CE marking timeline extensions, CNIL enforcement expansion into additional member states, and Qualcomm supply allocation decisions affecting regional device assemblers. Forecasts reflect documented assumptions regarding corporate training budget elasticity and healthcare reimbursement approval velocities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market