
 North America Immersive Entertainment Market | 2026-2036
North America Immersive Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Immersive Entertainment Market Insights
The FCC's 5G mmWave spectrum reallocation is consolidating the cost-of-entry calculus for location-based immersive venues. Microsoft Corporation leverages its Azure cloud infrastructure to sustain enterprise-grade mixed reality deployments across Canadian training centers. Sony Group Corporation anchors premium virtual reality content pipelines through its proprietary spatial audio and haptic feedback ecosystems. Meta Platforms, Inc competes aggressively on hardware subsidy models that lower headset acquisition barriers for North American consumers.
North America Immersive Entertainment encompasses digitally rendered environments that combine stereoscopic displays, spatial computing engines, and real-time sensor fusion to deliver perceptually convincing alternate realities for commercial recreation and enterprise training. These systems typically operate at 90 frames per second with sub-20 millisecond motion-to-photon latency to prevent simulator sickness in head-mounted displays. Virtual Reality and Mixed Reality command the dominant share of technology-driven revenue, though 360-Degree Video retains structural importance in live sports and concert broadcasting where production costs scale linearly rather than exponentially. Games and Interactive Experiences concentrate margin pools through recurring monetization, while Live Events face compressed margins due to venue-specific capital requirements and fragmented promoter networks.
The Federal Communications Commission governs wireless spectrum allocation that determines streaming fidelity for untethered augmented reality experiences, while the Federal Trade Commission scrutinizes data collection practices within immersive advertising frameworks. Health Canada and the Canadian Radio-television and Telecommunications Commission coordinate bilateral standards for cross-border content distribution and consumer safety certifications for head-worn devices. Stakeholders must monitor evolving privacy rulemakings that could restrict biometric gaze-tracking monetization before establishing long-term platform economics.
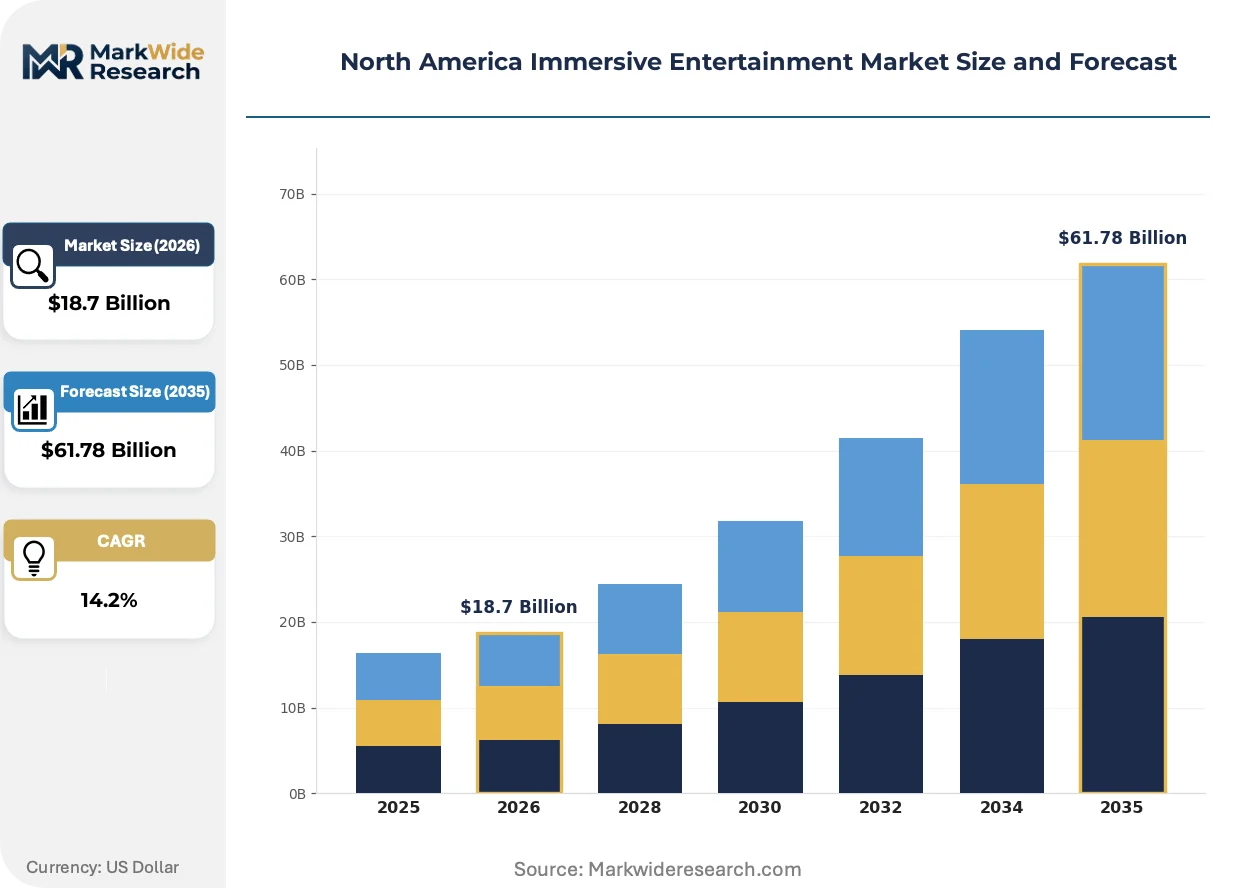
Market Dynamics
The Federal Communications Commission's 5G mmWave spectrum reallocation is compressing latency thresholds for untethered augmented reality streaming, fundamentally altering capital deployment patterns across theme park operators and live entertainment venues.
Growth Catalysts
- 5G mmWave Infrastructure:The FCC's spectrum allocation enables sub-20 millisecond motion-to-photon latency for volumetric content streaming. Theme parks in California deploy these networks to support multiplayer mixed reality attractions without tethering constraints.
- Spatial Computing Convergence:Real-time sensor fusion combining LiDAR, eye-tracking, and haptic feedback systems is elevating perceptual fidelity standards. Canadian training centers integrate these stacks for enterprise-grade simulation environments.
- Enterprise Training Demand:Healthcare and defense sectors across the United States procure immersive systems for procedural rehearsal. These contracts carry multi-year service attachments that stabilize vendor revenue streams.
Market Restraints
- Display Panel Supply Concentration:Micro-OLED and pancake lens modules concentrate among Asian component suppliers. North American headset manufacturers face allocation bottlenecks during demand surges.
- Biometric Data Friction:The Federal Trade Commission scrutinizes gaze-tracking monetization frameworks. Advertisers hesitate to deploy retinal heatmap analytics pending clarity on consent architectures.
- Simulator Sickness Thresholds:Human vestibular system limitations cap motion-to-photon latency tolerance at 20 milliseconds. Developers sacrifice graphical complexity to maintain frame rates above 90 per second.
Strategic Opportunities
- Underpenetrated Live Sports Broadcasting:360-degree video production for professional leagues remains structurally underdeveloped. Canadian broadcasters test volumetric capture for hockey replay systems with linear rather than exponential cost scaling.
- Location-Based Entertainment White Space:Secondary metropolitan markets in Texas and Florida lack dedicated immersive venues. Real estate developers partner with content studios to anchor mixed-use retail-entertainment complexes.
- Cross-Border Certification Harmonization:Health Canada and the CRTC coordinate bilateral safety standards for head-worn devices. Unified testing protocols reduce time-to-market for hardware vendors serving both national jurisdictions.
Industry Challenges
- Spatial Computing Talent Scarcity:Unity and Unreal Engine specialists with real-time optimization expertise command premium compensation. Studios in Los Angeles poach from gaming and visual effects pipelines.
- Venue-Specific Capital Intensity:Live event installations require bespoke structural engineering for motion platforms and projection mapping. Promoter networks fragment across state-level regulatory variations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Immersive Entertainment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Virtual Reality, Augmented Reality, Mixed Reality, 360-Degree Video Content Type: Games, Live Events, Simulations, Interactive Experiences User Demographic: Millennials, Gen Z, Families, Professionals Distribution Channel: Online Platforms, Retail Stores, Events, Subscription Services |
| Companies Covered | Microsoft Corporation, Apple Inc, Sony Group Corporation, Meta Platforms, Inc, Magic Leap, Inc, Samsung Electronics Co., Ltd, The Walt Disney Company, Qualcomm Inc, HTC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Immersive Entertainment Market Trends and Innovations
Volumetric capture pipelines and edge computing architectures are compressing production timelines for location-based experiences. These shifts are redistributing value from hardware manufacturers toward content studios and cloud infrastructure operators.
Light field display technology is electrifying headset form factor evolution. Sony and Meta deploy photonic chips to eliminate the vergence-accommodation conflict that causes eye strain. Enterprise buyers in medical simulation and military training accelerate procurement cycles as comfort thresholds extend beyond 30-minute sessions. The structural consequence is electrifying the displacement of Fresnel lens architectures that dominated prior generation hardware.
The Federal Trade Commission's pending rulemaking on biometric data collection is forcing architectural redesigns of immersive advertising systems. Stakeholders must implement granular opt-in frameworks for gaze heatmap analytics before deploying in retail environments. California-based location-based entertainment venues face the most immediate compliance pressure given the state's existing privacy statute density.
Consumption patterns among North American audiences are fragmenting across device categories. Console-tethered virtual reality cedes ground to standalone headsets for home use, while premium out-of-home experiences command per-capita spending multiples. Texas and Florida exhibition operators report strongest attachment rates for multiplayer mixed reality attractions that resist home replication.
North America Immersive Entertainment Market Segmentation
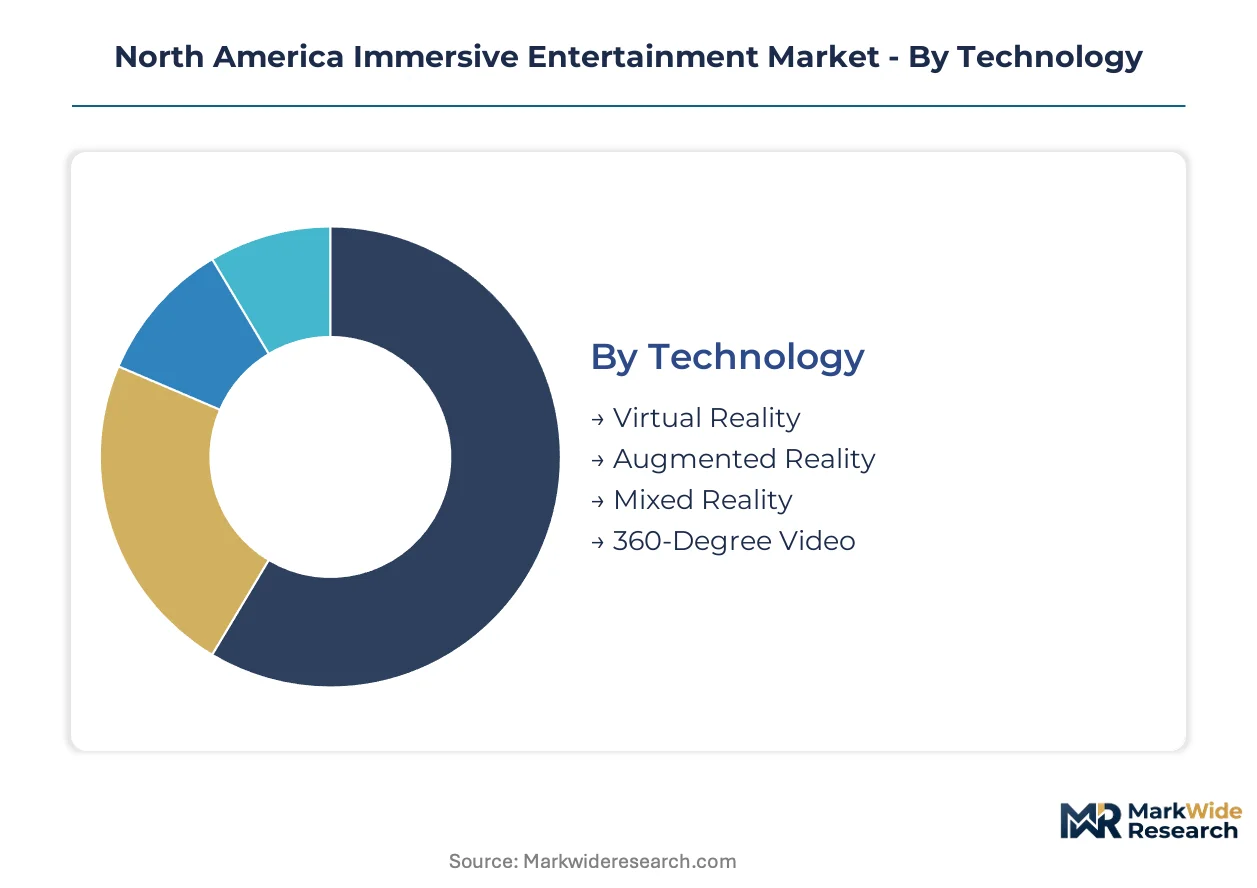
Technology selection dictates hardware procurement cycles, content development pipelines, and venue infrastructure requirements across North American immersive entertainment deployments. Buyer decisions cascade through content format, target demographic, and distribution modality, with each layer constraining monetization architecture and capital recovery timelines.
Technology:
Procurement teams evaluate latency tolerance, tethering requirements, and spatial tracking fidelity when selecting immersive hardware stacks for commercial deployment.
- Virtual Reality:Fully enclosed stereoscopic headsets operating at 90 frames per second with sub-20 millisecond motion-to-photon latency. Demand concentrates in Los Angeles and San Francisco training centers where healthcare and defense sectors procure enterprise-grade simulation environments for procedural rehearsal.
- Mixed Reality:Passthrough-enabled displays combining physical environment mapping with digital object overlay. Canadian defense contractors and Texas-based medical simulation centers drive procurement for untethered multi-user training scenarios requiring environmental awareness.
- Augmented Reality:Transparent or projection-based displays overlaying digital content onto physical surroundings. Theme park operators in California deploy these systems for location-based attractions requiring guest mobility.
- 360-Degree Video:Spherical capture and playback systems for passive immersive viewing. Sports broadcasters in Toronto and Chicago test volumetric replay integration with linear cost scaling advantages over real-time rendered alternatives.
Volume sits with Virtual Reality; growth tilts toward Mixed Reality.
Content Type:
Margin structure and capital intensity vary dramatically across production methodologies, with recurring monetization potential driving platform investment priorities.
- Games:Interactive software with controller-based or gesture-driven input systems enabling repeated play sessions. Microtransaction architectures and downloadable content pipelines concentrate revenue in California and Washington State development studios.
- Interactive Experiences:Narrative-driven environments with branching decision trees and environmental puzzle mechanics. New York and Montreal production houses specialize in museum installations and brand activations requiring bespoke content commissioning.
- Live Events:Time-bound performances incorporating volumetric capture or real-time avatar projection. Venue-specific capital requirements and fragmented promoter networks compress margins across Texas and Florida secondary markets.
- Simulations:Procedurally accurate recreations of operational environments for skill acquisition and certification. Federal training contracts through Virginia and Maryland defense corridors stabilize vendor revenue with multi-year service attachments.
Revenue concentrates in Games; steepest expansion trajectory emerges in Interactive Experiences.
User Demographic:
Spending patterns and session duration expectations shape content complexity thresholds and hardware comfort specifications.
- Gen Z:Native digital consumers aged 12-27 with high tolerance for experimental interface paradigms and social multiplayer architectures. Florida and Texas location-based venues report strongest attachment rates for competitive mixed reality attractions.
- Millennials:Consumers aged 28-43 with established console gaming histories transitioning to standalone headsets for home use. California and New York metropolitan areas show highest per-capita spending on premium out-of-home experiences.
- Professionals:Enterprise end-users in healthcare, defense, and industrial sectors procuring simulation systems for workforce development. Canadian and U.S. federal training budgets anchor demand stability.
- Families:Multi-generational household units seeking shared entertainment experiences with moderated intensity and accessibility features. Theme park operators in Orlando and Anaheim optimize for 15-30 minute session formats.
Volume sits with Millennials; growth tilts toward Gen Z.
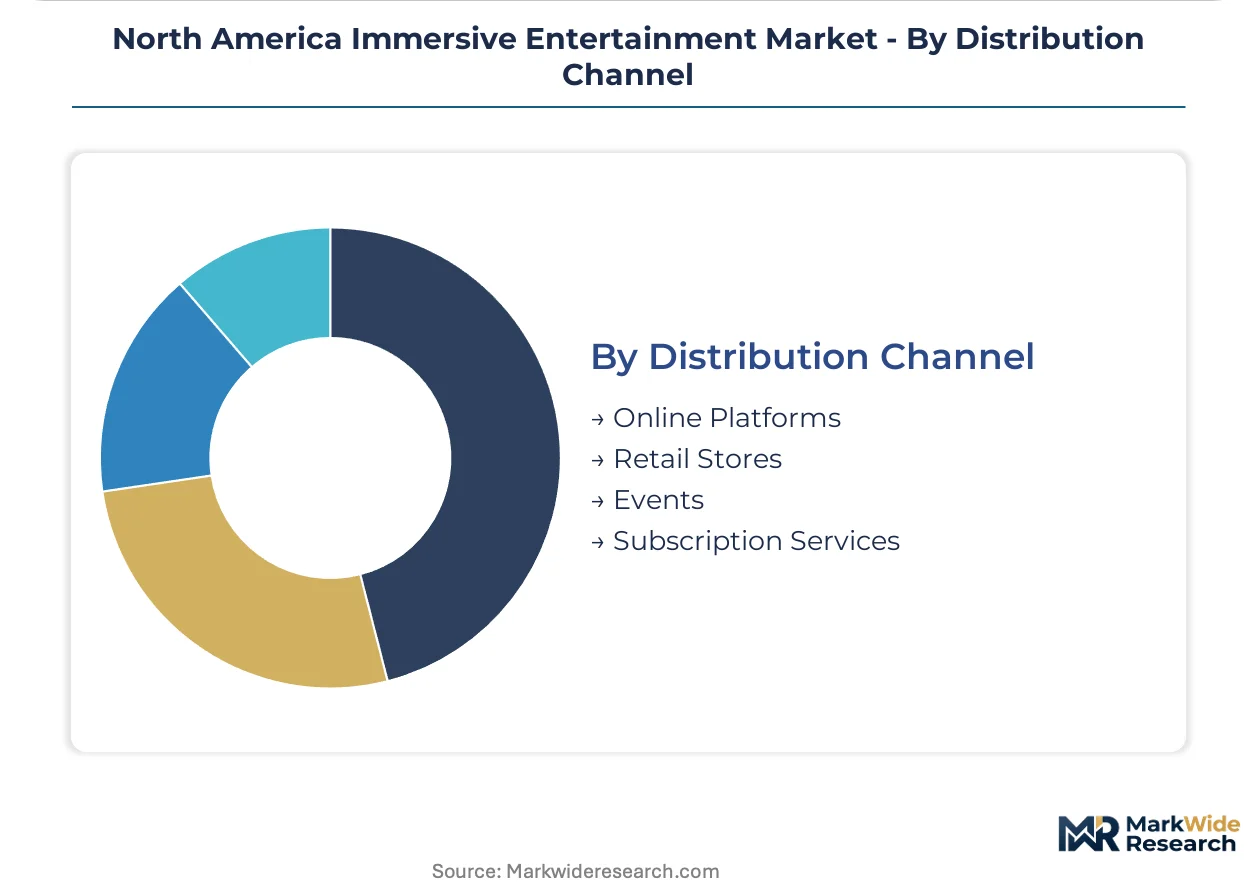
Distribution Channel:
Customer acquisition economics and lifetime value calculations diverge sharply across physical and digital touchpoints.
- Online Platforms:Digital storefronts enabling direct-to-consumer software distribution with instantaneous fulfillment. Meta and Sony maintain dominant market presence through hardware-integrated ecosystem lock-in.
- Subscription Services:Recurring revenue models bundling content libraries with hardware access or cloud streaming capabilities. Microsoft leverages Azure infrastructure to sustain enterprise-grade deployment across Canadian training centers.
- Events:Temporary or touring installations delivering premium per-capita experiences resistant to home replication. Texas and Florida exhibition operators report highest attachment rates for multiplayer attractions.
- Retail Stores:Physical demonstration environments enabling tactile evaluation before purchase commitment. Best Buy and specialized gaming retailers anchor consumer education in suburban markets.
Volume sits with Online Platforms; growth tilts toward Subscription Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's entertainment technology corridor concentrates production pipelines through state tax incentives for digital content creation. The Federal Communications Commission's 5G mmWave spectrum allocation enables sub-20 millisecond latency for volumetric streaming across major metropolitan clusters.
United States
Healthcare and defense sectors procure enterprise-grade simulation systems for procedural rehearsal with multi-year service attachments. The FCC governs wireless spectrum allocation determining streaming fidelity for untethered augmented reality experiences. Los Angeles and San Francisco anchor production pipelines for location-based immersive experiences.
Canada
Medical simulation centers and defense contractors drive procurement for untethered multi-user training scenarios requiring environmental awareness. Health Canada coordinates bilateral safety standards for head-worn devices with U.S. regulators. Toronto broadcasters test volumetric capture for hockey replay systems with linear cost scaling advantages.
Mexico
Manufacturing operations for display components and assembly operations support North American headset supply chains. The country's national telecommunications regulator manages spectrum coordination for cross-border content streaming. Mexico City metropolitan area hosts assembly facilities serving California-based hardware vendors.
North America Immersive Entertainment Market Competitive Landscape
California-based technology conglomerates anchor one tier; Asian component specialists hold supply-side influence through micro-OLED and pancake lens concentration. The vendor base organizes around three strategic archetypes: cloud infrastructure operators sustaining enterprise deployments, hardware manufacturers subsidizing consumer acquisition, and content studios commanding production pipelines. Competitive moves center on hardware-integrated ecosystem lock-in and strategic partnerships with theme park operators.
Within the cloud infrastructure tier, Microsoft Corporation represents enterprise-grade deployment capabilities across Canadian training centers. Sony Group Corporation and Meta Platforms, Inc exemplify contrasting hardware subsidy models—Sony anchors premium content pipelines through proprietary ecosystems while Meta competes aggressively on headset acquisition barriers for North American consumers.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Apple Inc |
| Sony Group Corporation |
| Meta Platforms, Inc |
| Magic Leap, Inc |
| Samsung Electronics Co., Ltd |
| The Walt Disney Company |
| Qualcomm Inc |
| HTC Corporation |
| Others |
Pricing and Supply Chain Analysis
Micro-OLED panel costs cascade through three distinct pricing tiers as display components journey from Taiwanese and South Korean fabrication facilities to California-based headset assemblers and ultimately to enterprise training centers and location-based entertainment venues across the United States and Canada.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to micro-OLED and pancake lens module procurement when Canadian medical simulation centers or Texas theme park operators bypass standard allocation queues. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in standard-tier hardware is intensifying because Asian component suppliers face allocation bottlenecks during demand surges. Enterprise training centers exhibit lowest price sensitivity due to multi-year federal contract stability, while secondary market location-based entertainment venues in Florida and Texas demonstrate highest sensitivity to per-unit hardware acquisition costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Microsoft and Meta for enterprise-grade mixed reality deployments across North American training centers. Component sourcing draws from Taiwan, South Korea, and Japan for micro-OLED displays, photonic chips, and spatial audio modules. Raw material dependencies include rare earth elements for magnet manufacturing, gallium arsenide for photonic integration, and high-purity silicon for sensor fabrication. Single-source vulnerability concentrates in advanced pancake lens manufacturing where one Japanese optics specialist controls premium-tier supply. Distribution runs through California-based integrators serving both United States federal training corridors and Canadian defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors controlling cloud infrastructure and hardware-integrated content ecosystems, with FCC spectrum rulemakings and biometric data compliance costs forcing weaker capitalized players toward exit or acquisition.
For Market Incumbents: Lock in exclusive content licensing with Los Angeles and San Francisco production studios before emerging cloud operators can replicate Azure-scale enterprise deployments. Deepen backward integration into micro-OLED supply through strategic partnerships with Taiwanese fabrication facilities to defend against allocation bottlenecks during demand surges. For New Entrants and Emerging Players: Theme park operators in Texas and Florida secondary metropolitan markets represent the most penetrable white-space opportunity, as these regions lack dedicated immersive venues despite strong Gen Z attachment rates for multiplayer mixed reality attractions. Pursue real estate development joint ventures to anchor mixed-use retail-entertainment complexes with bespoke structural engineering for motion platforms. For Investors and Strategic Acquirers: FCC finalization of biometric data consent rulemakings is the leading indicator that gaze-tracking monetization frameworks will either unlock advertising revenue streams or trigger compliance-driven consolidation among location-based entertainment operators. Target acquisition candidates with established Health Canada safety certifications and existing Azure or AWS enterprise integration pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Spatial Computing Talent Acquisition | Unity and Unreal Engine specialists command premium compensation in Los Angeles poaching wars. |
| 5G mmWave Infrastructure Partnership | Theme park operators leverage FCC spectrum allocation for untethered multiplayer attraction deployment. |
| Cross-Border Certification Harmonization | Unified Health Canada and CRTC testing protocols reduce hardware vendor time-to-market. |
| Volumetric Capture Pipeline Investment | Canadian broadcasters deploy linear-cost-scaling hockey replay systems through Toronto studios. |
| Biometric Data Compliance Architecture | Granular opt-in frameworks for gaze heatmap analytics satisfy FTC scrutiny in California venues. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with location-based entertainment venue operators, spatial computing engineers at Los Angeles production studios, FCC policy specialists, Health Canada medical device reviewers, and enterprise procurement officers at defense training centers. Triangulation combined bottom-up hardware shipment aggregation with top-down content spending estimates across the analysis window.
Data-stream reconciliation across technology adoption curves, content production timelines, and venue deployment schedules informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include immersive technology type, content format, user demographic cohort, and distribution channel architecture. CAGRs derived from curve-fitting procedures applied to hardware unit economics and recurring content monetization trajectories, with specific inputs from 5G infrastructure capex disclosures and federal training budget appropriations.
Several conditions sit outside the modeled scope, including potential FCC spectrum reallocation reversals, breakthrough light field display commercialization timelines, and bilateral trade restrictions affecting micro-OLED component flows. Forecasts reflect assumptions regarding sustained enterprise training demand and consumer headset price elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market