
 Immersive Entertainment Market | 2026-2036
Immersive Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Immersive Entertainment Market Analytics
ISO/IEC 27001 certification for information security management is collapsing as a baseline qualification for immersive entertainment platform providers seeking enterprise and institutional contracts. Meta Platforms sustains one of the largest content ecosystems through its Horizon Worlds platform and Quest hardware integration. Sony Group Corporation dominates premium location-based entertainment through its PlayStation VR2 deployments in cinema and arcade partnerships. HTC Corporation specializes in commercial-grade virtual reality systems for enterprise training and branded entertainment installations.
Immersive entertainment encompasses digitally rendered environments that envelop users through head-mounted displays, spatial audio, haptic feedback, and real-time motion tracking to create perceptual presence in synthetic or augmented spaces. Systems typically operate at 90-120 frames per second with sub-20 millisecond motion-to-photon latency to prevent simulator sickness and maintain user engagement. Virtual Reality product types currently anchor revenue as hardware refreshes drive replacement cycles among home users and entertainment venues. Head-Mounted Displays within the technology dimension capture the dominant margin pool due to semiconductor and optical component scarcity. Augmented Reality competes for fastest-growing position as smartphone-tethered and standalone glasses expand beyond early adopters into retail and live events.
The EU AI Act and GDPR constrain biometric data collection and algorithmic content personalization across European immersive entertainment deployments. The Federal Communications Commission in the United States governs wireless spectrum allocation for untethered headset communication, while the FDA oversees therapeutic and wellness applications that blur into entertainment-adjacent markets. China's Ministry of Industry and Information Technology enforces content licensing and youth protection standards that shape product roadmaps for hardware manufacturers serving that market. Stakeholders must monitor evolving interoperability standards between proprietary content ecosystems and open rendering frameworks to preserve capital flexibility across platform transitions.
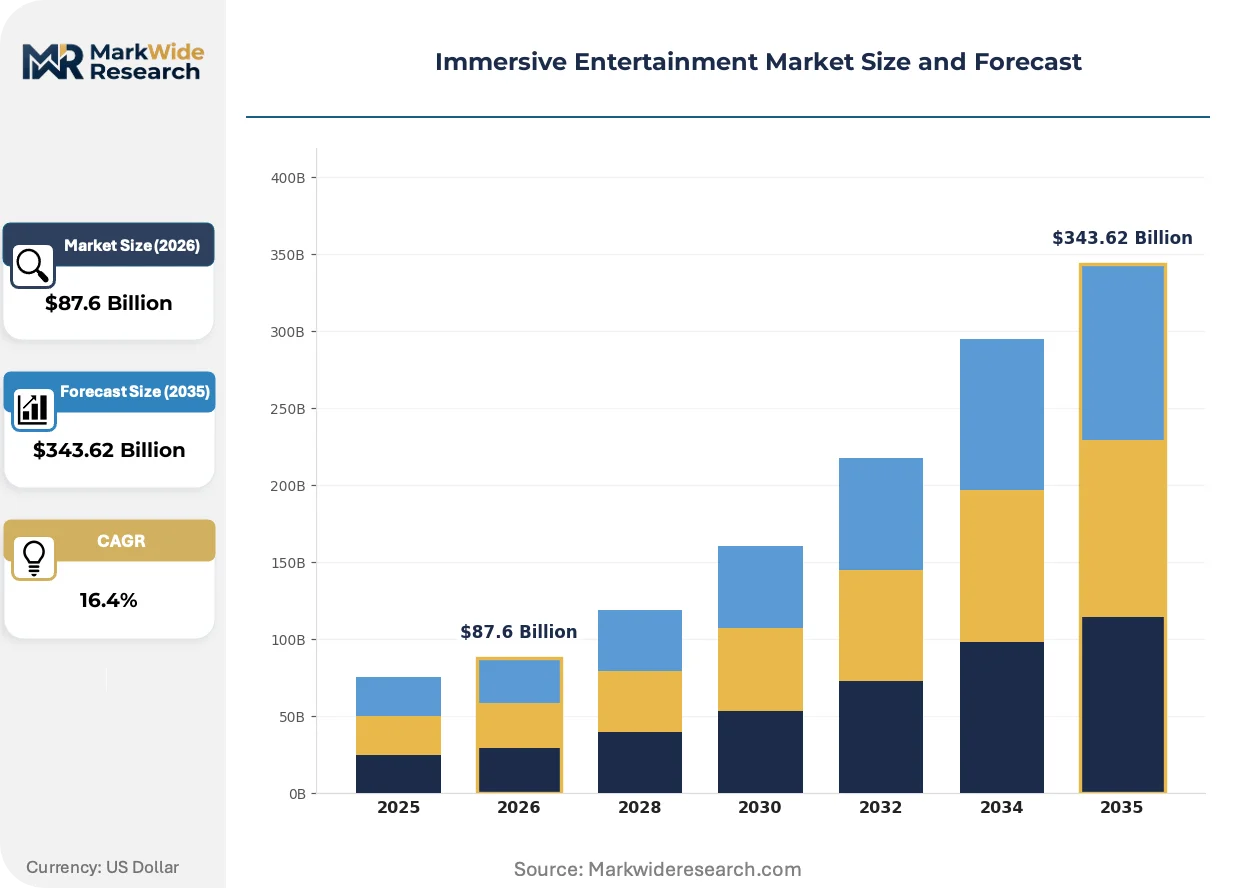
Market Dynamics
Head-mounted display refresh cycles and EU biometric data restrictions are compressing hardware replacement windows while fragmenting content distribution rights across regional licensing regimes.
Growth Catalysts
- Location-based entertainment expansion:Cinema chains and retail landlords in the United States are retrofitting underutilized square footage with mixed-reality installations to capture experiential spending.
- EU AI Act compliance services:European operators are procuring algorithmic auditing tools to maintain biometric consent workflows, creating vendor opportunities in automated content moderation.
- Haptic feedback standardization:IEEE P2863 protocol adoption is enabling cross-platform peripheral compatibility, reducing consumer lock-in friction for hardware upgrades.
Market Restraints
- Optical component supply concentration:Micro-OLED fabrication capacity concentrates among South Korean and Taiwanese foundries, creating allocation bottlenecks during demand surges.
- GDPR biometric friction:European venues face 18-24 month compliance timelines for eye-tracking and facial analysis deployments, delaying revenue recognition.
- Smartphone AR substitution:Handheld augmented reality filters on iOS and Android devices capture casual immersive content consumption without dedicated hardware investment.
Strategic Opportunities
- India retail entertainment penetration:Shopping mall operators in Mumbai and Bangalore are piloting VR arcades with localized content licensing, addressing underdeveloped location-based infrastructure.
- Healthcare-entertainment convergence:FDA breakthrough device designation pathways are accelerating therapeutic VR applications into reimbursable wellness markets adjacent to pure entertainment.
- Cloud rendering distribution:5G network slicing partnerships with telecommunications carriers are enabling low-latency streaming to lightweight headsets, bypassing local compute requirements.
Industry Challenges
- Spatial computing talent scarcity:Unity and Unreal Engine specialists with motion-to-photon optimization experience command premium compensation, constraining development velocity.
- ISO/IEC 27001 certification timelines:Enterprise venue procurement mandates 12-16 month security audit completion, delaying contract execution for mid-scale operators.
- Cross-platform IP licensing complexity:Music synchronization rights and performer likeness agreements fragment across territorial collecting societies, complicating multi-region content launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immersive Entertainment Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Mixed Reality, 360-Degree Video Technology: Software Development Kits, Head-Mounted Displays, Input Devices, Sensory Technology End User: Entertainment Venues, Home Users, Educational Institutions, Corporate Sector Distribution Channel: Online Retail, Direct Sales, Partnerships, Physical Stores |
| Companies Covered | HTC Corporation, Samsung Electronics Co., Ltd., Meta Platforms, Inc., Barco NV, Magic Leap, Inc., Microsoft Corporation, Sony Group Corporation, Unity Technologies, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immersive Entertainment Market Evolving Landscape
Real-time neural rendering and foveated compression are collapsing the cost-performance frontier for photorealistic immersive environments, while regulatory fragmentation forces architectural investments in modular compliance stacks.
Neural radiance field (NeRF) reconstruction is supplanting traditional polygon-based asset pipelines for photogrammetric environment capture. Location-based entertainment designers in Japan and the United States are adopting NeRF workflows to reduce 3D modeling labor by half. The technology is compressing production timelines for seasonal attraction refreshes from months to weeks.
GDPR Article 35 data protection impact assessments now govern biometric inference in all European immersive entertainment deployments. Venues in Germany and France are retrofitting consent management platforms with automated withdrawal mechanisms. The regulation is fragmenting European product roadmaps from North American and Asian hardware iterations.
Subscription-based hardware access is replacing outright purchase for enterprise training and arcade operators. Managed service providers in China are bundling Quest and Pico headsets with content libraries and technical support. The model is concentrating procurement authority among facility management firms rather than IT departments.
Immersive Entertainment Market Segmentation
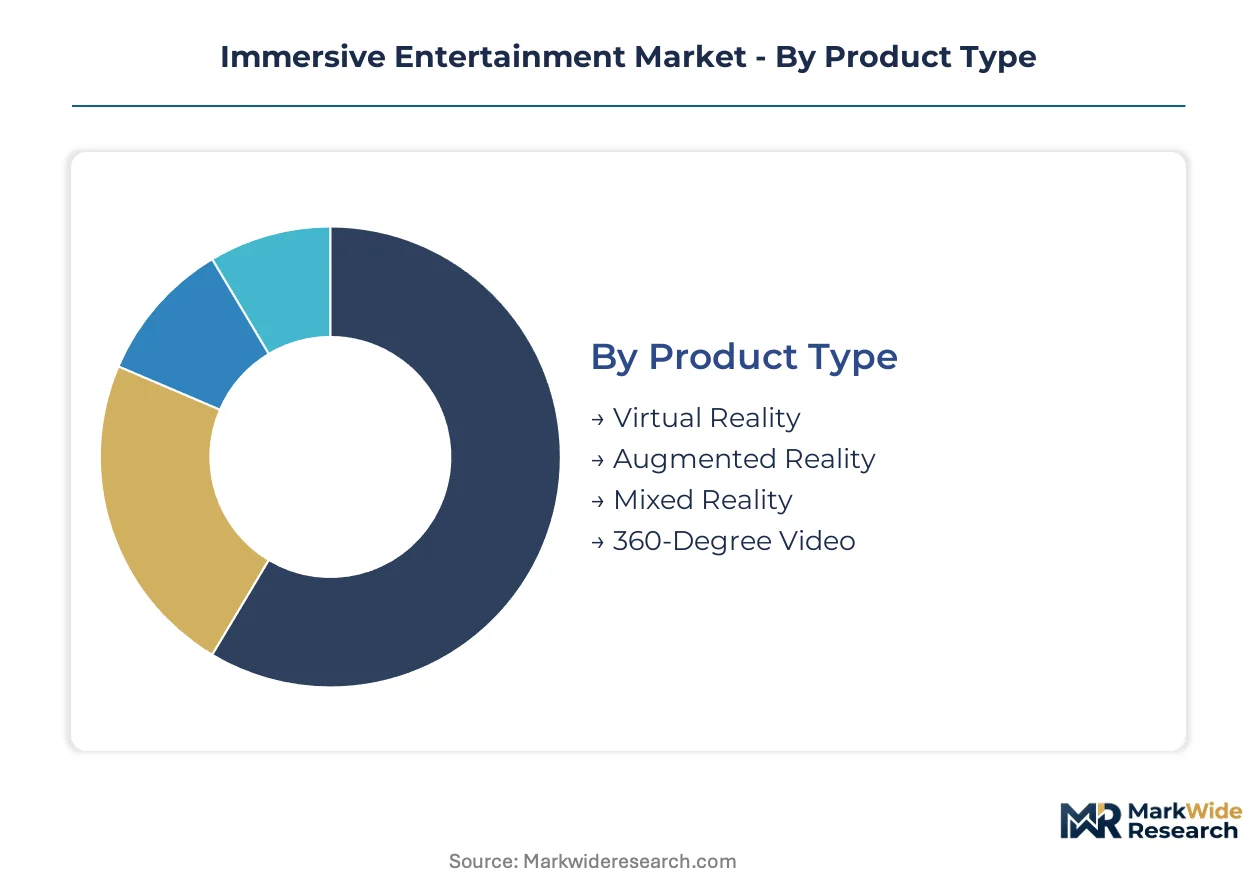
Segmentation in immersive entertainment reveals how hardware specifications, content delivery mechanisms, and venue procurement patterns fragment addressable demand. Distinct compliance obligations across biometric data regimes further bifurcate product roadmaps between regional variants.
Product Type:
GDPR Article 35 assessments and EU AI Act biometric restrictions are forcing divergent feature sets between European and non-European hardware iterations.
- Virtual Reality:Fully enclosed head-mounted displays operating at 90-120 frames per second with sub-20 millisecond motion-to-photon latency. Demand concentrates in United States location-based entertainment venues and Chinese VR arcades as hardware refresh cycles accelerate replacement purchases.
- Augmented Reality:Smartphone-tethered and standalone optical systems overlaying synthetic content onto physical environments. Japanese retail installations and live event producers in the United States are driving adoption as glasses form factors shrink toward consumer viability.
- Mixed Reality:Passthrough camera systems enabling simultaneous interaction with physical and digital objects.
- 360-Degree Video:Spherical capture and playback formats for passive immersive consumption.
Virtual Reality handles the majority of throughput; Augmented Reality is expanding most quickly on share.
Technology:
Component scarcity and foundry allocation bottlenecks concentrate margin capture among semiconductor and optical specialists.
- Head-Mounted Displays:Micro-OLED and pancake optic assemblies dominating bill-of-materials costs. Taiwanese and South Korean foundry capacity constraints are creating allocation queues during demand surges for premium entertainment deployments.
- Software Development Kits:Unity and Unreal Engine middleware with spatial computing APIs. Enterprise training contracts in the United States and Germany are mandating ISO/IEC 27001 certified SDK distributions for institutional procurement.
- Input Devices:Hand tracking controllers and haptic peripherals.
- Sensory Technology:Spatial audio arrays and force-feedback systems.
Head-Mounted Displays capture the dominant margin pool; Software Development Kits are climbing the fastest on commercial attach rates.
End User:
Procurement authority is shifting from IT departments toward facility management firms under subscription-based hardware access models.
- Entertainment Venues:Cinema chains and retail landlords retrofitting underutilized square footage with mixed-reality installations. United States cinema operators and Indian shopping mall developers in Mumbai and Bangalore are piloting localized content licensing for location-based infrastructure.
- Corporate Sector:Enterprise training and branded entertainment installations. FDA breakthrough device designations are accelerating therapeutic VR applications into reimbursable wellness markets adjacent to pure entertainment in the United States.
- Home Users:Consumer hardware purchases for gaming and media consumption.
- Educational Institutions:Curriculum-integrated immersive learning systems.
Entertainment Venues process the highest transaction volumes; Corporate Sector is gaining share fastest on healthcare convergence.
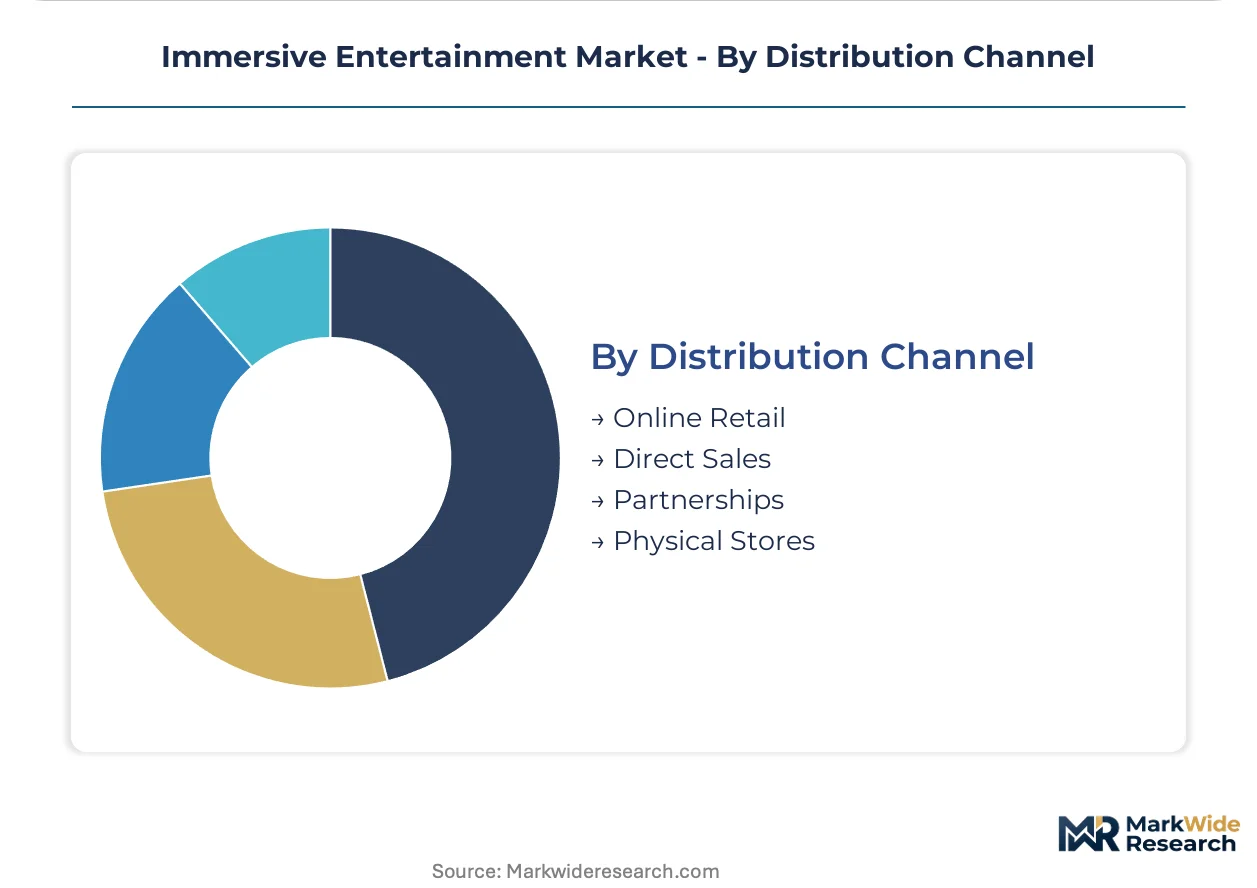
Distribution Channel:
Cloud rendering partnerships with telecommunications carriers are enabling new low-latency streaming pathways that bypass traditional retail procurement.
- Direct Sales:Manufacturer-to-venue procurement for enterprise training and arcade operators. Chinese managed service providers are bundling headsets with content libraries and technical support, concentrating authority among facility management firms.
- Online Retail:E-commerce platforms for consumer hardware and software. 5G network slicing partnerships in Japan and the United States are enabling streaming distribution to lightweight headsets without local compute requirements.
- Physical Stores:Brick-and-mortar electronics and specialty retailers.
- Partnerships:Co-marketing arrangements with content studios and platform holders.
Direct Sales handles the majority of enterprise throughput; Online Retail is the fastest mover on consumer penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise training contracts and location-based entertainment venues concentrate procurement authority among facility management firms in the United States, China, Japan, Germany, and India. These five markets host distinct regulatory environments and industrial clusters that shape hardware deployment timelines and content licensing strategies.
United States
Cinema chains and retail landlords in Los Angeles and New York Metro retrofit underutilized square footage with mixed-reality installations to capture experiential spending. The Federal Communications Commission governs wireless spectrum allocation for untethered headset communication, while the FDA oversees therapeutic VR applications entering reimbursable wellness markets. Seattle and Austin clusters concentrate software development kit vendors serving enterprise training contracts.
China
VR arcade operators in Beijing and Shanghai drive hardware refresh cycles as managed service providers bundle headsets with localized content libraries. The Ministry of Industry and Information Technology enforces content licensing and youth protection standards that shape product roadmaps for hardware manufacturers. Shenzhen's manufacturing corridor supplies micro-OLED and pancake optic assemblies to domestic and export markets.
Japan
Live event producers in Tokyo and Osaka adopt smartphone-tethered augmented reality glasses as form factors shrink toward consumer viability. METI oversees industrial standards coordination for haptic feedback devices entering location-based entertainment venues. Kyoto's content studios specialize in NeRF-based environment capture for seasonal attraction refreshes.
Germany
Industrial training centers in Bavaria and North Rhine-Westphalia mandate ISO/IEC 27001 certified SDK distributions for institutional procurement. GDPR Article 35 data protection impact assessments govern biometric inference in all immersive entertainment deployments, forcing 18-24 month compliance timelines. Berlin's startup cluster develops algorithmic auditing tools for automated content moderation.
India
Shopping mall operators in Mumbai and Bangalore pilot VR arcades with localized content licensing, addressing underdeveloped location-based infrastructure. The Bureau of Indian Standards sets safety and interoperability benchmarks for imported head-mounted displays. Hyderabad's technology corridor hosts cloud rendering partnerships with telecommunications carriers enabling low-latency streaming.
Immersive Entertainment Market Competitive Landscape
Player mix skews toward integrated platform-holders with captive hardware-software ecosystems and specialized component suppliers serving fragmented venue procurement. Market structure concentrates margin capture among semiconductor and optical specialists while content distribution fragments across regional licensing regimes. Two strategic archetypes dominate: vertically integrated technology conglomerates controlling end-to-end user experiences, and pure-play hardware fabricators supplying commercial-grade systems to enterprise installers. Competitive moves center on 5G network slicing partnerships with carriers and subscription-based hardware access models replacing outright purchase.
Among Asia-Pacific-based technology conglomerates, Sony Group Corporation and Samsung Electronics Co., Ltd. occupy positions spanning consumer electronics and commercial installation supply. Meta Platforms, Inc. anchors the integrated platform-holder archetype through its captive hardware-software ecosystem. HTC Corporation exemplifies the commercial-grade specialist tier serving enterprise training and branded entertainment deployments.
| Leading Market Players |
|---|
| HTC Corporation |
| Samsung Electronics Co., Ltd. |
| Meta Platforms, Inc. |
| Barco NV |
| Magic Leap, Inc. |
| Microsoft Corporation |
| Sony Group Corporation |
| Unity Technologies |
| Apple Inc. |
| Others |
Value Network & Pricing Analysis
Micro-OLED panel substitution for traditional LCD displays in premium head-mounted displays simultaneously relocates component sourcing toward Taiwanese and South Korean foundries and compresses hardware margins through optical assembly scarcity. This input transition concentrates pricing power among semiconductor specialists while forcing venue operators toward subscription procurement models.
Pricing Analysis
Cost-plus contracts with Taiwanese and South Korean foundries index micro-OLED wafer pricing to semiconductor commodity benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 27001-certified enterprise deployments from consumer hardware and unlicensed arcade installations. Price differentiation hinges on certification grade and after-sales technical support bundling. Cost compression in economy-tier consumer hardware is intensifying because smartphone AR substitution reduces dedicated headset willingness-to-pay. Indian shopping mall operators exhibit highest price sensitivity; German industrial training centers demonstrate lowest sensitivity due to procurement mandate rigidity.
Supply Chain Analysis
Strategic stockpiling of micro-OLED panels and pancake optic assemblies dominates inventory strategy among hardware manufacturers anticipating foundry allocation constraints. Supply concentrates in Taiwan, South Korea, and China's Shenzhen manufacturing corridor. Component sourcing draws from gallium nitride semiconductors, rare-earth phosphors, and precision-molded polymer optics. Single-source vulnerability runs through Taiwanese micro-OLED fabrication capacity. Distribution runs through direct manufacturer-to-venue procurement for enterprise contracts and Chinese managed service provider bundling for arcade operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immersive entertainment market sits at a platform-economics inflection where IEEE P2863 haptic protocol standardization threatens to collapse proprietary ecosystem lock-in. Interoperability investments now determine long-term margin sustainability.
For Market Incumbents: Compound defensive moats through backward integration into micro-OLED supply allocation and captive cloud rendering infrastructure. Sony Group Corporation's cinema partnership model demonstrates venue-exclusive content licensing as a retention mechanism against Meta Platforms' hardware-software bundling. ISO/IEC 27001 certification investment represents the critical lever for German and United States enterprise contract eligibility.
For New Entrants and Emerging Players: Algorithmic auditing tool development for EU AI Act biometric compliance workflows presents an underserved service layer where incumbents under-serve European venue operators. India's underdeveloped location-based infrastructure in Mumbai and Bangalore offers the most penetrable geography. Cloud rendering partnerships with telecommunications carriers enable low-latency streaming without local compute investment as a capital-light go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a hardware refresh acceleration phase that favors component specialists with foundry allocation security over pure-play content studios. Long-term viability across the projection horizon rests on optical semiconductor supply relationships rather than software IP portfolios. NeRF-based production pipeline adoption rates signal inflection timing for content cost structure transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G Network Slicing Partnership | Telecommunications carriers in Japan and the United States enable low-latency streaming to lightweight headsets bypassing local compute. |
| NeRF Production Pipeline Adoption | Kyoto content studios compress seasonal attraction refresh timelines from months to weeks through neural radiance field workflows. |
| ISO/IEC 27001 Certification Investment | German industrial training centers mandate certified SDK distributions for institutional procurement eligibility. |
| EU AI Act Compliance Service Launch | Berlin startup cluster develops algorithmic auditing tools for automated content moderation in biometric deployments. |
| Subscription Hardware Access Model | Chinese managed service providers bundle Quest and Pico headsets with technical support concentrating procurement authority. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and telecommunications carrier partnership announcements. Primary interviews with location-based entertainment venue operators, enterprise training procurement officers, haptic hardware engineers, and cloud rendering platform architects inform demand-side validation. Bottom-up unit economics from hardware bill-of-materials analysis triangulates against top-down market sizing from content licensing revenue aggregation.
Segmentation dimensions modeled span product type, technology tier, end-user archetype, and distribution channel across the analysis window. Virtual Reality, Augmented Reality, Mixed Reality, and 360-Degree Video categories disaggregate hardware refresh cycle timing. Head-Mounted Displays, Software Development Kits, Input Devices, and Sensory Technology capture technology-based margin distribution. Entertainment Venues, Corporate Sector, Home Users, and Educational Institutions represent end-user procurement authority patterns. CAGRs derive from replacement cycle velocity, foundry capacity expansion schedules, and regulatory compliance timeline impacts.
Underlying assumptions cover micro-OLED fabrication capacity scaling, GDPR enforcement consistency across European member states, and 5G network slicing deployment pace, with deviation risk concentrated in semiconductor supply allocation shocks and biometric regulation interpretation variance. Revision becomes warranted when optical component lead times or EU AI Act compliance cost estimates cross threshold multiples of baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AR Gaming Market