
 In-Game Advertising Market | 2026-2036
In-Game Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
In-Game Advertising Market Analysis
The EU AI Act is realigning how automated ad placement algorithms gain market access across European territories. Unity Technologies leverages its engine dominance to embed ad infrastructure directly into development pipelines. Bidstack Limited anchors its model in sports simulation titles where virtual stadium inventory commands sustained CPM premiums. InMobi competes through proprietary SDK penetration across emerging market mobile ecosystems.
In-game advertising denotes the insertion of brand messages, imagery, or interactive promotions within interactive software environments, rendered through real-time engines or pre-authored asset pipelines at frame rates matching native gameplay. The practice serves commercial purpose by capturing engaged attention during active play sessions rather than interrupting with external media. Video ads within mobile games currently occupy the largest revenue pool due to rewarded opt-in mechanics that preserve user experience. Sponsored content integrated into character clothing and environmental billboards represents the fastest-growing format as fashion and automotive brands seek non-intrusive presence. Native ads that mimic in-world textures and objects concentrate margin in premium console and PC titles where production values justify higher creative investment.
The Federal Trade Commission in the United States and the European Commission under the Digital Services Act both scrutinize disclosure standards for immersive advertising that blurs commercial and entertainment content. China's National Radio and Television Administration and the Cyberspace Administration impose content review requirements on in-game promotional material before distribution approval. Stakeholders must monitor how divergent disclosure mandates across the United States, European Union, and China reshape creative production workflows and platform compliance costs.
Market Dynamics
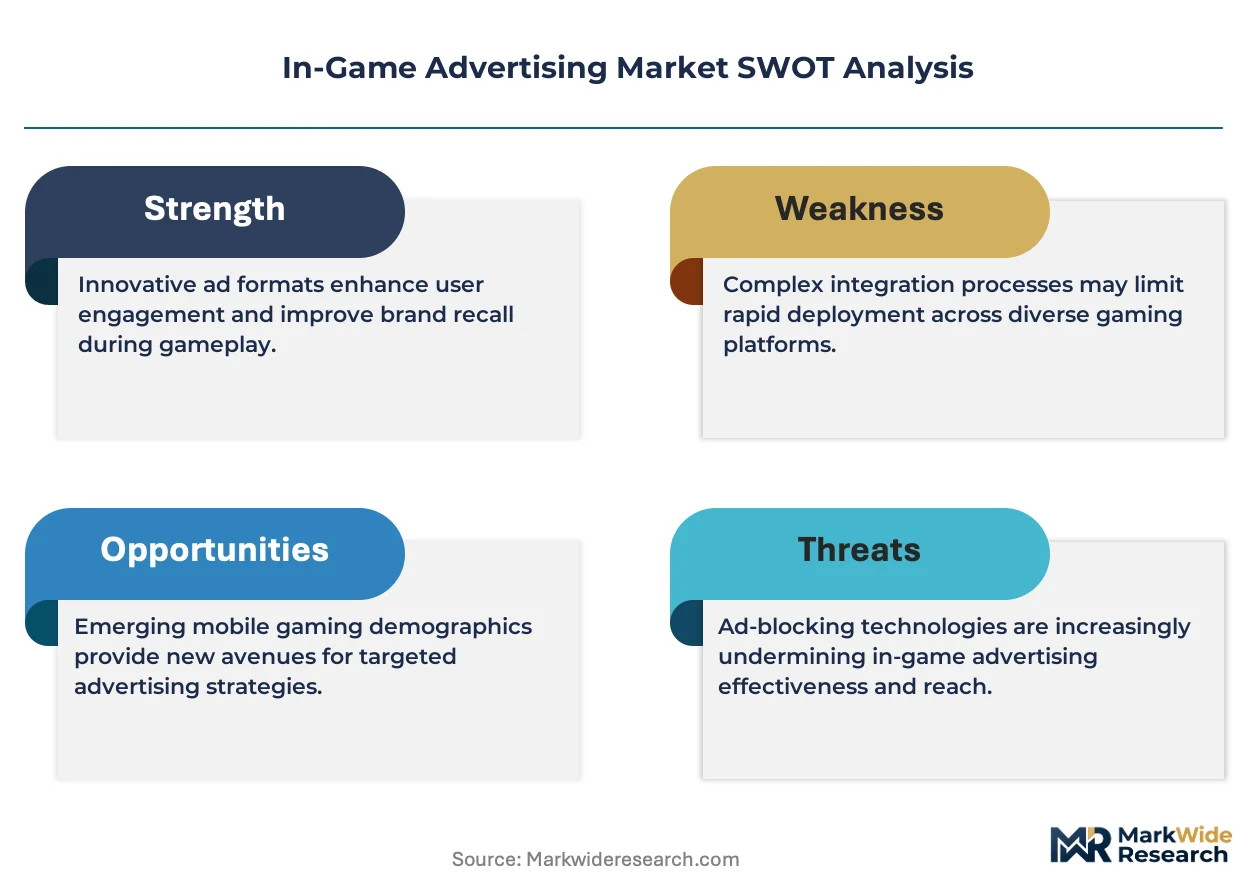
Privacy frameworks are fragmenting identity infrastructure across major gaming markets, forcing platforms to reconstruct targeting capabilities around first-party data relationships with players rather than third-party tracking.
Growth Catalysts
- Rewarded Video Mechanics:Opt-in ad formats preserve user experience while delivering measurable engagement metrics that consumer packaged goods brands require for programmatic media planning.
- GDPR-Driven First-Party Data Investment:European enforcement of consent requirements is accelerating publisher investment in direct player relationships and authenticated inventory pools.
- Live-Service Game Architecture:Continuous content updates in multiplayer titles create recurring insertion points for dynamic brand placements without disrupting narrative flow.
Market Restraints
- Identifier Deprecation:Apple's App Tracking Transparency and Google's planned Privacy Sandbox phase-out are degrading cross-platform attribution precision for mobile game campaigns.
- Creative Production Bottlenecks:Console and PC titles demand 3D asset pipelines that extend campaign lead times to 8-12 weeks, compressing reactive marketing windows.
- Platform Concentration Risk:Unity and Unreal Engine control development toolchains, enabling gatekeeping of ad SDK integration and revenue share terms.
Strategic Opportunities
- India Mobile Expansion:Low in-game ad saturation relative to time spent gaming creates arbitrage potential for early programmatic entrants before inventory commoditization.
- Virtual Production Convergence:Real-time engine technology from film and television is unifying asset pipelines, reducing cost to adapt cinematic brand content for interactive environments.
- EU AI Act Compliance Services:Automated ad placement algorithms require conformity assessment, creating advisory and technical verification revenue streams for specialized vendors.
Industry Challenges
- Technical Art Talent Scarcity:Shortage of specialists capable of integrating brand assets into proprietary game engines without frame rate degradation limits campaign scale.
- Cross-Border Content Review:China's National Radio and Television Administration pre-approval requirements for promotional material create unpredictable launch timelines for multinational campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Game Advertising Market |
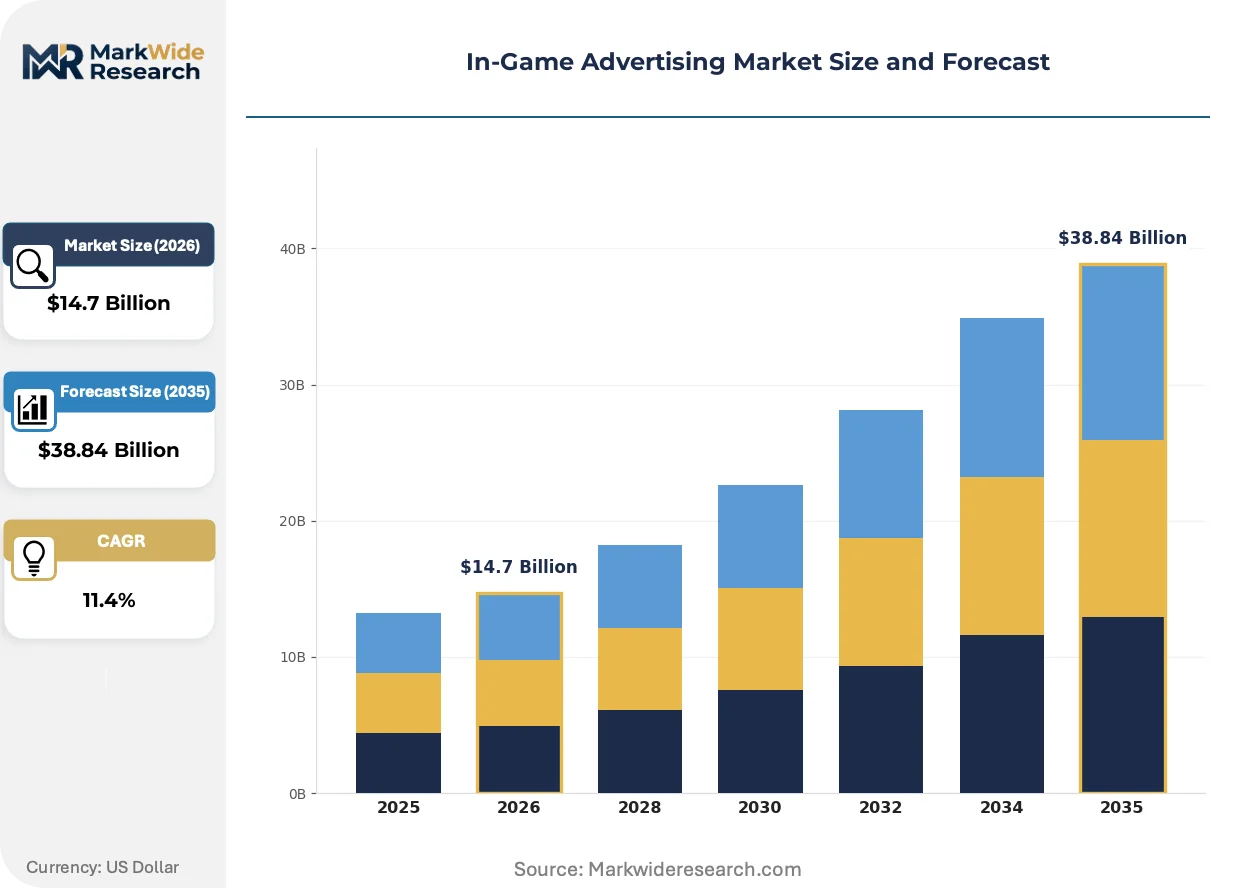
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Banner Ads, Video Ads, Sponsored Content, Native Ads Game Type: Mobile Games, Console Games, PC Games, Browser Games Target Audience: Casual Gamers, Hardcore Gamers, Competitive Gamers, Family Gamers Ad Placement: In-Game Billboards, Character Clothing, Interactive Objects, Cutscenes |
| Companies Covered | Anzu Virtual Reality Ltd., Bidstack Limited, Frameplay, Playwire LLC, Unity Technologies, InMobi, AppLovin, ironSource, Adverty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Game Advertising Market Emerging Trajectories
Real-time rendering infrastructure is dissolving boundaries between pre-authored advertising assets and dynamically generated placements, enabling responsive brand presence that adapts to individual play contexts.
Programmatic in-game ad platforms are unifying previously siloed inventory pools across mobile, console, and PC environments into single buying interfaces. Media agencies in North America and Western Europe are consolidating spend through these unified platforms to reduce fragmentation overhead. This consolidation is compressing CPM variance between premium console inventory and high-engagement mobile rewarded video, redistributing margin toward technology intermediaries and away from publisher direct sales teams.
The EU AI Act's risk classification system for automated decision-making is imposing documentation and human oversight requirements on algorithmic ad placement systems. Publishers deploying dynamic creative optimization in European territories must now maintain audit trails for targeting logic and maintain human-in-the-loop review protocols. Sports simulation titles with virtual stadium inventory are most affected, as their real-time bidding systems require retrofitting to satisfy conformity assessment procedures before market access.
Brand safety verification has shifted from post-campaign reporting to pre-bid filtering as advertisers demand granular control over contextual adjacency. Fashion and automotive buyers now require keyword blocklists and scene-level classification before committing to environmental billboard placements. This behavioral shift is most pronounced in the United States, where FTC scrutiny of undisclosed immersive advertising has elevated legal risk tolerance as a primary vendor selection criterion alongside reach and pricing.
In-Game Advertising Market Segmentation
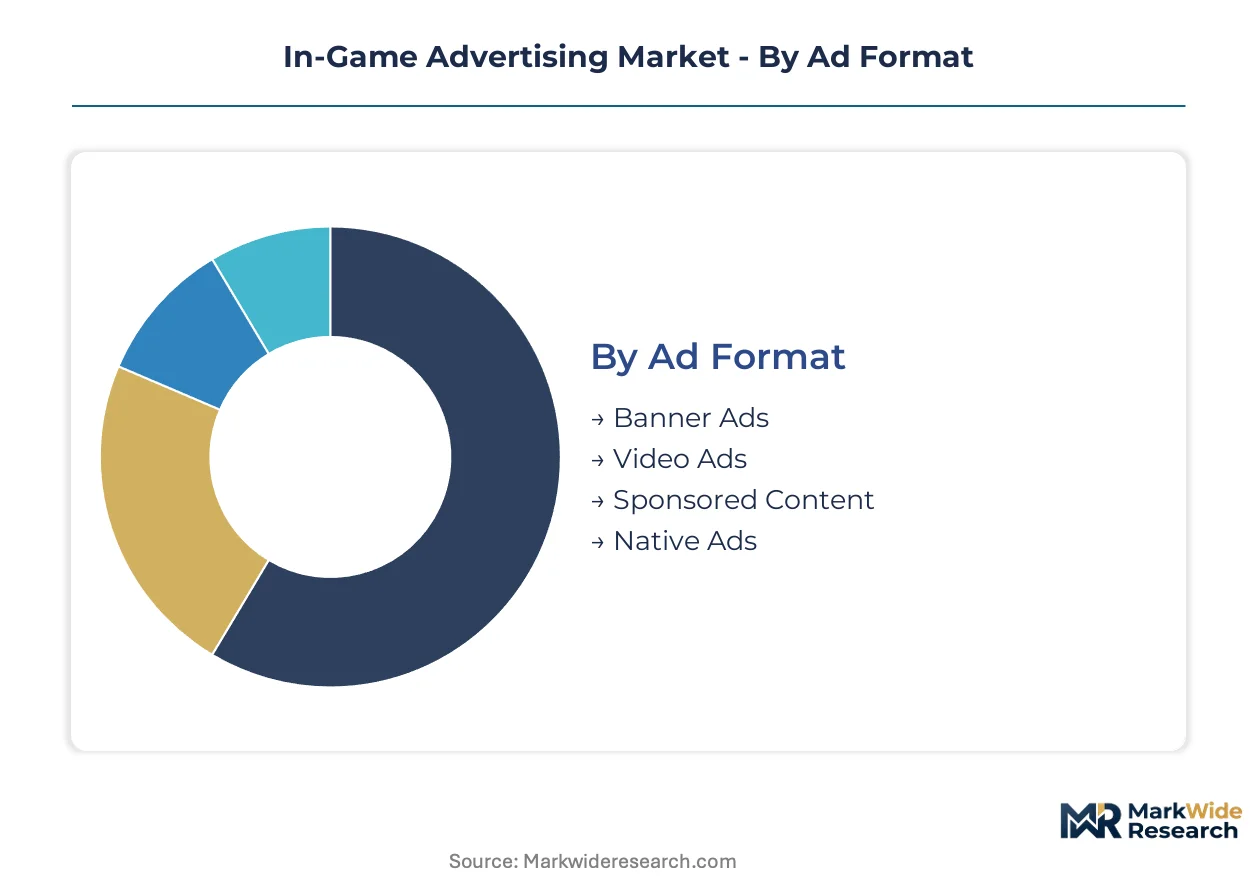
In-game advertising requires granular segmentation because ad format compatibility varies dramatically across rendering pipelines and player attention states. Buyers select inventory based on frame rate constraints, opt-in mechanics, and immersion preservation rather than reach metrics alone.
Ad Format:
Buyers in this category differentiate by immersion tolerance and creative production timelines.
- Video Ads:Rewarded opt-in formats deliver 15-30 second spots between gameplay loops, preserving user experience through explicit value exchange. Demand concentrates in mobile free-to-play titles where consumer packaged goods brands require measurable completion rates for programmatic media planning.
- Sponsored Content:Deep integration into character clothing and environmental assets creates non-intrusive brand presence that mimics native game aesthetics. Fashion and automotive advertisers in the United States and South Korea drive premium CPMs for virtual stadium inventory and avatar customization systems.
- Native Ads:Texture-mimicking placements blend into in-world surfaces without interrupting gameplay flow.
- Banner Ads:Static display units occupy screen periphery during casual mobile sessions with lower production requirements.
Volume sits with Video Ads; growth tilts toward Sponsored Content.
Game Type:
Technical architecture and player session length separate buyers by platform investment thresholds.
- Mobile Games:Proprietary SDK ecosystems and rewarded video mechanics dominate inventory pools. India's low ad saturation relative to time spent gaming creates arbitrage potential for early programmatic entrants before inventory commoditization compresses margins.
- Console Games:Premium 3D asset pipelines demand 8-12 week campaign lead times, attracting automotive and entertainment studios with sustained creative budgets. Technical art talent scarcity limits campaign scale as specialists capable of integrating brand assets without frame rate degradation command premium compensation.
- PC Games:Real-time engine modularity enables dynamic creative optimization across live-service titles.
- Browser Games:Lightweight HTML5 implementations serve rapid-deployment campaigns with minimal technical barriers.
Console Games capture premium pricing; Mobile Games expand most quickly.
Target Audience:
Engagement depth and purchasing intent distinguish buyer strategies across player psychographics.
- Casual Gamers:Short session mobile players respond to rewarded video opt-ins with minimal friction. Family-oriented titles in China face content review requirements from the National Radio and Television Administration that extend campaign approval timelines unpredictably.
- Hardcore Gamers:Extended PC and console sessions enable immersive environmental placements with higher attention capture. Competitive Gamers concentrate in esports titles where live-service architecture creates recurring insertion points for dynamic brand presence.
- Family Gamers:Multi-generational households drive brand safety scrutiny with pre-bid filtering demands.
Casual Gamers supply volume density; Hardcore Gamers yield CPM premiums.
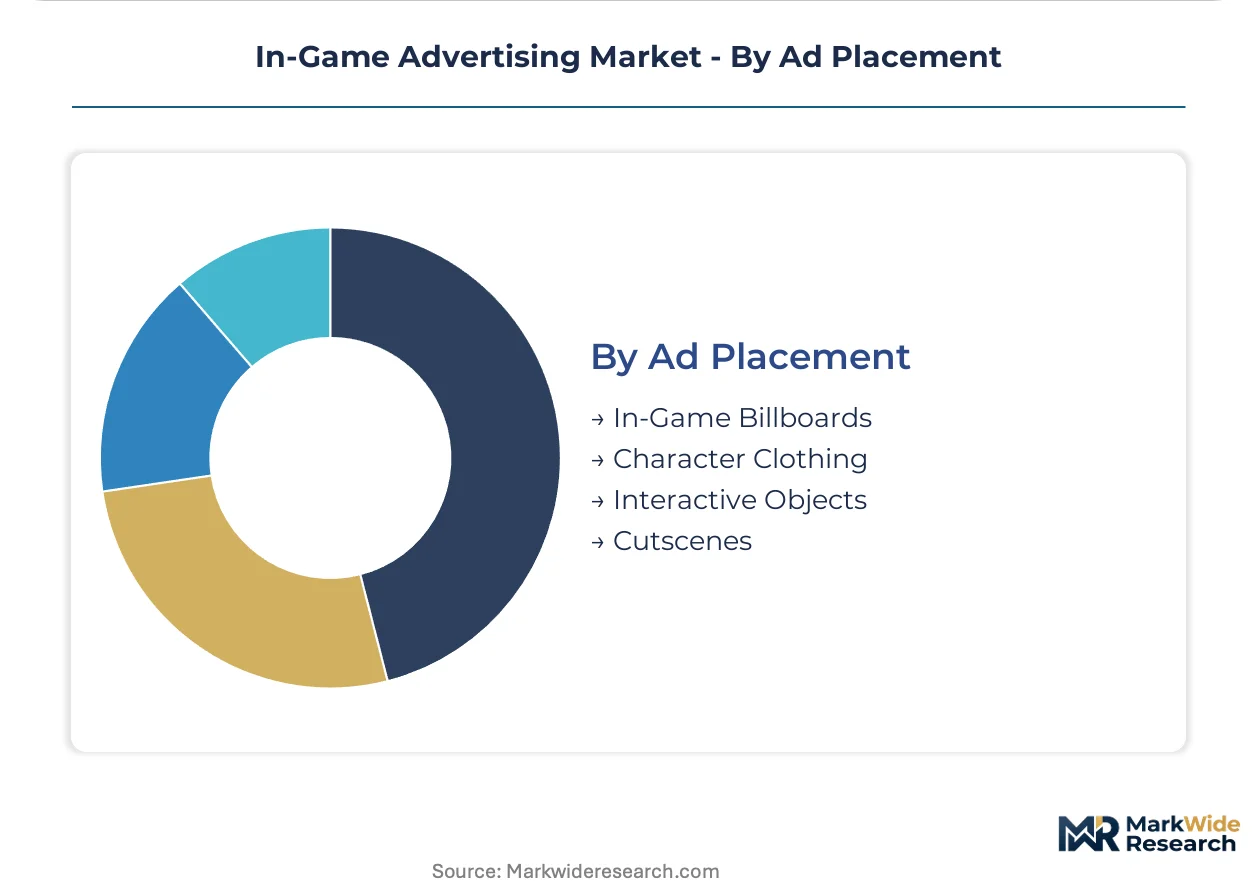
Ad Placement:
Contextual adjacency control and narrative disruption risk segment buyer preferences.
- In-Game Billboards:Environmental signage within sports simulation and open-world titles commands sustained premiums. Brand safety verification has shifted to pre-bid filtering as United States advertisers demand keyword blocklists and scene-level classification under elevated FTC scrutiny of undisclosed immersive advertising.
- Character Clothing:Avatar customization systems enable persistent brand presence across multiplayer sessions. Virtual production convergence from film and television is reducing cost to adapt cinematic fashion content for interactive character assets.
- Interactive Objects:Branded drivable vehicles and usable items create memorable player engagement.
- Cutscenes:Pre-rendered cinematic sequences guarantee placement visibility with fixed timing.
In-Game Billboards anchor revenue stability; Character Clothing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the industry's commercial gravity, hosting headquarters clusters for both game engine infrastructure and programmatic advertising technology that serve inventory across mobile, console, and PC environments.
United States
Esports viewership in Los Angeles and Seattle sustains premium pricing for virtual stadium inventory, while New York-based media agencies consolidate programmatic spend through unified buying interfaces. The FTC scrutinizes disclosure standards for immersive advertising that blurs commercial and entertainment content. Austin's live-service game development cluster generates recurring insertion points for dynamic brand placements without disrupting narrative flow.
China
Mobile game penetration in Shenzhen and Shanghai creates dense rewarded video inventory pools that attract consumer packaged goods brands. The National Radio and Television Administration imposes content review requirements on in-game promotional material before distribution approval. Chengdu's emerging game development corridor specializes in multiplayer titles with continuous content updates that enable recurring brand insertion.
South Korea
Seoul's esports ecosystem commands sustained CPM premiums for virtual stadium inventory across sports simulation titles. The country's broadcast regulator maintains disclosure standards for commercial content integrated into character clothing and environmental assets. Busan's mobile game studios leverage proprietary SDK ecosystems to capture arbitrage opportunities in rewarded opt-in mechanics.
Germany
Munich's automotive brands drive demand for sponsored content integration into premium console and PC titles with 8-12 week campaign lead times. GDPR enforcement accelerates publisher investment in direct player relationships and authenticated inventory pools. Hamburg's technical art talent cluster faces scarcity pressures as specialists capable of integrating brand assets without frame rate degradation command premium compensation.
India
Bangalore's mobile gaming time spent far exceeds current ad saturation, creating arbitrage potential for early programmatic entrants. The country's central telecommunications authority shapes data localization requirements that affect cross-border identity graph construction. Mumbai's brand marketing headquarters increasingly route experimental budgets toward rewarded video formats in casual free-to-play titles.
In-Game Advertising Market Vendor Landscape
The competitive structure tilts toward engine-integrated infrastructure providers rather than standalone ad networks. Market concentration clusters around three technology layers: real-time rendering engines, programmatic mediation platforms, and specialized virtual environment inventory managers. Strategic archetypes include engine-native ad SDK operators, cross-platform mediation specialists, and vertical-focused sports simulation inventory brokers. Dominant competitive moves encompass first-party data relationship investments and virtual production pipeline convergence to reduce creative adaptation costs.
Within the engine-native tier, Unity Technologies exemplifies infrastructure embedding where ad technology integrates directly into development toolchains. Bidstack Limited occupies a position as a vertical specialist concentrating on sports simulation titles where virtual stadium inventory commands sustained premiums. InMobi sits within the emerging market penetration archetype, leveraging proprietary SDK distribution across mobile ecosystems where rewarded video mechanics dominate revenue pools. These three anchors illustrate how competitive positioning fragments across technical integration depth rather than consolidating around reach scale alone.
| Leading Market Players |
|---|
| Anzu Virtual Reality Ltd. |
| Bidstack Limited |
| Frameplay |
| Playwire LLC |
| Unity Technologies |
| InMobi |
| AppLovin |
| ironSource |
| Adverty |
| Others |
Supply Flow & Price Mechanics
Real-time rendering engine consolidation is compressing creative production timelines while simultaneously concentrating pricing power among Unity Technologies and Epic Games, whose SDK gatekeeping enables revenue share extraction that independent ad networks cannot match. This technical layer dominance feeds into CPM tiering where authenticated first-party inventory pools command premiums over commoditized mobile rewarded video slots.
Pricing Analysis
Engagement-based pricing anchors inventory valuation, with opt-in rewarded video mechanics in mobile titles sustaining measurable completion rates that consumer packaged goods brands require for programmatic planning. Premium-mid-economy pricing differentiation separates virtual stadium inventory in sports simulation titles from banner placements in casual mobile sessions, with authentication level and frame rate fidelity as primary tiering mechanisms. Cost compression in standard mobile inventory is intensifying because identifier deprecation degrades cross-platform attribution precision. Hyper-casual publishers exhibit highest price sensitivity, while automotive and fashion buyers in Munich and Seoul accept extended lead times for sponsored content integration.
Supply Chain Analysis
Technical art talent supply rests on specialist clusters in Hamburg, San Francisco, and Seoul, where professionals capable of integrating brand assets without frame rate degradation command premium compensation. Proprietary SDK distribution draws from InMobi's emerging market penetration and Unity's engine-native embedding, while 3D asset pipelines hinge on real-time engine modularity. Single-source vulnerability concentrates in Unity and Unreal Engine development toolchains, where gatekeeping of ad integration creates platform concentration risk. Distribution runs through programmatic mediation platforms that unify previously siloed inventory pools across mobile, console, and PC environments into single buying interfaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical art specialist scarcity props CPM premiums for sponsored content integration, constraining campaign scale and sustaining pricing power for qualified production houses.
For Market Incumbents: Lock in first-party data relationships through direct player authentication systems before GDPR enforcement accelerates further. Consolidate technical art talent in Hamburg and San Francisco through acquisition of boutique production studios to defend against identifier deprecation eroding mobile attribution precision. Prioritize SDK integration depth with Unity and Unreal Engine to maintain gatekeeping leverage over revenue share terms. For New Entrants and Emerging Players: AI-powered creative adaptation tools offer entry leverage into the EU AI Act compliance services segment, where automated ad placement algorithms require conformity assessment documentation. White-space concentrates in India's mobile gaming arbitrage, where time spent gaming far exceeds current ad saturation. Target Bangalore and Mumbai with rewarded video specialization before inventory commoditization compresses margins. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical-focused sports simulation inventory brokers with sustained virtual stadium CPM premiums. Long-term viability hinges on first-party data infrastructure ownership rather than reach scale alone. Watch FTC disclosure standard enforcement intensity as the inflection signal for legal risk tolerance becoming the primary vendor selection criterion.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Investment | GDPR enforcement in Europe and state-level US statutes force authenticated inventory pool construction. |
| Virtual Production Pipeline Convergence | Real-time engine technology from film reduces cost to adapt cinematic brand content for interactive environments. |
| EU AI Act Compliance Service Development | Automated ad placement algorithms require conformity assessment, creating advisory revenue for specialized vendors. |
| India Mobile Expansion | Low ad saturation relative to time spent gaming creates arbitrage potential before inventory commoditization. |
| Technical Art Talent Acquisition | Specialist scarcity limits campaign scale, making qualified production houses strategic acquisition targets. |
Methodological Framework
Multi-period observation of SDK penetration rates, CPM tier movements, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with game engine product managers, programmatic platform executives, brand safety verification specialists, and technical art directors. Secondary validation drew from SEC filings of publicly traded ad technology firms, FTC disclosure enforcement records, EU AI Act implementation guidance, and mobile game revenue disclosures. Bottom-up inventory pool sizing and top-down media spend allocation estimates were triangulated to cross-validate market dimensions.
Segment-weighting across ad format, game type, target audience, and ad placement dimensions structured the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in schedules and technology adoption curves. Modeled inputs included live-service game architecture penetration, identifier deprecation timelines, and virtual production pipeline convergence rates across film and interactive entertainment.
Several conditions sit outside the modeled scope, including unpredictable content review timelines from China's National Radio and Television Administration and sudden platform policy shifts by Apple or Google. Forecasts reflect assumptions about sustained esports viewership growth and stable enforcement patterns for immersive advertising disclosure. A small set of named triggers warrants ongoing watch: FTC litigation intensity, EU AI Act conformity assessment procedural finalization, and Unity or Unreal Engine revenue share term changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
United States Marketing Agencies Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Native Video Advertising Market