
 Teleshopping Market | 2026-2036
Teleshopping Market Size, Share, and Industry Trends Forecast 2026-2036
Teleshopping Market Intelligence
Synthetic diamond substitutes are pivoting traditional jewelry teleshopping economics by collapsing price floors for gemstone programming. QVC leverages captive studio production to sustain margin control across live broadcast slots. America's Collectibles Network, Inc. anchors its competitive stance through deep specialization in numismatic and collectible coins. Naaptol Online Shopping Private Limited dominates India's Hindi-language teleshopping band with aggressive price positioning on household electronics.
Teleshopping denotes a direct-response retail format where products are demonstrated and sold through broadcast television, streaming platforms, or dedicated shopping channels, typically featuring toll-free ordering, installment billing, and live presenter interaction designed to compress purchase decision cycles. The format relies on 24-hour programming schedules, studio-based product demonstration sets, and real-time inventory countdowns to manufacture urgency. Electronics and home appliances categories lead transaction volume due to high price points that justify extended on-air explanation time. Health and beauty segments attract the fastest-growing advertiser investment because serum and skincare demonstrations translate viscerally to camera. Fashion programming occupies a mature position where return rates erode profitability and constrain expansion.
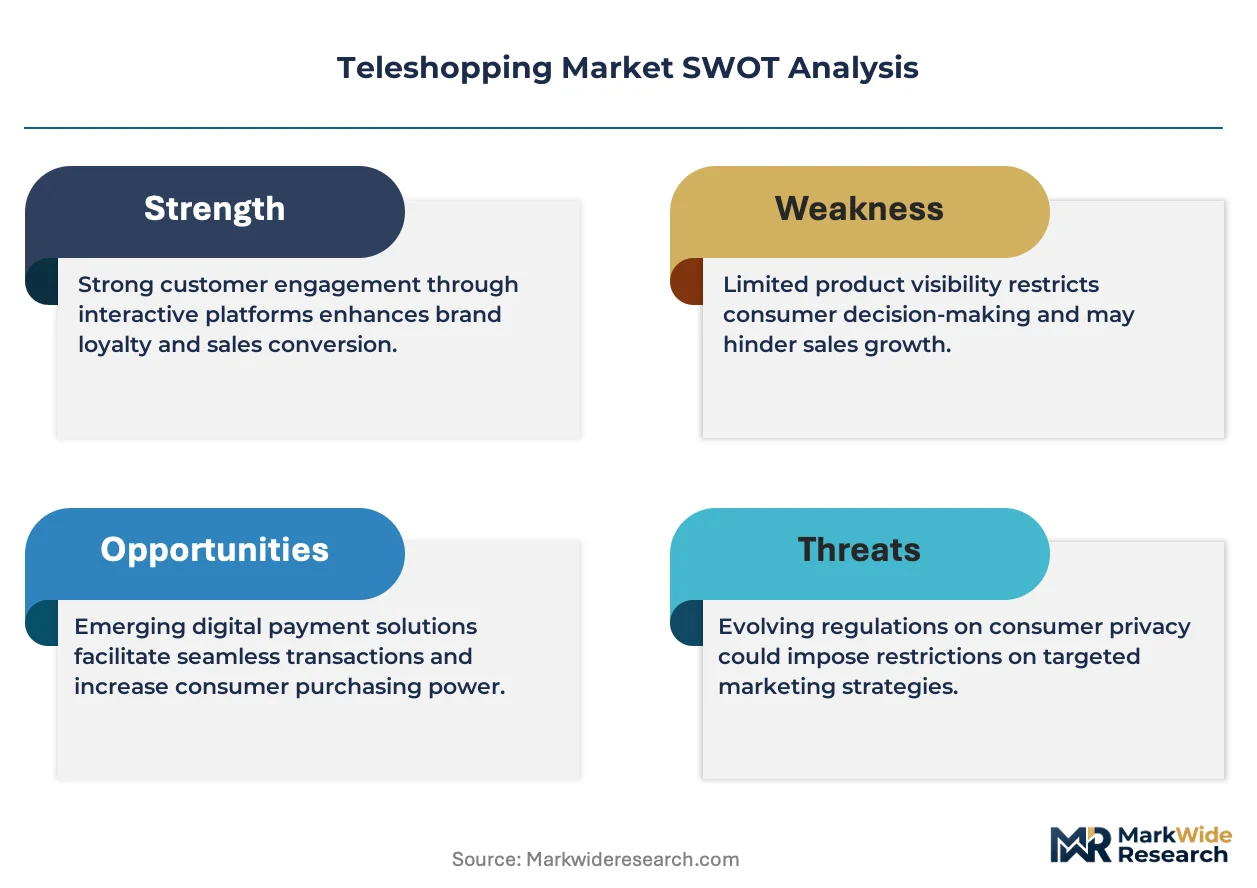
The US Federal Trade Commission enforces truth-in-advertising standards that mandate substantiation for health claims aired during live programming, while the EU's Consumer Rights Directive imposes cooling-off periods and disclosure requirements on distance sales concluded through broadcast media. Japan's Consumer Affairs Agency monitors exaggerated efficacy claims in beauty and wellness teleshopping with escalating penalty schedules. Stakeholders must monitor how streaming platform migration reshapes regulatory jurisdiction and which compliance frameworks transfer from broadcast to over-the-top delivery.
Market Dynamics
Streaming platform migration is fragmenting regulatory jurisdiction across broadcast and over-the-top delivery, forcing teleshopping operators to maintain dual compliance frameworks while real-time inventory systems compress purchase decision cycles into sub-minute windows.
Growth Catalysts
- Aging Demographics:Health and beauty product adoption accelerates among populations over 55 in Germany, Japan, and the United States, where extended on-air demonstrations of serums and skincare translate viscerally to camera and justify premium price positioning.
- EU Consumer Rights Directive:Cooling-off periods and disclosure requirements on distance sales concluded through broadcast media have standardized trust mechanisms that reduce purchase hesitation and lower return rates for electronics programming.
- Synthetic Diamond Substitutes:Laboratory-grown gemstone alternatives are collapsing price floors for jewelry programming, enabling volume expansion in mid-market demographics previously priced out of traditional gemstone teleshopping economics.
Market Restraints
- Return Rate Erosion:Fashion programming suffers profitability compression from garment return rates exceeding 35 percent, constraining inventory commitment and on-air slot allocation for apparel categories.
- FTC Substantiation Requirements:The US Federal Trade Commission mandates documented evidence for health claims aired during live programming, extending pre-broadcast review timelines and increasing legal compliance overhead.
- Studio Production Concentration:Captive studio infrastructure in Pennsylvania and North Rhine-Westphalia creates geographic supply risk and limits operational flexibility for operators seeking to diversify production locations.
Strategic Opportunities
- India Hindi-Language Expansion:Underpenetrated tier-two and tier-three cities present white space for household electronics programming localized to regional dialects and payment preferences including cash-on-delivery.
- Installment Billing Convergence:Integration of buy-now-pay-later platforms with toll-free ordering systems enables price point accessibility for high-value appliances without credit card penetration requirements.
- Japan Consumer Affairs Agency Tailwinds:Escalating penalty schedules for exaggerated efficacy claims create competitive advantage for operators investing in clinical substantiation and transparent demonstration protocols.
Industry Challenges
- Presenter Talent Scarcity:Live selling requires hybrid competencies combining product expertise, improvisational timing, and regulatory awareness, creating recruitment bottlenecks and wage inflation for qualified on-air talent.
- Legacy Broadcast Integration:Migration to streaming platforms forces simultaneous maintenance of satellite transmission infrastructure and over-the-top delivery systems, duplicating technical overhead without immediate audience transfer guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teleshopping Market |
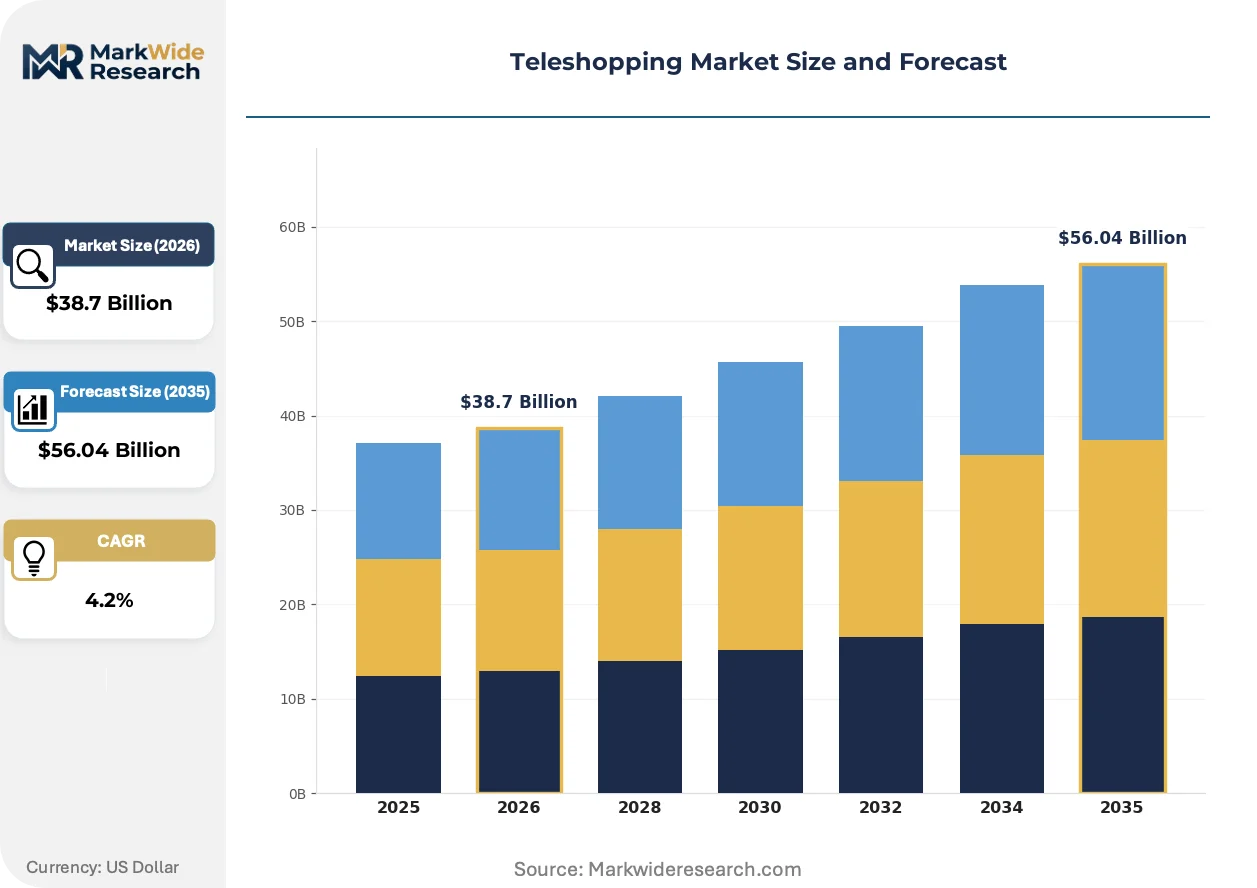
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Home Appliances, Fashion, Health & Beauty Sales Channel: Television, Online, Mobile Apps, Direct Response Advertising Customer Demographics: Millennials, Baby Boomers, Gen X, Families Payment Mode: Credit Card, Debit Card, PayPal, Installment Plans |
| Companies Covered | America's Collectibles Network, Inc., Naaptol Online Shopping Private Limited, QVC, HSE24, Jupiter Shop Channel, HSN, Inc., Gem Shopping Network Inc., Jewelry Television, Shop TJC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teleshopping Market Strategic Shifts & Innovations
Artificial intelligence is reshaping how teleshopping operators personalize live programming, with real-time viewer data triggering dynamic product rotations and individualized pricing displays that compress decision windows without human presenter intervention.
Cloud-based production infrastructure is modularizing studio operations across the teleshopping value chain. Mid-market operators in Southeast Asia are adopting modular studio components that enable rapid configuration changes between electronics and beauty sets. This technology is compressing capital requirements for market entry and fragmenting production concentration away from legacy captive facilities.
The EU AI Act imposes transparency obligations on algorithmic recommendation systems used to sequence product demonstrations during live broadcasts. Operators deploying automated programming optimization must now disclose when AI determines airtime allocation. Beauty and wellness segments in Germany and France face the steepest compliance adaptation as they rely most heavily on predictive analytics for inventory countdown timing.
Social commerce platforms are capturing younger demographics who previously represented marginal teleshopping penetration, with live-stream shopping on mobile applications displacing traditional toll-free ordering among consumers under 35 in South Korea and urban China. This behavioral pivot forces incumbent broadcast operators to develop hybrid talent capable of simultaneous television and mobile-native presentation without fragmenting brand consistency.
Teleshopping Market Segmentation
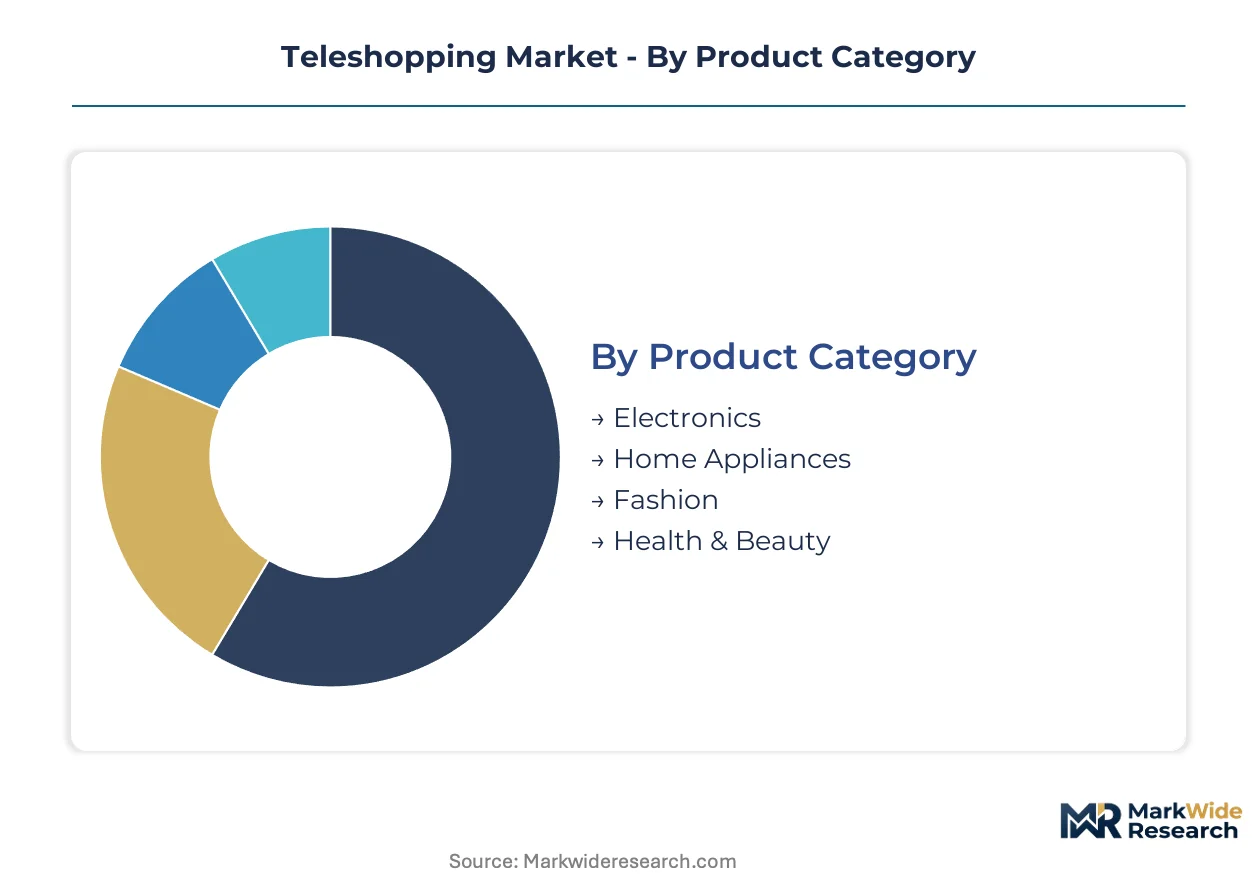
Teleshopping operators calibrate programming slots, presenter expertise, and inventory depth against segment-specific purchase cycles. Electronics demand extended demonstration time; health and beauty segments compress decision windows through visceral before-after visuals. Payment flexibility and channel migration reshape how each segment converts viewers into buyers.
Product Category:
Replacement cycles and upgrade urgency vary dramatically across teleshopping product categories, with durable goods commanding longer on-air explanations than consumable segments.
- Electronics:High-definition televisions, smartphones, and computing peripherals dominate transaction value through extended technical demonstrations. Demand concentrates in Germany and the United States, where aging populations seek simplified technology interfaces and toll-free support substitutes for complex retail navigation.
- Home Appliances:Kitchen equipment, climate control systems, and cleaning devices justify premium price positioning through live functionality testing. Volume clusters in tier-two Indian cities, where cash-on-delivery preferences and Hindi-language programming reduce purchase hesitation for first-time appliance buyers.
- Fashion:Apparel and accessories programming suffers margin compression from return rates exceeding 35 percent, constraining inventory commitment.
- Health & Beauty:Serums, skincare systems, and wellness devices attract the steepest advertiser investment growth through visceral camera-ready demonstrations.
Volume placements concentrate in Electronics; the faster expansion belongs to Health & Beauty.
Sales Channel:
Channel cost structures and regulatory exposure diverge sharply, with legacy broadcast carrying fixed infrastructure overhead while digital platforms fragment compliance jurisdiction.
- Television:Dedicated shopping channels maintain 24-hour programming schedules with captive studio production and real-time inventory countdowns. QVC Deutschland and HSE24 anchor viewer loyalty in Germany through presenter-driven appointment viewing.
- Online:Streaming platform migration enables algorithmic personalization but forces dual maintenance of satellite and over-the-top delivery systems.
- Mobile Apps:Live-stream shopping on native applications displaces toll-free ordering among consumers under 35 in South Korea and urban China.
- Direct Response Advertising:Infomercial slots on general entertainment networks compress decision windows through manufactured urgency and limited-time offers.
Revenue concentration remains with Television; Mobile Apps are climbing the fastest as younger demographics abandon legacy broadcast formats.
Customer Demographics:
Generational viewing habits and payment instrument penetration determine which demographics respond to live selling versus on-demand catalog browsing.
- Baby Boomers:Consumers over 55 generate disproportionate health and beauty volume through extended on-air demonstrations they trust more than digital advertising. FTC truth-in-advertising enforcement resonates with this cohort's demand for substantiated claims.
- Millennials:Mobile-native presentation formats and buy-now-pay-later integration drive electronics and appliance purchases without credit card requirements.
- Gen X:Balanced exposure to broadcast and streaming channels produces hybrid purchase behavior across all product categories.
- Families:Household electronics programming targets multi-generational decision-making with installment billing accessibility.
Transaction value peaks with Baby Boomers; Millennial engagement is gaining share fastest through social commerce platform migration.
Payment Mode:
Payment infrastructure penetration and regulatory treatment of consumer credit reshape which modes enable high-value teleshopping conversion.
- Installment Plans:Buy-now-pay-later integration with toll-free ordering systems removes credit card penetration barriers for appliance purchases in underbanked Indian markets.
- Credit Card:Chargeback protections and rewards programs sustain preference for electronics transactions in mature markets.
- Debit Card:Immediate settlement reduces merchant discount fees but limits buyer protection perception.
- PayPal:Digital wallet adoption concentrates in mobile app environments where guest checkout accelerates impulse conversion.
Credit Card usage dominates transaction value; Installment Plans show the steepest expansion trajectory as operators penetrate cash-preferred demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health and beauty programming concentrates in Germany and the United States, where aging populations over 55 sustain extended on-air demonstrations. Electronics volume clusters in tier-two Indian cities with cash-on-delivery preferences. Japan's wellness segment attracts strict regulatory oversight.
United States
Baby Boomers over 55 generate disproportionate transaction value through trust in substantiated health claims. The FTC enforces truth-in-advertising standards that mandate documented evidence for live wellness programming. Pennsylvania's captive studio infrastructure anchors QVC's margin control across broadcast slots.
Germany
HSE24 and QVC Deutschland command substantial viewer loyalty through presenter-driven appointment viewing. The EU Consumer Rights Directive imposes cooling-off periods that standardize trust mechanisms for electronics programming. North Rhine-Westphalia's production concentration creates geographic supply risk for operators seeking diversification.
India
Tier-two and tier-three cities present white space for Hindi-language household electronics with aggressive price positioning. TRAI regulates broadcast content while RBI oversees payment instrument integration for installment billing. Mumbai-based Naaptol dominates regional dialect programming with cash-on-delivery accessibility.
Japan
Wellness device demonstrations attract escalating regulatory scrutiny from the Consumer Affairs Agency. METI monitors cross-border streaming platform migration that fragments traditional broadcast jurisdiction. Tokyo's Jupiter Shop Channel anchors competitive positioning through transparent clinical substantiation protocols.
United Kingdom
Shop TJC Limited specializes in gemstone programming amid synthetic diamond price floor collapse. The UK's Advertising Standards Authority enforces parallel substantiation requirements to EU frameworks. London's broadcast production clusters face talent scarcity for hybrid television-mobile presentation formats.
Teleshopping Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with captive studio operators sustaining margin control while modular production entrants fragment regional markets. The vendor base organizes around three archetypes: integrated broadcast-studio operators, mobile-native platform specialists, and collectible-numismatic niche players. Consolidation pressure concentrates among legacy satellite channels facing streaming migration costs. Dominant competitive moves include geographic expansion into underpenetrated tier-two cities and installment billing integration with toll-free ordering systems.
Within the integrated broadcast-studio tier, QVC and HSE24 exemplify captive production models that compress decision windows through real-time inventory countdowns. Among collectible-specialist operators, America's Collectibles Network, Inc. occupies a position defined by deep numismatic focus rather than diversified category breadth. These anchors represent how specialization versus integration shapes competitive resilience across diverging regulatory and technology pathways.
| Leading Market Players |
|---|
| America's Collectibles Network, Inc. |
| Naaptol Online Shopping Private Limited |
| QVC |
| HSE24 |
| Jupiter Shop Channel |
| HSN, Inc. |
| Gem Shopping Network Inc. |
| Jewelry Television |
| Shop TJC Limited |
| Others |
Cost & Logistics Intelligence
Cloud-based production infrastructure is collapsing fixed cost barriers for studio operations while simultaneously fragmenting supply concentration away from legacy captive facilities in Pennsylvania and North Rhine-Westphalia. This technology shift enables mid-market operators to compress capital requirements and reconfigure pricing power across regional markets.
Pricing Analysis
Volume placements concentrate in electronics programming where extended demonstration time justifies premium positioning; margin protection erodes in fashion segments where return rates exceed 35 percent. Three-tier pricing structure across premium, standard, and economy levels separates QVC's presenter-driven appointment viewing from modular entrants competing on price. Cost compression in mid-market jewelry programming intensifies because synthetic diamond substitutes collapse gemstone price floors. Tier-two Indian cities show highest price sensitivity due to cash-on-delivery preferences and limited credit card penetration.
Supply Chain Analysis
Single-source vulnerability sits with captive studio infrastructure concentrated in Pennsylvania and North Rhine-Westphalia, creating geographic supply risk for operators seeking production diversification. Raw material dependencies include broadcast transmission equipment, modular studio components, and presenter talent pools. Supply chain risk centers on regulatory fragmentation as streaming platform migration forces dual maintenance of satellite and over-the-top delivery systems. Distribution runs through dedicated shopping channels with 24-hour programming schedules, toll-free ordering systems, and emerging buy-now-pay-later platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The teleshopping market is becoming a vertical-integration race as operators pursue captive studio production to sustain margin control against modular entrants fragmenting regional markets.
For Market Incumbents: Extend presenter-driven appointment viewing formats into streaming platform environments to defend audience loyalty against mobile-native competitors. Deepen backward integration into cloud-based production infrastructure to reduce geographic supply risk from Pennsylvania and North Rhine-Westphalia concentration. Prioritize clinical substantiation investment to exploit Japan Consumer Affairs Agency penalty escalation and differentiate wellness programming. For New Entrants and Emerging Players: Enter via tier-two and tier-three Indian cities with Hindi-language household electronics programming and cash-on-delivery accessibility. Target underpenetrated aging demographics in Germany and the United States with health and beauty segments requiring extended on-air demonstrations. Pursue installment billing convergence with toll-free ordering systems to remove credit card penetration barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of modular production technology providers serving Southeast Asian mid-market operators. Long-term viability favors integrated broadcast-studio operators with dual streaming capability and established presenter talent pipelines. Watch for inflection in mobile app penetration rates among consumers under 35 as signal of legacy broadcast displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Studio Modularization | Reduces capital barriers for Southeast Asian entrants competing against QVC's captive infrastructure. |
| Installment Billing Integration | Enables appliance penetration in India's cash-preferred tier-two cities without credit requirements. |
| Clinical Substantiation Investment | Creates compliance advantage under Japan Consumer Affairs Agency escalating penalty schedules. |
| Hybrid Talent Development | Addresses presenter scarcity for simultaneous television and mobile-native presentation formats. |
| Streaming Platform Migration | Forces dual infrastructure maintenance while fragmenting regulatory jurisdiction across delivery modes. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with teleshopping channel executives, studio production managers, presenter talent agents, and payment platform integration specialists. Bottom-up modeling of transaction volumes across product categories reconciled with top-down market sizing from FTC enforcement disclosures, EU Consumer Rights Directive implementation reports, and TRAI broadcast licensing data.
Data-stream reconciliation across shipment records, advertising expenditure filings, and inventory turnover metrics shaped the analytical framework. Segmentation dimensions included product category, sales channel, customer demographic cohort, and payment mode preference across the projection horizon. CAGRs were derived from trend extrapolation of aging demographic penetration, synthetic gemstone substitution rates, and mobile app adoption curves among under-35 consumers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated streaming platform migration or presenter talent supply constraints. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Deviation in mobile-native consumer conversion rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Middle East and North Africa Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
Argentina OOH and DOOH Market