
 Vegan Cactus Leather Market | 2026-2036
Vegan Cactus Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Cactus Leather Market Analysis
Aftermarket material certification and repair services is tilting margin pools away from virgin production toward lifecycle stewardship. Adriano Di Marti anchors its position through captive farming partnerships in Zacatecas. BASF SE leverages polymer chemistry expertise to engineer bio-based polyurethane coatings that bond with cactus fiber substrates. Kuraray Co. Ltd. competes on synthetic leather heritage while navigating plant-based transition demands from European automotive clients.
Vegan cactus leather denotes a bio-fabricated material harvested from mature Opuntia ficus-indica cladodes, processed through mechanical desalination and protein stabilization to yield a fibrous sheet laminated with waterborne polyurethane at 0.8-1.2 mm gauge for upholstery-grade durability. The material serves as a chromium-free substitute in applications where tactile performance and abrasion resistance must meet automotive and luxury specifications. Handbag applications currently occupy the dominant margin pool given unit premiums and brand storytelling value, while automotive interiors represent the fastest-growing segment as OEMs face EU fleet sustainability mandates. Footwear trails in adoption due to flex-fatigue testing gaps that cactus fiber formulations have yet to close against bovine hide benchmarks.
REACH restrictions on hexavalent chromium and the EU Green Deal's circular economy action plan shape product formulation standards across European supply chains, forcing tannery-adjacent chemical suppliers to recertify inputs. Mexico's environmental regulator enforces wastewater discharge limits on cactus processing facilities, raising capital requirements for new entrants in Jalisco. Stakeholders must monitor whether bio-based content thresholds in emerging procurement rules exclude waterborne polyurethane lamination from qualifying as fully renewable.
Market Dynamics
REACH restrictions on hexavalent chromium and the EU Green Deal's circular economy mandates are forcing tannery-adjacent chemical suppliers to recertify inputs, redirecting capital toward bio-based polyurethane lamination technologies that bond with cactus fiber substrates.
Growth Catalysts
- REACH chromium restrictions:European ECHA enforcement accelerates substitution toward plant-based alternatives in automotive upholstery and luxury handbag specifications.
- Guadalajara cluster proximity:Mexico's integrated farming-to-sheet processing in Jalisco reduces raw material transport costs and stabilizes fiber quality for export-grade material.
- Automotive sustainability mandates:EU fleet CO₂ regulations pressure OEMs to certify bio-based interior materials, opening specification windows for cactus-derived substrates.
Market Restraints
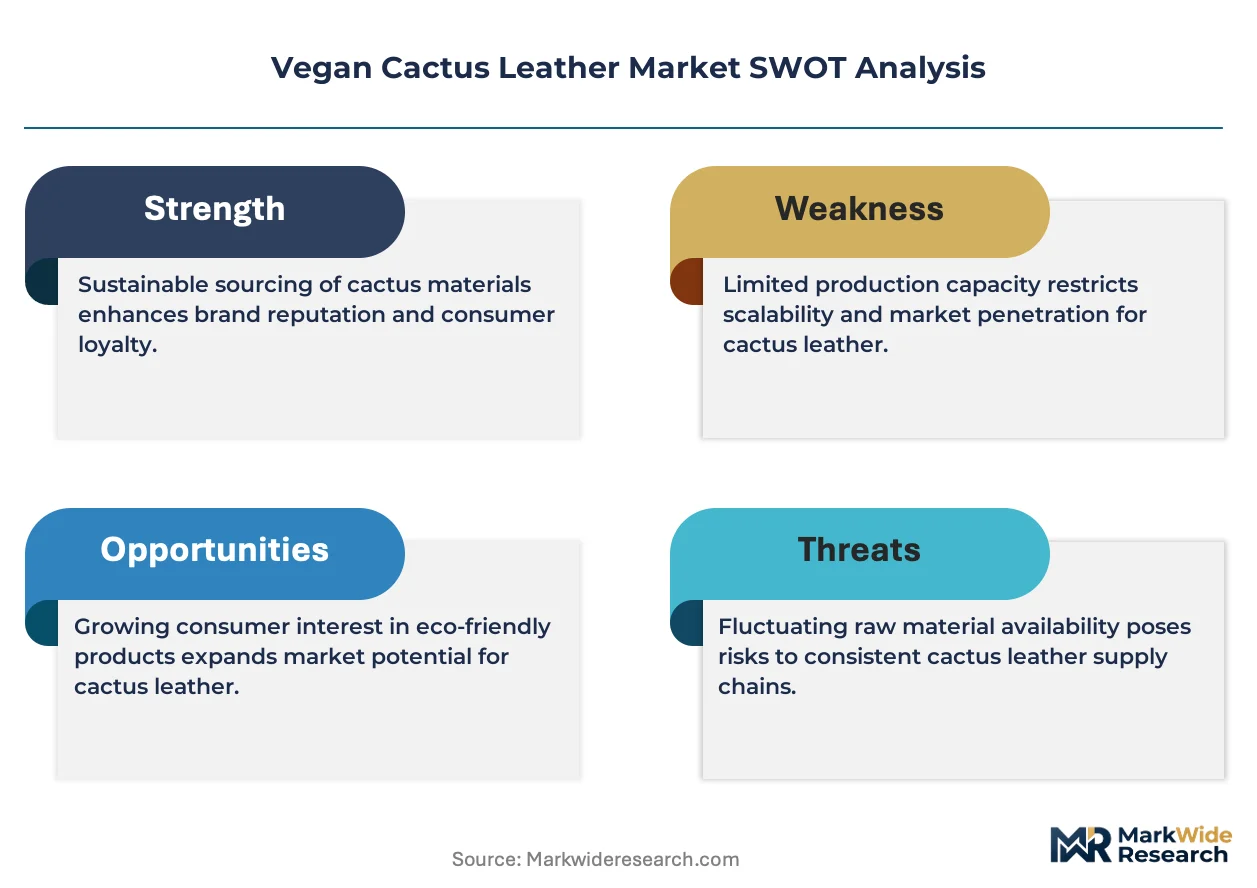
- Waterborne polyurethane dependency:Bio-based content thresholds in emerging procurement rules may exclude laminated materials from qualifying as fully renewable, limiting premium pricing power.
- Jalisco supply concentration:Regulatory enforcement of wastewater discharge limits raises capital barriers for new entrants, entrenching incumbent processors.
- Footwear flex-fatigue gaps:Cactus fiber formulations have yet to close performance benchmarks against bovine hide in repeated bending stress tests, delaying adoption in sneaker and boot applications.
Strategic Opportunities
- Aftermarket certification services:Lifecycle stewardship models including material repair and recertification capture margin pools shifting away from virgin production.
- Furniture upholstery expansion:Contract hospitality and office furniture segments remain underpenetrated relative to handbags, offering volume scale without luxury brand gatekeeping.
- Waterborne bio-polymer convergence:Advances in bio-based polyurethane chemistry from specialty chemical suppliers enable thinner, more pliable coatings that expand application range.
Industry Challenges
- Protein stabilization expertise:Mechanical desalination and fiber sheet formation require specialized process engineers scarce outside established Mexican processing facilities.
- Multi-jurisdiction certification timelines:Automotive OEMs demand simultaneous compliance with EU REACH, US EPA standards, and OEM-specific material qualification protocols, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Cactus Leather Market |
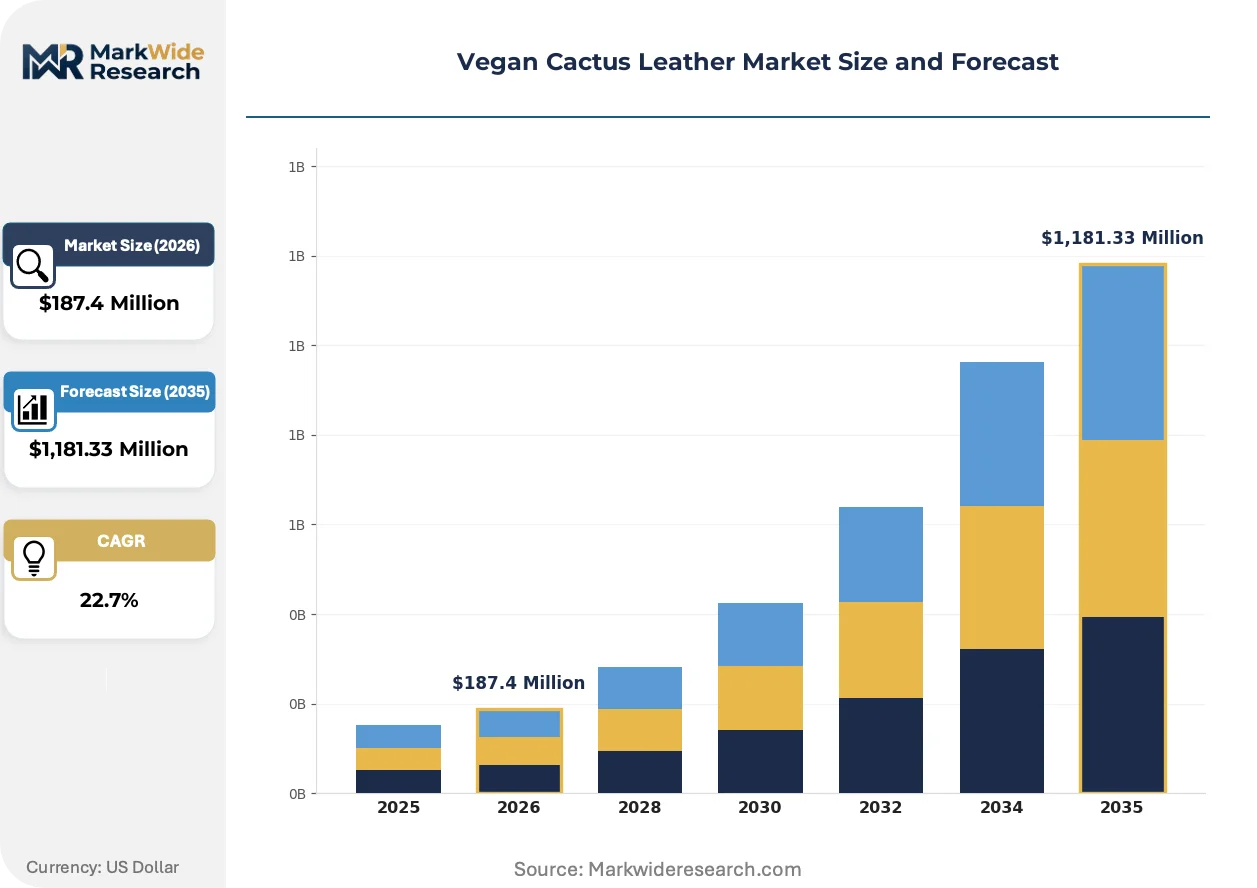
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handbags, Footwear, Upholstery, Accessories Application: Fashion, Automotive Interiors, Furniture, Sporting Goods End User: Retail Consumers, Manufacturers, Wholesalers, Designers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | H.R. Polycoats Pvt. Ltd., Alfatex Italia, Adriano Di Marti, Ultrafabrics, DuPont, Kuraray Co. Ltd., Yantai Wanhua Group Co. Ltd., Anli Group, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Cactus Leather Market Emerging Trajectories
Digital material passports and blockchain traceability systems are rewiring how bio-fabricated leather credentials travel through supply chains, compressing verification timelines while raising transparency expectations among brand sustainability officers.
Waterborne polyurethane coating technology is virtualizing the boundary between synthetic and bio-based material categories. Specialty chemical suppliers now engineer bio-based polyurethane dispersions that bond at molecular level with cactus fiber sheets. Automotive tier-one suppliers in Germany and Italy are qualifying these laminates for seat and dashboard applications at accelerated pace. The technology is virtualizing traditional tannery economics by eliminating chromium tanning infrastructure entirely.
EU Green Deal circular economy action plan mandates are hardening material disclosure requirements across European supply chains. ECHA enforcement of substance restrictions now extends to imported finished goods, not just EU-manufactured inputs. Luxury fashion houses sourcing from Mexican processors must demonstrate full chemical inventory transparency. Handbag and accessories segments face the steepest compliance ramps given direct consumer-facing brand exposure.
Brand sustainability officers are consolidating supplier relationships around vertically integrated processors with captive farming operations. Single-source accountability replaces fragmented raw material purchasing. Procurement teams at French and Italian luxury houses now conduct direct audits of Zacatecas farming partnerships rather than relying on trading intermediaries. This concentration is most visible in premium handbag collections where material origin storytelling commands retail price premiums.
Vegan Cactus Leather Market Segmentation
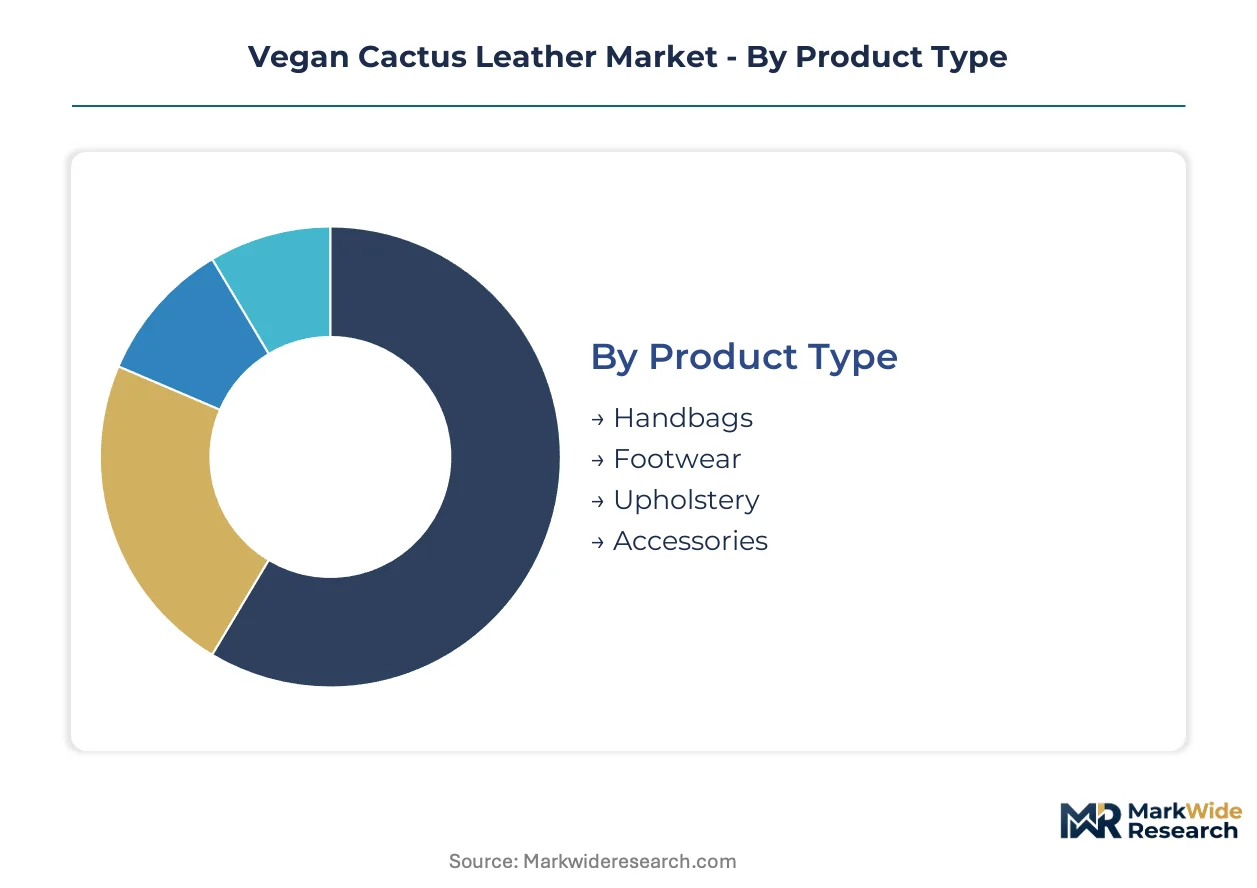
Cycle times vary dramatically across cactus leather applications. Handbag collections refresh seasonally while automotive qualification cycles stretch across multiple years. Understanding these velocity differentials shapes inventory planning and capital allocation for processors and brand partners.
Product Type:
Replacement cycles stretch from months in accessories to decades in upholstery, compressing margin capture windows for faster-turning categories.
- Handbags:Premium accessory specifications at 0.8-1.2 mm gauge command the highest unit economics. Italian and French luxury houses concentrate specification activity here, driven by origin storytelling requirements and direct consumer brand exposure.
- Footwear:Flex-fatigue performance gaps against bovine hide benchmarks delay adoption in sneaker and boot applications. Repeated bending stress testing remains unresolved for cactus fiber formulations.
- Upholstery:Contract hospitality and residential furniture segments offer volume scale without luxury brand gatekeeping constraints.
- Accessories:Wallets, belts, and small leather goods provide entry-point positioning for emerging processors.
Handbags dominate installed base. Footwear is where expansion concentrates once flex-fatigue benchmarks close.
Application:
Margin structures diverge sharply between specification-driven industrial procurement and brand-mediated consumer markets.
- Fashion:Direct-to-consumer brand storytelling commands retail price premiums. ECHA substance restrictions now extend to imported finished goods, forcing full chemical inventory transparency across Mexican supply chains.
- Automotive Interiors:EU fleet CO₂ regulations pressure OEMs to certify bio-based materials for seat and dashboard applications. Tier-one suppliers in Germany and Italy accelerate qualification timelines for waterborne polyurethane laminates.
- Furniture:Contract office and hospitality segments remain underpenetrated relative to fashion applications.
- Sporting Goods:Performance requirements in athletic equipment create additional durability testing hurdles.
Fashion commands current revenue concentration. Automotive interiors are climbing the fastest as OEM sustainability mandates harden.
End User:
Procurement authority patterns split between consolidated manufacturer specifications and fragmented designer-led purchasing.
- Retail Consumers:Sustainability-conscious purchasers in European and North American markets drive brand-level demand signaling.
- Manufacturers:Automotive tier-one suppliers and furniture producers consolidate volume procurement around vertically integrated processors with captive farming operations.
- Wholesalers:Trading intermediaries face disintermediation as luxury houses conduct direct audits of Zacatecas farming partnerships.
- Designers:Independent fashion designers provide market development function for novel material adoption.
Manufacturers dominate installed base. Retail consumers are where expansion concentrates as sustainability transparency expectations rise.
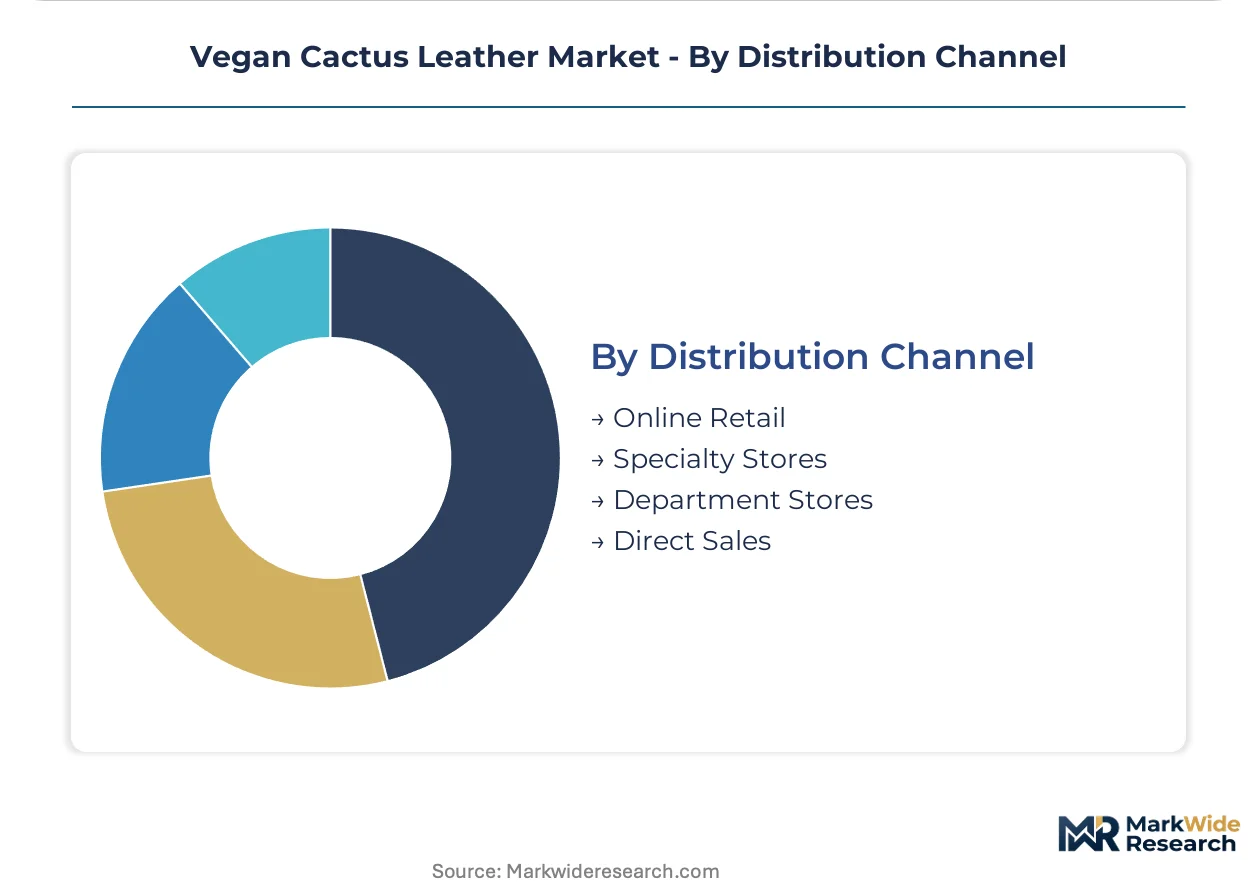
Distribution Channel:
Channel economics favor direct relationships for specification-heavy applications while intermediaries persist in fragmented retail segments.
- Online Retail:Digital material passports and blockchain traceability systems compress verification timelines for direct-to-consumer sales.
- Specialty Stores:Curated sustainability-focused retail environments in Milan, Paris, and New York provide brand positioning value.
- Department Stores:Traditional retail intermediaries face margin pressure from direct brand relationships.
- Direct Sales:Automotive and furniture manufacturers source through qualified supplier programs bypassing retail channels entirely.
Direct sales dominate installed base. Online retail is where expansion concentrates as digital traceability systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European luxury buyers absorb premium pricing for traceable origin stories, while North American automotive procurement drives volume scale through specification mandates. Mexican processors command raw material cost advantages that Asian chemical suppliers struggle to replicate. Demand elasticity splits sharply between brand-mediated fashion markets and industrial procurement systems.
Mexico
Guadalajara's integrated farming-to-sheet cluster anchors global cactus fiber supply, with Zacatecas captive partnerships securing raw material pipelines for export-grade production. SEMARNAT wastewater discharge enforcement raises capital barriers for Jalisco processors, entrenching incumbent positions. Adriano Di Marti exemplifies vertical control through direct agricultural partnerships in central Mexico.
Italy
Milan-based luxury houses specify cactus-derived materials for handbag collections where origin storytelling commands retail premiums. EU Green Deal circular economy mandates harden chemical inventory disclosure requirements across Italian supply chains. Tuscany leatherworking districts now audit Mexican farming partnerships directly, bypassing traditional trading intermediaries.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg accelerate qualification timelines for bio-based interior laminates under fleet CO₂ regulations. ECHA REACH enforcement on hexavalent chromium redirects tannery-adjacent chemical procurement toward plant-based alternatives. Stuttgart OEM sustainability offices now require simultaneous compliance with EU, US EPA, and proprietary material protocols.
France
Parisian luxury conglomerates consolidate supplier relationships around single-source accountability for premium accessory collections. ANSM chemical substance tracking extends to imported finished goods, forcing full supply chain transparency. Lyon-based chemical distributors recertify polyurethane inputs to meet emerging bio-based content thresholds in procurement rules.
United States
California and New York sustainability-focused retailers drive consumer-facing brand demand for traceable bio-fabricated materials. EPA standards on imported articles create multi-jurisdiction compliance complexity for Mexican processors seeking US market access. Los Angeles apparel brands now require digital material passports compressing verification timelines for direct-to-consumer sales.
Vegan Cactus Leather Market Vendor Landscape
Capability concentration sits with integrated processors possessing captive farming partnerships; scale advantage sits with diversified chemical conglomerates with polymer chemistry expertise. The market structures around three archetypes: vertically integrated Mexican material fabricators, European specialty chemical suppliers engineering bio-based coatings, and Asian synthetic leather incumbents navigating plant-based transition demands. Dominant competitive moves include backward integration into agricultural supply and strategic partnerships with automotive tier-one suppliers for qualification acceleration.
Among chemistry-focused multinationals, BASF SE and Kuraray Co. Ltd. exemplify divergent responses to bio-based material transitions, with the former leveraging polymer dispersion expertise and the latter drawing on synthetic leather heritage. Adriano Di Marti occupies a distinct position as an integrated processor archetype, representing captive supply chain control from Zacatecas farming through finished sheet production. Chinese and Indian material suppliers including Yantai Wanhua Group Co. Ltd. and H.R. Polycoats Pvt. Ltd. sit within regional cost-competitive tiers serving domestic market development.
| Leading Market Players |
|---|
| H.R. Polycoats Pvt. Ltd. |
| Alfatex Italia |
| Adriano Di Marti |
| Ultrafabrics |
| DuPont |
| Kuraray Co. Ltd. |
| Yantai Wanhua Group Co. Ltd. |
| Anli Group |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Jalisco's integrated farming-to-sheet processing cluster concentrates raw material conversion expertise in a single Mexican state, anchoring margin capture with processors who control Opuntia ficus-indica supply from Zacatecas partnerships through finished sheet export. This geographic lock-in enables premium pricing for automotive-grade laminates while exposing buyers to single-source risk during SEMARNAT enforcement periods.
Pricing Analysis
Aftermarket certification and repair services now drive lifetime value beyond virgin sheet sales. Three-tier pricing structure across automotive-specification, luxury handbag-grade, and furniture-volume tiers reflects certification grade and captive farming provenance. Pricing pressure stems from waterborne polyurethane input costs as bio-based content thresholds tighten in EU procurement rules. Automotive tier-one suppliers exhibit lowest price sensitivity given sustainability mandate compliance requirements; contract furniture buyers face acute cost compression.
Supply Chain Analysis
Adriano Di Marti and vertically integrated Jalisco processors hold captive capacity for export-grade cactus fiber sheet production. Raw material supply draws from Zacatecas farming partnerships, Guadalajara mechanical desalination infrastructure, and BASF-engineered bio-based polyurethane dispersions. Single-source vulnerability concentrates in protein stabilization expertise scarce outside established Mexican facilities. Distribution runs through direct supplier programs to automotive OEMs and luxury house procurement offices, bypassing traditional chemical trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EU Green Deal mandates splinter demand across automotive, luxury fashion, and furniture verticals with incompatible specification timelines. Each vertical rewards different capability bundles, creating niche entry points for specialized players.
For Market Incumbents: Harden defensibility by deepening captive farming partnerships in Zacatecas against emerging Brazilian Opuntia cultivators. Accelerate waterborne bio-polymer R&D collaboration with specialty chemical suppliers to preempt coating technology substitution. SEMARNAT compliance investments should extend to closed-loop wastewater systems that raise capital barriers for prospective entrants. For New Entrants and Emerging Players: Build out contract hospitality furniture upholstery specifications where luxury brand gatekeeping is absent and volume scale rewards thinner coating expertise. Target Lyon-based chemical distributors and Stuttgart OEM sustainability offices with digital material passport capabilities that compress automotive qualification timelines. Lead with blockchain traceability systems that satisfy ECHA substance disclosure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Mexican integrated processors possessing Jalisco infrastructure but lacking automotive tier-one supplier relationships. Five-to-ten year viability hinges on closing flex-fatigue performance gaps for footwear applications. Monitor EU bio-based content threshold rulings as inflection indicator for laminated material premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Farming Partnership Expansion | Adriano Di Marti's Zacatecas control secures raw material pipeline against SEMARNAT disruption. |
| Waterborne Bio-Polymer Convergence | BASF polyurethane chemistry advances enable thinner coatings that expand automotive specification range. |
| Digital Material Passport Deployment | Blockchain traceability compresses ECHA verification timelines for direct-to-consumer luxury sales. |
| Aftermarket Certification Services | Lifecycle stewardship models capture margin pools shifting away from virgin cactus sheet production. |
| Automotive Tier-One Qualification Acceleration | German and Italian supplier integration opens EU fleet CO₂ compliance pathways for bio-based laminates. |
Methodological Framework
A standing panel of automotive tier-one supplier procurement leads, luxury house sustainability officers, Jalisco processing facility engineers, and specialty chemical R&D directors provided ongoing calibration. Primary interviews combined with secondary validation from ECHA substance restriction databases, SEMARNAT discharge compliance records, EU Green Deal implementation guidance, and customs trade flow data. Bottom-up fiber processing capacity estimates triangulated against top-down automotive interior material procurement forecasts.
Scenario-bracketing framed projections across conservative, baseline, and accelerated bio-based procurement adoption paths. Segmentation dimensions modeled include product type, application vertical, end-user procurement authority, and distribution channel complexity. CAGRs derived from fitted growth curves applied to disclosed capacity expansion timelines and OEM sustainability mandate phase-in schedules. Waterborne polyurethane coating technology maturity and protein stabilization process yield improvements served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration by Asian synthetic leather conglomerates would shift outcomes. Quarterly review of EU bio-based content threshold rulings and SEMARNAT enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Pet Gadgets Market
Consumer Goods
US Smoking Pipe Market
Consumer Goods
China Eyelash Serum Market
Consumer Goods
Commercial Induction Cooktops Market
Consumer Goods
Baby Pacifier Market
Consumer Goods
Organic Bar Soap Market
Consumer Goods
Dog Biscuit Market
Consumer Goods
Thailand Retail Market
Consumer Goods
Earplug Distributor Market
Consumer Goods
Ultra HD Action Camera Market
Consumer Goods
Canada Kitchen Appliances Market
Consumer Goods
Audio Jack Market
Consumer Goods
Barefoot Shoes Market
Consumer Goods
US Household Coffee Machine Market
Consumer Goods
White Goods Market
Consumer Goods
Global E-Cigarettes Market