
 Smart E-Cigarettes Market | 2026-2036
Smart E-Cigarettes Market Size, Share, and Industry Trends Forecast 2026-2036
Smart E-Cigarettes Market Insights
Ceramic coil substrates are repositioning heating element economics across premium device tiers. Philip Morris International leverages vertical integration in heated tobacco platforms to sustain manufacturing scale advantages. British American Tobacco anchors its competitive stance through R&D intensity in connected device architectures. Shenzhen IVPS Technology competes on cost-engineered pod systems that dominate Asian supply channels.
Smart e-cigarettes integrate sensor-enabled inhalation tracking, Bluetooth connectivity, and firmware-updatable power management circuits to deliver personalized nicotine delivery profiles. These devices serve adult smokers seeking measurable consumption data and customizable vapor outputs as alternatives to combustible products. Pod systems capture the dominant installed base among transitioners seeking low-maintenance formats, while box mods retain margin concentration within hobbyist segments demanding variable wattage control. Disposable e-cigarettes face structural pressure from environmental compliance costs across European markets.
The FDA's premarket authorization requirements, the EU Tobacco Products Directive with its notification protocols, and China's NMPA standards collectively determine market access trajectories for cross-border manufacturers. Flavor restrictions under FDA enforcement discretion and EU member-state prohibitions directly constrain product portfolio breadth for brands serving younger adult demographics. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate geographic deployment timelines and flavor development pipelines.
Market Dynamics
Flavor prohibition mandates across multiple jurisdictions are compressing product portfolio breadth and forcing manufacturers toward hardware-centric differentiation strategies centered on connected device architectures and sensor-enabled consumption tracking.
Growth Catalysts
- FDA Premarket Authorization Pathway:The streamlined review framework for modified risk tobacco products accelerates market entry timelines for adult-focused formulations that demonstrate reduced exposure claims.
- Ceramic Coil Substrates:Advanced alumina-zirconia heating elements enable precise temperature control and extended device longevity, attracting premium-tier buyers seeking consistent vapor density profiles.
- United Kingdom:The National Health Service endorsement framework for smoking cessation tools positions prescribed e-cigarettes as reimbursable alternatives within integrated care pathways.
Market Restraints
- EU Tobacco Products Directive Notification Costs:Six-to-eighteen month regulatory review cycles and substantial toxicological testing requirements create capital barriers for mid-scale manufacturers without captive laboratory infrastructure.
- Lithium-Ion Cell Supply Concentration:Cylindrical battery sourcing dependence on East Asian cell fabricators exposes device assemblers to freight volatility and export license unpredictability.
- Flavor Additive Bans:Characterizing flavor prohibitions in multiple US states and EU member states eliminate the primary differentiation vector for pod-based systems targeting adult transitioners.
Strategic Opportunities
- Japan:The heated tobacco product acceptance under PMDA guidelines creates adjacent market space for smart e-cigarettes with comparable reduced-risk positioning and clinical validation frameworks.
- Closed-Loop Recycling Mandates:Extended producer responsibility regulations across France and Germany incentivize modular device architectures with standardized battery replacement protocols.
- Bluetooth-Firmware Convergence:Integration of inhalation biometric sensors with smartphone-native health monitoring ecosystems enables subscription-based consumption analytics services.
Industry Challenges
- Aerosol Chemistry Expertise Scarcity:The specialized toxicology and analytical chemistry capabilities required for premarket authorization submissions command premium compensation and extended recruitment cycles.
- Cross-Border Certification Fragmentation:Divergent electrical safety standards between UL, CE marking, and GB testing protocols necessitate redundant product variant engineering for multi-jurisdictional deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart E-Cigarettes Market |
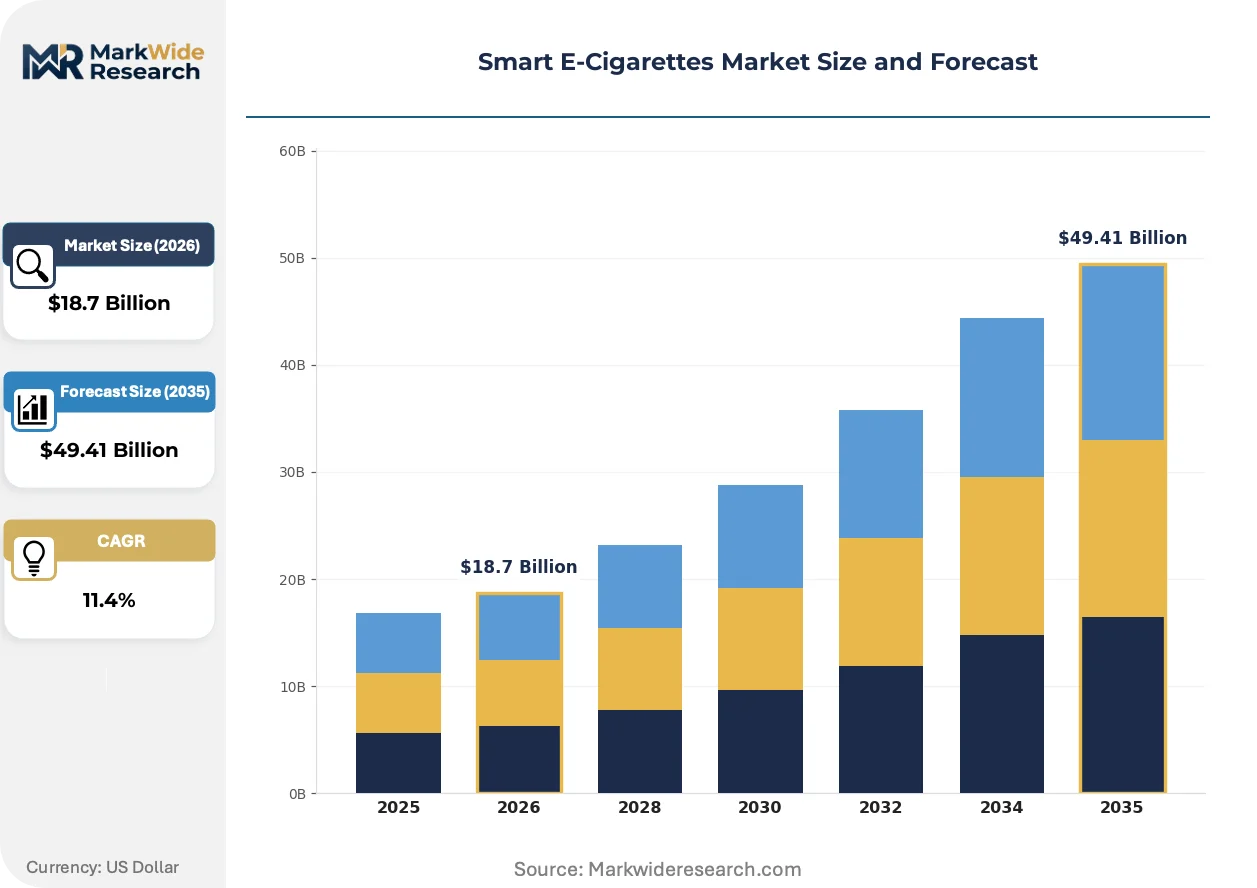
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pod Systems, Box Mods, Vape Pens, Disposable E-Cigarettes Battery Capacity: High Capacity, Medium Capacity, Low Capacity, Variable Flavor Profile: Tobacco, Menthol, Fruit, Dessert User Demographics: Young Adults, Smokers, Transitioners, Hobbyists |
| Companies Covered | Philip Morris International Inc., British American Tobacco, Altria Group, Inc., Imperial Brands, Japan Tobacco Inc., JUUL Labs, Inc., R.J. Reynolds Vapor Company, Shenzhen IVPS Technology Co., Ltd., Shenzhen KangerTech Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart E-Cigarettes Market Trends and Innovations
Sensor miniaturization and cloud-connected firmware architectures are redefining how manufacturers capture recurring revenue through consumable-agnostic service layers rather than hardware margins alone.
Precision temperature control chipsets is expanding into mainstream pod systems previously limited to fixed-output designs. Adult smokers seeking combustion-free alternatives now demand wattage-adjustable profiles previously confined to enthusiast-grade box mods. This capability migration is expanding into the standard-tier segment and compressing premium-mid-economy pricing differentiation.
REACH substance restrictions on nickel alloy compositions in heating elements are forcing migration toward stainless steel and ceramic alternatives. The industrial consequence involves supply chain requalification for coil fabricators and extended validation timelines for new material stacks. Box mod manufacturers serving European markets are responding with accelerated ceramic substrate adoption to preempt regulatory non-compliance exposure.
Direct-to-consumer subscription models are displacing traditional retail channel dependence for consumable replenishment. Closed-system pod users increasingly favor automated cartridge delivery programs over convenience store purchasing. This behavioral shift is most visible in the United States, where state-level flavor restrictions have driven adult smokers toward online procurement of compliant formulations.
Smart E-Cigarettes Market Segmentation
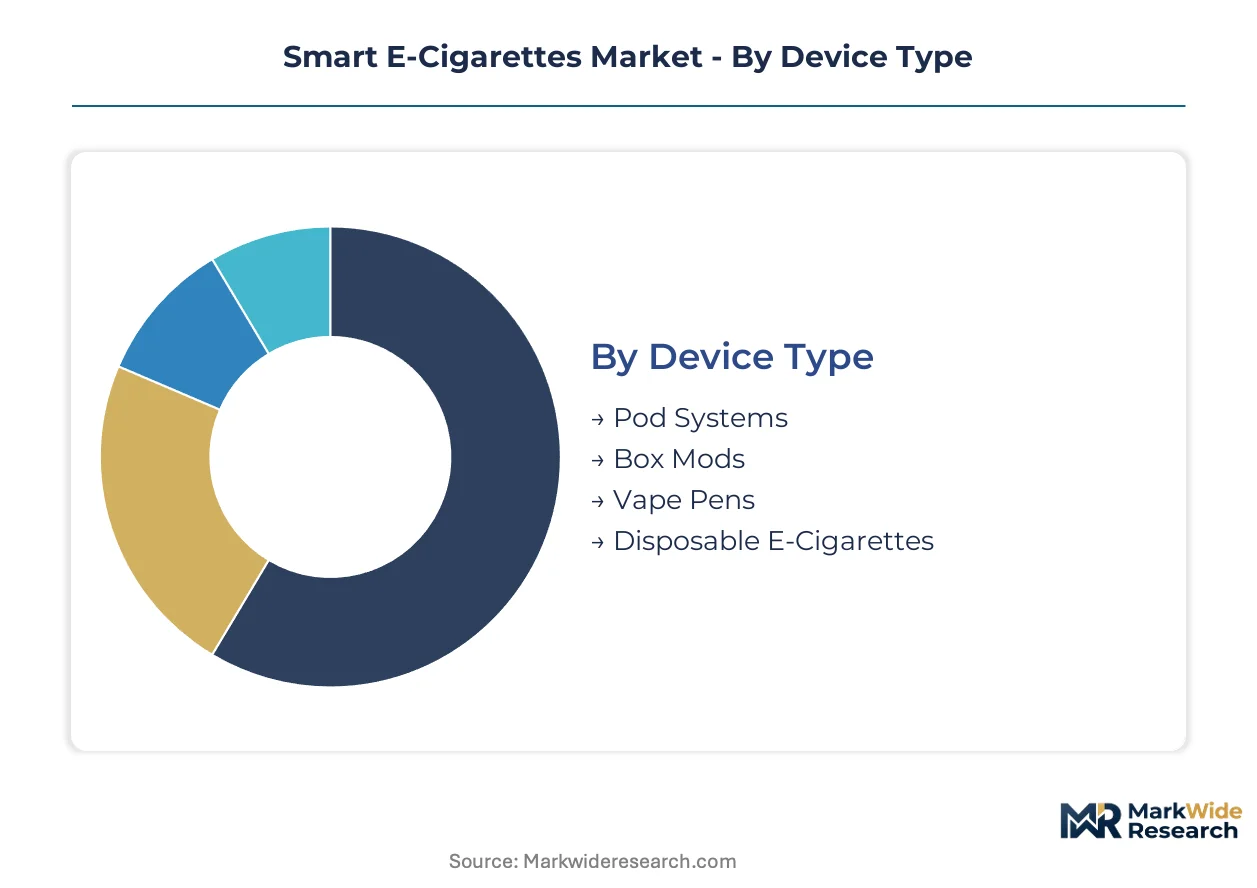
Smart e-cigarette segmentation reflects divergent user priorities across maintenance tolerance, nicotine control precision, and flavor accessibility. Manufacturers calibrate hardware architectures and consumable portfolios to match distinct consumption patterns rather than pursuing undifferentiated scale.
Device Type:
Buyers in this category separate by technical sophistication tolerance and willingness to manage replaceable components versus sealed convenience.
- Pod Systems:Closed or refillable cartridge architectures with integrated coil assemblies minimize user maintenance. Adult transitioners in the United Kingdom and United States gravitate toward these formats as NHS-endorsed cessation tools and FDA-authorized alternatives reduce perceived risk.
- Box Mods:Modular chassis accommodating interchangeable tanks, rebuildable atomizers, and variable wattage chipsets deliver granular vapor density control. Hobbyists across Germany and France drive demand for temperature control precision and firmware customization capabilities.
- Vape Pens:Cylindrical form factors bridge portability and moderate battery capacity for intermittent users seeking discretion without pod system lock-in.
- Disposable E-Cigarettes:Single-use integrated designs face structural compression from EU extended producer responsibility mandates and French recycling quotas raising landed cost structures.
Pod systems lead volumes today; box mods command the steepest per-unit margins.
Battery Capacity:
Power architecture preferences map directly to daily consumption intensity and charging infrastructure access patterns.
- High Capacity:Cells exceeding 3000mAh enable multi-day operation without recharge cycles. Heavy users in China and the United States prioritize these configurations where all-day nicotine delivery consistency outweighs device bulk.
- Medium Capacity:1500-3000mAh configurations balance portability with sufficient endurance for moderate daily sessions. Urban commuters across the United Kingdom and Japan favor this tier for pocket-friendly dimensions without midday charging dependency.
- Low Capacity:Sub-1500mAh designs serve occasional users and backup device scenarios where minimal weight supersedes runtime requirements.
- Variable:Swappable cell architectures allow users to scale capacity via external 18650 or 21700 cells. Enthusiast segments in Germany and Australia adopt these for field-replaceable power without device retirement.
Medium capacity dominates unit shipments; high capacity is climbing fastest among replacement purchases.
Flavor Profile:
Palate preferences in this category are restructuring under regulatory compression, with permissible formulations becoming scarcer competitive terrain.
- Tobacco:Unflavored or cured tobacco-replicating formulations align with FDA modified risk tobacco product pathways and NHS prescribing guidelines. Manufacturers targeting authorized medical channels in the United States and United Kingdom concentrate development here.
- Menthol:Cooling sensation additives retain regulatory tolerance in more jurisdictions than characterizing flavors. Smokers transitioning in Germany and Japan show persistent demand for menthol analogs to combustible products.
- Fruit:Berry, citrus, and tropical profiles face prohibitions across multiple US states and EU member states, constraining legal addressable market for pod-based brands.
- Dessert:Custard, bakery, and confectionery flavor categories encounter the strictest enforcement discretion under FDA youth access prevention priorities.
Tobacco formulations lead compliant volumes; menthol holds the most stable regulatory footing.
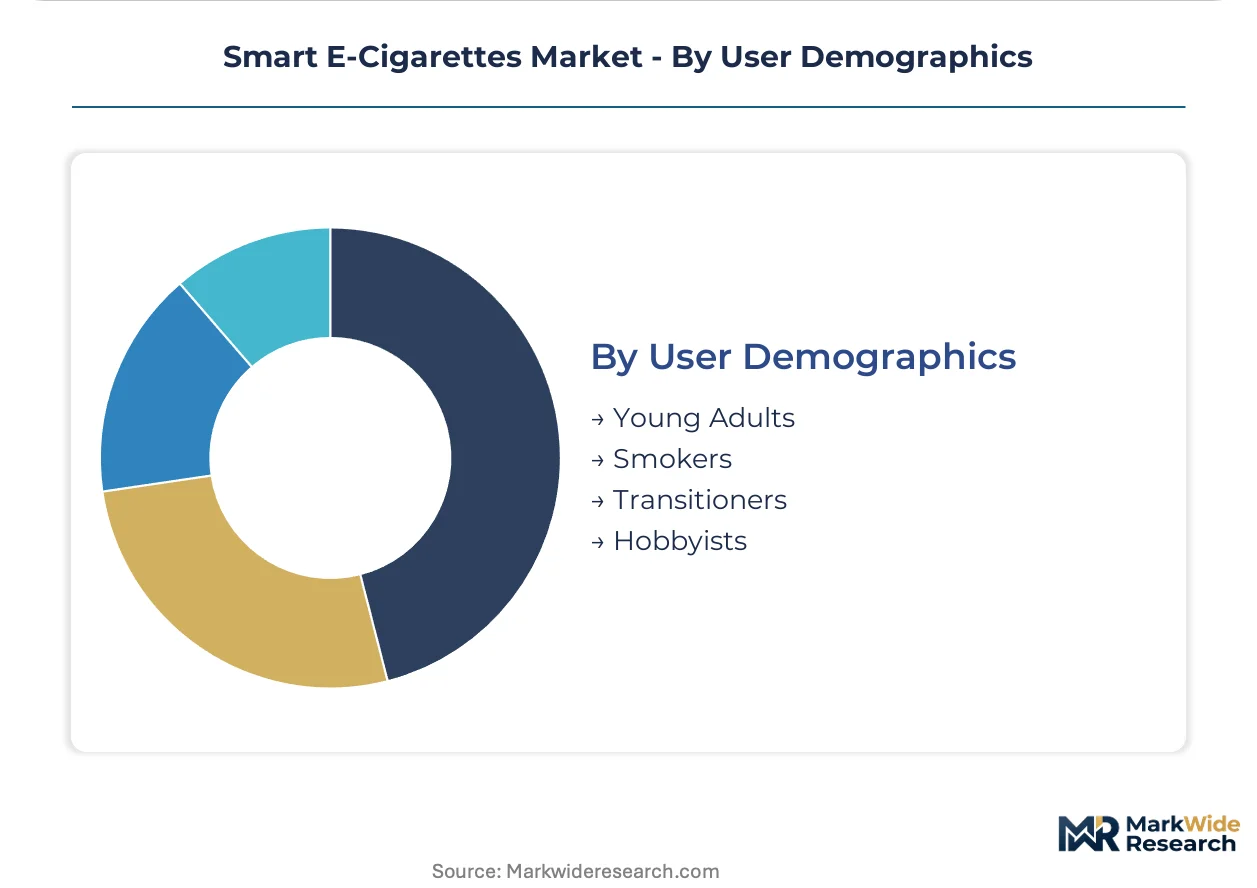
User Demographics:
Life stage and smoking history in this category determine price sensitivity, feature complexity appetite, and channel preference.
- Transitioners:Adult smokers seeking measurable migration from combustible products demand connected consumption tracking and step-down nicotine protocols. United Kingdom prescribing pathways and US employer wellness subsidies accelerate this segment's expansion.
- Hobbyists:Coil building, firmware modification, and cloud-chasing subcultures sustain premium hardware demand despite shrinking as a population share. German and French enthusiast communities drive box mod and rebuildable atomizer innovation cycles.
- Young Adults:Age-restricted cohorts face flavor prohibition exposure and marketing limitation constraints across FDA and EU jurisdictions.
- Smokers:Dual-use populations maintaining combustible and vapor product consumption show lower device investment willingness and higher price elasticity.
Transitioners are expanding most quickly; hobbyists retain the highest per-capita hardware spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the global smart e-cigarette manufacturing base, with component fabrication and device assembly concentrating in the Pearl River Delta before distribution to regulated consumer markets across North America, Europe, and Asia-Pacific.
United States
Adult smokers transitioning from combustible products drive demand for connected consumption tracking devices. The FDA premarket tobacco product application pathway determines market access timelines for authorized formulations. California and New York host the largest installed bases of sensor-enabled devices among employer wellness program participants.
China
Domestic demand for reduced-risk alternatives expands alongside manufacturing scale for export markets. The NMPA standards framework governs product registration and quality certification requirements. Shenzhen's industrial corridor supplies ceramic coil substrates and precision temperature control chipsets to global device assemblers.
United Kingdom
NHS prescribing pathways position e-cigarettes as reimbursable smoking cessation tools within integrated care networks. The Medicines and Healthcare products Regulatory Agency oversees medical device classification for connected inhalation trackers. London and Manchester clusters concentrate specialty retail and clinical distribution partnerships.
Germany
Hobbyist segments demanding variable wattage control and rebuildable atomizers sustain premium hardware demand. The Federal Institute for Drugs and Medical Devices implements EU Tobacco Products Directive notification protocols. Bavaria and North Rhine-Westphalia host enthusiast communities driving firmware customization and coil-building innovation cycles.
Japan
Heated tobacco product acceptance under PMDA guidelines creates adjacent market space for smart e-cigarettes with comparable reduced-risk positioning. The Ministry of Economy, Trade and Industry oversees electrical safety standards for connected device architectures. Tokyo and Osaka metropolitan areas concentrate early adopters of biometric sensor integration with smartphone health ecosystems.
Smart E-Cigarettes Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities, with multinational tobacco conglomerates leveraging premarket authorization expertise against agile Chinese fabricators optimizing cost-engineered pod systems for price-sensitive Asian channels. The vendor base stratifies into three tiers: vertically integrated heated tobacco platforms, R&D-intensive connected device specialists, and high-volume contract manufacturers serving private-label brands. Dominant competitive moves include backward integration into ceramic coil substrate production and strategic partnerships with lithium-ion cell fabricators to secure battery supply.
Within the multinational tier, Philip Morris International Inc. and British American Tobacco occupy positions defined by regulatory submission infrastructure and clinical validation capabilities. Among Asia-Pacific fabricators, Shenzhen IVPS Technology Co., Ltd. and Shenzhen KangerTech Technology Co., Ltd. exemplify cost-optimized manufacturing archetypes competing on pod system economies and supply chain velocity. Altria Group, Inc. anchors the North American distribution-focused segment.
| Leading Market Players |
|---|
| Philip Morris International Inc. |
| British American Tobacco |
| Altria Group, Inc. |
| Imperial Brands |
| Japan Tobacco Inc. |
| JUUL Labs, Inc. |
| R.J. Reynolds Vapor Company |
| Shenzhen IVPS Technology Co., Ltd. |
| Shenzhen KangerTech Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Shenzhen's Pearl River Delta manufacturing corridor anchor supply-side concentration, translating captive coil fabrication capabilities into pricing discipline that resists commoditization pressure across pod system tiers.
Pricing Analysis
Input-cost pass-through from lithium-ion cell sourcing volatility and REACH-compliant ceramic substrate migration is compressing margins across standard-tier pod systems. Three-tier pricing structure across premium, standard, and economy levels separates firmware-customizable box mods from fixed-output pod devices and single-use disposables. Pricing pressure stems from EU extended producer responsibility mandates raising landed costs for sealed-system designs. Transitioners seeking NHS-prescribed cessation tools show lowest price sensitivity; dual-use smokers maintaining combustible consumption exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from multinational tobacco conglomerates, while specialty distributors serve hobbyist segments across Germany and France. Manufacturing gravity centers on China, South Korea, and Japan for precision temperature control chipsets and cylindrical battery cells. Raw material dependencies span alumina-zirconia ceramic substrates, nickel-chrome heating alloys, and lithium cobalt oxide cathodes. Single-source vulnerability concentrates in East Asian cell fabrication. Distribution runs through Shenzhen export hubs before customs clearance at destination markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA premarket authorization milestones for modified risk tobacco products accelerate demand for clinical-validation-capable device architectures.
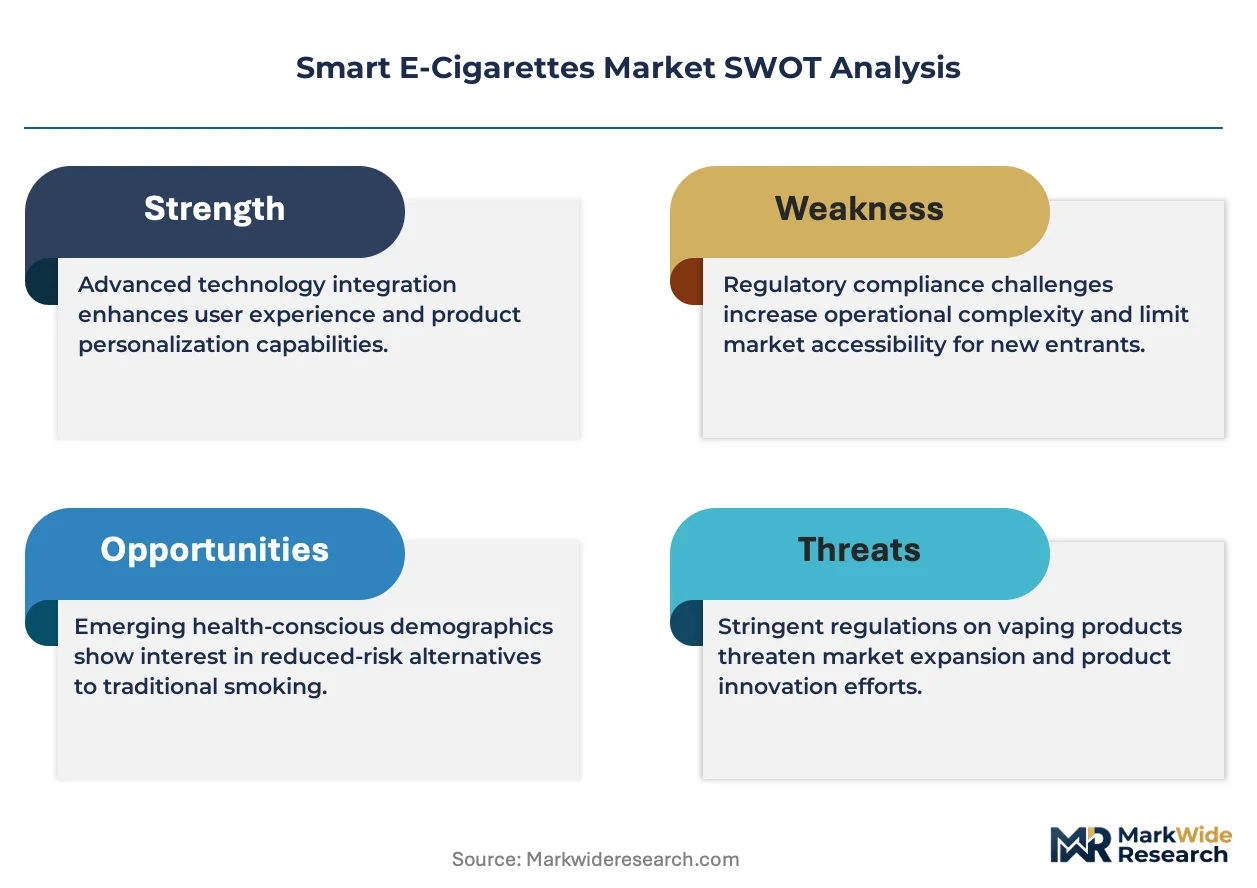
For Market Incumbents: Deepen backward integration into ceramic coil substrate production to preempt REACH substance restrictions on nickel alloys. Fortify toxicology submission infrastructure against aerosol chemistry expertise scarcity that extends recruitment cycles. Capture employer wellness program procurement channels before connected-device competitors consolidate NHS prescribing pathways. For New Entrants and Emerging Players: The price-point gap between premium box mods and economy disposables offers white-space opportunity for mid-tier pod systems with biometric sensor integration. Target Japan's PMDA-validated reduced-risk positioning where heated tobacco acceptance creates adjacent demand. Pursue direct-to-consumer subscription models displacing convenience store dependence for consumable replenishment. For Investors and Strategic Acquirers: Multinational tobacco conglomerates are the most active acquirers in this space, seeking clinical validation capabilities and premarket authorization expertise. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than hardware margins alone. Monitor FDA enforcement discretion on flavor additive prohibitions as inflection indicator for portfolio breadth compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | REACH compliance on heating elements forces supply chain requalification that favors captive fabrication. |
| Firmware-Subscription Service Launch | Bluetooth-health ecosystem integration enables recurring revenue beyond hardware margins in United States and Japan. |
| Premarket Authorization Submission | FDA modified risk tobacco product pathway determines market access timelines for adult-focused formulations. |
| Modular Device Architecture Redesign | France and Germany extended producer responsibility mandates incentivize standardized battery replacement protocols. |
| Clinical Validation Partnership | NHS prescribing pathways in United Kingdom require medical device classification for connected inhalation trackers. |
Research Methodology
Direct dialogue with device engineering leads, regulatory affairs specialists at premarket authorization consultancies, NHS clinical commissioning group procurement officers, and Shenzhen-based contract manufacturing executives grounded qualitative insights. Secondary validation drew from FDA 510(k) and PMTA filing databases, EU TPD notification registries, NMPA product certification listings, and customs export records from China's General Administration. Bottom-up unit shipment estimates triangulated against top-down category spending analysis.
Bottom-up modeling segmented volume and value across device type, battery capacity tier, flavor profile regulatory status, and user demographic cohort throughout the forecast period. CAGRs derived from regression analysis against adult smoking prevalence transition rates, regulatory authorization timelines, and employer wellness program adoption curves. Industry-specific inputs included REACH substance restriction implementation schedules and lithium-ion cell freight rate volatility indices.
Caveats apply where FDA enforcement discretion shifts, EU member-state flavor prohibitions expand, or East Asian battery export licensing unpredictability could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory divergence persistence and substitution elasticity between heated tobacco and smart e-cigarette formats. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
Lighter Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
North America Cigarette Lighter Market
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
China Smoking Pipe Market