
 US Higher Education Market | 2026-2036
US Higher Education Market Size, Share, and Industry Trends Forecast 2026-2036
US Higher Education Market Outlook
Market Context
The online program management channel is rewriting how degree credentials reach working adults. Harvard University leverages its extension school infrastructure to sustain enrollment scale beyond traditional residential capacity. Stanford University anchors its position through proprietary MOOC platforms that feed into stackable degree pathways. Yale University competes in the same digital space through curated professional certificate streams that bridge toward full graduate degrees.
Technical Definition and Segment Structure
Higher education in the United States constitutes a tertiary credentialing system encompassing accredited degree-granting institutions regulated by regional and national bodies, delivering curricula measured in credit hours toward stackable qualifications. The system serves workforce preparation, research generation, and social mobility functions across public and private institutional forms. Public universities dominate enrollment volume due to state-subsidized tuition structures, while fully online delivery modes capture the fastest structural expansion as asynchronous learning platforms reduce geographic and temporal barriers to access. Master's degree programming concentrates margin pools through premium tuition pricing and employer-sponsored reimbursement channels.
Regulatory Framework and Outlook
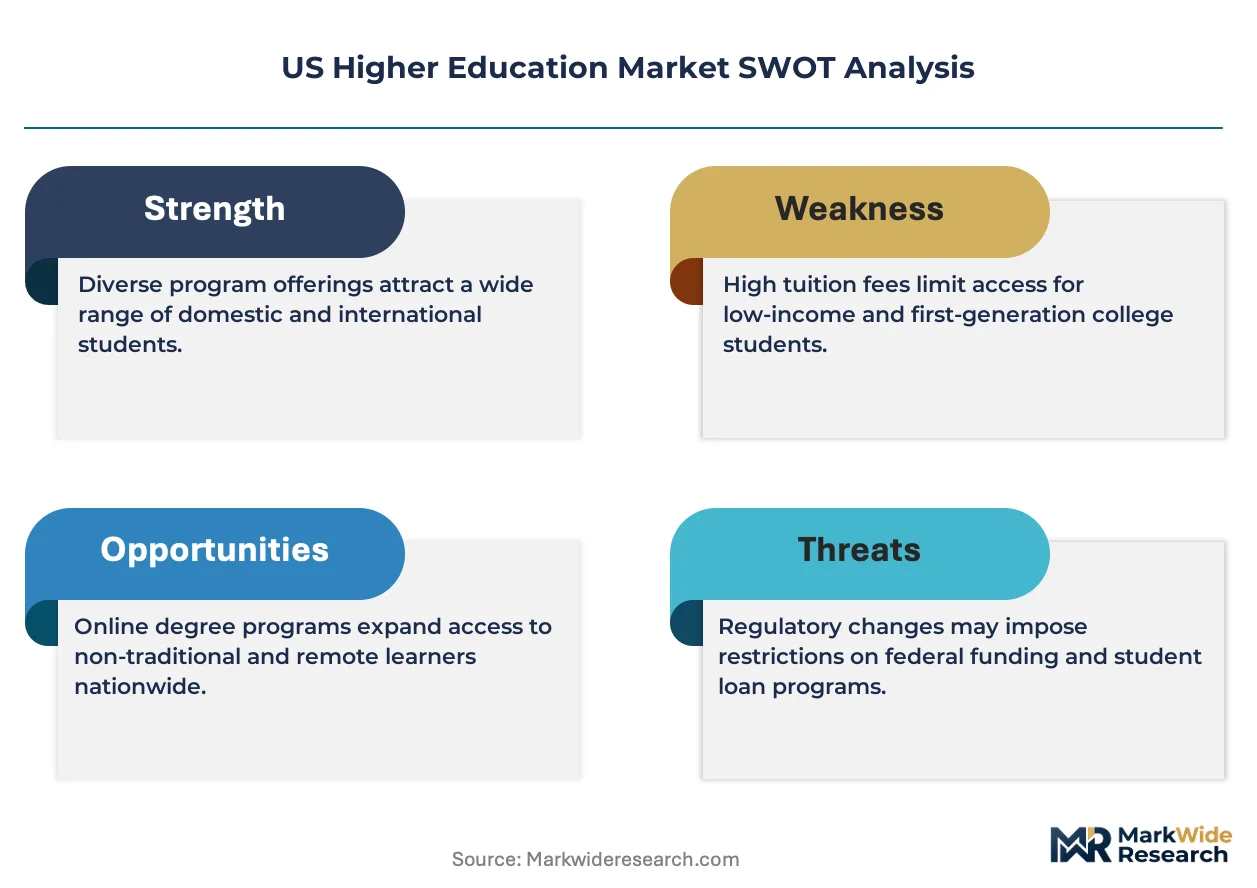
Title IV federal student aid administered by the Department of Education gates market access for participating institutions, while regional accreditors such as SACSCOC and MSCHE enforce baseline academic standards that shape program viability. State authorization reciprocity agreements under NC-SARA determine cross-border online enrollment eligibility, compressing regulatory fragmentation for multi-state operators. Stakeholders must monitor pending gainful-employment rule revisions and state-level performance-based funding shifts that will recalibrate institutional risk exposure and program portfolio priorities.
Market Dynamics
Online program management platforms are compressing the traditional residential delivery model by decoupling credential access from physical campus infrastructure, forcing legacy institutions to restructure cost bases around asynchronous delivery capabilities.
Growth Catalysts
- NC-SARA Reciprocity:State authorization reciprocity agreements eliminate regulatory friction for multi-state online enrollment, expanding addressable markets for regional public universities beyond their traditional geographic footprints.
- Healthcare Workforce Pipelines:Hospital systems and health networks sponsor degree completion for clinical staff through employer-funded tuition channels, concentrating demand in nursing and allied health credentials.
- Stackable Credentials:Micro-certificate and professional certificate pathways feed into full degree programs, reducing enrollment friction for working adults with interrupted academic histories.
Market Restraints
- Title IV Administrative Burden:Federal student aid compliance requirements impose fixed cost structures that disadvantage smaller institutions lacking dedicated financial aid infrastructure.
- State Funding Compression:Public university operating subsidies from state legislatures have not kept pace with enrollment growth, forcing tuition-dependent revenue models that price out lower-income demographics.
- Accreditation Timelines:Regional accreditor review cycles for new program approvals extend eighteen to thirty-six months, constraining institutional responsiveness to labor market skill shifts.
Strategic Opportunities
- Rural Broadband Expansion:Federal infrastructure investment in high-speed internet access unlocks previously unserved adult learner populations in Appalachian and Great Plains regions.
- Corporate Learning Integration:Direct contracting between employers and institutions for customized cohort-based degrees bypasses traditional admissions funnel inefficiencies.
- Competency-Based Education:Direct assessment models that award credit for demonstrated mastery rather than seat time compress degree completion timelines and improve retention metrics.
Industry Challenges
- Instructional Design Talent Scarcity:Universities face acute shortages of learning experience designers capable of translating residential pedagogy into effective asynchronous formats.
- Legacy Student Information Systems:Decades-old administrative platforms require expensive integration work to support flexible term structures and subscription-based tuition models.
- Gainful Employment Compliance:Pending Department of Education rules on debt-to-earnings ratios threaten program viability in low-wage credential fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Higher Education Market |
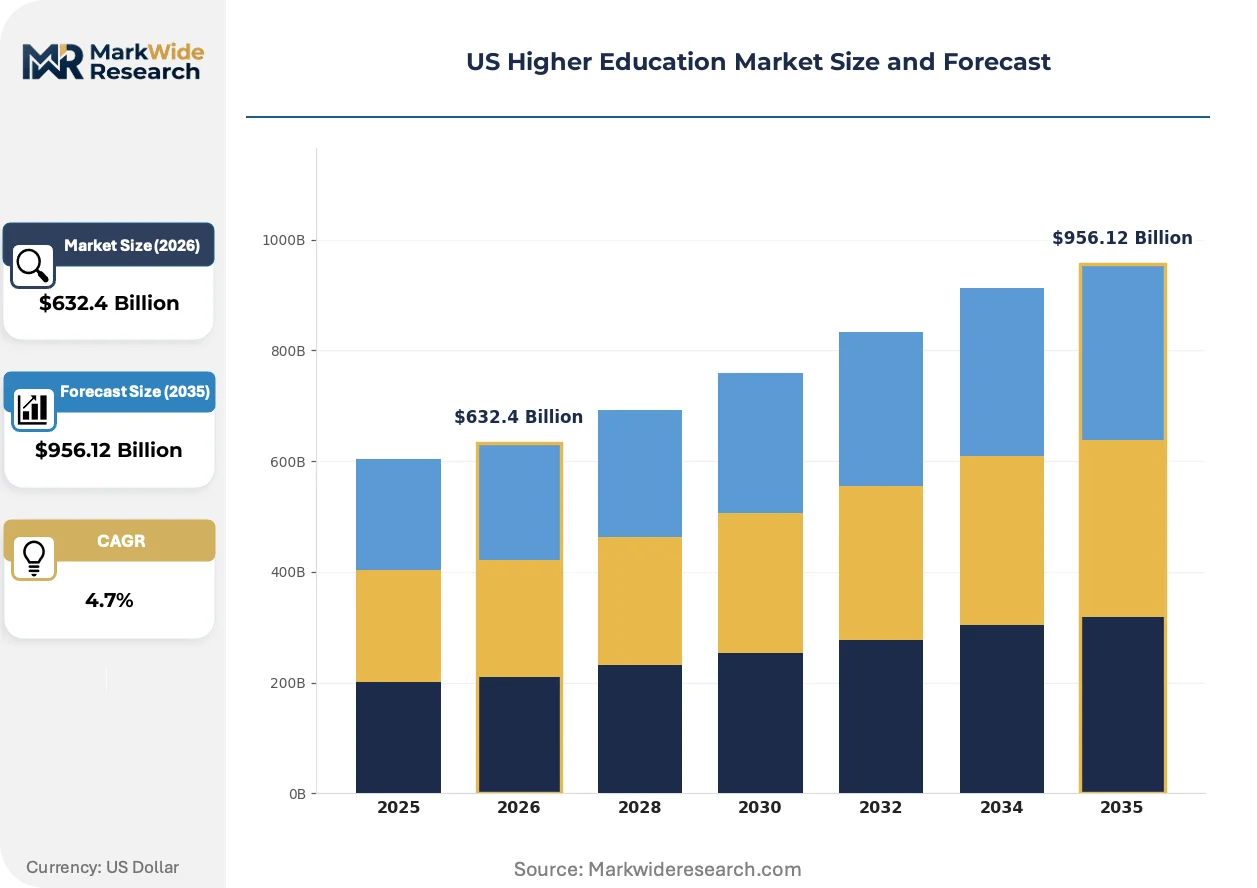
| Market Size in 2026 | $632.4 Billion |
| Market Size in 2035 | $956.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Institution Type: Public Universities, Private Colleges, Community Colleges, Online Institutions Program Level: Associate Degree, Bachelor's Degree, Master's Degree, Doctoral Degree Delivery Mode: In-Person, Hybrid, Fully Online, Blended Learning Funding Source: Federal Grants, State Funding, Tuition Fees, Private Donations |
| Companies Covered | Massachusetts Institute of Technology (MIT), Stanford University, Harvard University, California Institute of Technology (Caltech), University of Chicago, Princeton University, Columbia University, University of Pennsylvania, Yale University, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Higher Education Market Strategic Shifts
Artificial intelligence tools are penetrating instructional workflows at scale, compressing production timelines for course content while raising fundamental questions about assessment integrity and faculty labor models.
Generative AI tutoring assistants are collapsing the cost structure for personalized academic support by automating routine student queries and draft feedback loops. Community colleges and broad-access institutions deploy these tools most aggressively to manage high enrollment-to-advisor ratios. The technology is collapsing the traditional assumption that individualized attention requires proportional human staffing investment.
The Department of Education's pending gainful employment rule revisions will impose debt-to-earnings thresholds on graduate certificate and for-profit degree programs. Institutions must now model program-level economic outcomes before launch approval. Graduate schools in education and social services face the steepest compliance exposure due to historically modest graduate salary trajectories.
Working adult learners increasingly demand subscription-based tuition models that allow pause-and-resume flexibility rather than rigid semester calendars. Employers negotiate direct-bill arrangements that bypass traditional financial aid workflows. Texas and Florida public university systems show the most advanced experimentation with these alternative revenue structures.
US Higher Education Market Segmentation
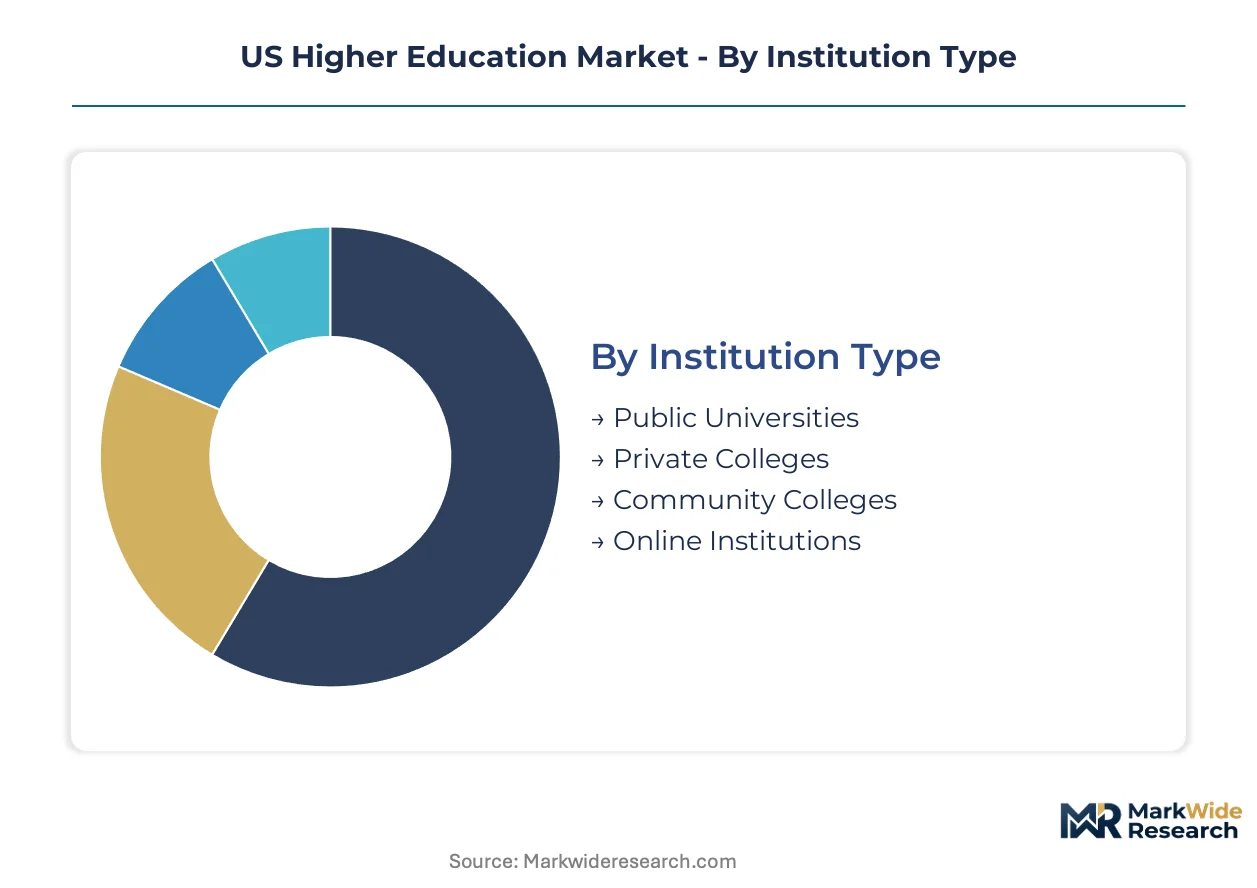
Institutional form, credential level, and delivery modality create distinct economic architectures within US higher education. Each segment carries unique regulatory exposure, cost structures, and workforce alignment characteristics that reshape competitive positioning.
Institution Type:
Mature public systems anchor enrollment volume while emerging online platforms capture structural growth.
- Public Universities:State-subsidized flagships and regional comprehensives absorb the majority of undergraduate enrollment. Texas and Florida systems expand online degree completion to capture working adult demand beyond traditional residential capacity.
- Private Colleges:Endowment-dependent liberal arts institutions face acute tuition discounting pressure as demographic headwinds compress the traditional college-age cohort. Selective research universities leverage proprietary MOOC infrastructure to extend market reach.
- Community Colleges:Open-access two-year institutions serve as the primary on-ramp for first-generation and low-income students. Stackable credential pathways feed into four-year transfer pipelines.
- Online Institutions:Asynchronous delivery platforms eliminate geographic constraints on enrollment. NC-SARA reciprocity agreements compress regulatory fragmentation for multi-state operators.
Public universities handle the majority of throughput; online institutions are the fastest mover on share.
Program Level:
Cost tier stratification concentrates margin pools at the graduate level while volume concentrates in undergraduate credentials.
- Associate Degree:Two-year occupational and transfer-focused curricula dominate community college portfolios. Healthcare workforce pipelines in nursing and allied health absorb outsized completion volume.
- Bachelor's Degree:Four-year undergraduate programming remains the dominant credential for labor market entry. Employer tuition reimbursement channels increasingly favor degree completion over new enrollment.
- Master's Degree:Post-baccalaureate programming commands premium pricing through specialized professional curricula. Texas and Florida public systems absorb concentrated demand in business, education, and healthcare administration.
- Doctoral Degree:Research-intensive terminal credentials sustain institutional research generation functions. STEM and health sciences fields capture the majority of sponsored research funding.
Bachelor's degrees handle the majority of throughput; master's programming is climbing the fastest on enrollment share.
Delivery Mode:
Application context determines modality selection, with workforce-aligned programming driving asynchronous adoption.
- In-Person:Residential delivery sustains traditional campus-based student life and research infrastructure. Selective institutions defend premium positioning through physical amenity differentiation.
- Hybrid:Mixed-modality scheduling accommodates working adults with intermittent campus requirements. Weekend and evening intensive formats concentrate in professional graduate programming.
- Fully Online:Asynchronous platforms decouple credential access from geographic proximity. Title IV federal aid eligibility gates market access for participating institutions.
- Blended Learning:Integrated synchronous and asynchronous components optimize flexibility against engagement requirements. Competency-based direct assessment models compress completion timelines.
In-person delivery handles the majority of throughput; fully online programming is gaining share fastest.
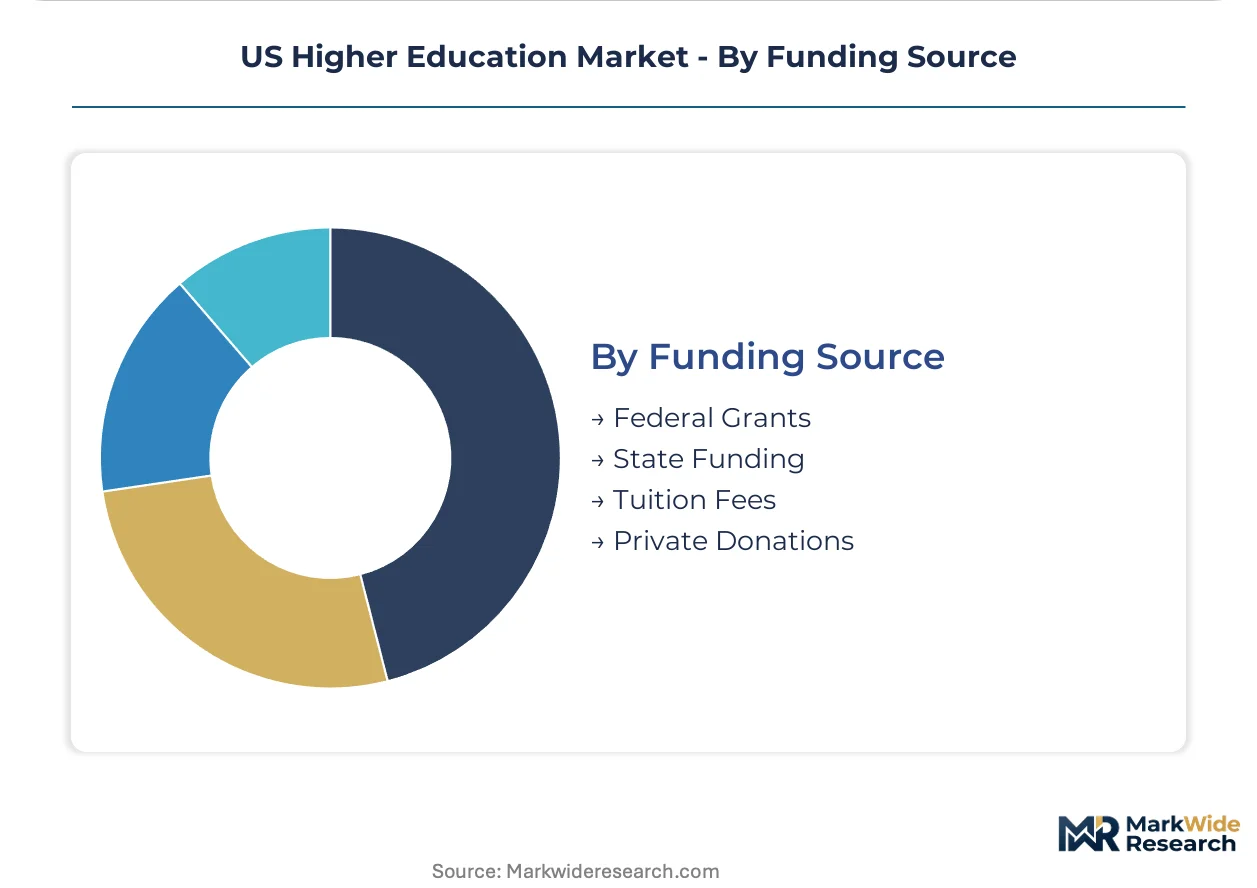
Funding Source:
Margin structure varies sharply across revenue archetypes, with unrestricted private support enabling strategic flexibility unavailable to tuition-dependent models.
- Federal Grants:Pell Grants and Title IV aid flows determine access for lower-income demographics. Gainful employment rule revisions threaten program viability in low-wage credential fields.
- State Funding:Legislative appropriations have not kept pace with enrollment growth, forcing tuition-dependent revenue models. Performance-based funding shifts recalibrate institutional priorities toward completion metrics.
- Tuition Fees:Student-paid revenue dominates private college operating models and supplements public university state support. Subscription-based tuition experiments in Texas and Florida test pause-and-resume flexibility.
- Private Donations:Endowment returns and annual giving sustain selective liberal arts colleges and research flagships. Restricted gift terms often limit deployment flexibility despite dollar magnitude.
Tuition fees handle the majority of throughput; federal grant flows are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California command premium tuition pricing power through flagship research infrastructure, while Appalachian and Great Plains states struggle with state funding compression and rural broadband gaps that limit online program expansion.
Texas
The Texas public university system absorbs concentrated demand for master's degrees in business administration and healthcare management through employer-sponsored tuition channels. State authorization reciprocity under NC-SARA enables flagship institutions to enroll working adults across state lines without regulatory friction. The Austin-San Antonio corridor anchors the state's online program management expansion, with system-wide enrollment growth concentrated in asynchronous professional degree formats.
California
California's community college network serves as the primary on-ramp for first-generation students transferring into four-year public universities. The state's Master Plan for Higher Education restricts doctoral-granting authority to specific segments, creating tiered credential access. The Bay Area and Los Angeles metro regions concentrate private research university endowment capacity that sustains MOOC platform infrastructure and stackable certificate development.
Florida
Florida's performance-based funding model recalibrates institutional priorities toward completion metrics rather than enrollment volume alone. State authorization reciprocity agreements compress regulatory barriers for multi-campus online operations. The Tampa-Orlando corridor hosts the densest concentration of healthcare workforce pipeline partnerships, with hospital systems sponsoring nursing and allied health degree completion.
New York
New York's Excelsior Scholarship program shapes public university enrollment patterns through last-dollar free tuition for qualifying residents. The state's private research universities leverage New York City corporate proximity for customized executive education cohorts. The Hudson Valley and Long Island regions concentrate community college transfer pathways feeding into SUNY four-year institutions.
Illinois
Illinois public universities face acute state funding compression that forces tuition-dependent revenue models pricing out lower-income Chicago metro demographics. The state's participation in NC-SARA enables regional comprehensives to compete for working adult learners across Midwestern markets. The Chicago-land corridor anchors corporate learning integration partnerships, with employers negotiating direct-bill arrangements for customized degree cohorts.
US Higher Education Market Competitive Environment
Elite private research universities and large-scale public systems split the market along prestige-versus-access fault lines. The competitive structure concentrates margin pools at the graduate level while undergraduate enrollment fragments across thousands of accredited providers. Three strategic archetypes dominate: endowment-sustained selective privates, state-subsidized public flagships, and online-native platforms. M&A activity concentrates in online program management acquisitions, while strategic partnerships between employers and institutions bypass traditional admissions infrastructure.
Within the selective private tier, Harvard University, Stanford University, and Yale University anchor distinct competitive positions. Harvard leverages its extension school infrastructure to sustain enrollment scale beyond residential capacity. Stanford anchors market presence through proprietary MOOC platforms feeding stackable degree pathways. Yale competes through curated professional certificate streams bridging toward full graduate credentials. Each exemplifies how elite endowment capacity enables digital infrastructure investment unavailable to tuition-dependent competitors.
| Leading Market Players |
|---|
| Massachusetts Institute of Technology (MIT) |
| Stanford University |
| Harvard University |
| California Institute of Technology (Caltech) |
| University of Chicago |
| Princeton University |
| Columbia University |
| University of Pennsylvania |
| Yale University |
| Others |
Value Chain & Pricing Dynamics
The Austin-San Antonio corridor anchors the nation's highest-margin online program management capacity, with Texas public university system expansion feeding premium pricing power for asynchronous master's degrees in business and healthcare administration. State authorization reciprocity under NC-SARA enables cross-border enrollment capture without regulatory friction, compressing delivery costs while sustaining tuition premiums.
Pricing Analysis
The customization-premium spread separates employer-sponsored cohort pricing from standard per-credit tuition, with corporate direct-bill arrangements commanding fifteen to thirty percent discounts against published rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery modality and support intensity, with blended learning formats capturing mid-tier positioning. Pricing pressure stems from state funding compression forcing public institutions toward tuition-dependent models that price out lower-income demographics. Community college transfer pathways show highest price sensitivity, while executive graduate programming at selective privates demonstrates lowest elasticity.
Supply Chain Analysis
Online program management contract manufacturing concentrates with Pearson, Wiley Education Services, and 2U holding dominant third-party platform capacity for course development and student acquisition. Instructional design talent draws from India and the Philippines for offshore content production, while learning experience platform software rests on cloud infrastructure anchored in US data centers. Single-source vulnerability sits with legacy student information systems requiring expensive integration work for flexible term structures. Distribution runs through direct institutional channels, employer partnership networks, and NC-SARA-enabled multi-state enrollment portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US higher education market represents early-cycle expansion in workforce-aligned credentialing, with employer-sponsored tuition reimbursement channels accelerating penetration among working adult learners previously excluded from residential delivery.
For Market Incumbents: Harden competitive position by acquiring instructional design talent pools capable of translating residential pedagogy into effective asynchronous formats, and deepen backward integration into proprietary learning experience platforms to reduce third-party OPM dependency. Title IV administrative burden and pending gainful employment rule revisions threaten program viability for tuition-dependent institutions lacking diversified revenue streams. For New Entrants and Emerging Players: Rural broadband expansion zones in Appalachian and Great Plains regions represent the most penetrable entry point for fully online degree completion targeting previously unserved adult learner populations. Corporate learning integration partnerships with hospital systems and regional employers offer direct-bill revenue channels that bypass traditional financial aid infrastructure and admissions funnel inefficiencies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors online-native platforms with established NC-SARA multi-state authorization and employer partnership networks over legacy residential institutions with fixed cost structures. Long-term viability across the five-to-ten year window hinges on competency-based direct assessment capabilities and AI-augmented instructional delivery. Monitor quarterly Title IV program participation rate disclosures and state-level performance-based funding metric shifts as inflection indicators for institutional risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Competency-Based Education Expansion | Direct assessment models compress degree timelines and improve retention metrics for working adults. |
| Corporate Learning Integration Partnership | Direct employer contracting bypasses traditional admissions inefficiencies and secures tuition revenue. |
| AI-Augmented Instructional Platform | Generative tutoring assistants collapse personalized support costs at broad-access institutions. |
| Rural Broadband Market Entry | Federal infrastructure investment unlocks previously unserved adult learner populations in underserved regions. |
| NC-SARA Multi-State Authorization | Reciprocity agreements eliminate regulatory friction for cross-border online enrollment expansion. |
Study Parameters
Desk research of IPEDS enrollment databases, NC-SARA participation records, and Title IV program participation agreements preceded structured interviews with chief online learning officers, enrollment management executives, and employer tuition benefits administrators. Secondary validation drew from Department of Education gainful employment disclosures, state higher education agency funding reports, and regional accreditor program approval records. Bottom-up institution-level enrollment modeling triangulated against top-down market sizing from federal student aid flow analysis.
Assumptions held Title IV eligibility criteria and NC-SARA reciprocity framework stable across the projection horizon, while varying state appropriation trajectories and employer reimbursement policy shifts. Segmentation modeling captured institution type, program level, delivery modality, and geographic market cluster dimensions. CAGRs derived from enrollment trend extrapolation calibrated against demographic projection inputs and labor market demand indicators for healthcare and business administration credentials.
Macroeconomic conditions sit as an overlay; deviation in unemployment rates, federal student aid appropriations, or state budget cycles would shift the trajectory for tuition-dependent revenue models. Forecasts reflect assumptions regarding sustained employer sponsorship growth and stable regulatory frameworks for online program eligibility. Quarterly review of Title IV cohort default rate releases and state authorization compact participation data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Edtech and Smart Classroom Market
Education & Training
School Information Management System Market
Education & Training
Educational Consulting and Training Market
Education & Training
Global Exam Management Software Market
Education & Training
Online Tutoring Market
Education & Training
Language Learning Games Market
Education & Training
GCC Massive Open Online Course (MOOC) Market
Education & Training
Global Language Service Market
Education & Training
Canada Executive Education Program Market
Education & Training
Canada Outplacement Services Market
Education & Training
Europe Corporate Training Market
Education & Training
Global Dyslexia Treatment Market
Education & Training
Blockchain in Edutech Market
Education & Training
US Child Care Market
Education & Training
US Life Coaching Market
Education & Training
Vocational English Course Counselling Solution Market