
 Global Language Service Market | 2026-2036
Global Language Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Language Service Market Outlook
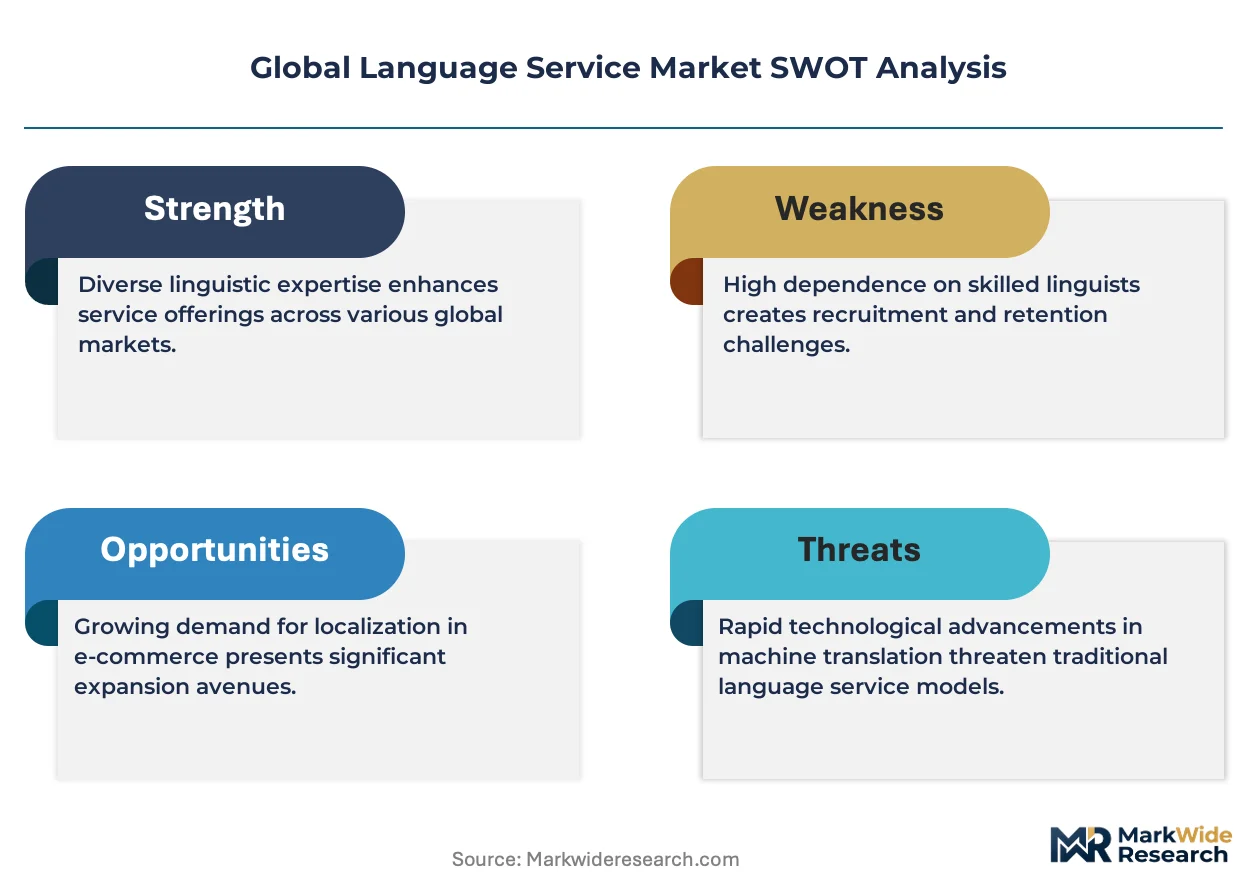
Modular bundling of machine translation with human post-editing is hardening as the default procurement format for enterprise buyers. TransPerfect leverages its global interpreter network to sustain premium positioning in regulated sectors. RWS Holdings anchors its competitive stance through specialized life-sciences localization capabilities. Lionbridge Technologies competes on technology leadership in AI-powered content transformation workflows.
Language services encompass the professional conversion, adaptation, and management of content across linguistic, cultural, and technical boundaries, typically delivered through cloud-based platforms with API integration and quality-assurance protocols such as ISO 17100 certification. These services enable regulatory compliance, market access, and user engagement for organizations operating across multilingual environments. Localization commands the largest margin pool as pharmaceutical and software clients demand culturally adapted products rather than literal conversion. Machine translation paired with human review represents the fastest-expanding technology configuration as enterprises balance speed with accuracy requirements. Interpretation services remain mature in offline delivery mode while hybrid formats gain share in healthcare and legal settings.
The EU AI Act imposes transparency obligations on automated translation systems deployed in Europe, reshaping product development roadmaps for vendors serving European Commission and EMA-regulated content. FDA submission requirements for multilingual clinical trial documentation in the United States create persistent demand for certified translation providers. China's SAMR and NMPA enforce stringent labeling and documentation standards for imported pharmaceuticals and medical devices, channeling investment into specialized Mandarin localization capacity. Stakeholders must monitor divergent regulatory timelines for AI governance across Brussels, Washington, and Beijing to align compliance investments with revenue exposure.
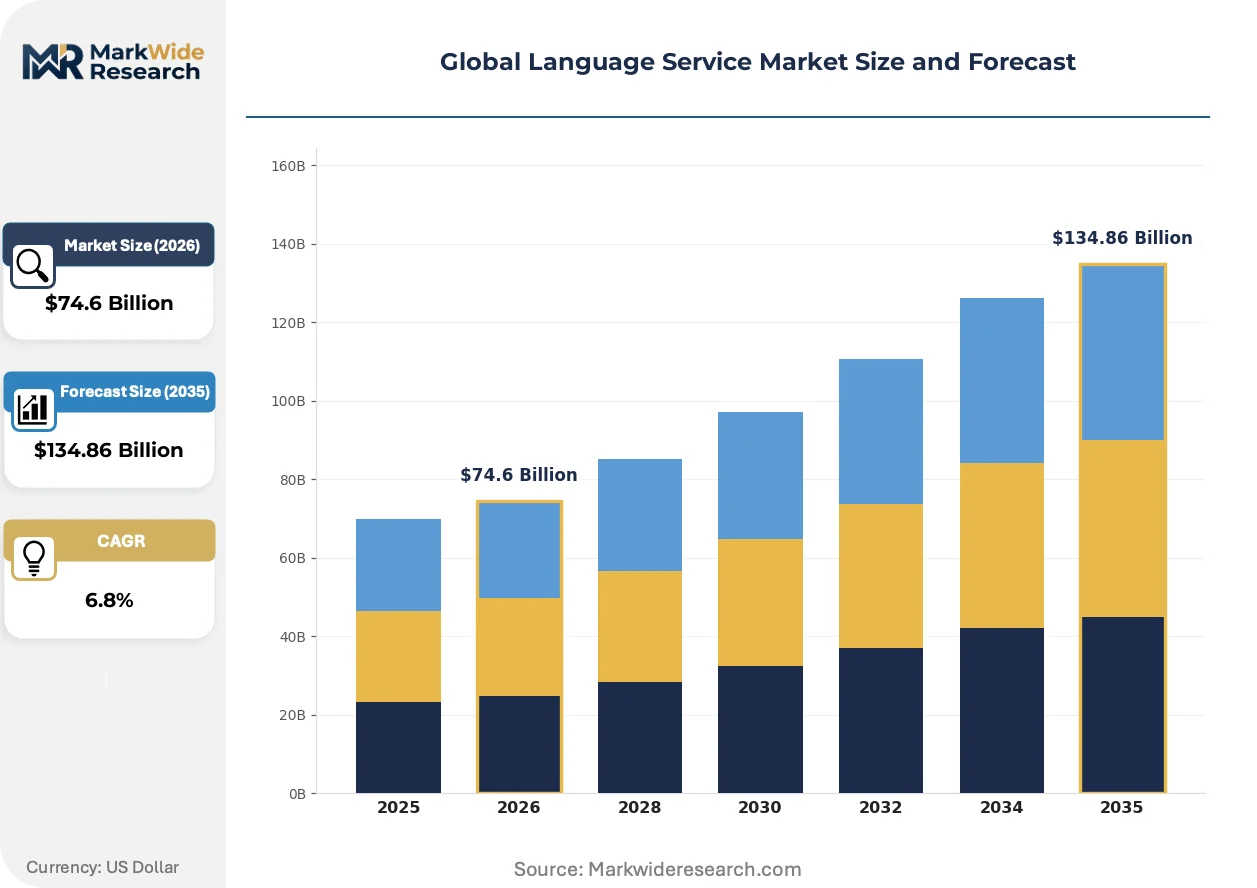
Market Dynamics
Machine translation paired with human post-editing is compressing project timelines and redrawing competitive boundaries across enterprise localization procurement. This hybrid delivery model is forcing traditional pure-play human translation providers to restructure pricing and capacity planning or cede volume to technology-enabled competitors.
Growth Catalysts
- EU AI Act transparency mandates:Automated translation systems deployed in Europe now require algorithmic explainability, driving healthcare providers and public-sector buyers toward certified vendors with documented quality protocols.
- Cloud-based localization platforms:API-first delivery architectures enable pharmaceutical and software clients to embed translation workflows directly into content management systems, reducing handoff friction.
- FDA multilingual submission requirements:Clinical trial documentation for drug approval in the United States must meet certified translation standards, sustaining demand for specialized life-sciences linguists.
Market Restraints
- Neural MT training data scarcity:Low-resource languages lack sufficient parallel corpora for effective neural machine translation, limiting automation potential in African and Southeast Asian markets.
- ISO 17100 certification bottlenecks:Auditor capacity constraints extend certification timelines for emerging providers, concentrating qualified supply among incumbent networks.
- Freelance translator rate volatility:Specialized medical and legal linguists command premium pricing that scales non-linearly with project complexity, compressing margins on fixed-price enterprise contracts.
Strategic Opportunities
- India's pharmaceutical export documentation:CDSCO-aligned labeling requirements for generic drug exports create demand for regulatory-grade localization capacity serving both domestic manufacturers and multinational sponsors.
- Real-time video interpretation:Remote patient-provider communication in telehealth settings is opening subscription-based revenue models distinct from per-minute billing.
- Convergence of MT and synthetic media:Automated dubbing pipelines combining speech synthesis with translated scripts are penetrating streaming content localization, displacing traditional studio recording for secondary markets.
Industry Challenges
- Post-editor skill calibration:Human reviewers must master domain-specific error taxonomy and MT error pattern recognition, creating training pipeline backlogs that delay workforce scaling.
- Legacy TMS integration friction:Enterprise content repositories built on decade-old translation management systems resist API-based connectivity, forcing costly middleware development or manual workflow bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Language Service Market |
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $134.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Translation, Interpretation, Localization, Transcription End User: Corporates, Educational Institutions, Government, Healthcare Providers Technology: Machine Translation, AI-Powered Tools, Cloud-Based Solutions, Human Translation Delivery Mode: Online, Offline, Hybrid, Mobile Applications |
| Companies Covered | TransPerfect, LanguageLine Solutions, RWS Holdings, Lionbridge Technologies, Welocalize, Hogarth Worldwide Limited, Keywords Studios, Semantix, Iyuno, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Language Service Market Strategic Shifts
Generative AI architectures are penetrating core translation workflows, reshaping how linguistic assets are created, validated, and deployed. This technological inflection is compressing the traditional human-in-the-loop model while raising new quality-assurance complexities.
Large language model fine-tuning for domain-specific translation is rewriting how pharmaceutical and legal buyers approach multilingual content production. Enterprise procurement teams in Germany and Switzerland are piloting LLM-first workflows for internal documentation, reserving human review for external-facing materials. This bifurcation is creating tiered service architectures that separate commodity translation from premium certified output.
China's NMPA and SAMR are tightening labeling standards for imported medical devices, mandating Mandarin documentation that exceeds literal translation to include culturally adapted usage instructions. Foreign manufacturers are responding by embedding Shanghai-based localization teams rather than outsourcing to offshore vendors. This regulatory pressure is accelerating investment in captive Mandarin capacity.
Subscription-based interpretation procurement is displacing per-minute billing in healthcare and legal settings. Hospital systems in the United States are consolidating vendor relationships into annual platform contracts with guaranteed interpreter availability. This shift concentrates purchasing power among buyers with sufficient volume to justify fixed-fee structures, pressuring smaller interpretation agencies to consolidate or exit.
Global Language Service Market Segmentation
Language service procurement splits sharply between embedded workflow solutions and standalone project delivery. Enterprise buyers select segments based on regulatory certification requirements, content velocity demands, and integration depth with existing content management infrastructure.
Service Type:
Standalone translation projects operate independently from client systems, while localization services embed directly into product development pipelines.
- Translation:Document-level linguistic conversion delivered through certified workflows meeting ISO 17100 standards. Demand concentrates in FDA-regulated clinical trial documentation for pharmaceutical sponsors in the United States, driven by mandatory certified accuracy for regulatory submission.
- Localization:Cultural and technical adaptation of software, media, and product interfaces for target markets. German healthcare providers are expanding procurement of medical device localization to satisfy EU AI Act transparency mandates for algorithmic documentation.
- Interpretation:Real-time spoken language conversion across in-person, telephonic, and video modalities. Hospital systems in the United States are consolidating vendor relationships into subscription-based contracts.
- Transcription:Audio-to-text conversion with optional translation layering for legal and media workflows. Court systems and broadcasters in India drive demand for vernacular language pairs.
Volume placements concentrate in Translation; the faster expansion belongs to Localization.
End User:
Cost-tier stratification separates enterprise-scale buyers with dedicated localization budgets from project-based purchasers.
- Corporates:Multinational technology and pharmaceutical firms with continuous localization needs. These buyers embed API-first translation workflows directly into content management systems, reducing handoff friction across software release cycles.
- Healthcare Providers:Hospital systems and telehealth platforms requiring certified interpretation and documentation translation. German providers are accelerating procurement to align with EU AI Act compliance timelines for automated translation systems.
- Government:Public-sector agencies procuring multilingual services for citizen-facing communications and international treaty documentation. Procurement emphasizes certified vendor status and documented quality protocols.
- Educational Institutions:Universities and research organizations translating academic materials and international student communications. Budget constraints favor machine translation with selective human review.
Revenue concentration sits with Corporates; Healthcare Providers are gaining share fastest.
Technology:
Maturity-stage differentiation separates established human workflows from emerging AI-augmented configurations.
- Machine Translation:Neural and statistical engines processing high-volume content with minimal human intervention. China's SAMR and NMPA labeling requirements are driving investment in Mandarin-specific engine training for medical device documentation.
- AI-Powered Tools:Generative AI and large language model fine-tuning for domain-specific translation. Enterprise procurement teams in Switzerland are piloting LLM-first workflows for internal documentation.
- Human Translation:Professional linguist delivery with full accountability chains for certified outputs. Premium pricing scales non-linearly with specialized medical and legal domain expertise.
- Cloud-Based Solutions:API-first delivery architectures enabling direct embedding into client content pipelines. Pharmaceutical and software buyers in the United States prioritize this modality for continuous deployment workflows.
Deployment scale favors Cloud-Based Solutions; AI-Powered Tools are climbing the fastest.
Delivery Mode:
Customer-type preferences split between on-demand mobile access and structured enterprise platform integration.
- Online:Web-based platforms for document submission, project tracking, and delivery. Corporate buyers in India leverage these channels for pharmaceutical export documentation aligned with CDSCO requirements.
- Hybrid:Blended human and automated workflows with flexible touchpoint selection. Healthcare and legal settings are expanding hybrid interpretation formats combining scheduled video sessions with on-demand audio backup.
- Offline:Traditional in-person interpretation and physical document handling. Mature in legal deposition and diplomatic settings where presence requirements override convenience.
- Mobile Applications:Smartphone-based interpretation and translation access for field-deployed workers and travelers. Telehealth providers are exploring subscription models distinct from per-minute billing structures.
Contract value aggregates in Online delivery; Hybrid formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Ireland and Singapore accelerate vendor concentration for pharmaceutical and technology localization. Tax-advantaged jurisdictions attract captive shared-service centers from multinational buyers seeking regulatory proximity without full market entry costs.
United States
FDA submission requirements for multilingual clinical trial documentation sustain demand for certified life-sciences linguists. Healthcare systems consolidate interpretation procurement into annual platform contracts with guaranteed availability. Boston and San Francisco clusters host specialized regulatory translation capacity serving pharmaceutical sponsors.
Germany
Healthcare providers accelerate procurement to satisfy EU AI Act transparency mandates for algorithmic documentation. The country's national pharmaceutical regulator enforces strict multilingual labeling standards for imported medical devices. Berlin and Munich hubs concentrate post-editing capacity for machine-translation workflows serving European Commission-regulated content.
China
NMPA and SAMR labeling requirements for imported pharmaceuticals drive investment in Mandarin-specific localization capacity. Foreign manufacturers embed Shanghai-based teams rather than outsourcing to offshore vendors. The Yangtze River Delta cluster attracts captive localization centers from medical device multinationals seeking regulatory proximity.
India
CDSCO-aligned documentation requirements for generic drug exports create demand for regulatory-grade localization serving domestic manufacturers and multinational sponsors. Corporate buyers leverage cloud-based platforms for pharmaceutical export documentation. Hyderabad and Mumbai clusters combine pharmaceutical manufacturing with specialized regulatory translation services.
Switzerland
Enterprise procurement teams pilot LLM-first workflows for internal documentation, reserving human review for external-facing materials. Swissmedic maintains stringent multilingual standards for pharmaceutical marketing authorization. Basel and Zurich clusters anchor life-sciences localization capacity serving both domestic headquarters and global operations.
Global Language Service Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered service architectures. The vendor base spans technology-enabled platforms, human-centric boutique networks, and hybrid configurations blending automation with certified review. Three archetypes dominate: scale-driven interpretation aggregators, domain-specialized life-sciences boutiques, and AI-first workflow platforms. Consolidation through strategic acquisitions and captive technology development represent the primary competitive vectors reshaping market boundaries.
Within the scale-driven interpretation tier, LanguageLine Solutions and TransPerfect occupy positions emphasizing network breadth and regulatory certification depth. RWS Holdings exemplifies the domain-specialized archetype through its concentrated life-sciences capabilities. These three entities anchor competitive positioning across divergent buyer procurement criteria—volume scalability, vertical expertise, and technology integration—without overlapping core value propositions.
| Leading Market Players |
|---|
| TransPerfect |
| LanguageLine Solutions |
| RWS Holdings |
| Lionbridge Technologies |
| Welocalize |
| Hogarth Worldwide Limited |
| Keywords Studios |
| Semantix |
| Iyuno |
| Others |
Value Chain & Pricing Dynamics
Enterprise pharmaceutical sponsors with continuous localization pipelines anchor pricing power through multi-year platform contracts, compressing spot-market rates for project-based buyers. Subscription lock-in among hospital systems and software firms concentrates volume purchasing, forcing boutique providers toward certified premium tiers or exit.
Pricing Analysis
Short lead-time premiums of 40-60% above standard rates apply to FDA submission deadlines and EU AI Act compliance windows. Three-tier pricing structure across certified life-sciences, standard enterprise, and economy machine-translation tiers separates buyers by regulatory risk exposure. Price differentiation hinges on ISO 17100 certification grade and vertical integration of post-editing capacity. Pricing pressure stems from neural MT commoditization of high-volume European language pairs, squeezing margins on non-certified document work. Educational institutions and internal corporate documentation buyers exhibit highest price sensitivity; pharmaceutical sponsors with regulatory submission requirements show lowest.
Supply Chain Analysis
China's NMPA and SAMR domestic-content mandates for medical device labeling are reshaping sourcing toward Shanghai-based captive teams and away from offshore vendors. Linguist supply concentrates in Germany, China, and India, with Berlin and Munich anchoring post-editing networks for EU-regulated content. Raw material dependencies include parallel corpora for neural engine training, specialized medical terminology databases, and API infrastructure from hyperscaler cloud providers. Supply chain risk centers on single-source vulnerability for ISO 17100-certified auditor capacity, extending certification timelines. Distribution runs through API-first platforms embedded directly into pharmaceutical content management systems and hospital procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified linguist scarcity props pricing across life-sciences verticals, creating durable margin pools for incumbents with established auditor relationships and captive training pipelines.
For Market Incumbents: Cement defensible positioning through backward integration into post-editor training academies and ISO 17100 certification infrastructure, locking in auditor relationships before capacity constraints tighten. Acquire niche life-sciences boutiques in Basel and Zurich clusters to capture Swissmedic-mandated documentation flows. Neural MT commoditization threatens non-certified translation tiers; vertical integration into synthetic media dubbing pipelines opens adjacent revenue in streaming localization. For New Entrants and Emerging Players: AI-powered real-time video interpretation platforms offer the most penetrable wedge, targeting subscription-based contracts with telehealth providers in the United States and hybrid court interpretation in India. White-space sits in CDSCO-aligned regulatory documentation for Indian generic drug exporters, where cloud-native platforms displace legacy document workflows. Go-to-market through direct hospital system partnerships, bypassing incumbent GPO relationships. For Investors and Strategic Acquirers: The window for entry favors domain-specialized boutiques with captive Mandarin or German regulatory capacity over scale-driven interpretation aggregators. Target acquisition archetype: ISO 17100-certified life-sciences providers with embedded pharmaceutical sponsor relationships and Shanghai or Berlin-based delivery teams. Watch for inflection in EU AI Act enforcement intensity as signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17100 Certification Infrastructure Investment | Creates auditor capacity moat as certification bottlenecks concentrate qualified supply among incumbents. |
| Captive Mandarin Localization Center Buildout | Satisfies NMPA and SAMR domestic-content mandates for medical device labeling in Shanghai cluster. |
| LLM-First Workflow Platform Launch | Captures Swiss and German enterprise pilot demand for internal documentation automation. |
| Subscription-Based Interpretation Contract Conversion | Locks in hospital system volume and displaces per-minute billing competitors in telehealth. |
| Synthetic Media Dubbing Pipeline Integration | Penetrates streaming content localization for secondary markets, displacing traditional studio recording. |
Study Parameters
Multi-period observation of ISO 17100 certification timelines, neural MT engine deployment rates, and EU AI Act procurement acceleration anchored the trend analysis, supplemented by interviews with localization procurement officers at pharmaceutical sponsors, hospital system vendor management leads, regulatory affairs directors at medical device manufacturers, and cloud platform integration specialists. Secondary validation drew from FDA submission databases, EMA regulatory guidance documents, CDSCO export documentation requirements, and SEC filings of publicly traded language service providers. Bottom-up project pipeline tracking across 15 countries triangulated against top-down market sizing from enterprise IT spending surveys.
Input-output matrices mapped linguist supply pools, certification capacity constraints, and technology adoption curves across the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology configuration, and delivery mode, with additional granularity on regulatory jurisdiction clusters. CAGRs were derived from elasticity-adjusted demand projections and capacity-constrained supply responses. Forecast inputs incorporated EU AI Act implementation timelines, FDA multilingual submission volume trends, and NMPA labeling standard revisions.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement delays, breakthrough advances in unsupervised neural MT eliminating post-editing requirements, and geopolitical disruptions to cross-border data flows for cloud-based platforms. Forecasts reflect assumptions about sustained certification demand and technology adoption continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Language Learning and Training
Bilingual Education for Children Market
Language Learning and Training
English Learning for Children Market
Language Learning and Training
English Learning App Market
Language Learning and Training
Digital English Learning Market
Language Learning and Training
Language Learning Software Market
Language Learning and Training
Vocational English Course Counselling Solution Market
Language Learning and Training
Language Learning Games Market
Language Learning and Training
Global Digital English Language Learning Market
Language Learning and Training
Online Language Learning Market
Language Learning and Training
Cloud Based Language Learning Market