
 Language Learning Games Market | 2026-2036
Language Learning Games Market Size, Share, and Industry Trends Forecast 2026-2036
Language Learning Games Market Outlook
Multilingual workforce shortages across hospitality, healthcare, and logistics is redrawing competitive boundaries for edtech providers. Duolingo leverages its freemium user base to sustain organic acquisition costs below industry averages. Babbel anchors its revenue model on structured subscription tiers aimed at adult professionals. Rosetta Stone competes through institutional licensing relationships with government and enterprise clients.
Language learning games are interactive digital or physical systems that embed vocabulary acquisition, grammar reinforcement, and pronunciation feedback within rule-based play mechanics, typically deploying spaced repetition algorithms and speech recognition scoring to sustain learner engagement. Their primary commercial purpose is to reduce attrition in self-directed language study by replacing rote memorization with variable reward schedules and progress visualization. Mobile apps command the largest installed base among game types, though scenario-based learning modules carry higher per-user monetization rates due to enterprise licensing. Children and teenager segments dominate download volumes, while adult subscriptions generate superior lifetime value through sustained payment persistence.
FDA oversight applies where speech therapy games make clinical claims, while COPPA and GDPR govern data collection from minors across US and European deployments. China's SAMR enforces content licensing for foreign-language instruction platforms, creating compliance cost barriers for non-domestic entrants. Stakeholders must monitor how generative AI integration triggers reclassification under medical device or educational software frameworks in key jurisdictions.
Market Dynamics
Generative AI integration is fragmenting content production pipelines across language learning platforms, forcing incumbents to rebuild adaptive engines around large language models while managing compliance exposure under emerging algorithmic governance frameworks.
Growth Catalysts
- GDPR and EU AI Act:These frameworks are creating competitive moats for compliant European platforms by raising data-handling barriers against non-compliant foreign entrants targeting EU learners.
- Corporate HR departments:Distributed workforce normalization post-pandemic has institutionalized gamified language training as a standard employee benefit category with recurring procurement cycles.
- Spaced repetition algorithms:Neuroscience-backed retention mechanics embedded in mobile-first products are compressing time-to-proficiency metrics that enterprise buyers use for vendor selection.
Market Restraints
- Speech recognition input costs:Cloud-based pronunciation scoring APIs from dominant providers impose per-call fees that scale unfavorably with freemium user bases exceeding tens of millions.
- Content licensing concentration:China's SAMR enforcement creates supply-side bottlenecks where foreign-language instruction platforms face 12-18 month approval timelines for curriculum updates.
- Clinical claim boundaries:FDA jurisdiction over speech therapy applications with medical positioning restricts product expansion paths for developers seeking to address stuttering or aphasia use cases.
Strategic Opportunities
- Scenario-based enterprise modules:Hospitality and logistics verticals with acute multilingual workforce shortages are accepting per-seat premiums for role-specific conversational simulations.
- Japan and South Korea mobile ecosystems:Premium positioning tolerance for English proficiency tools in these markets supports subscription pricing multiples above North American benchmarks.
- COPPA-aligned parental control layers:Enhanced minor data protection features are opening institutional procurement channels with K-12 districts previously blocked by liability concerns.
Industry Challenges
- Adaptive learning engineering talent:Shortage of specialists combining computational linguistics with reinforcement learning expertise is extending product development cycles for next-generation personalization engines.
- Generative AI reclassification risk:Uncertainty over whether LLM-powered tutoring features trigger educational software or medical device frameworks across EU member states is freezing capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Language Learning Games Market |
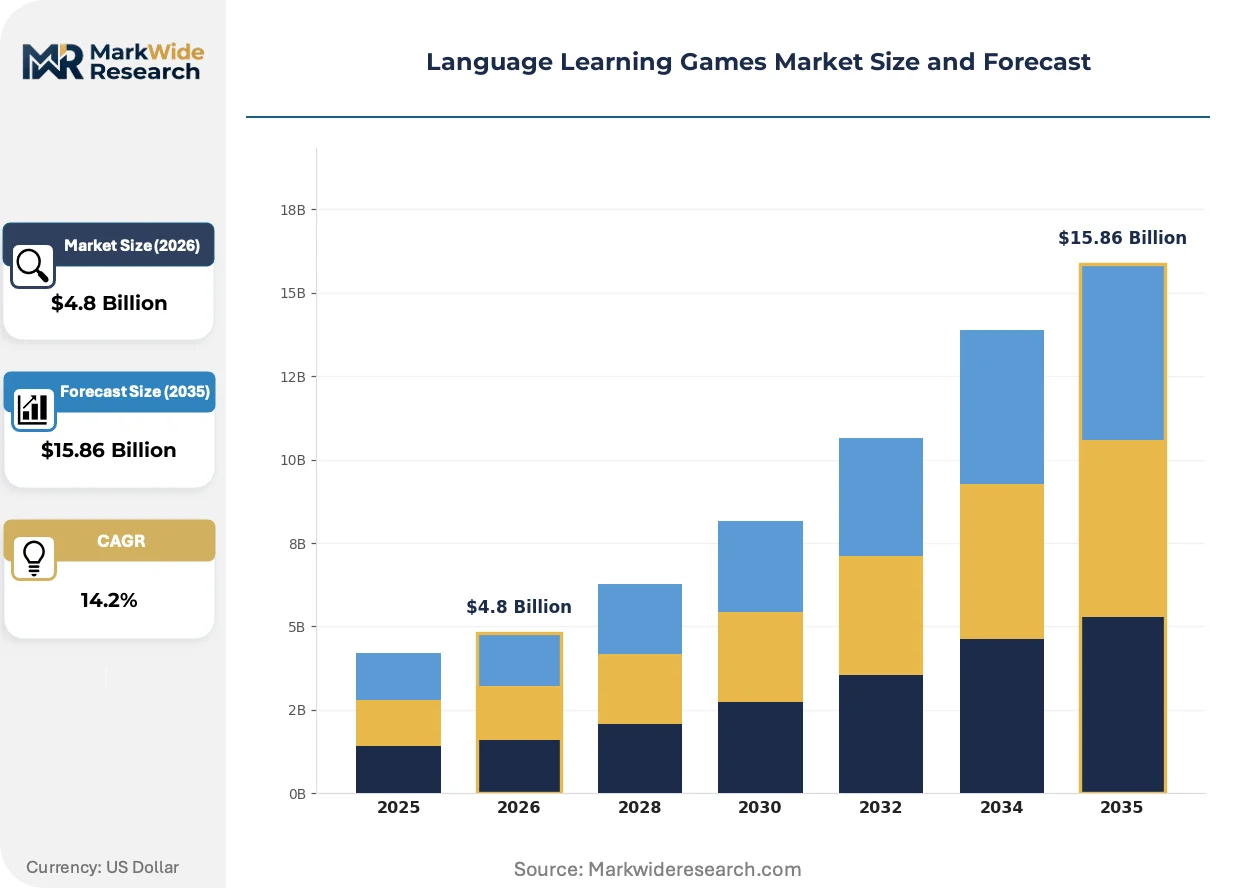
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Board Games, Mobile Apps, Video Games, Card Games Target Age Group: Children, Teenagers, Adults, Seniors Learning Methodology: Gamification, Immersive Learning, Interactive Quizzes, Scenario-Based Learning Language Offered: Spanish, Mandarin, French, German |
| Companies Covered | Duolingo, Rosetta Stone, Babbel, Busuu, Memrise, HelloTalk, GeekSLP, IXL Learning, MindSnacks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Language Learning Games Market Strategic Shifts
Three distinct vectors are reshaping competitive positioning in language learning games: algorithmic personalization depth, regulatory compliance architecture, and enterprise sales motion specialization.
Large language model fine-tuning is fragmenting the adaptive content landscape. Platforms deploying retrieval-augmented generation for contextual dialogue practice are attracting mid-market enterprise buyers seeking role-specific training. The technology is fragmenting vendor tiers between API-dependent challengers and vertically integrated incumbents building proprietary model stacks.
GDPR Article 22 automated decision-making restrictions are forcing algorithmic transparency investments. European platforms must now document how adaptive difficulty engines weight learner performance data, adding compliance engineering headcount. Adult subscription segments targeting EU professionals are absorbing these costs through pricing adjustments while maintaining retention rates.
Enterprise procurement teams are unbundling implementation services from software licenses. Hospitality and healthcare buyers with urgent multilingual staffing gaps are demanding dedicated customer success resources and LMS integration guarantees as table stakes. This pattern is most pronounced in Germany and France, where works council consultation requirements extend vendor selection timelines and favor established institutional relationships.
Language Learning Games Market Segmentation
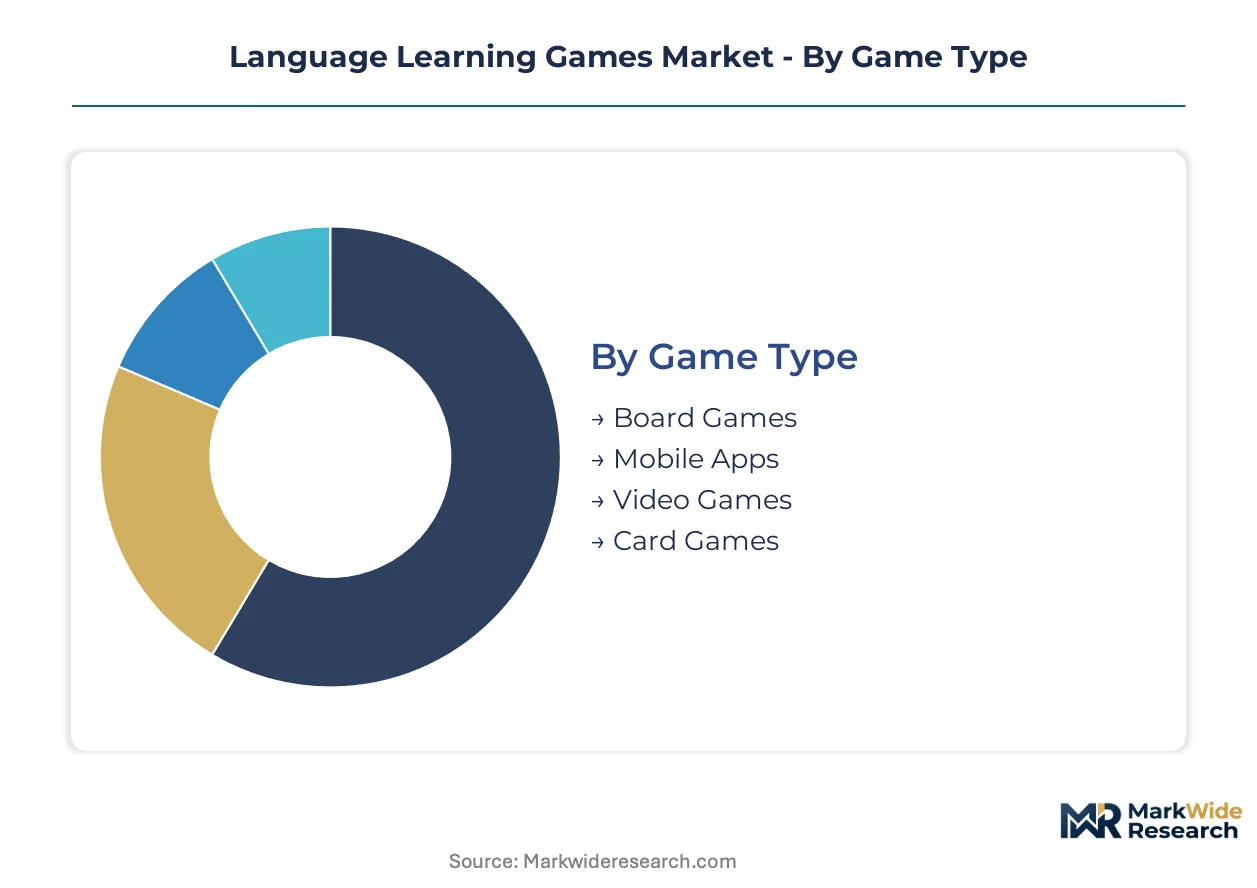
Segmentation in language learning games determines monetization architecture and regulatory exposure. Game type dictates distribution economics while age targeting shapes data governance requirements under COPPA and GDPR frameworks.
Game Type:
Mobile apps face intensifying substitution pressure from generative AI chatbots offering conversational practice without dedicated app infrastructure.
- Mobile Apps:Spaced repetition algorithms and push notification systems sustain daily active user rates. Demand concentrates in Japan and South Korea where commuters absorb micro-lessons during transit. Premium subscription tiers in these markets command pricing multiples above North American benchmarks due to cultural tolerance for English proficiency investment.
- Video Games:Narrative-driven role-playing formats embed vocabulary acquisition within quest mechanics. Enterprise procurement teams in Germany and France increasingly license these modules for hospitality workforce training, demanding LMS integration guarantees and dedicated customer success resources as standard terms.
- Board Games:Physical-digital hybrid products serve K-12 institutional channels with COPPA-aligned data handling.
- Card Games:Compact vocabulary drilling systems target family learning environments with multiplayer mechanics.
Mobile apps retain volume leadership; video games hold the steepest expansion curve in enterprise verticals.
Target Age Group:
Cost tier stratification separates freemium acquisition models from premium subscription persistence across demographic bands.
- Adults:Structured subscription tiers with progress certification drive superior lifetime value through payment persistence. Corporate HR departments in the United States and United Kingdom institutionalize gamified training as standard employee benefits with recurring procurement cycles.
- Children:Download volumes dominate but monetization requires COPPA-compliant parental control layers. Enhanced minor data protection features are opening K-12 district procurement channels previously blocked by liability concerns in California and Texas school systems.
- Teenagers:Social competition mechanics and leaderboard systems sustain engagement through peer network effects.
- Seniors:Simplified interface designs and larger typography accommodate accessibility requirements for cognitive maintenance applications.
Children dominate install base; adults capture the highest revenue per user through sustained subscription retention.
Learning Methodology:
Application focus separates consumer entertainment positioning from enterprise training contracts with measurable proficiency outcomes.
- Scenario-Based Learning:Role-specific conversational simulations address acute multilingual workforce shortages in hospitality and logistics verticals. Buyers accept per-seat premiums for modules tailored to front-desk check-in protocols or warehouse safety instruction.
- Gamification:Variable reward schedules and achievement badges reduce attrition in self-directed study. Mobile-first deployment in South Korea leverages premium positioning tolerance for English proficiency tools.
- Immersive Learning:Virtual reality environments simulate foreign city navigation for tourism industry training.
- Interactive Quizzes:Rapid assessment formats support classroom supplement use cases with teacher dashboard integration.
Gamification retains the broadest user base; scenario-based learning gains share fastest in enterprise procurement.
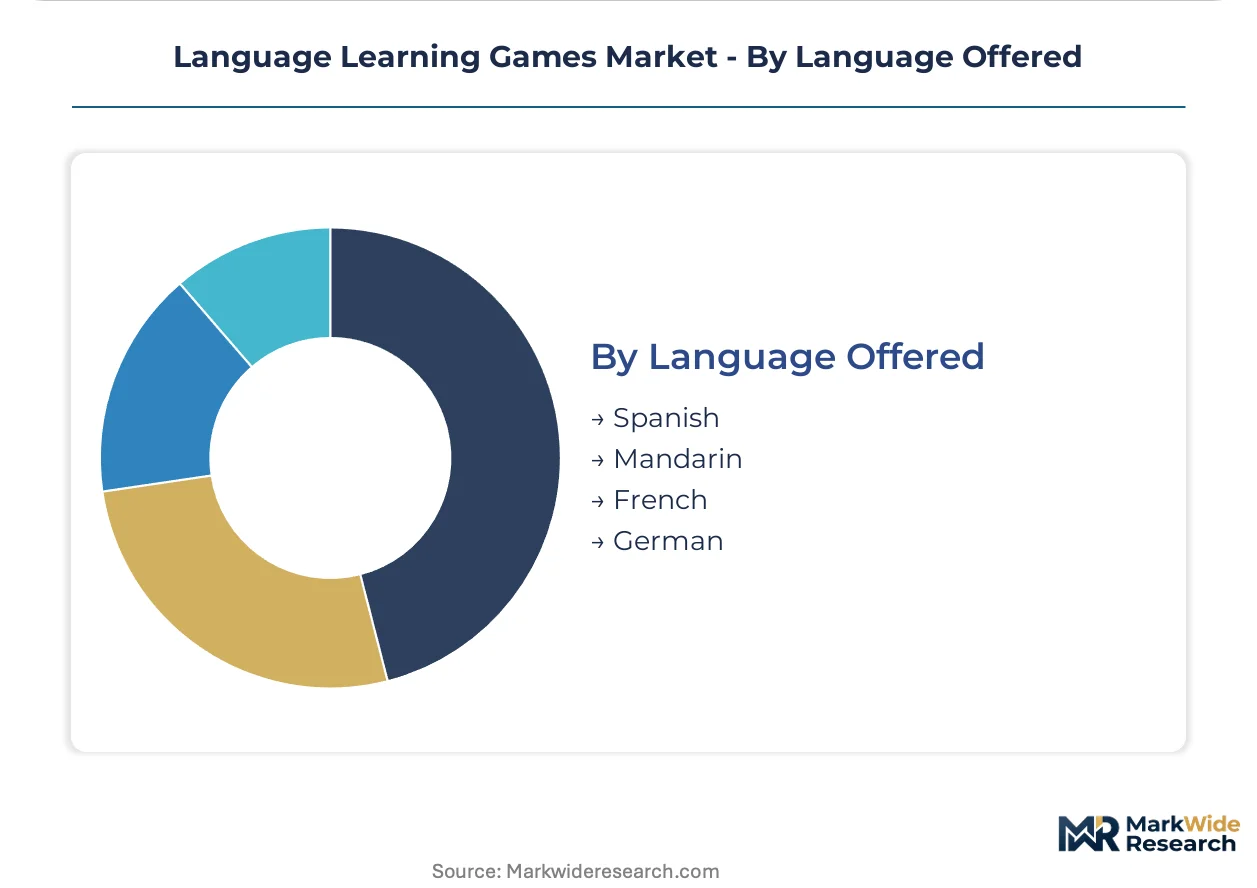
Language Offered:
Geographic demand concentration determines content production priority and regulatory licensing burden.
- Spanish:Dominant demand in the United States from healthcare and logistics employers serving Hispanic patient and customer populations. SAMR content licensing in China creates 12-18 month approval bottlenecks for curriculum updates.
- Mandarin:Strategic priority for European business professionals engaging with Chinese supply chains. GDPR Article 22 compliance requirements force algorithmic transparency investments for adaptive difficulty engines targeting EU learners.
- French:Institutional licensing relationships with Canadian federal government clients sustain recurring revenue streams.
- German:Works council consultation requirements in Germany extend vendor selection timelines and favor established enterprise relationships.
Spanish holds volume leadership in North American markets; Mandarin climbs the fastest in European corporate subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA jurisdiction over speech therapy applications with clinical claims anchors the United States as the primary regulatory reference point for developers navigating medical-device boundaries. GDPR and the EU AI Act in Europe reshape algorithmic governance requirements for adaptive learning platforms targeting professional learners.
United States
Corporate HR departments in technology and healthcare sectors institutionalize gamified language training as standard employee benefits with recurring procurement cycles. COPPA enforcement from the Federal Trade Commission governs data collection from minors across K-12 deployments. California and Texas school districts drive institutional adoption through enhanced parental control layers that address liability concerns previously blocking district-level contracts.
China
SAMR content licensing creates 12-18 month approval bottlenecks for foreign-language curriculum updates, raising compliance cost barriers for non-domestic platform entrants. The national pharmaceutical regulator monitors speech therapy applications making clinical claims about stuttering or aphasia intervention. Shanghai and Beijing technology corridors concentrate domestic platform development for Mandarin instruction targeting European business professionals.
Germany
Works council consultation requirements extend vendor selection timelines for enterprise procurement teams in hospitality and logistics verticals facing acute multilingual workforce shortages. GDPR Article 22 automated decision-making restrictions force algorithmic transparency investments for adaptive difficulty engines. The Eindhoven Region and Frankfurt Rhine-Main cluster concentrate enterprise licensing relationships with institutional buyers demanding dedicated customer success resources.
Japan
Mobile-first English proficiency tools command premium positioning tolerance among commuter demographics absorbing micro-lessons during transit. METI standards influence adaptive learning algorithm certification for corporate training deployments. The Tokyo and Osaka metropolitan areas concentrate demand for scenario-based hospitality training modules addressing front-desk check-in protocols.
South Korea
Premium subscription pricing multiples for English proficiency tools exceed North American benchmarks due to cultural investment tolerance in self-directed study. MFDS oversight applies where speech recognition applications make clinical claims about pronunciation correction. The Seoul Capital Area drives concentrated demand for gamified vocabulary acquisition products leveraging spaced repetition algorithms and push notification systems.
Language Learning Games Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the language learning games ecosystem. The market structure fragments between freemium-scale mobile platforms, structured subscription specialists, and institutional licensing incumbents with established enterprise relationships. Three strategic archetypes dominate: algorithmic personalization engines built on proprietary model stacks, API-dependent challengers leveraging third-party generative AI infrastructure, and vertical specialists targeting regulatory-compliant K-12 channels. Competitive moves concentrate on M&A for adaptive learning engineering talent and strategic partnerships with cloud speech recognition providers to manage per-call API cost scaling.
Within the freemium-scale archetype, Duolingo exemplifies organic user acquisition economics sustained by variable reward schedules and progress visualization mechanics. Among structured subscription specialists, Babbel and Rosetta Stone occupy positions anchored on adult professional segments with superior lifetime value through payment persistence. These three companies represent the dominant competitive vectors: freemium user base monetization, tiered subscription retention, and institutional licensing with government and enterprise clients.
| Leading Market Players |
|---|
| Duolingo |
| Rosetta Stone |
| Babbel |
| Busuu |
| Memrise |
| HelloTalk |
| GeekSLP |
| IXL Learning |
| MindSnacks |
| Others |
Value Chain & Pricing Dynamics
COPPA and GDPR certification regimes gate both supply qualification for K-12 and EU enterprise channels and price differentiation between compliant and non-compliant platform tiers simultaneously. SAMR content licensing in China creates parallel supply barriers that compress margin structures for foreign entrants seeking curriculum updates.
Pricing Analysis
Japan and South Korea sustain subscription pricing multiples above North American benchmarks for mobile-first English proficiency tools. Three-tier pricing structure across premium, standard, and economy levels separates enterprise scenario-based modules from freemium consumer tiers. Cost compression in the freemium tier intensifies because cloud-based speech recognition APIs impose per-call fees that scale unfavorably with user base expansion. Corporate HR procurement teams show lowest price sensitivity; individual consumer segments in emerging markets exhibit highest.
Supply Chain Analysis
Content production lead times extend 12-18 months for SAMR curriculum approvals in China, forcing inventory pre-positioning for platform updates. Adaptive learning engineering talent concentrates in the United States, Germany, and Japan. Cloud infrastructure and speech recognition APIs constitute critical input dependencies. Single-source vulnerability in LLM API providers threatens operational continuity. Distribution runs through mobile app stores and direct enterprise licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI integration constitutes a high-growth disruption inflection, fragmenting content pipelines and forcing adaptive engine rebuilds while regulatory reclassification risk freezes capital allocation.
For Market Incumbents: Compound defensive moats through proprietary model stack development and vertical integration into speech recognition infrastructure. API-dependent architectures face margin erosion from per-call scaling costs. GDPR compliance engineering investments protect EU market access against non-compliant foreign challengers. For New Entrants and Emerging Players: Lead with scenario-based enterprise modules targeting hospitality and logistics verticals with acute multilingual workforce shortages. COPPA-aligned parental control layers represent the most penetrable white-space for K-12 district procurement. Pursue channel partnerships with established LMS integrators to bypass direct enterprise sales cycle barriers. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by elevating compliance engineering capabilities as valuation premiums. Five-to-ten year viability hinges on adaptive personalization depth rather than content library scale. Target acquisition archetype: vertically integrated platforms with proprietary LLM fine-tuning pipelines. Monitor FDA speech therapy reclassification determinations as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary LLM Stack Development | Reduces API dependency costs and enables differentiated adaptive tutoring features. |
| GDPR Article 22 Compliance Architecture | Creates competitive moats in EU enterprise procurement against non-compliant entrants. |
| Scenario-Based Enterprise Module Expansion | Captures per-seat premiums from hospitality and logistics buyers with workforce gaps. |
| COPPA-Aligned K-12 Channel Development | Opens institutional procurement previously blocked by liability concerns in California and Texas. |
| Speech Recognition Infrastructure Integration | Mitigates per-call API cost scaling pressure from dominant cloud providers. |
Study Parameters
Initial hypotheses were tested against primary input from edtech product managers, corporate HR learning officers, K-12 district technology directors, and adaptive learning engineers and refined through secondary validation against SEC filings, App Annie mobile analytics, SAMR content licensing disclosures, and EU regulatory filings. Bottom-up triangulation across user acquisition economics and top-down validation against enterprise licensing contract values anchored market sizing.
Variance decomposition across game type, target age group, learning methodology, and language offered segmentation dimensions structured the analytical framework. CAGRs were derived from modeled user base expansion and monetization rate trajectories across the projection horizon. Speech recognition API cost curves and SAMR approval timeline assumptions constituted industry-specific forecast inputs.
Forecasts assume regulatory continuity in COPPA, GDPR, and SAMR regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Language Learning and Training
English Learning for Children Market
Language Learning and Training
Digital English Learning Market
Language Learning and Training
Cloud Based Language Learning Market
Language Learning and Training
Global Digital English Language Learning Market
Language Learning and Training
Online Language Learning Market
Language Learning and Training
Global Language Service Market
Language Learning and Training
English Learning App Market
Language Learning and Training
Bilingual Education for Children Market
Language Learning and Training
Vocational English Course Counselling Solution Market
Language Learning and Training
Language Learning Software Market