
 Facial Make-Up Market | 2026-2036
Facial Make-Up Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Make-Up Market Foresight
Clean-label mineral pigments are broadening the raw-material palette for foundation and concealer formulations, displacing certain synthetic colorants that face regulatory headwinds. L'Oréal SA leverages its integrated pigment supply chain to control cost quality across liquid and powder lines. The Estée Lauder Companies Inc. anchors its prestige positioning through concentrated R&D spending on skin-compatible formulations. Shiseido Company Limited differentiates via biotechnology-derived ingredients sourced from its Japanese research network.
Facial make-up comprises pigmented cosmetic preparations designed for application to the face to modify skin tone, texture, and color, typically incorporating titanium dioxide, iron oxides, and emollient bases in cream, liquid, powder, or stick vehicles that provide coverage, finish, and wear properties for consumer or professional use. Foundation dominates product-type revenue due to its universal adoption across demographic segments and its role as a daily-use anchor SKU. Liquid formulation leads volume within foundation while powder formats compete on portability and oil-control performance in humid climates. Online retail channels are capturing the fastest growth in distribution, driven by virtual try-on tools and direct-to-consumer subscription models that reduce dependency on department store counter traffic.
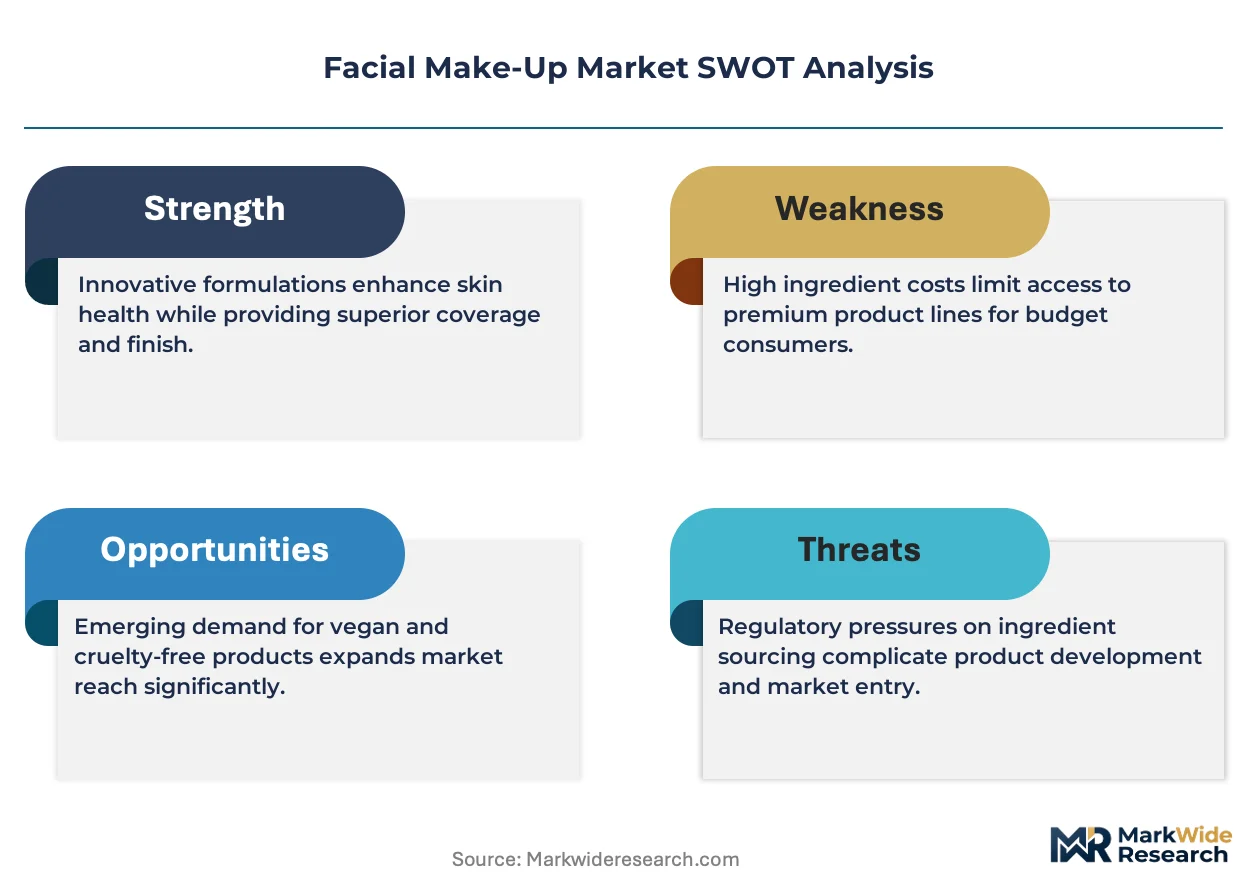
The US FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while the EU REACH framework restricts certain preservatives and nanoparticles in color cosmetics, forcing reformulation cycles that elevate compliance costs for exporters. China's NMPA requires animal-testing alternatives for imported cosmetics, reshaping market access protocols for Western brands entering that regulatory jurisdiction. Stakeholders must monitor divergent ingredient approval timelines across FDA, EMA, and NMPA systems when planning multi-region product portfolios.
Market Dynamics
Clean-label mineral pigments are electrifying formulation strategies across foundation and concealer lines, forcing rapid displacement of legacy synthetic colorants facing regulatory headwinds under EU REACH and FDA oversight.
Growth Catalysts
- EU REACH compliance mandates:Tightening restrictions on nanoparticles and certain preservatives are accelerating reformulation investments, pulling demand toward skin-compatible mineral bases.
- Professional makeup artist segment:This end-use category anchors volume for high-performance liquid foundations, with artists prioritizing coverage durability and shade-matching precision.
- Virtual try-on technology:Augmented reality tools embedded in direct-to-consumer platforms are compressing purchase cycles and reducing return rates for online color cosmetics.
Market Restraints
- Titanium dioxide supply concentration:Pigment sourcing clusters in Chinese and European production zones, exposing formulators to input cost volatility and logistics friction.
- REACH reformulation cycles:Compliance-driven ingredient substitutions extend product development timelines by 12-18 months, elevating R&D overhead for multi-region portfolios.
- Natural pigment performance gaps:Mineral alternatives often deliver inferior color saturation and stability versus synthetic iron oxides, limiting premium positioning.
Strategic Opportunities
- Biotechnology-derived actives:Japanese and Korean research networks are commercializing fermentation-based pigments that merge clean-label positioning with enhanced skin compatibility.
- Subscription replenishment models:Direct-to-consumer channels are capturing recurring revenue through personalized shade-matching algorithms and automated refill shipments.
- China NMPA alternative testing pathways:New animal-testing exemptions for imported cosmetics are reopening market access for Western brands previously blocked by regulatory barriers.
Industry Challenges
- Multi-jurisdiction compliance synchronization:Divergent approval timelines across FDA, EMA, and NMPA systems complicate unified product launches and strain regulatory affairs teams.
- Formulation-scale manufacturing gaps:Small-batch clean-label production lacks the throughput efficiency of legacy synthetic lines, constraining margin expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Make-Up Market |
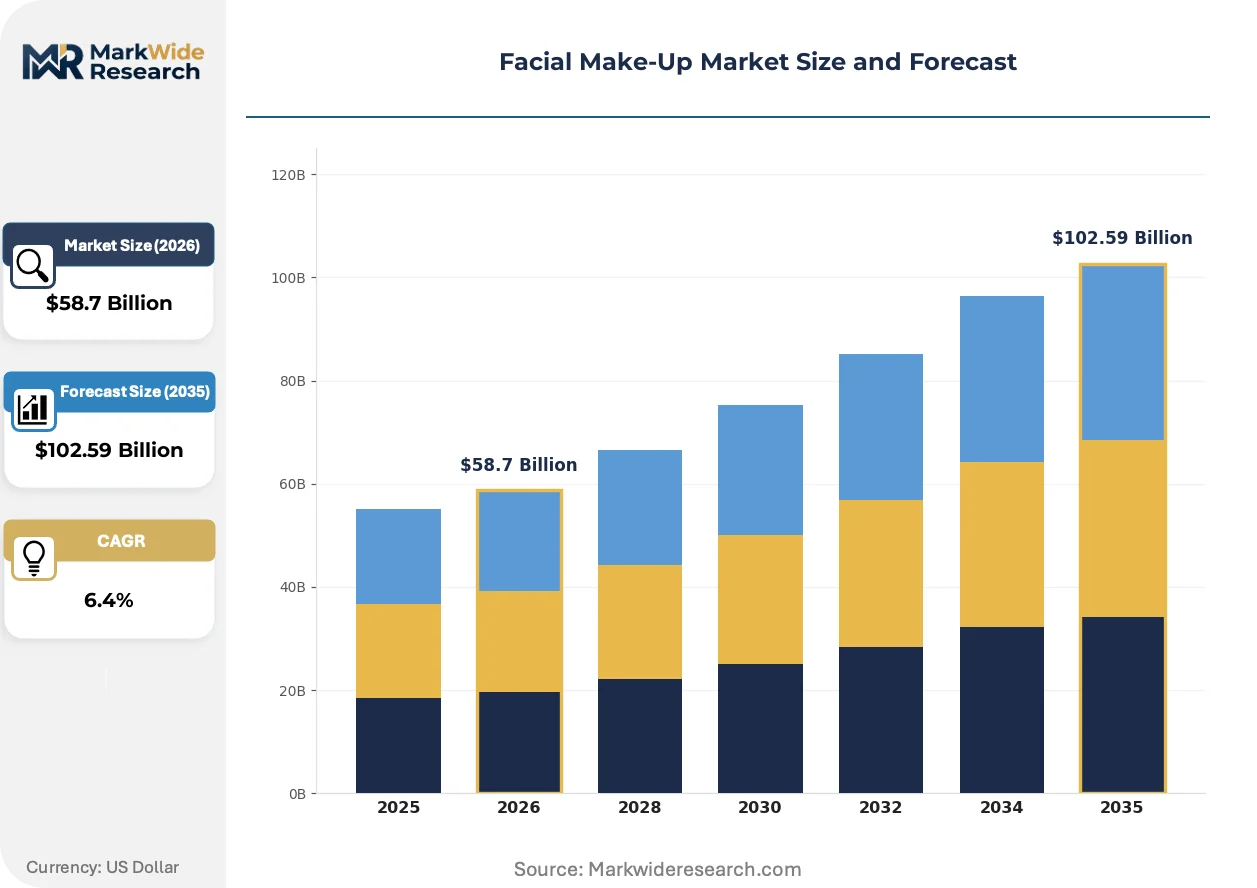
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundation, Primer, Concealer, Blush End User: Professional Artists, General Consumers, Beauty Enthusiasts, Salons Distribution Channel: Online Retail, Specialty Stores, Department Stores, Drugstores Formulation: Cream, Liquid, Powder, Stick |
| Companies Covered | L'Oréal SA, The Estée Lauder Companies Inc., Procter & Gamble Company, Revlon, Inc., Beiersdorf AG, Shiseido Company Limited, Coty Inc., Unilever PLC, Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Make-Up Market Shifts & Advancements
Digital color-matching and biotechnology convergence are compressing traditional shade-development cycles while elevating performance expectations across liquid, powder, and stick formats.
AI-powered skin-tone analysis is electrifying the foundation selection process. Mobile applications and in-store kiosks now map thousands of undertone variations, enabling millennial and Gen Z consumers to bypass counter consultations. This compression of the discovery phase is reducing brand-switching friction and elevating retention for platforms with proprietary matching databases.
REACH Annex XVII expansions are tightening nanoparticle disclosure requirements for color cosmetics sold in EU member states. Formulators must now document particle size distributions and dermal penetration profiles, adding analytical costs that disproportionately burden mid-tier brands lacking captive testing infrastructure. Exporters are responding by segregating EU-compliant SKUs from other regional variants.
Direct-to-consumer sampling programs are displacing department store counter traffic as the primary trial mechanism for prestige facial make-up. Virtual try-on tools paired with micro-sample subscriptions allow brands to bypass wholesale margins while capturing first-party consumer data. This channel pivot is most visible in United States urban markets where foot traffic at traditional beauty retail locations has not recovered to pre-pandemic levels.
Facial Make-Up Market Segmentation
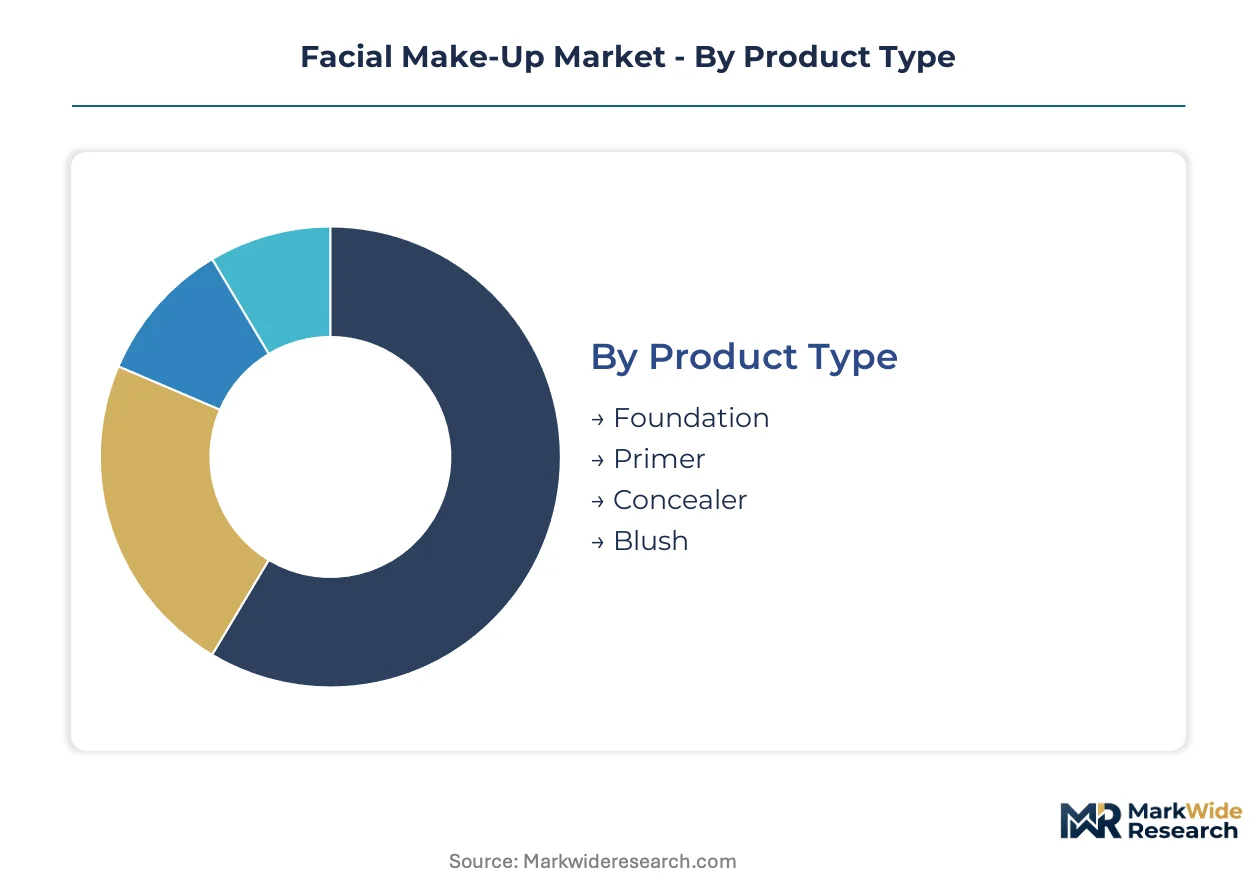
Facial make-up segmentation reveals divergent performance requirements across professional and consumer use cases, with formulation choices and channel access determining margin capture. Understanding these fault lines exposes where technology investments and regulatory compliance costs concentrate.
Product Type:
Customization intensity varies sharply across this category, with daily-use anchor products demanding standardized shade ranges while specialized correction products reward bespoke formulation.
- Foundation:Titanium dioxide and iron oxide dispersions in emollient bases provide coverage grading from sheer to full. Professional makeup artists in the United States drive premium liquid foundation volume, prioritizing shade-matching precision for diverse skin undertones.
- Primer:Silicone and water-based matrices create surface preparation layers that extend wear time. Demand concentrates among millennial and Gen Z consumers in direct-to-consumer channels, where virtual try-on tools reduce trial friction for this discretionary add-on category.
- Concealer:High-pigment concentrated formulations target localized discoloration correction.
- Blush:Pressed powder and cream vehicles deliver cheek color with finish variations from matte to luminous.
Leading the category by volume: Foundation. Growing fastest: Primer.
End User:
Volume scale inversely correlates with performance specification stringency across this customer matrix.
- Professional Artists:This segment demands broadcast-quality coverage durability and flashback-resistant formulations for photography and film applications. Kit replenishment cycles in Los Angeles and New York production hubs sustain bulk purchasing of liquid foundations with expanded shade libraries.
- General Consumers:Daily-use purchasers prioritize convenience and price accessibility over technical performance, with drugstore and mass-market online channels capturing routine replenishment.
- Beauty Enthusiasts:Self-directed learners engage deeply with ingredient transparency and clean-label positioning, driving mineral pigment adoption.
- Salons:Service-oriented establishments require professional-grade durability at wholesale cost structures.
Highest specification requirements: Professional Artists. Expanding most quickly: Beauty Enthusiasts.
Distribution Channel:
Margin compression intensity separates digital-native pathways from legacy retail infrastructure burdened by fixed occupancy costs.
- Online Retail:Direct-to-consumer platforms leverage AI-powered shade-matching algorithms and subscription replenishment to capture recurring revenue. Virtual try-on technology embedded in mobile applications reduces return rates and captures first-party consumer data for personalization.
- Specialty Stores:Sephora and Ulta Beauty in the United States combine experiential testing with loyalty program stickiness, though foot traffic remains below pre-pandemic levels in urban markets.
- Department Stores:Counter-based consultation models face structural decline as discovery shifts to digital channels.
- Drugstores:Mass-market accessibility sustains volume for standard shade ranges with limited service interaction.
Fastest channel expansion: Online Retail. Highest service intensity: Specialty Stores.
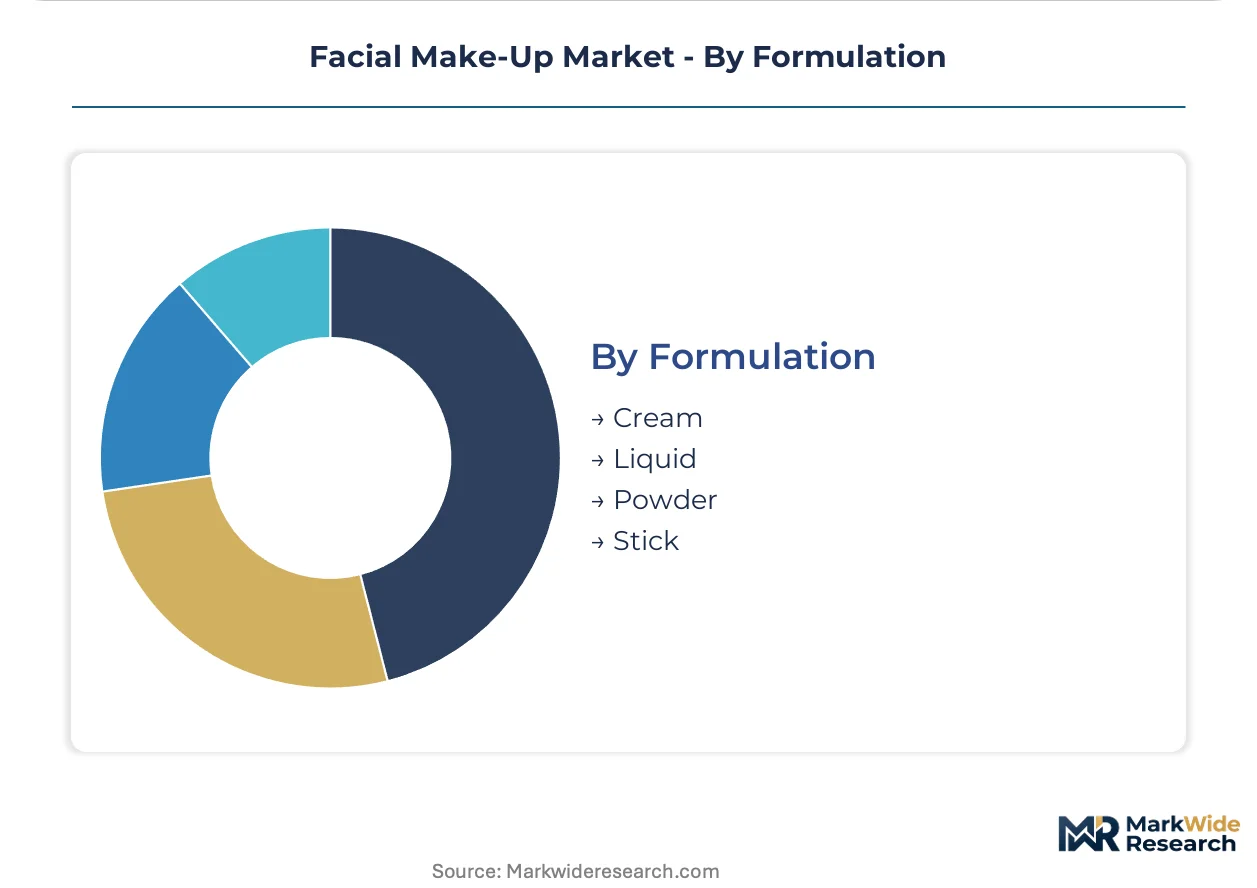
Formulation:
Manufacturing throughput and clean-label compatibility create divergent investment profiles across physical form categories.
- Liquid:Emulsion-based vehicles dominate foundation and concealer production, enabling suspended pigment dispersion and adjustable viscosity for application method versatility. Professional makeup artists in humid climates favor liquid formats for coverage buildability.
- Powder:Pressed and loose mineral bases compete on oil-control performance and portability, with mica and talc alternatives gaining traction under EU REACH scrutiny.
- Cream:Anhydrous and water-in-oil systems deliver emollient-rich payoff for mature skin segments.
- Stick:Solid balm formats prioritize travel convenience and precise application control.
Volume leadership: Liquid. Steepest clean-label reformulation pressure: Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z consumers in the United States drive disproportionate premium beauty spending, while regulatory divergence across FDA, ECHA, and NMPA systems fragments formulation standardization for exporters.
United States
Professional makeup artists in Los Angeles and New York production hubs sustain bulk purchasing of high-performance liquid foundations with expanded shade libraries. The FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, maintaining pre-market notification requirements for color additives. Direct-to-consumer platforms leveraging virtual try-on tools are capturing share from department store counters in urban markets where foot traffic remains below pre-pandemic levels.
China
The NMPA's animal-testing alternatives for imported cosmetics have reopened market access for Western brands previously blocked by regulatory barriers. MIIT and SAMR coordinate national standards for cosmetic ingredient safety alongside provincial enforcement. Shanghai and the Yangtze River Delta concentrate e-commerce fulfillment infrastructure for cross-border beauty platforms serving domestic consumers.
Japan
Shiseido's biotechnology-derived ingredient research networks anchor domestic innovation in fermentation-based pigments. METI supports cosmetic industry competitiveness through regulatory harmonization initiatives with ASEAN markets. Tokyo and Osaka house specialized testing laboratories serving brands seeking compliance with dual domestic and export standards.
Germany
EU REACH Annex XVII expansions on nanoparticle disclosure requirements are elevating analytical costs for color cosmetics sold in EU member states. ECHA coordinates chemical safety assessments that force reformulation cycles extending product development timelines. Hamburg and the Rhine-Ruhr region concentrate contract manufacturing capacity for mineral pigment processing serving pan-European distribution.
France
Prestige heritage brands anchor demand for skin-compatible formulations targeting professional artist segments across European production hubs. ANSM enforces cosmetic vigilance reporting requirements for adverse reactions detected in marketed products. Paris and the Île-de-France region concentrate headquarters operations for global beauty conglomerates managing multi-jurisdiction compliance portfolios.
Facial Make-Up Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance prestige heritage positioning against mass-market volume capture. The vendor base clusters around three strategic tiers: multinational conglomerates with integrated supply chains, mid-cap specialists with regional formulation expertise, and digital-native challengers leveraging direct-to-consumer distribution. Tiered competitive moves include M&A activity targeting biotechnology capabilities and geographic expansion through regulatory-compliant local production.
Within the multinational conglomerate tier, L'Oréal SA and The Estée Lauder Companies Inc. exemplify divergent strategic postures. L'Oréal SA anchors a position through captive pigment supply chain control spanning liquid and powder production lines. The Estée Lauder Companies Inc. occupies a prestige-focused position exemplifying concentrated R&D spending on skin-compatible formulation science. Shiseido Company Limited represents the biotechnology-specialist archetype, with its Japanese research network sourcing fermentation-derived ingredients for clean-label positioning.
| Leading Market Players |
|---|
| L'Oréal SA |
| The Estée Lauder Companies Inc. |
| Procter & Gamble Company |
| Revlon, Inc. |
| Beiersdorf AG |
| Shiseido Company Limited |
| Coty Inc. |
| Unilever PLC |
| Johnson & Johnson Services Inc. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap pigment processors in Germany and France anchor upstream supply discipline, translating captive mineral sourcing into pricing power that resists commodity volatility while forcing synthetic-dependent formulators into cost compression cycles.
Pricing Analysis
Volume leadership in liquid foundation runs through mass-market drugstore tiers while margin capture concentrates in prestige direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by brand heritage and virtual try-on integration depth. Cost compression in mass-market synthetic lines is intensifying because REACH-driven reformulation cycles elevate R&D overhead. Professional makeup artists exhibit lowest price sensitivity due to kit replenishment urgency, whereas general consumers in humid climates prioritize oil-control performance at accessible price points.
Supply Chain Analysis
Single-source vulnerability sits with Chinese titanium dioxide clusters that feed 60% of global pigment dispersion demand. Raw material dependencies center on iron oxides from Indian processing hubs, mica alternatives from Brazilian deposits, and silicone emollients from Japanese chemical networks. Supply chain risk hinges on EU REACH Annex XVII nanoparticle disclosure requirements that delay batch releases. Distribution runs through direct-to-consumer platforms embedding AI shade-matching algorithms alongside specialty store wholesale channels in United States urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual try-on technology is displacing counter-based consultation as the primary trial mechanism, compressing discovery timelines and elevating first-party data value for platforms with proprietary matching infrastructure.
For Market Incumbents: Lock in captive supply of clean-label mineral pigments through backward integration into German and French processing facilities. Secure EU REACH pre-certification for expanded shade libraries before synthetic-dependent competitors complete reformulation cycles. Channel control through subscription replenishment algorithms defends against digital-native challengers capturing millennial and Gen Z retention.
For New Entrants and Emerging Players: Capture white-space in professional artist bulk purchasing for broadcast-quality liquid foundations with flashback-resistant formulations. Target Los Angeles and New York production hubs where kit replenishment cycles sustain volume concentration. Deploy biotechnology-derived pigment positioning sourced from Japanese research networks as differentiation against legacy synthetic lines.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier brands lacking captive testing infrastructure for EU REACH nanoparticle compliance in Hamburg and Rhine-Ruhr manufacturing zones. Long-term viability over the next decade rests on fermentation-based pigment capabilities merging clean-label positioning with performance parity. Watch NMPA animal-testing alternative adoption rates as inflection indicator for Western brand market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Pigment Sourcing | Japanese fermentation networks supply skin-compatible alternatives to REACH-restricted synthetics. |
| Direct-to-Consumer Platform Launch | AI-powered shade matching captures first-party data while bypassing wholesale margin compression. |
| EU REACH Pre-Certification Investment | Early nanoparticle disclosure compliance accelerates product launch timelines versus reformulation-lagged rivals. |
| Subscription Replenishment Model | Automated refill shipments anchored to personalized algorithms secure recurring revenue retention. |
| Professional Artist Segment Expansion | Los Angeles and New York production hub relationships sustain bulk volume with premium pricing durability. |
Research Methodology
Trade databases, SEC 10-K filings, and EU REACH registration records formed the secondary backbone, cross-referenced with primary interviews involving formulation chemists, professional makeup artists, regulatory affairs specialists, and direct-to-consumer platform operators. Bottom-up shipment data from pigment processors and top-down beauty retail audit records were triangulated against channel-specific pricing disclosures.
Historical trendline analysis across mineral pigment adoption curves and synthetic displacement rates informed projection modeling over the analysis window. Segmentation dimensions spanned product type, end-user specification intensity, formulation vehicle, and distribution channel margin structure. CAGRs were derived from fitted growth curves incorporating REACH compliance cost trajectories and virtual try-on penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA regulatory shifts and biotechnology pigment scale-up timelines. Forecasts reflect documented assumptions about professional artist kit replenishment cyclicality and clean-label consumer preference stickiness. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Global Beauty and Personal Care Products Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Electric Face Cleanser Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Personal Care Products Market