
 Essential Oil Soap Market | 2026-2036
Essential Oil Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Oil Soap Market Foresight
Wellness-focused millennials and boutique hospitality buyers is bifurcating demand away from mass retail channels. Dr. Bronner's leverages its organic supply chain and fair-trade sourcing to anchor premium positioning in North American natural grocery. Forest Essentials dominates India's luxury Ayurveda segment through controlled retail distribution and heritage formulation narratives. Rocky Mountain Soap Company competes on small-batch manufacturing transparency and regional ingredient provenance.
Essential oil soap denotes surfactant-based cleansing products where fragrance and therapeutic claims derive entirely from volatile plant extracts rather than synthetic aroma compounds, typically formulated with saponified vegetable oils at 2-5% essential oil loading to preserve skin barrier function while delivering antimicrobial or aromatherapy benefits. Solid bar formats retain cost advantages in emerging markets due to minimal packaging and lower shipping weights, while liquid variants capture premium margins in hospitality and spa channels where dispenser integration matters. Lavender and tea tree fragrance types lead volume given established consumer recognition of their calming and antiseptic properties, though eucalyptus is gaining fastest in wellness-oriented hotel amenity programs.
EPA regulations on antimicrobial claims constrain how tea tree and eucalyptus soaps market germ-killing benefits in the United States, while EU REACH and the EU Green Deal push substitution of palm-derived surfactants with sustainably certified alternatives. India's BIS mandatory certification for cosmetics and the CDSCO's evolving herbal product standards create compliance thresholds that favor organized manufacturers over informal producers. Stakeholders must monitor how fragmented national organic certification schemes either harmonize or splinter, determining which suppliers can scale cross-border without reformulation costs.
Market Dynamics
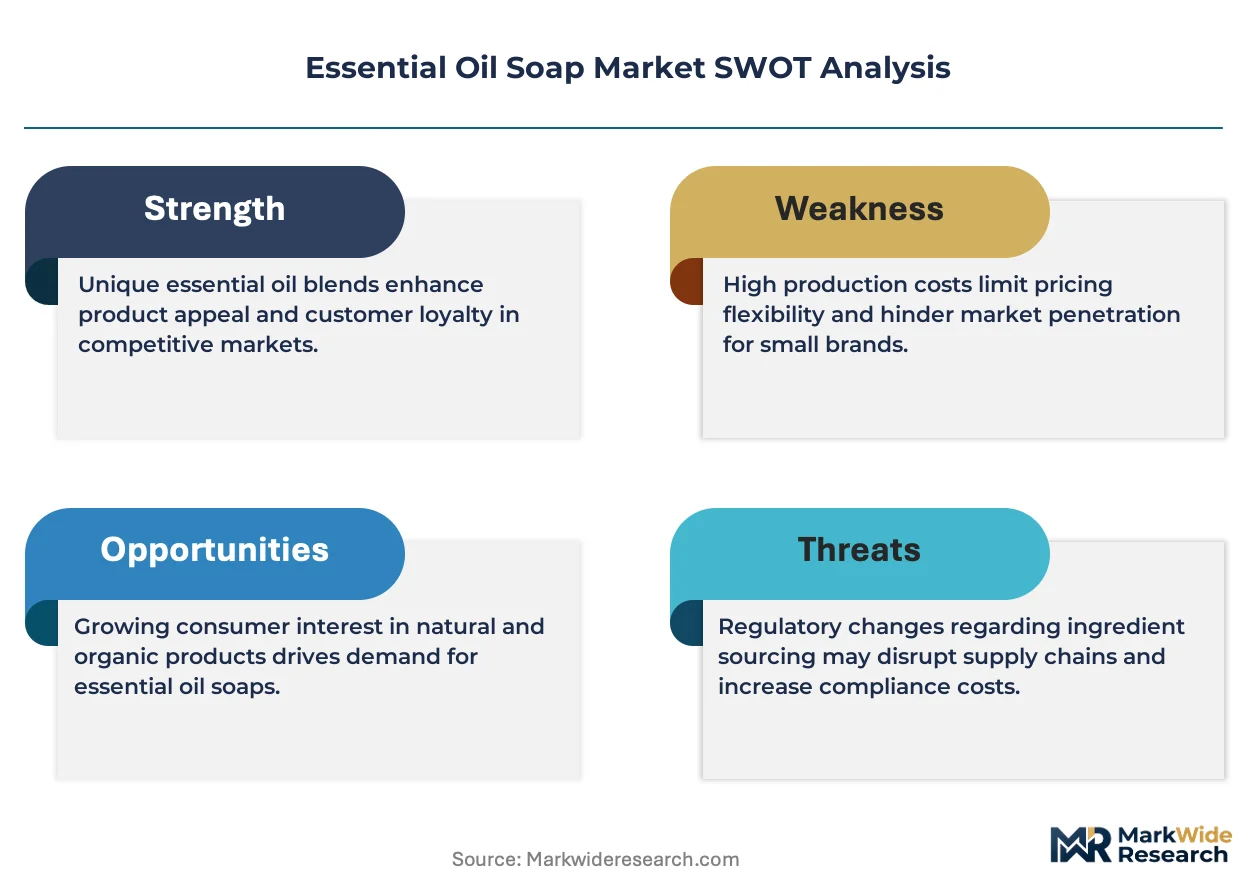
EU REACH restrictions on synthetic fragrance chemicals are forcing formulators to rebuild supply chains around certified organic essential oil inputs, compressing margins for producers dependent on petroleum-derived aroma compounds.
Growth Catalysts
- Regulatory substitution mandates:EU REACH and the EU Green Deal are prohibiting phthalate-based synthetic fragrances, compelling mass-market brands to source lavender and tea tree oils from certified organic cooperatives.
- Hospitality amenity upgrades:Premium hotel chains in India and the United Arab Emirates now specify essential oil soaps as brand differentiators, creating pull-through demand for 2-5% loaded formulations.
- Ayurvedic export channels:India's heritage wellness brands leverage CDSCO herbal product standards to access regulated markets in Europe and North America with traceable supply chains.
Market Restraints
- Essential oil price volatility:Climate-induced harvest failures in Bulgaria and France spike lavender oil costs, squeezing mid-tier manufacturers without backward integration into farming cooperatives.
- Antimicrobial claim constraints:EPA regulations in the United States restrict how tea tree and eucalyptus soaps market germ-killing benefits, limiting therapeutic positioning in the world's largest personal care market.
- Palm-derived surfactant substitution costs:EU Green Deal mandates for sustainably certified palm alternatives raise input costs 15-25% versus conventional bases, disadvantaging price-sensitive bar soap segments.
Strategic Opportunities
- Spa and wellness center channels:Liquid dispenser formats capture premium margins in hospitality and medical wellness facilities where aromatherapy integration drives repurchase contracts.
- Indian domestic market deepening:BIS mandatory certification for cosmetics creates compliance thresholds that favor organized manufacturers over informal producers in tier-two and tier-three cities.
- Convergence of solid formats with zero-waste retail:Minimal packaging bar soaps align with plastic-free retail mandates in France and Germany, opening shelf space previously dominated by liquid body wash.
Industry Challenges
- Organic certification fragmentation:Non-harmonized national schemes in India, the United States, and EU member states force redundant auditing costs on exporters seeking multi-territory approval.
- Skilled formulation chemist scarcity:Expertise in balancing antimicrobial essential oil loads against skin barrier preservation concentrates at heritage Ayurveda houses and European natural cosmetic specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Oil Soap Market |
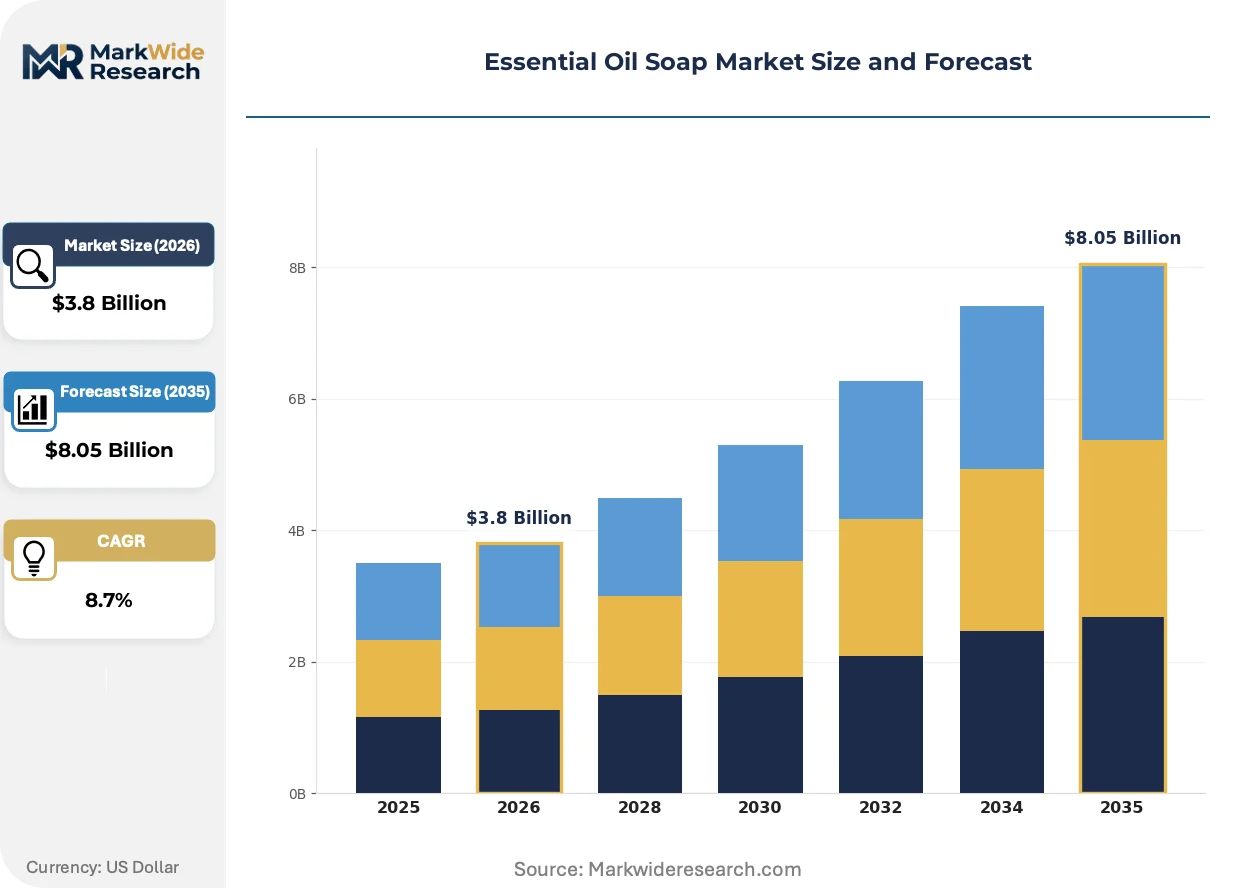
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Solid Bar, Foaming Soap, Crème Soap Fragrance Type: Lemon, Lavender, Eucalyptus, Tea Tree End User: Households, Hotels, Spas, Salons Packaging Type: Bottles, Jars, Pouches, Bars |
| Companies Covered | Young Living Essential Oils, doTERRA, Dr. Bronner's, Rocky Mountain Soap Company, EO Products, Neal's Yard Remedies, Lush, Forest Essentials, Kama Ayurveda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Oil Soap Market Shifts & Advancements
Cold-process saponification methods are gaining industrial scale as brands seek to preserve volatile terpene compounds that degrade under heat-intensive manufacturing, reshaping equipment investment patterns across mid-sized producers.
Supercritical CO2 extraction is supplanting steam distillation for citrus and flower oils in premium formulations, preserving heat-sensitive limonene and linalool fractions. Boutique hospitality buyers in California and Provence now specify CO2-extracted oils for guest amenities. This technology is compressing the addressable market for conventional distilled oils above the mass retail tier.
India's CDSCO is tightening herbal product standards for cosmetics claiming Ayurvedic heritage, requiring documented ingredient provenance and heavy metal testing. Manufacturers must restructure supplier qualification protocols to maintain export licenses. Heritage brands with captive farming operations gain compliance speed advantages over contract-manufactured competitors.
Boutique hospitality procurement teams now source essential oil amenities through specialized B2B platforms that bypass traditional distributor markups. Small-batch producers in Colorado and the Himalayas sell directly to hotel chains, disintermediating regional wholesalers. This channel compression is most visible in the 50-200 room independent hotel segment across Portugal and Morocco.
Essential Oil Soap Market Segmentation
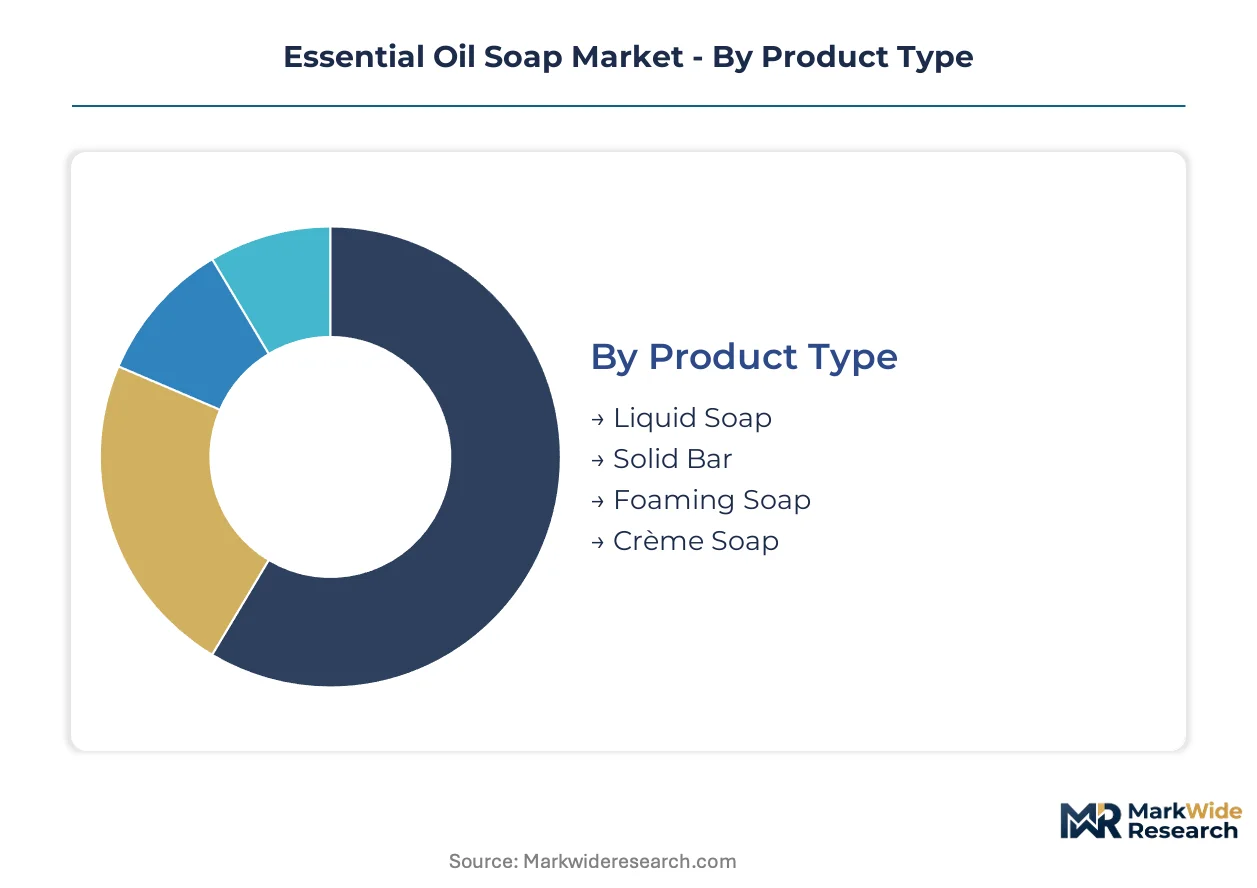
Product configuration determines margin capture in essential oil soaps, where hospitality procurement specifications diverge sharply from mass retail requirements. Format, fragrance chemistry, and dispenser compatibility each create distinct competitive arenas with different supplier qualification thresholds.
Product Type:
Margin pools concentrate in liquid formats where dispenser integration commands hospitality premiums, while solid bars retain cost advantages in emerging market retail.
- Liquid Soap:Surfactant-based formulations at 2-5% essential oil loading integrate with wall-mounted dispenser systems in hotel bathrooms and medical wellness facilities. Premium chains in India and the United Arab Emirates now specify liquid formats as brand differentiators, creating pull-through demand for certified organic inputs.
- Solid Bar:Saponified vegetable oil bases with minimal packaging weight deliver cost advantages in price-sensitive retail channels across tier-two and tier-three Indian cities. Zero-waste retail mandates in France and Germany are reopening shelf space previously dominated by liquid body wash.
- Foaming Soap:Aerated formulations requiring specialized pump mechanisms concentrate in institutional hygiene contracts.
- Crème Soap:High-fat content bars targeting premium domestic consumers with skin barrier preservation claims.
The dominant share belongs to solid bars, while liquid formats are climbing the fastest as hospitality channels upgrade amenities.
Fragrance Type:
Established consumer recognition drives volume concentration in lavender and tea tree, though regulatory constraints on antimicrobial claims reshape competitive positioning.
- Lavender:Volatile oil from Lavandula angustifolia dominates volume given established aromatherapy associations with sleep and stress reduction. Climate-induced harvest failures in Bulgaria and France periodically spike input costs, squeezing mid-tier manufacturers without backward integration into farming cooperatives.
- Tea Tree:Melaleuca alternifolia oil carries antiseptic terpinen-4-ol concentrations that support therapeutic positioning. EPA regulations in the United States restrict germ-killing benefit claims, limiting market penetration in the world's largest personal care market despite proven antimicrobial efficacy.
- Eucalyptus:Eucalyptus globulus oil is gaining fastest in wellness-oriented hotel amenity programs across California and Provence.
- Lemon:Citrus limonum extracts from cold-pressed peel dominate budget retail segments with fresh scent profiles.
Lavender retains the largest volume position, though eucalyptus is expanding most quickly as spa channels prioritize respiratory wellness associations.
End User:
Procurement sophistication separates hospitality buyers with technical specifications from household consumers driven by shelf presence and price.
- Hotels:Premium hospitality chains now source essential oil amenities through specialized B2B platforms that bypass traditional distributor markups, disintermediating regional wholesalers in the 50-200 room independent hotel segment across Portugal and Morocco.
- Households:Mass retail consumers in India demonstrate strong loyalty toward Ayurvedic heritage brands with BIS mandatory certification, creating compliance thresholds that favor organized manufacturers over informal producers.
- Spas:Medical wellness facilities drive repurchase contracts for liquid dispenser formats where aromatherapy integration supports premium pricing.
- Salons:Professional beauty services specify bulk formats with consistent fragrance profiles for back-bar use.
Households command the greatest volume, yet hotels are gaining share fastest as boutique properties differentiate through amenity upgrades.
Packaging Type:
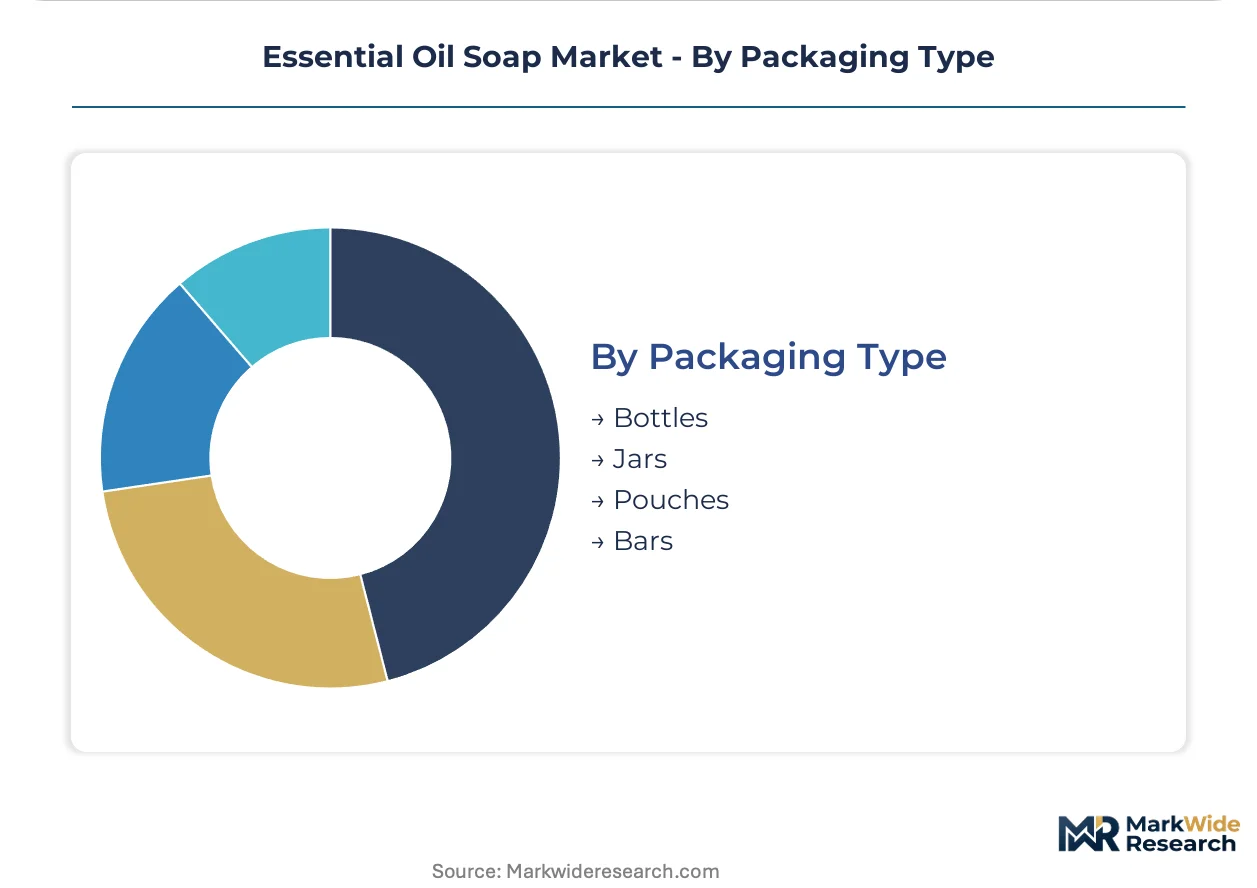
Material choice reflects channel requirements, from dispenser-compatible bottles to naked bars for zero-waste retail.
- Bottles:PET and glass containers dominate liquid soap distribution, with pump mechanisms specified for hospitality dispenser integration.
- Bars:Unwrapped or paper-wrapped formats align with plastic-free retail mandates in France and Germany.
- Jars:Wide-mouth containers target premium crème soap positioning in domestic gift channels.
- Pouches:Flexible refill formats reduce shipping weights for e-commerce distribution.
Bottles hold the leading position, while bars are advancing fastest on sustainability-driven retail policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports Ayurvedic heritage formulations to premium hospitality buyers across the United Arab Emirates and European Union, while Bulgarian lavender oil feeds manufacturing clusters in France and Germany.
India
Domestic demand concentrates in tier-two cities where BIS mandatory certification for cosmetics filters informal producers. CDSCO's evolving herbal product standards create compliance thresholds that favor organized manufacturers with documented ingredient provenance. Manufacturing clusters in Maharashtra and Karnataka supply both domestic retail and export channels to regulated markets.
United States
Wellness-focused millennials drive natural grocery channel expansion for certified organic formulations. EPA regulations constrain antimicrobial claim marketing for tea tree and eucalyptus variants, limiting therapeutic positioning. Colorado-based small-batch producers supply boutique hospitality buyers through direct B2B platforms.
Germany
Zero-waste retail mandates in metropolitan centers reopen shelf space for naked bar formats previously displaced by liquid body wash. EU REACH restrictions on synthetic fragrance chemicals compel formulators to source certified organic essential oil inputs. Production facilities in Bavaria and North Rhine-Westphalia specialize in cold-process saponification equipment.
France
Provence-based cooperatives supply lavender oil to premium hospitality amenity programs across California and the UAE. EU Green Deal mandates for sustainably certified palm alternatives raise surfactant input costs. Manufacturing concentration in Grasse and the Alpes-de-Haute-Provence cluster centers on fragrance extraction and formulation.
United Arab Emirates
Premium hotel chains specify essential oil amenities as brand differentiators, creating pull-through demand for liquid dispenser formats. MOHAP cosmetic registration requirements favor suppliers with established EU or US regulatory compliance. Dubai-based procurement platforms disintermediate traditional regional wholesalers for independent hotel properties.
Essential Oil Soap Market Competitive Landscape
Player mix skews toward heritage wellness houses and small-batch regional specialists rather than multinational consumer goods conglomerates. Market structure fragments across three tiers: Ayurvedic heritage brands with captive farming operations, North American natural grocery anchors with fair-trade supply chains, and European boutique formulators emphasizing regional ingredient provenance. Dominant competitive moves include backward integration into organic farming cooperatives and direct B2B platform sales to hospitality procurement teams.
Within the heritage wellness tier, Forest Essentials and Kama Ayurveda represent Indian manufacturers leveraging BIS certification and CDSCO compliance to access regulated export markets. Dr. Bronner's anchors the North American natural grocery segment with organic supply chain positioning. Among boutique regional specialists, Rocky Mountain Soap Company exemplifies small-batch manufacturing transparency focused on ingredient provenance narratives.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| doTERRA |
| Dr. Bronner's |
| Rocky Mountain Soap Company |
| EO Products |
| Neal's Yard Remedies |
| Lush |
| Forest Essentials |
| Kama Ayurveda |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lavender oil inventory cycles compress pricing power for mid-tier manufacturers lacking backward integration into Bulgarian or French farming cooperatives, while certified organic essential oil premiums widen against conventional inputs as EU REACH restrictions harden.
Pricing Analysis
Steam-distilled versus supercritical CO2-extracted essential oil grades command a three-tier pricing structure across premium, standard, and economy levels, with boutique hospitality buyers absorbing CO2-extraction premiums for volatile terpene preservation. Certification tier—EU organic, USDA organic, or uncertified—drives price differentiation alongside volume scale and regional ingredient provenance narratives. Pricing pressure stems from climate-induced harvest volatility in Provence and Bulgaria, squeezing mid-tier bar soap segments. Household consumers in tier-two Indian cities demonstrate highest price sensitivity, while premium hotel procurement teams in the UAE and California show lowest sensitivity to dispenser-format premiums.
Supply Chain Analysis
Port congestion along Asia-Europe container lanes elevates inbound logistics costs for Indian manufacturers exporting Ayurvedic formulations to regulated markets, compressing margins on liquid dispenser formats. Essential oil supply concentrates in Bulgaria, France, and India, with surfactant bases drawing from Malaysian and Indonesian palm oil sources subject to EU Green Deal sustainability mandates. Raw material dependencies span lavender and tea tree oils, saponified vegetable bases, and cold-process equipment. Single-source vulnerability in Bulgarian lavender harvests poses structural risk. Distribution runs through specialized B2B hospitality platforms disintermediating regional wholesalers, alongside traditional retail channels for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-hotel procurement platforms are reconfiguring this market toward ecosystem economics, with interoperability between boutique producer inventory systems and chain-wide amenity specifications creating winner-take-most dynamics.
For Market Incumbents: Fortify captive farming operations in Maharashtra and Karnataka to secure CDSCO-compliant ingredient provenance against contract-manufactured competitors. Deepen backward integration into organic cooperatives to buffer lavender price volatility, while deploying cold-process saponification capacity to preserve terpene premiums that synthetic-fragrance-dependent mass brands cannot replicate.
For New Entrants and Emerging Players: Lead with zero-waste retail mandates in France and Germany as shelf-space entry points, targeting independent hotel properties in Portugal and Morocco through direct B2B platforms bypassing distributor markups. Penetrate the 50-200 room boutique hospitality segment with CO2-extracted oil credentials and regional ingredient provenance narratives that command dispenser-integration premiums.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because fragmented national organic certification schemes favor acquirers with multi-territory compliance infrastructure over pure-brand targets. Target heritage Ayurveda houses with captive farming and established BIS certification. Watch for CDSCO herbal product standard tightening as inflection signal accelerating consolidation toward organized manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farming | Captive lavender and tea tree supply buffers climate-induced price volatility for mid-tier manufacturers. |
| Cold-Process Saponification Scale-Up | Heat-minimizing production preserves volatile terpenes that command boutique hospitality premiums. |
| Direct B2B Platform Launch | Bypassing regional wholesalers captures margin from independent hotel procurement teams in Portugal and Morocco. |
| Zero-Waste Retail Certification | France and Germany plastic-free mandates reopen shelf space for naked bar formats against liquid body wash. |
| CDSCO Compliance Infrastructure | Documented ingredient provenance and heavy metal testing protocols unlock regulated export market access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including hospitality procurement managers at premium chains in India and the UAE, formulation chemists at heritage Ayurveda houses, organic farming cooperative directors in Provence and Bulgaria, and BIS certification auditors. Secondary validation drew from CDSCO herbal product guidelines, EU REACH restriction updates, customs records for essential oil trade flows, and SEC filings for publicly listed personal care companies. Bottom-up volume modeling triangulated against top-down market sizing.
Across the analysis window, forecasts incorporated product format segmentation by liquid, solid bar, and foaming variants; fragrance chemistry tier by distillation method; end-use channel by hospitality, household, and spa; and regional regulatory cluster by EU REACH, EPA antimicrobial claim constraints, and CDSCO evolving standards. CAGRs derived from segment-level growth trajectory blending. Industry-specific inputs included lavender harvest yield data from Bulgarian agricultural statistics and hospitality amenity upgrade pipeline tracking from Dubai-based procurement platforms.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, CDSCO standard harmonization, or climate stability in Mediterranean growing regions would require recalibration. Forecasts reflect documented assumptions regarding organic certification adoption curves and hospitality channel premiumization rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Silicone Makeup Sponge Market