
 Luxury Handbag Market | 2026-2036
Luxury Handbag Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Handbag Market Intelligence
The gap between artisan-crafted leather goods and synthetic-alternative entry luxury is recalibrating how brands allocate capital and talent. Chanel sustains its position through vertical integration of tannery operations in France. Prada differentiates via its Re-Nylon initiative and controlled scarcity in product drops. Louis Vuitton dominates trunk-making heritage while extending into experiential retail formats.
A luxury handbag is a structured or soft-bodied personal accessory, typically constructed from calfskin, crocodile, or coated canvas with brass or gold-plated hardware, designed for status signaling and daily utility. Tote bags and crossbody bags anchor volume, while clutches capture event-driven margin pools. Genuine leather occupies the premium tier, though exotic skins face shrinking supply under CITES frameworks. Brand stores and luxury boutiques control pricing power, while online retailers expand access among younger collectors.
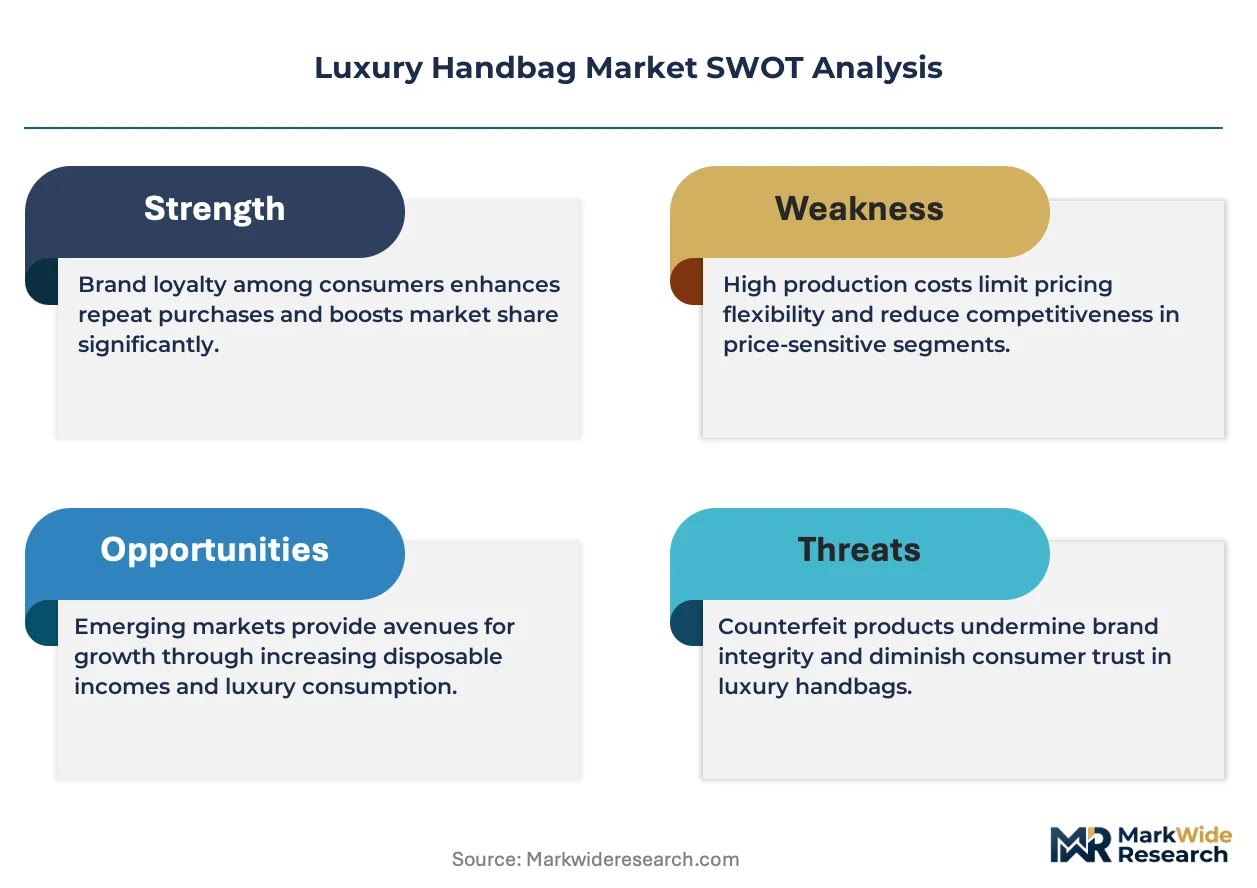
REACH in Europe restricts chromium tanning and exotic skin processing, while CITES governs cross-border trade in crocodile and python materials. The EU Green Deal pushes brands toward traceable supply chains and bio-based alternatives. Stakeholders must weigh material compliance costs against heritage positioning as regulatory scope widens.
Market Dynamics
REACH restrictions on chromium tanning and exotic skin processing are forcing European tanneries to retool toward bio-based alternatives, while Chinese domestic consumption concentrates demand power in Shanghai and Beijing. This regulatory-demand squeeze is compressing heritage supply chains and accelerating material substitution timelines.
Growth Catalysts
- EU Green Deal traceability mandates:Brussels is requiring supply chain disclosure for leather goods, pushing brands to invest in blockchain-tracked sourcing that commands premium positioning among sustainability-oriented collectors.
- Gen Z collector entry:First-time luxury buyers under 30 are purchasing entry-tier leather goods at double the rate of prior cohorts, expanding addressable demand beyond established socialite networks.
- Mycelium leather maturation:Biofabricated alternatives from Bolt Threads and MycoWorks are achieving tensile parity with calfskin, enabling compliant product lines that bypass CITES exotic skin restrictions.
Market Restraints
- Crocodile farming concentration:Over 70% of legal Nile crocodile skins originate from Australian and African farms facing climate volatility and export permit delays under CITES Appendix II quotas.
- Artisan labor scarcity:French and Italian saddlery schools produce fewer than 200 master leatherworkers annually, constraining expansion of hand-stitched atelier lines regardless of capital availability.
- Chrome VI liability exposure:ECHA classification of hexavalent chromium as a substance of very high concern is triggering insurance premium spikes for tanneries still using traditional mineral tanning.
Strategic Opportunities
- India domestic luxury emergence:Mumbai and Delhi are developing indigenous high-end leather goods consumption as import duties on European finished goods create protected space for local atelier brands.
- Recommerce platform integration:Vestiaire Collective and The RealReal authentication protocols are creating certified secondary markets that extend product lifecycle value and capture margin from resale velocity.
- Biopolymer hardware substitution:Zamac and brass alternatives derived from castor oil polymers are eliminating nickel allergy liabilities while satisfying EU nickel directive compliance for metal components.
Industry Challenges
- Master craftsperson succession:The average age of leather artisans at heritage French manufactures exceeds 55, with apprenticeship programs failing to attract sufficient replacement talent despite wage premiums.
- Dual certification complexity:Brands must simultaneously satisfy LWG (Leather Working Group) environmental standards and CITES documentation for exotic skin products, creating documentation bottlenecks that extend time-to-market by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Handbag Market |
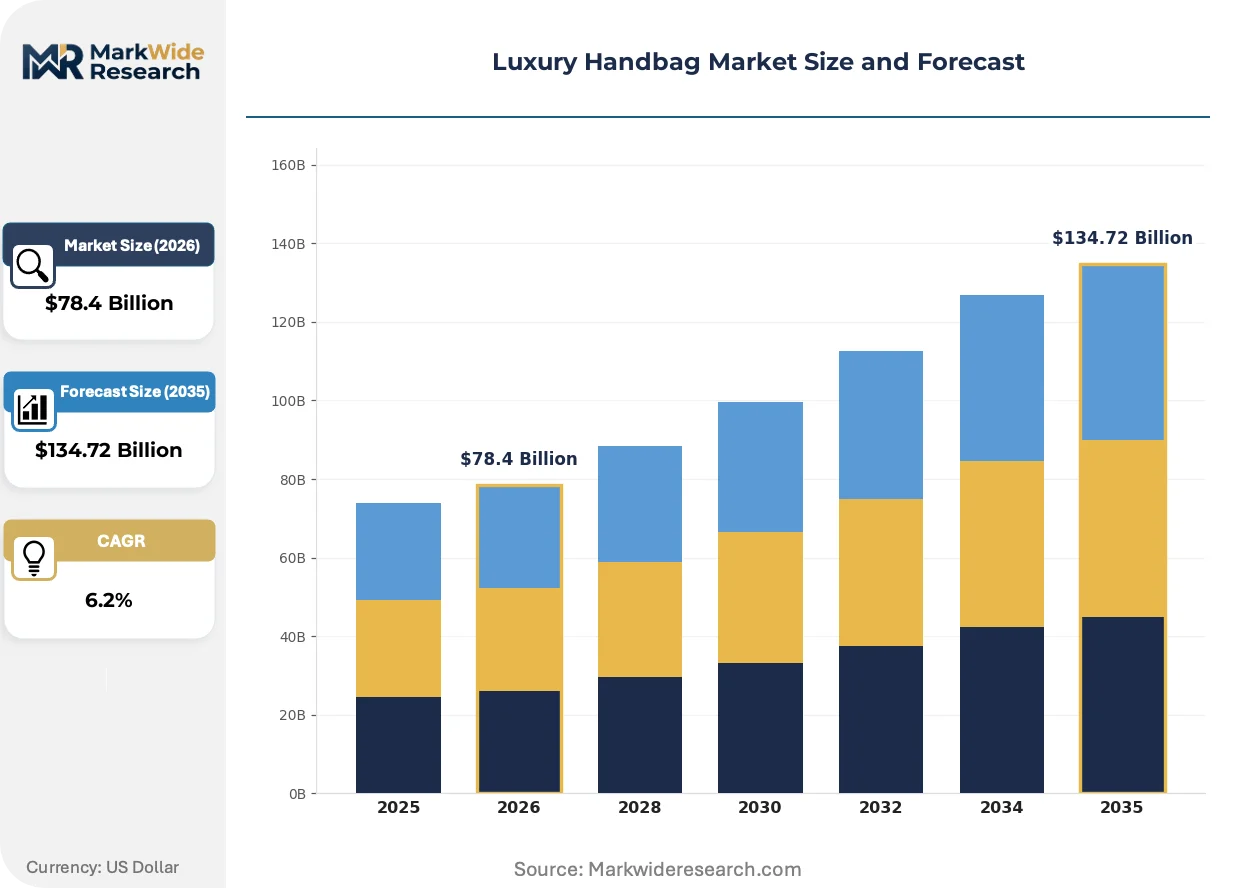
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tote Bags, Clutches, Satchels, Shoulder Bags, Crossbody Bags, Duffel Bags Material: Genuine Leather, Faux Leather, Canvas, Nylon, Suede, Exotic Skins End User: Fashion Enthusiasts, Collectors, Celebrities, Professionals, Socialites Distribution Channel: Online Retailers, Luxury Boutiques, Department Stores, Brand Stores, Specialty Shops |
| Companies Covered | Gucci, Bottega Veneta, Chanel, Fendi, Saint Laurent, Dior, Prada, Celine, Louis Vuitton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Handbag Market Strategic Shifts & Innovations
Biofabrication and digital traceability are converging to redefine material provenance as a competitive weapon. Heritage craftsmanship is being preserved through hybrid production models that separate hand-finishing from automated cutting.
Mycelium-derived leather from Bolt Threads and MycoWorks is expanding into structured handbag bodies previously reserved for exotic skins, with early adoption concentrated among sustainability-focused millennials in California and New York. The material's batch-to-batch consistency now supports hardware attachment stress points, enabling full product substitution rather than panel-only applications. This capability expansion is compressing the price premium between biofabricated and conventional leather from 40% to 15% at wholesale.
REACH Annex XVII restrictions on chromium VI compounds are compelling Italian tanneries in Tuscany to convert vegetable tanning vats at capital outlays exceeding €2 million per facility. The regulation's 2024 enforcement window is accelerating consolidation among mid-size tanneries unable to fund compliance independently. Vegetable-tanned output is commanding 20-30% wholesale premiums from brands seeking EU market access without regulatory risk.
Collector purchasing is fragmenting across authentication-enabled resale channels that bypass primary retail entirely. Vestiaire Collective's European user base is transacting vintage Chanel and Hermès at volumes that rival boutique sales in Paris and London. This channel displacement is most pronounced among collectors aged 25-35 who treat resale platforms as primary discovery mechanisms rather than liquidation outlets.
Luxury Handbag Market Segmentation
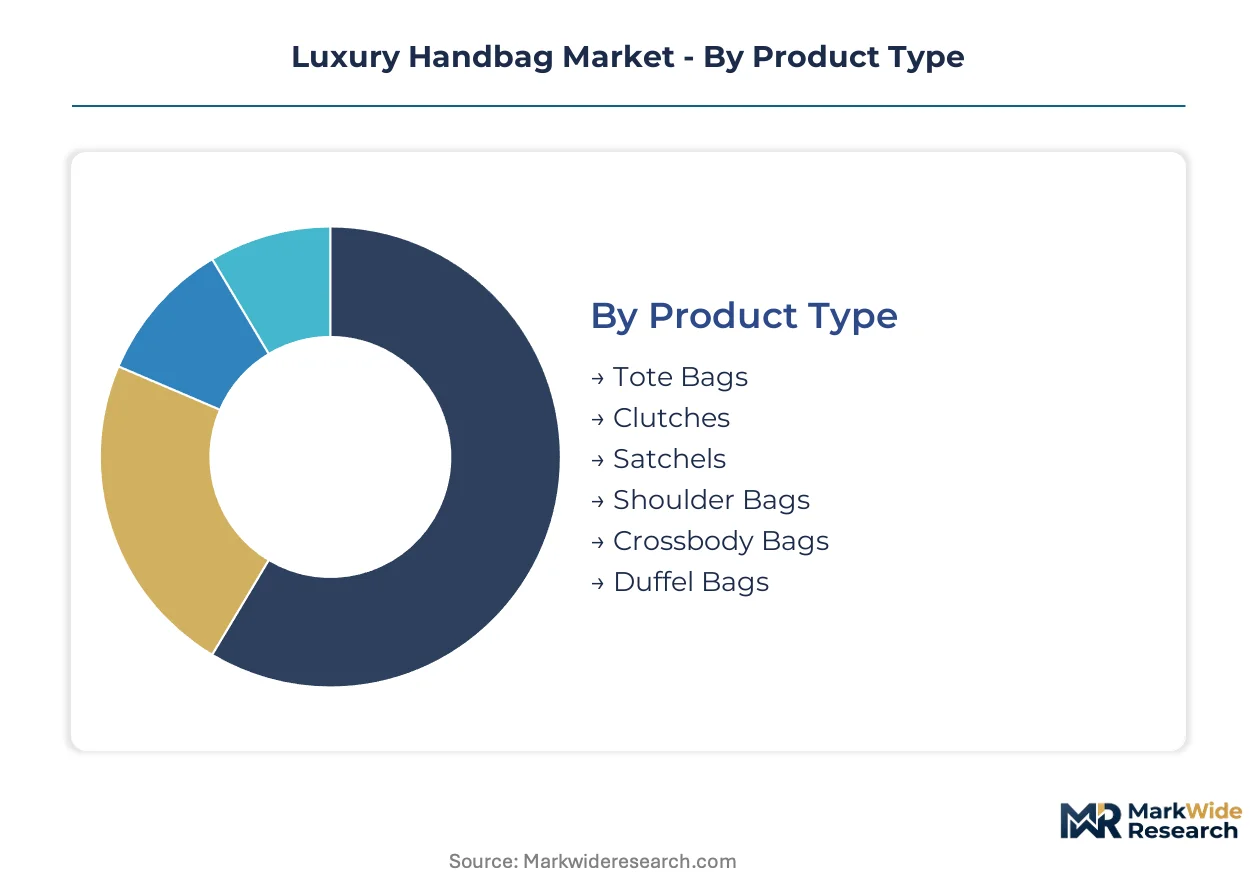
Segmentation in luxury handbags reveals how capital allocation, regulatory exposure, and collector behavior diverge across product architectures. Each dimension carries distinct margin structures and supply chain requirements that determine competitive positioning.
Product Type:
Capital intensity escalates with structural complexity and hardware integration, separating volume-driven silhouettes from artisan-limited editions.
- Tote Bags:Unstructured or semi-structured bodies with reinforced base panels accommodate daily utility and work commuting. Demand concentrates among professionals in Shanghai and New York where office-to-evening versatility commands premium positioning.
- Clutches:Rigid-frame or soft envelope constructions with minimal hardware for event-driven occasions. Collector appetite in Milan and Paris sustains margin pools despite lower absolute volumes, driven by gala and red-carpet placement.
- Satchels:Flap-top designs with adjustable straps bridging academic and professional aesthetics. Japanese and South Korean markets favor compact proportions with organized interior compartments.
- Shoulder Bags:Single-strap constructions with curved bases for weight distribution. Heritage French manufactures allocate dedicated atelier lines to this silhouette given its enduring cross-demographic appeal.
- Crossbody Bags:Compact rectangular bodies with long adjustable straps enabling hands-free mobility. Gen Z entry purchases in California cluster here, prioritizing convenience and entry-tier price accessibility.
- Duffel Bags:Cylindrical or barrel-shaped travel-focused constructions with extended zipper apertures. Weekend travel patterns in London and Dubai sustain niche positioning outside core handbag revenue.
Tote bags absorb the bulk of installed capacity; crossbody bags are expanding most quickly.
Material:
Raw material selection determines regulatory compliance burden and heritage authenticity signaling, with exotic skins facing the steepest documentation requirements.
- Genuine Leather:Full-grain or top-grain bovine hides processed through chrome or vegetable tanning for structural integrity. Italian tanneries in Tuscany supply heritage brands, though REACH Annex XVII conversion costs are compressing mid-tier supplier margins.
- Exotic Skins:Nile crocodile, python, and lizard materials governed by CITES Appendix II quotas. Australian and African farm concentration creates supply volatility that Hermès and Loro Piana manage through multi-year purchasing agreements.
- Faux Leather:Polyurethane or polyvinyl chloride alternatives avoiding animal-derived content. Bolt Threads and MycoWorks mycelium variants are achieving tensile parity in California pilot programs.
- Canvas:Cotton or linen plain-weave bases with coated finishes for water resistance. Louis Vuitton's Monogram and Damier patterns anchor brand recognition in this category.
- Nylon:Recycled ECONYL or virgin polyamide constructions pioneered by Prada's Re-Nylon initiative. Marine plastic sourcing commands sustainability premiums among Scandinavian collectors.
- Suede:Split-grain leather with napped surface finish requiring specialized cleaning protocols. Seasonal color rotations in Paris and Milan drive limited production runs.
Genuine leather commands the deepest supply chain investment; mycelium-derived alternatives are climbing the fastest as CITES restrictions tighten.
End User:
Collector sophistication and purchase frequency separate transactional buyers from relationship-driven accounts that brands cultivate across decades.
- Collectors:Serial purchasers with authentication expertise and resale market participation. Vestiaire Collective and The RealReal user bases in Europe concentrate this segment, where vintage Hermès and Chanel transact at volumes rivaling primary retail.
- Fashion Enthusiasts:Trend-responsive buyers rotating silhouettes seasonally with lower per-unit expenditure. Social media discovery in Seoul and São Paulo drives rapid style turnover.
- Celebrities:Gifting recipients and paid placement partners whose public appearances generate aspirational demand. Contractual obligations with houses like Dior and Celine structure visibility timelines.
- Professionals:Function-first purchasers prioritizing capacity, organization, and durability for daily commuting. London and Singapore financial services clusters sustain structured tote and satchel demand.
- Socialites:Traditional heritage-brand loyalists with multi-generational purchase histories. This cohort is aging, with succession planning failing to attract equivalent replacement rates among under-40 demographics.
Collectors absorb the bulk of high-margin limited editions; fashion enthusiasts are gaining share fastest through digital-native discovery channels.
Distribution Channel:
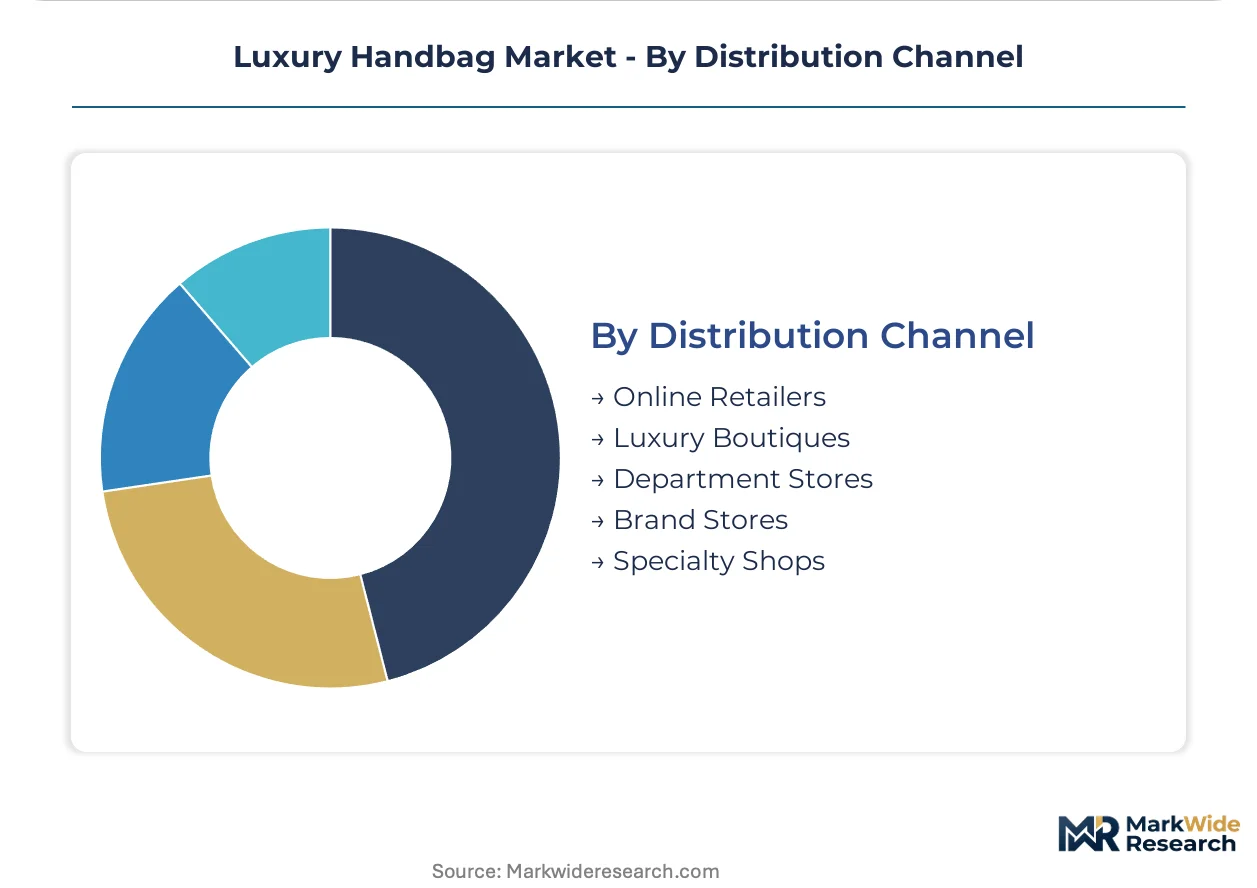
Channel selection determines pricing control, authentication burden, and customer data capture, with direct retail commanding the steepest capital requirements.
- Brand Stores:Flagship and secondary locations with full assortment control and bespoke services. Chanel's vertical integration of retail real estate in Paris, New York, and Tokyo exemplifies this model's capital intensity.
- Luxury Boutiques:Multi-brand curated environments with edited assortments and personalized service. Milan's Via Montenapoleone and London's Bond Street clusters concentrate independent retail expertise.
- Online Retailers:E-commerce platforms with authentication protocols and global reach. Farfetch and Net-a-Porter infrastructure enables geographic expansion without physical retail investment.
- Department Stores:Concessions within larger retail environments with shared foot traffic but reduced brand control. Printemps in Paris and Bergdorf Goodman in New York maintain relevance through location exclusivity.
- Specialty Shops:Niche accessories-focused retailers with deep category expertise. Tokyo's Daikanyama and Brooklyn's Williamsburg neighborhoods host emerging atelier discovery venues.
Brand stores command the heaviest capital deployment; online retailers are scaling fastest through authentication-enabled resale integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Beijing concentrate the world's most active luxury handbag collector base, with domestic Chinese consumption now outpacing outbound tourist spending across all major heritage houses.
France
Paris anchors European atelier production through vertically integrated tannery operations in the Loire Valley. REACH Annex XVII restrictions on chromium VI compounds are compelling Tuscan suppliers to convert vegetable tanning vats at capital outlays exceeding €2 million per facility. The Maroquinerie de Guyenne cluster near Bordeaux is expanding hand-stitched capacity for heritage trunk-making lines.
Italy
Milan and Florence sustain margin pools through event-driven clutch demand and artisan-limited editions. The EU Green Deal traceability mandates are pushing brands to invest in blockchain-tracked sourcing that commands premium positioning. Tuscan tanneries in Santa Croce sull'Arno are consolidating as mid-size suppliers fail to fund REACH compliance independently.
United States
New York and California host the fastest-growing Gen Z collector entry, with first-time luxury buyers under 30 purchasing entry-tier leather goods at double prior cohort rates. California pilot programs are achieving tensile parity for mycelium-derived alternatives from Bolt Threads and MycoWorks. Vestiaire Collective's authentication protocols are creating certified secondary markets that extend product lifecycle value.
China
Shanghai's domestic luxury consumption continues to outpace outbound tourist spending, concentrating demand power in the Yangtze River Delta. The country's dual carbon goals are accelerating material substitution timelines for bio-based alternatives. Beijing's financial services clusters sustain structured tote and satchel demand for daily commuting.
Japan
Tokyo and Osaka favor compact satchel proportions with organized interior compartments, bridging academic and professional aesthetics. Japanese collectors treat resale platforms as primary discovery mechanisms rather than liquidation outlets. The Kanto region's department store concessions maintain relevance through location exclusivity in Ginza and Omotesando.
Luxury Handbag Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a tiered structure where heritage atelier capacity constrains expansion regardless of capital availability. The market consolidates around houses with captive tannery operations and multi-decade collector relationships. Two strategic archetypes dominate: vertically integrated heritage manufactures with in-house leatherworking schools, and design-led houses sourcing through certified Italian tannery networks. Competitive moves center on material substitution R&D partnerships and authentication-enabled recommerce platform integration.
Within the heritage manufacture tier, Chanel and Louis Vuitton exemplify vertical integration archetypes with controlled scarcity in product drops and experiential retail formats. Prada occupies a distinct position through its Re-Nylon initiative and marine plastic sourcing that commands sustainability premiums. Among Italian design houses, Bottega Veneta represents the artisan-limited edition vector with Intrecciato weaving techniques that constrain volume regardless of demand.
| Leading Market Players |
|---|
| Gucci |
| Bottega Veneta |
| Chanel |
| Fendi |
| Saint Laurent |
| Dior |
| Prada |
| Celine |
| Louis Vuitton |
| Others |
Cost & Logistics Intelligence
EU Green Deal traceability mandates gate both qualified supply and premium-tier pricing access, as brands without blockchain-tracked sourcing face exclusion from sustainability-oriented collector segments while compliant competitors command wholesale premiums. REACH Annex XVII conversion costs at Tuscan tanneries compress mid-tier supplier margins and concentrate pricing power among heritage manufactures with captive tannery operations.
Pricing Analysis
Heritage craftsmanship and controlled scarcity anchor value-based pricing, with hand-stitched atelier lines from French manufactures sustaining 40-60% premiums over mechanized equivalents. Price differentiation rests on CITES documentation burden and vegetable-tanning certification grade, with exotic skin products facing extended time-to-market delays that inflate carrying costs. Cost compression in entry-tier synthetic alternatives is intensifying because mycelium leather tensile parity has compressed wholesale premiums from 40% to 15%. Fashion enthusiasts purchasing through digital-native channels exhibit highest price sensitivity, while collectors transacting on authentication-enabled resale platforms demonstrate lowest sensitivity due to vintage scarcity premiums.
Supply Chain Analysis
Single-source vulnerability sits with Australian and African Nile crocodile farms supplying over 70% of legal exotic skins, where climate volatility and CITES Appendix II quota delays cascade through heritage atelier production schedules. Raw material dependencies center on Tuscan vegetable-tanned bovine hides, ECONYL marine plastic feedstock, and mycelium biomass from Bolt Threads and MycoWorks pilot facilities. Supply chain risk hinges on artisan labor scarcity, as French and Italian saddlery schools produce fewer than 200 master leatherworkers annually regardless of capital availability. Distribution runs through vertically integrated brand flagships in Paris, New York, and Tokyo, with Farfetch and Net-a-Porter infrastructure enabling geographic expansion without physical retail investment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The luxury handbag market has become a vertical-integration race, with upstream tannery control and downstream authentication-enabled resale platforms serving as the decisive levers separating margin leaders from design-dependent competitors.
For Market Incumbents: Hedge against mycelium substitution by securing multi-year purchasing agreements with Australian crocodile farms and accelerating Re-Nylon or biofabricated product line expansion. Defensive consolidation should prioritize backward integration into vegetable-tanning capacity at Loire Valley and Santa Croce sull'Arno clusters, while channel control investments in Vestiaire Collective authentication protocols capture resale velocity margins. For New Entrants and Emerging Players: The price-point gap between heritage atelier limited editions and entry-tier synthetic alternatives offers white-space targeting at the 15-25% wholesale premium band where mycelium leather tensile parity now enables compliant positioning. Mumbai and Delhi domestic luxury emergence presents the most penetrable geography given protected space from European import duties. Go-to-market execution should anchor on blockchain-tracked sourcing narratives that satisfy EU Green Deal mandates without legacy compliance burdens. For Investors and Strategic Acquirers: Tuscan tannery consolidation announcements are the leading indicator that REACH Annex XVII conversion costs have eliminated independent mid-tier suppliers, concentrating supply power among consolidated players. Long-term viability over the next decade favors vertically integrated heritage manufactures with captive leatherworking schools and multi-decade collector relationships. Acquisition targeting should prioritize Italian design houses with Intrecciato or equivalent artisan-constrained techniques that limit volume regardless of demand.| Strategic Initiative | Industry Significance |
|---|---|
| Tannery Backward Integration | Captive supply of REACH-compliant vegetable-tanned hides secures EU market access without regulatory risk. |
| Mycelium Product Line Launch | Biofabricated alternatives bypass CITES restrictions while capturing sustainability premiums from California and New York collectors. |
| Recommerce Platform Partnership | Vestiaire Collective authentication protocols extend product lifecycle value and capture margin from resale velocity. |
| Artisan Apprenticeship Expansion | French saddlery school capacity additions address master craftsperson succession gaps constraining atelier line growth. |
| Blockchain Traceability Implementation | EU Green Deal-compliant sourcing disclosure commands premium positioning among sustainability-oriented collectors. |
Research Approach
Multi-period observation of CITES permit issuance volumes, REACH compliance conversion announcements, and resale platform transaction velocity anchored the trend analysis, supplemented by interviews with heritage brand supply chain directors, Tuscan tannery operations managers, luxury boutique category buyers, and authentication technology specialists. Secondary validation drew from customs records of exotic skin imports, Leather Working Group certification databases, EU regulatory filings under ECHA, and collector behavior studies from Vestiaire Collective and The RealReal. Bottom-up segment sizing triangulated against top-down market value estimates.
Input-output matrices modeled demand drivers across product type, material composition, end-user sophistication tier, and distribution channel structure throughout the forecast period. CAGRs were derived from segment-level growth rate distributions weighted by collector demographic expansion patterns and regulatory compliance cost trajectories. Forecast inputs included mycelium leather tensile parity achievement timelines and Chinese domestic consumption concentration indices for Shanghai and Beijing.
Underlying measurement precision varies by segment; mycelium-derived alternatives and recommerce platform volumes carry tighter precision than artisan-limited edition production given documentation standardization. Forecasts reflect assumptions about CITES quota stability and REACH enforcement consistency that could revise materially with regulatory amendments or trade policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Wooden Watch Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
North America Luxury Goods Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
China Luxury Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
Russia Luxury Goods Market