
 India Casino Tourism Market | 2026-2036
India Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
India Casino Tourism Market Foresight
Goa's floating casino fleet and integrated resort pipeline is reconfiguring India's casino tourism infrastructure. Delta Corp leverages its monopoly on offshore gaming vessels to anchor market presence along the Mandovi River. Deltin competes through premium hospitality bundled with gaming floors, while Big Daddy Casino differentiates via entertainment programming and waterfront location control.
India casino tourism encompasses travel experiences centered on legal gambling activities, hospitality accommodation, and ancillary entertainment services, typically operating under state-specific exemptions to national gambling prohibitions. Structural segmentation reveals integrated resorts capturing the highest-margin visitor spend by combining gaming floors with hotel rooms, dining, and event spaces. Domestic tourists dominate volume flows, though VIP players generate disproportionate revenue per visit through high-stakes table games and exclusive packaged services.
State governments in Goa, Sikkim, and Daman administer casino licensing under localized interpretations of the Public Gambling Act, creating fragmented regulatory terrain that operators must navigate facility by facility. The Information Technology Act and pending state-level online gaming rules shape digital extension possibilities for established brands. Stakeholders should monitor pending legislative reviews in Maharashtra and Karnataka, where proposed casino legalization could redistribute regional demand patterns.
Market Dynamics
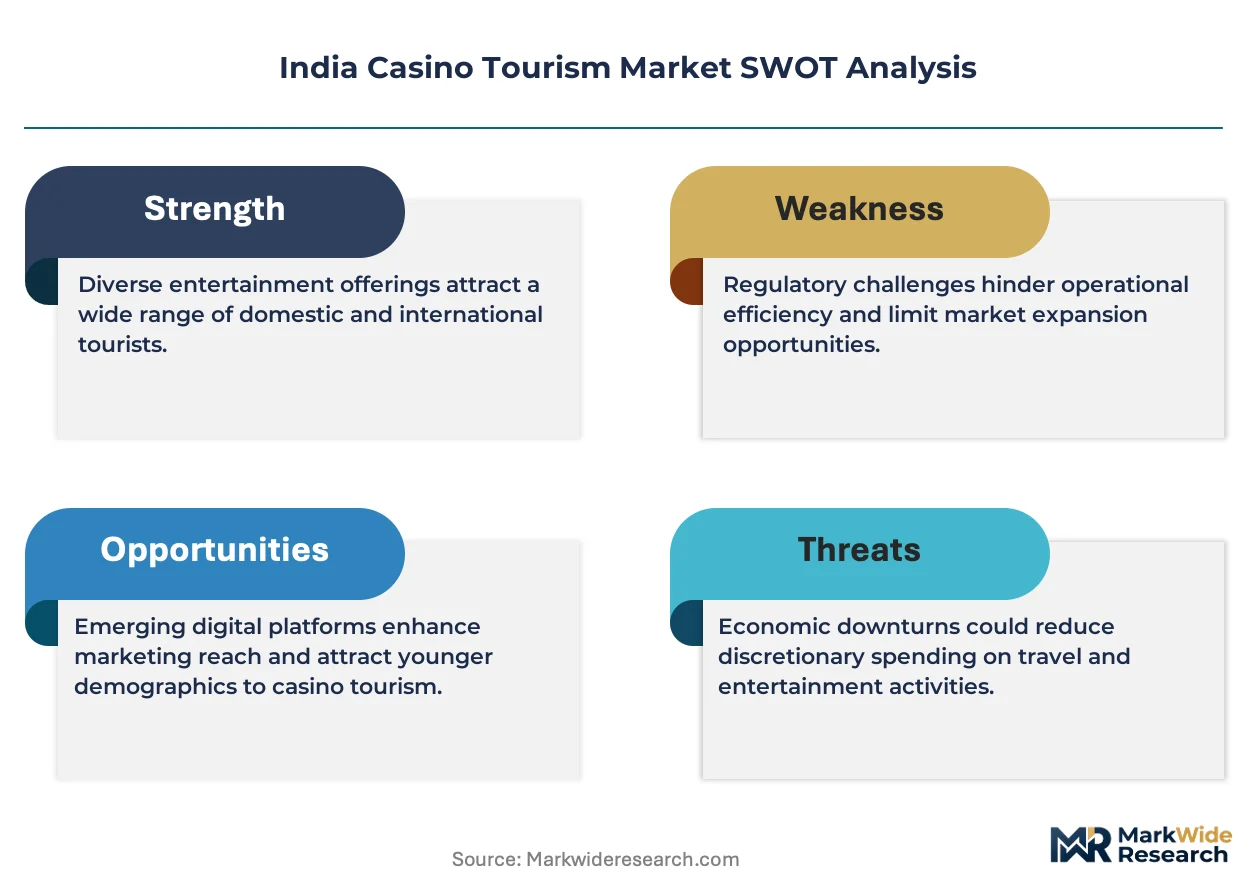
State-level licensing fragmentation under the Public Gambling Act and its amendments creates a bifurcated operating environment where casino tourism concentrates in Goa while other states maintain prohibitions. This regulatory patchwork forces operators to navigate facility-by-facility compliance rather than scale nationally.
Growth Catalysts
- International visitor flows:Foreign tourists seeking luxury gaming experiences represent the fastest-expanding visitor segment, drawn by Goa's floating casino fleet and integrated resort pipeline.
- Public Gambling Act state amendments:Goa, Sikkim, and Daman administer localized licensing exemptions that enable legal casino operations where national prohibitions would otherwise apply.
- Integrated resort development:Hospitality-gaming-entertainment complexes capture higher-margin visitor spend through bundled accommodation, dining, and event services.
Market Restraints
- Geographic concentration risk:Operational casino infrastructure clusters overwhelmingly in Goa, creating vulnerability to localized regulatory changes or infrastructure disruptions.
- Input cost volatility:Floating casino vessels face marine maintenance, fuel, and crew costs that fluctuate with global shipping and energy markets.
- Technical limitation:The absence of uniform national licensing prevents standardized technology platforms and operational protocols across state jurisdictions.
Strategic Opportunities
- Maharashtra legislative review:Pending casino legalization proposals in India's second-most populous state could unlock a major untapped demand pool adjacent to Mumbai's financial center.
- Karnataka regulatory tailwind:Proposed amendments to state gaming laws may permit casino operations, creating a southern hub to complement Goa's western dominance.
- Digital channel convergence:Established casino brands can extend into online gaming under pending state-level rules, leveraging physical presence for digital trust.
Industry Challenges
- Skill scarcity in gaming operations:Qualified dealers, pit managers, and compliance officers require specialized training that Indian hospitality institutes rarely provide.
- Capex intensity of vessel compliance:Offshore casino operators must continuously invest in maritime safety certifications, environmental standards, and passenger capacity upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Casino Tourism Market |
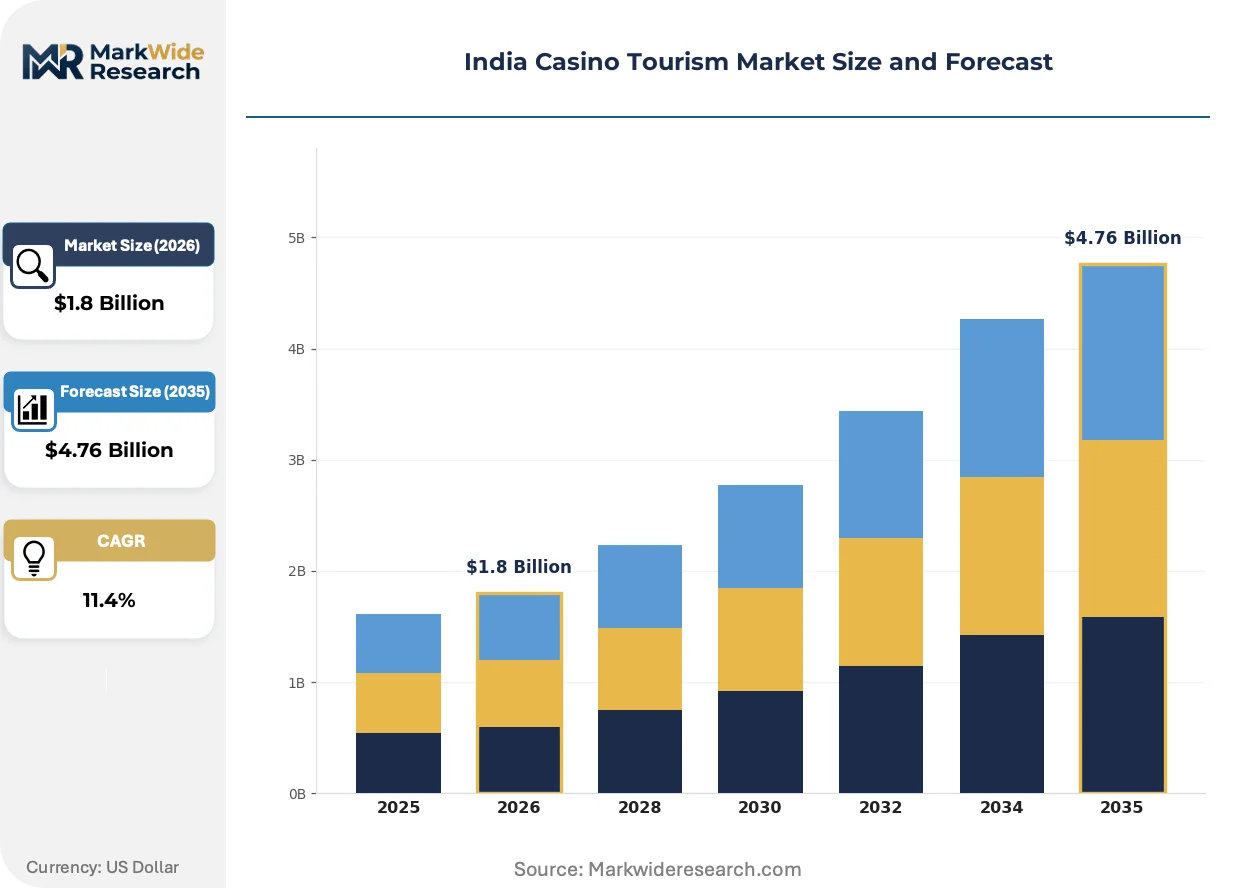
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Integrated Resorts, Standalone Casinos, Riverboat Casinos, Online Gaming Customer Type: Domestic Tourists, International Tourists, VIP Players, Casual Gamblers Service Type: Accommodation, Gaming Facilities, Entertainment Options, Dining Services Event Type: Tournaments, Live Shows, Themed Events, Exclusive Packages |
| Companies Covered | Nazara Technologies, India Travel Tours, Delta Corp, Tripadvisor, Casino Tours, Deltin, Guide India Tour, Big Daddy Casino, Hotel Leela Ventures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Casino Tourism Market Shifts & Advancements
Technology integration is redefining how casino tourism operators engage visitors and manage regulatory compliance. Three interconnected developments are compressing traditional operational models and creating new competitive axes.
Biometric authentication systems are hybridizing physical and digital identity verification across gaming floors. Premium integrated resorts deploy facial recognition and fingerprint-linked player tracking to streamline entry, customize service delivery, and satisfy anti-money laundering requirements. This convergence compresses fraud risk while enabling real-time personalization that loyalty programs alone cannot achieve.
The Information Technology Act and emerging state-level online gaming frameworks are reshaping how established operators extend their brands. Physical casino license holders in Goa and Sikkim now navigate parallel compliance obligations for digital extensions, with regulators scrutinizing whether online platforms maintain the same integrity standards as their terrestrial counterparts. This bifurcation most affects operators seeking to monetize domestic players who cannot access floating vessels.
Visitor expectations now prioritize experience density over pure gaming volume. Domestic tourists and international arrivals alike demand programming that bundles live entertainment, culinary events, and wellness services with table games. Goa's waterfront casinos respond by restructuring floor space allocation and staffing models to accommodate non-gaming revenue centers that command higher per-visitor yields than slot machines alone.
India Casino Tourism Market Segmentation
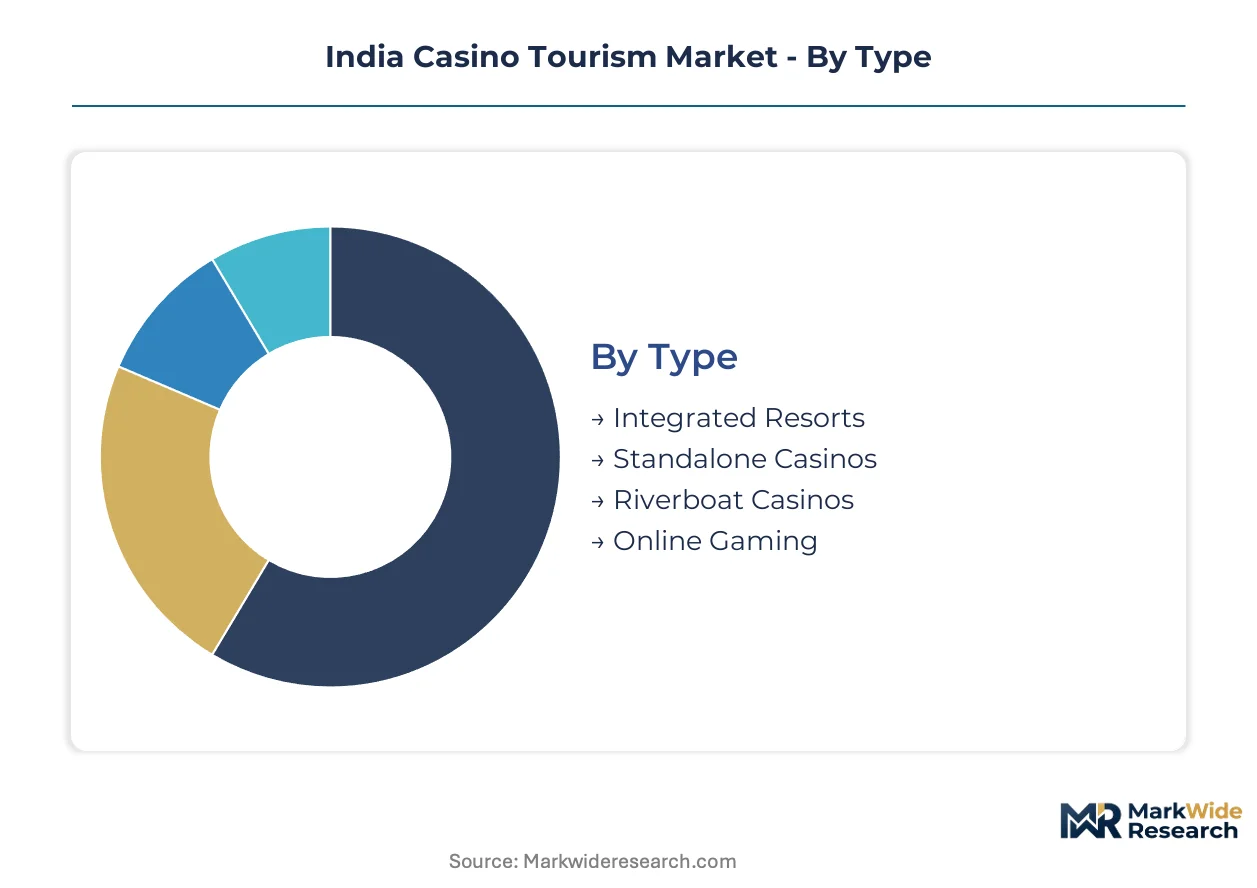
Segmentation in India's casino tourism market reveals how regulatory fragmentation and visitor behavior patterns create distinct operational requirements across facility types and service tiers. Operators must calibrate capital deployment and staffing models differently for each segment given varying license conditions and revenue cycles.
Type:
Revenue velocity varies dramatically across facility types, with floating vessels turning inventory daily while integrated resorts lock in multi-day guest commitments through bundled packages.
- Integrated Resorts:Hospitality-gaming-entertainment complexes combine hotel inventory, convention facilities, and casino floors under single management. Goa's onshore developments along the Mandovi River corridor concentrate demand from high-spend domestic tourists and international visitors seeking extended stays.
- Standalone Casinos:Gaming-focused facilities without captive accommodation rely on walk-in traffic and local patronage. Sikkim's land-based operations in Gangtok serve this model under state-specific Public Gambling Act exemptions, constrained by limited room inventory in surrounding hotels.
- Riverboat Casinos:Offshore gaming vessels anchored in Goa's waterways dominate India's operational casino count. Delta Corp's floating fleet generates revenue through shorter visit durations and higher table turnover rates than land-based alternatives.
- Online Gaming:Digital platforms extend physical casino brands into domestic markets beyond Goa's geographic reach. Regulatory uncertainty under pending state-level Information Technology Act implementations constrains monetization velocity.
Integrated Resorts dominate installed base. Riverboat Casinos are where expansion concentrates.
Customer Type:
Spend concentration follows a steep pyramid, with a narrow VIP tier generating disproportionate revenue against high-volume casual segments.
- Domestic Tourists:Volume leaders from Maharashtra, Gujarat, and Karnataka drive weekday occupancy at Goa's floating casinos. Rail and road connectivity from Mumbai and Pune shapes visitation patterns and peak timing.
- International Tourists:Foreign arrivals seeking luxury gaming experiences represent the fastest-expanding visitor segment, drawn by visa accessibility and Goa's established hospitality infrastructure.
- VIP Players:High-net-worth individuals command dedicated floor space, private gaming salons, and relationship-managed credit facilities. Per-visit spend multiples exceed casual gambler averages by an order of magnitude.
- Casual Gamblers:Entry-level visitors seeking entertainment rather than serious gaming drive slot machine utilization and F&B capture rates. Price-sensitive behavior limits ancillary spend per visit.
VIP Players dominate revenue contribution. International Tourists are where expansion concentrates.
Service Type:
Margin profiles diverge sharply between gaming and non-gaming revenue centers, with accommodation and dining capturing spend that strict gaming facilities forfeit.
- Accommodation:Captive hotel inventory extends visitor duration and enables packaged pricing that obscures gaming margin pressure. Goa's integrated resorts prioritize room construction to anchor multi-night stays.
- Gaming Facilities:Table games and electronic gaming machines generate the core revenue stream but face regulatory caps on capacity and operating hours. State licensing conditions vary floor space allocation rules.
- Entertainment Options:Live performances, nightclubs, and cultural programming attract non-gaming visitors and extend dwell time. Big Daddy Casino differentiates through waterfront event infrastructure.
- Dining Services:Restaurants and banquet facilities command premium pricing from captive resort guests. Celebrity chef partnerships and themed culinary events support rate positioning.
Gaming Facilities dominate revenue mix. Accommodation is where expansion concentrates.
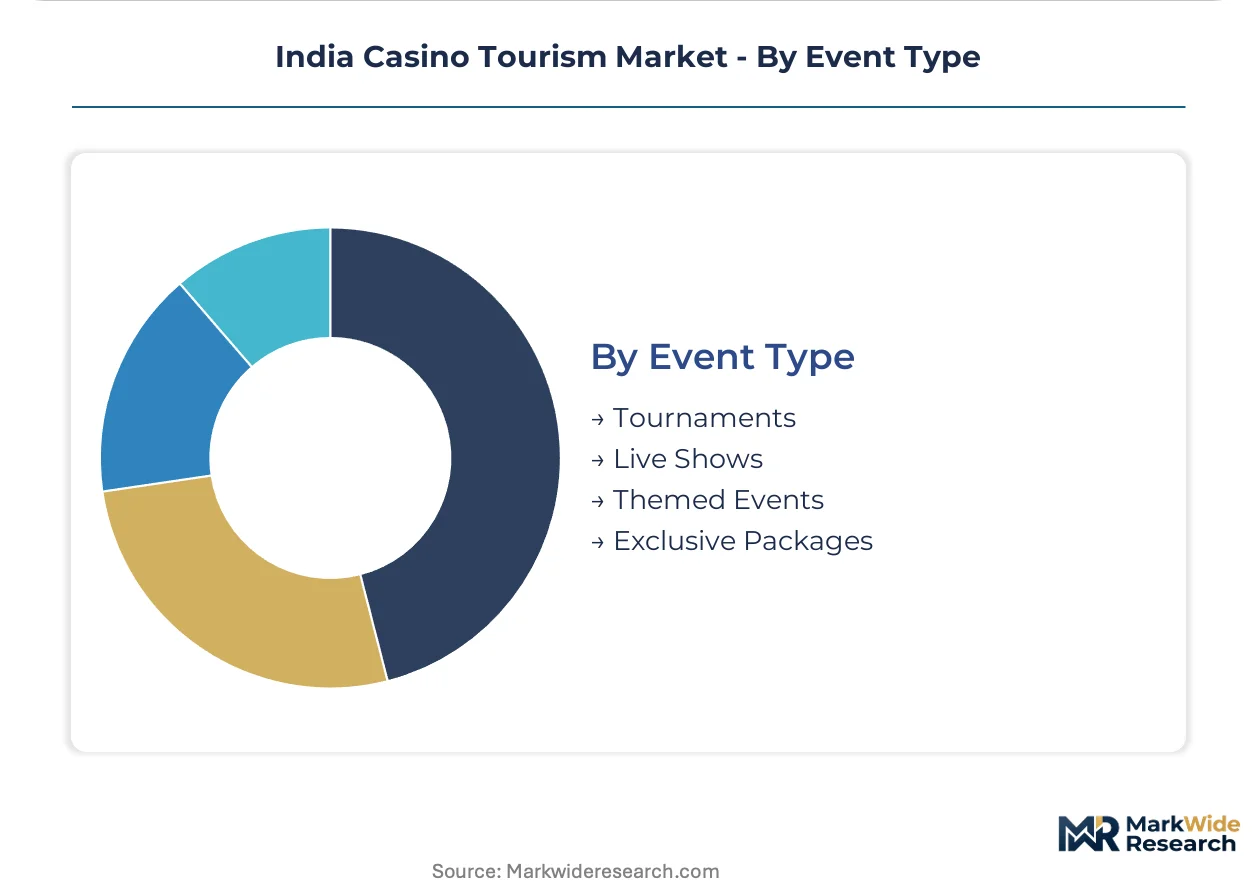
Event Type:
Programming intensity separates premium properties from commodity gaming operations, with tournament and exclusive event calendars driving off-peak utilization.
- Tournaments:Poker and teen patti competitions attract serious players and generate media coverage that supports brand positioning. Entry fees and sponsorships diversify revenue beyond house-edge gaming.
- Live Shows:Musical performances and theatrical productions fill evening programming gaps and attract non-gaming visitors. Production costs scale with performer tier and venue technical specifications.
- Themed Events:Holiday programming and cultural celebrations align with Indian festival calendars to drive visitation spikes. Seasonal decoration and specialized staffing requirements create operational complexity.
- Exclusive Packages:Bundled hospitality-gaming-entertainment offerings target celebration occasions and corporate incentive travel. Customization capabilities separate premium operators from standardized competitors.
Live Shows dominate programming frequency. Tournaments are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mandovi River's floating casino fleet anchors Goa's infrastructure dominance in India's casino tourism landscape. State-level licensing under the Public Gambling Act enables legal operations where national prohibitions otherwise apply.
Goa
Marine vessel infrastructure along the Mandovi River supports India's highest concentration of operational casinos. The state government administers offshore gaming licenses under its Public Gambling Act amendment, permitting floating operations that circumvent federal gambling restrictions. Panaji and the river corridor host Delta Corp's vessel fleet alongside integrated resort developments that bundle hospitality with gaming floors.
Sikkim
Mountain tourism traffic from Gangtok sustains land-based casino operations in India's northeastern periphery. State-level exemptions to the Public Gambling Act allow limited gaming facilities, though room inventory constraints restrict visitor throughput compared to western counterparts. The Gangtok cluster operates under tighter regulatory caps on floor space and operating hours than Goa's marine-based alternatives.
Daman
Coastal location adjacent to Gujarat's industrial corridor positions Daman as a secondary gaming destination. Union territory status enables distinct regulatory treatment under Public Gambling Act interpretations administered by local authorities. The Daman Ganga River zone hosts smaller-scale operations that capture spillover demand from Mumbai and Surat without requiring maritime vessel infrastructure.
Maharashtra
Mumbai's financial center generates latent demand that currently diverts to Goa's floating casinos via rail and road corridors. Pending legislative reviews of casino legalization proposals could unlock domestic demand from India's second-most-populous state. The Maharashtra government has examined regulatory frameworks that would permit integrated resort developments in the Mumbai-Pune corridor.
Karnataka
Bengaluru's technology workforce and international connectivity create a southern demand pool currently underserved by legal gaming infrastructure. Proposed amendments to state gaming laws under legislative consideration may permit casino operations that complement Goa's western dominance. The state government has evaluated licensing models that would attract integrated resort investment to the Bengaluru-Mysuru corridor.
India Casino Tourism Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in India's bifurcated casino tourism structure. The market concentrates around vessel-based and land-based platform operators who bundle hospitality, gaming, and entertainment under single management, while upstream specialists provide tour packaging, technology infrastructure, and ancillary services. Two strategic archetypes dominate: integrated resort operators controlling captive accommodation and gaming floors, and tour aggregators bundling transportation with casino access. Competitive dynamics center on waterfront location control and state licensing access rather than price-based rivalry.
Among vessel-based platform operators, Delta Corp, Deltin, and Big Daddy Casino occupy positions that exemplify the integrated resort archetype. Delta Corp anchors the offshore gaming segment through its monopoly on floating casino vessels along the Mandovi River. Deltin represents premium hospitality bundling with dedicated gaming floors. Big Daddy Casino sits within the entertainment-differentiated tier, leveraging waterfront programming and event infrastructure to extend dwell time beyond pure gaming volume.
| Leading Market Players |
|---|
| Nazara Technologies |
| India Travel Tours |
| Delta Corp |
| Tripadvisor |
| Casino Tours |
| Deltin |
| Guide India Tour |
| Big Daddy Casino |
| Hotel Leela Ventures |
| Others |
Supply & Pricing Matrix
Regulatory chokepoint risk at state licensing authorities determines both pricing tier spreads and supply chain shape across India's casino tourism infrastructure. Operators face fragmented compliance costs that cascade into premium pricing for integrated resort experiences while vessel-based alternatives compete on accessibility.
Pricing Analysis
Volume-discount tiering structures dominate casino tourism pricing, with VIP players accessing relationship-managed credit facilities and bundled hospitality packages unavailable to casual visitors. Three-tier pricing stratifies across premium integrated resorts, mid-tier floating casinos, and economy-focused day-trip vessels. Pricing pressure stems from marine maintenance cost volatility and crew retention challenges in Goa's concentrated vessel market. Casual gamblers exhibit highest price sensitivity, while VIP segments demonstrate inelastic demand for exclusive salon access and personalized service tiers.
Supply Chain Analysis
Tariff exposure between international gaming equipment manufacturers and Indian port infrastructure dominates supply chain risk assessment for casino operators. Gaming hardware concentrates in supply from the United States, Macau, and Singapore, while vessel construction and marine engineering services draw from South Korean and Indian shipyard clusters. Raw material dependencies span specialized casino felt, precision-engineered chips, and electronic gaming machine components. Single-source vulnerability affects biometric authentication system procurement. Distribution runs through state-licensed facility operators who control downstream access to gaming floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's casino tourism market represents high-growth disruption as pending legislative reviews in Maharashtra and Karnataka threaten to fragment Goa's geographic monopoly. The Information Technology Act's evolving state-level implementations create parallel digital extension pathways alongside physical infrastructure expansion.
For Market Incumbents: Harden waterfront location control through extended lease negotiations on Mandovi River anchorages before competing jurisdictions open. Secure maritime engineering talent pools through captive training partnerships with Goa's hospitality institutes. Vertical integration into vessel maintenance capabilities reduces exposure to global shipping cost volatility threatening floating casino margins.
For New Entrants and Emerging Players: Mid-market integrated resort developments in Karnataka's Bengaluru-Mysuru corridor represent the most penetrable entry point pending regulatory authorization. Maharashtra's Mumbai-Pune corridor offers secondary white-space targeting financial services incentive travel demand. Digital platform extensions under pending state online gaming frameworks provide lower-capex market access than vessel or land-based construction.
For Investors and Strategic Acquirers: Boutique hospitality operators holding dormant casino licenses in Sikkim and Daman offer acquisition targets with embedded regulatory permissions. Long-term viability across the analysis window hinges on successful geographic diversification beyond Goa's infrastructure cluster. Monitor Maharashtra legislative committee proceedings as the critical inflection signal for demand redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Resort Development | Captures extended-stay revenue through bundled hospitality-gaming-entertainment packaging in Goa and prospective Maharashtra markets. |
| State Licensing Diversification | Reduces geographic concentration risk by securing operating permissions across multiple Public Gambling Act jurisdictions. |
| Digital Platform Extension | Extends physical casino brand reach into domestic markets beyond Goa's geographic constraints under pending IT Act rules. |
| Vessel Fleet Modernization | Addresses marine maintenance cost pressures through upgraded environmental certification and passenger capacity optimization. |
| VIP Relationship Management | Secures highest-margin revenue tier through dedicated gaming salons and credit facility customization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, state tourism board statistics, and maritime licensing records. Primary interviews engaged casino operations directors, state tourism ministry officials, hospitality procurement managers, and vessel engineering contractors. Secondary validation drew from Public Gambling Act amendments across Goa, Sikkim, and Daman, Information Technology Act draft rules, and SEBI disclosures from listed gaming operators. Bottom-up facility capacity modeling and top-down visitor expenditure estimates were triangulated against official tourism arrival data.
Forecast inputs incorporate facility-type segmentation, customer-tier spending patterns, and service-mix margin profiles across the projection horizon. Segmentation dimensions modeled include integrated resort versus vessel-based versus standalone facilities, domestic versus international versus VIP customer archetypes, and gaming versus accommodation versus entertainment revenue centers. CAGRs were derived from visitor volume trajectories, per-capita expenditure trends, and licensed capacity expansion pipelines. Regulatory scenario analysis and macroeconomic sensitivity overlays inform projection boundaries.
Macroeconomic conditions sit as an overlay; deviation in rupee volatility, international air connectivity recovery, or state fiscal pressures would shift the trajectory. Forecasts reflect assumptions on legislative timelines and licensing throughput that state government deliberations could accelerate or delay. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Italy Culinary Tourism Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market
Destination Management and Attractions
Smart Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market