
 China Smoking Accessories Market | 2026-2036
China Smoking Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
China Smoking Accessories Market Insights
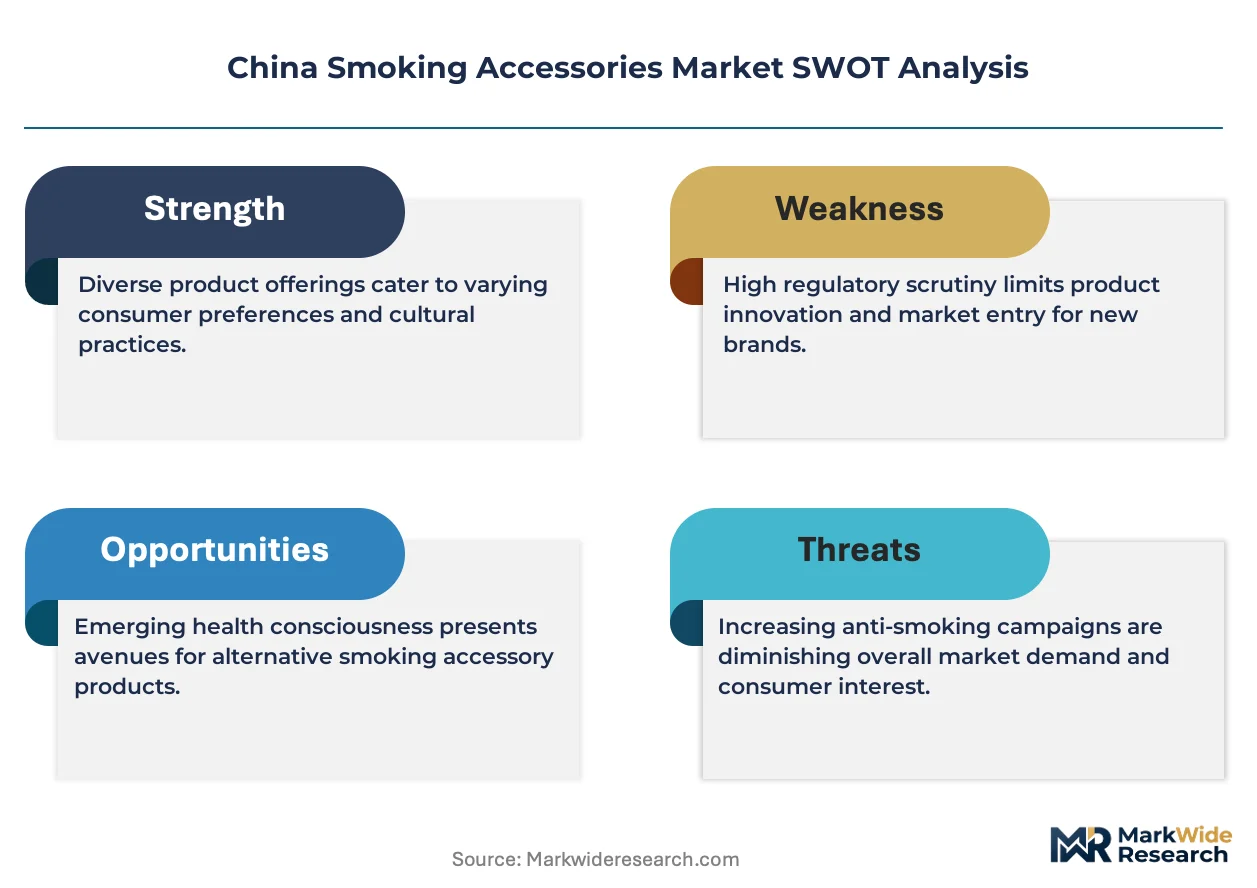
GB standards for tobacco-related product materials is redrawing competitive boundaries in China's smoking accessories sector. Smoore leverages its vertical integration across ceramic heating elements and battery systems to sustain manufacturing scale advantages. HEBEI DINGSHUO GLASSWARE CO.,LTD anchors its position through specialized borosilicate glass production for water pipes and hand-blown accessories. Aspire competes on design differentiation, particularly in refillable tank systems and precision-machined metal components.
China smoking accessories encompass functional and aesthetic implements—including lighters, ashtrays, cigarette holders, rolling papers, and vaporizer hardware—fabricated from metal alloys, borosilicate glass, hardwoods, and engineered polymers to serve combustion, filtration, and concentrate consumption rituals. Metal and glass segments command premium positioning due to durability and thermal performance specifications, while plastic variants occupy mass-market channels through cost-optimized injection molding. Lighters and rolling papers represent mature volume categories with thin margins, whereas custom-designed glassware and portable electronic accessories capture expanding margin pools among design-conscious urban consumers.
SAMR enforces product quality and labeling standards, while MEE oversees environmental compliance in materials processing and waste directives for disposable components. China's dual carbon goals pressure manufacturers toward recyclable metals and reduced plastic content, reshaping material selection across supply chains. The NMPA framework for novel tobacco products creates parallel compliance tracks that bifurcate traditional accessories from electronic device categories. Stakeholders must monitor regulatory alignment between national standards and municipal enforcement patterns in key production zones.
Market Dynamics
GB standards for materials certification and SAMR's expanding product safety mandates are compressing manufacturing timelines while elevating capital requirements for China's smoking accessories producers. These regulatory pressures concentrate competitive advantage among vertically integrated manufacturers with captive laboratory testing capabilities.
Growth Catalysts
- Urban professional demand:Young consumers in Shenzhen and Shanghai drive premium glassware and electronic accessory adoption through design-conscious purchasing.
- Dual carbon goals:China's national emissions targets accelerate recyclable metal substitution for plastic components across supply chains.
- Guangdong cluster effect:Manufacturing concentration around Dongguan and Shenzhen enables rapid prototyping and shortened product development cycles.
Market Restraints
- Lithium battery cost volatility:Electronic accessory margins compress when raw material prices spike, forcing price pass-through delays.
- MEE environmental directives:Waste disposal regulations for disposable components raise compliance costs disproportionately for small-batch producers.
- Ceramic heating element supply:Specialized component sourcing concentrates among limited domestic suppliers, creating bottleneck risks.
Strategic Opportunities
- Tier-2 city penetration:Chengdu and Hangzhou exhibit underdeveloped premium accessory retail infrastructure relative to coastal megacities.
- Cross-category convergence:Precision-machined metal capabilities from consumer electronics transfer into high-end vaporizer housing production.
- NMPA framework alignment:Novel tobacco product regulations create parallel certification tracks that favor manufacturers with existing pharmaceutical-grade cleanroom capacity.
Industry Challenges
- Borosilicate glassblowing talent:Hand-blown specialty production requires master craftsmen whose training cycles exceed five years.
- GB standard compliance timelines:Materials certification testing creates six-to-nine month product launch delays.
- Injection mold retooling:Biodegradable polymer transitions demand capital-intensive equipment replacement for mass-market producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Smoking Accessories Market |
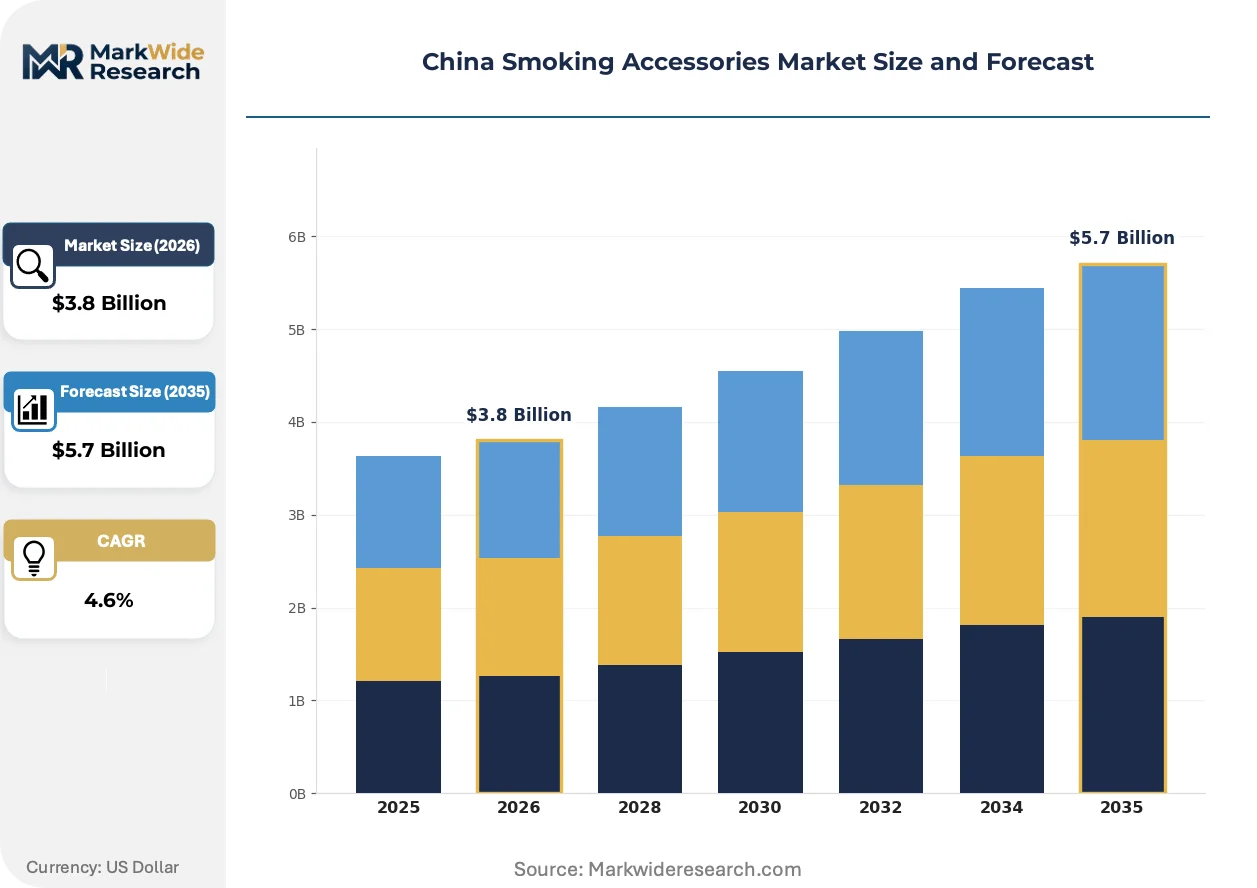
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarette Holders, Lighters, Ashtrays, Rolling Papers Material: Metal, Glass, Wood, Plastic Customer Type: Retail Customers, Wholesalers, Online Buyers, Distributors Design: Custom Designs, Vintage Styles, Modern Aesthetics, Portable Designs |
| Companies Covered | Jinlin (HK) Smoking Accessories Co., Ltd., Smoore, HEBEI DINGSHUO GLASSWARE CO.,LTD, VapeOnly, Innokin, KangerTech, Aspire, China National Tobacco Corporation, China Tobacco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Smoking Accessories Market Trends and Innovations
China's smoking accessories sector is experiencing material science divergence and regulatory segmentation that separate premium from commodity production. These forces reshape competitive positioning across manufacturing tiers.
Ceramic heating technology is bifurcating the electronic accessories segment. Precision-engineered ceramic elements deliver superior thermal consistency for concentrate consumption. High-end manufacturers in Shenzhen adopt these components rapidly, while mass-market producers retain metal coil systems to preserve price positioning.
SAMR's expanded labeling requirements for battery-powered devices compress product launch windows. Manufacturers must submit extended safety documentation before market entry. Electronic accessory categories face the steepest compliance burden, with firms restructuring quality assurance departments to manage documentation workflows.
Direct-to-consumer channels disrupt traditional wholesale distribution for premium glassware. Artisan producers in Hebei province now transact through live-streaming platforms, bypassing layered distributor margins. This pattern concentrates in urban consumer segments where brand storytelling substitutes for physical retail inspection.
China Smoking Accessories Market Segmentation
China's smoking accessories market fragments across four intersecting dimensions that determine pricing power and channel access. Product type and material composition anchor manufacturing strategy, while customer type and design orientation dictate margin capture.
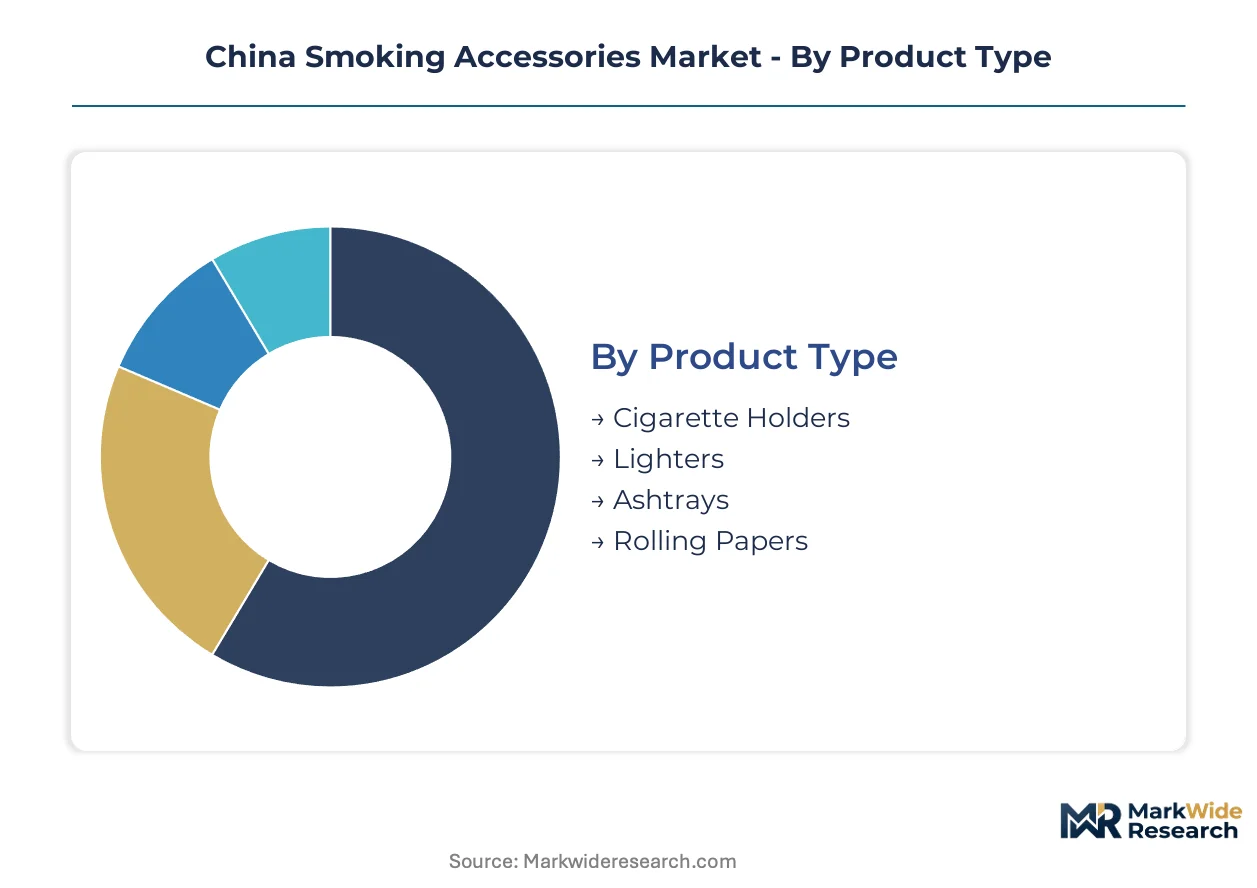
Product Type:
Channel distribution varies sharply by product category—convenience stores and gas stations dominate high-velocity disposable items, while specialty retailers and direct-to-consumer platforms capture premium durable goods.
- Cigarette Holders:Precision-machined metal and filtered variants serve health-conscious urban professionals in Shanghai and Shenzhen. Demand clusters among gift purchasers seeking branded packaging and filtration claims. GB standards for mouthpiece materials elevate compliance costs for importers.
- Lighters:Disposable flint-wheel and electronic ignition systems constitute the highest-volume category with thinnest margins. Manufacturing concentrates in Wenzhou's metalworking clusters where automated assembly lines achieve unit economics below one RMB.
- Ashtrays:Borosilicate glass and ceramic variants command premium positioning through thermal shock resistance. Hotel and hospitality procurement in Guangzhou and Beijing drives commercial-grade specification demand.
- Rolling Papers:Unbleached hemp and rice paper formulations attract younger consumers through natural positioning. E-commerce platforms capture the fastest expansion in this segment, bypassing traditional tobacco retail licensing constraints.
Lighters dominate installed base. Rolling papers are where expansion concentrates.
Material:
Cost tier stratification separates commodity plastics from engineered materials requiring specialized fabrication equipment and extended supplier qualification.
- Metal:Zinc alloys and stainless steel deliver durability for daily-carry accessories. Shenzhen's CNC machining ecosystem enables rapid prototyping of precision components for vaporizer housings and grinder mechanisms.
- Glass:Hand-blown borosilicate commands the highest artisan premiums. Hebei province's glassblowing heritage supports custom water pipe production with lead times exceeding standard manufacturing by 400 percent.
- Wood:Hardwood dugouts and hand-carved pipes occupy niche positioning. Sustainability certification requirements under MEE directives are reshaping raw material sourcing from domestic forests.
- Plastic:Injection-molded acrylics and ABS serve mass-market price points. Dual carbon goals are accelerating biodegradable polymer transitions that demand capital-intensive mold retooling.
Plastic holds volume leadership. Glass is climbing the fastest on margin contribution.
Customer Type:
Procurement patterns diverge between volume-driven wholesale channels and relationship-intensive retail distribution requiring inventory financing and merchandising support.
- Retail Customers:Individual purchasers through brick-and-mortar tobacconists and convenience stores. Transaction sizes remain small but brand loyalty generates repeat purchase economics.
- Wholesalers:Regional distributors aggregating volume for secondary market penetration. Payment terms and inventory risk allocation define competitive positioning in this tier.
- Online Buyers:Direct-to-consumer demand through Tmall, JD.com, and live-streaming platforms. Social commerce enables artisan glassblowers in Hebei to bypass traditional distributor margins entirely.
- Distributors:National-level partners managing SAMR compliance documentation and logistics for multi-province coverage. Regulatory complexity elevates barriers to entry for new channel participants.
Wholesalers dominate throughput volume. Online buyers are gaining share fastest.
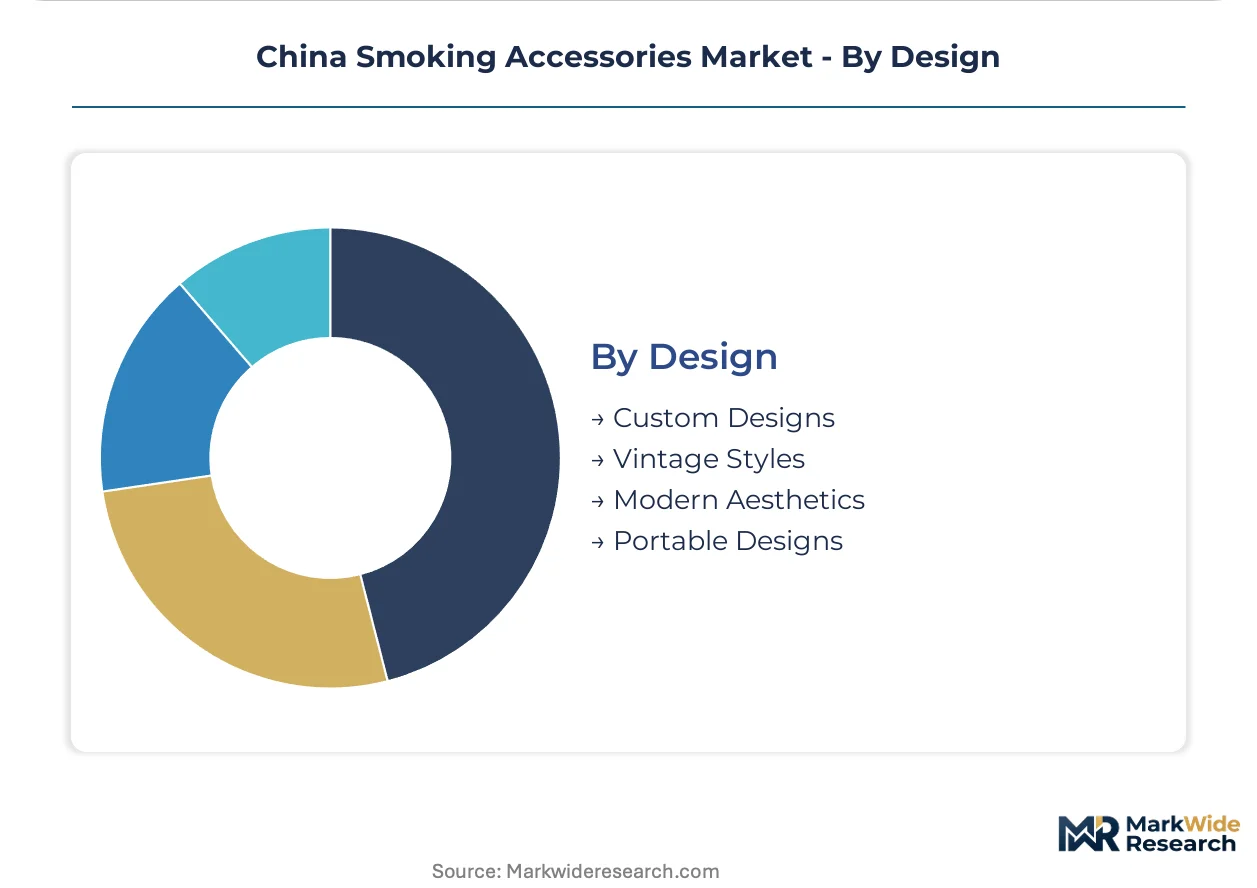
Design:
Aesthetic differentiation separates mass-market commoditized production from collectible positioning that supports price premiums independent of functional performance.
- Custom Designs:Bespoke engraving, color matching, and collaborative artist editions. Corporate gifting in Beijing and Shanghai drives seasonal demand spikes for personalized production runs.
- Vintage Styles:Art Deco and mid-century reproductions targeting collector demographics. Antique brass finishes and mother-of-pearl inlay require specialized finishing capabilities concentrated in Guangdong.
- Modern Aesthetics:Minimalist geometric forms and matte surface treatments. Young urban professionals in Chengdu and Hangzhou demonstrate willingness-to-pay premiums for design-forward accessories.
- Portable Designs:Collapsible and keychain-integrated formats optimized for travel and discretion. Compact dimensions prioritize engineering miniaturization over material prestige.
Modern aesthetics command the steepest expansion trajectory. Portable designs anchor volume penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and GB standards for materials certification are redrawing manufacturing requirements across provincial clusters. Regional demand concentrates in coastal manufacturing belts where regulatory enforcement and export infrastructure intersect.
Guangdong Province
Shenzhen's electronics ecosystem drives precision-machined metal component demand for vaporizer housings. SAMR product safety mandates compress launch timelines for battery-powered devices. Dongguan's injection molding clusters pivot toward biodegradable polymers under MEE environmental directives.
Jiangsu Province
Shanghai's urban professional base sustains premium glassware and design-forward accessory consumption. Dual carbon targets accelerate recyclable metal substitution in nearby Suzhou manufacturing zones. Nanjing's logistics hub enables rapid distribution to interior provinces.
Zhejiang Province
Hangzhou's e-commerce infrastructure supports direct-to-consumer channels for artisan producers. Young consumers in the city demonstrate willingness-to-pay premiums for modern aesthetic designs. Wenzhou's metalworking heritage anchors automated lighter assembly at sub-one-RMB unit economics.
Hebei Province
Beijing's corporate gifting culture drives seasonal demand for custom-engraved accessories and branded packaging. MEE forestry compliance reshapes hardwood sourcing for hand-carved pipe production. Hand-blown borosilicate glassblowing in provincial craft clusters faces five-year master craftsman training cycles.
Sichuan Province
Chengdu's underdeveloped premium accessory retail infrastructure presents whitespace for tier-2 city penetration. Chongqing's manufacturing cost base attracts mass-market plastic component producers. Provincial demand for portable designs rises among travel-oriented consumer segments.
China Smoking Accessories Market Competitive Landscape
Player mix skews toward vertically integrated electronics specialists and regional glassware craft clusters. The vendor base separates into three tiers: multinational component suppliers with captive laboratory testing, provincial artisan collectives leveraging live-streaming distribution, and mass-market injection molders serving convenience retail channels. Dominant competitive moves include backward integration into ceramic heating element supply and geographic expansion into tier-2 city retail infrastructure.
Among Guangdong-based electronics fabricators, Smoore and Aspire exemplify the vertically integrated archetype with in-house production of battery systems and precision-machined housings. HEBEI DINGSHUO GLASSWARE CO.,LTD anchors the artisan-craft tier, representing specialized borosilicate production capabilities concentrated in northern provincial clusters. These three entities occupy positions that map directly onto the regulatory bifurcation between electronic device categories and traditional combustion accessories under China's NMPA framework.
| Leading Market Players |
|---|
| Jinlin (HK) Smoking Accessories Co., Ltd. |
| Smoore |
| HEBEI DINGSHUO GLASSWARE CO.,LTD |
| VapeOnly |
| Innokin |
| KangerTech |
| Aspire |
| China National Tobacco Corporation |
| China Tobacco |
| Others |
Pricing and Supply Chain Analysis
Six-to-nine month GB materials certification timelines compress inventory turns for new product introductions while concentrating pricing power among vertically integrated manufacturers with captive laboratory testing capabilities in Guangdong and Hebei provinces.
Pricing Analysis
Certification level creates the primary spread across China's smoking accessories sector, with NMPA-aligned pharmaceutical-grade cleanroom production commanding premiums over standard GB-compliant output. Three-tier pricing structure across premium, standard, and economy levels separates hand-blown borosilicate glassware from precision-machined metal components and mass-market injection-molded plastics. Cost compression in the electronic accessories tier is intensifying because lithium battery raw material volatility forces delayed price pass-through. Convenience store purchasers of disposable lighters exhibit highest price sensitivity, while corporate gifting segments in Beijing and Shanghai demonstrate lowest elasticity for custom-engraved artisan pieces.
Supply Chain Analysis
China anchors global smoking accessories manufacturing, with South Korea supplying specialized ceramic heating elements and Japan providing precision battery management systems. Domestic production draws from lithium carbonate deposits, borosilicate glass feedstock, and engineered polymer resins. Single-source vulnerability concentrates in ceramic heating element supply, where limited domestic suppliers create bottleneck exposure for electronic device manufacturers. Distribution runs through layered wholesale networks for mass-market channels, while direct-to-consumer live-streaming platforms capture growing share of premium glassware transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's smoking accessories sector sits in early-cycle expansion, with tier-2 city premium retail infrastructure penetration representing substantial runway ahead of saturation.
For Market Incumbents: Shield market position by deepening backward integration into ceramic heating element supply to offset single-source dependency risks from limited domestic suppliers. Accelerate certification investment for NMPA-aligned cleanroom capacity to capture parallel regulatory track premiums before compliance timelines compress further. For New Entrants and Emerging Players: Artisan glassblower direct-to-consumer service layers present whitespace where incumbent distributors under-serve design-conscious urban professionals. Target Chengdu and Hangzhou for premium retail infrastructure buildout, leveraging live-streaming platform go-to-market angles that bypass traditional wholesale margin stacking. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and certification timelines disproportionately burden small-batch producers, creating acquisition targets among Hebei glassware craft clusters and Wenzhou metalworking operations. Watch ceramic heating element supply capacity expansion as the inflection signal for electronic accessories margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Heating Elements | Captive supply of specialized components reduces NMPA compliance timeline exposure for Shenzhen electronics fabricators. |
| Direct-to-Consumer Live-Streaming Launch | Hebei artisan glassblowers bypass distributor margins through Tmall and Douyin platform storefronts. |
| Pharmaceutical-Grade Cleanroom Certification | NMPA framework alignment opens parallel revenue tracks for battery-powered device manufacturers. |
| Biodegradable Polymer Mold Retooling | MEE environmental directive compliance secures mass-market channel access for Dongguan injection molders. |
| Tier-2 City Retail Infrastructure Expansion | Chengdu and Hangzhou whitespace capture builds premium brand positioning ahead of coastal saturation. |
Research Methodology
Operator-level perspectives from manufacturing plant managers, procurement leads at downstream distributors, SAMR compliance officers, and e-commerce platform category directors anchored the qualitative base. Primary fieldwork combined with secondary validation from customs export records, SAMR product registration databases, NMPA novel tobacco product filings, and provincial manufacturing cluster economic reports. Bottom-up production volume estimates and top-down consumption expenditure patterns were triangulated to establish market sizing.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios and raw material cost trajectories. Segmentation modeling incorporated product type, material composition, customer channel, and design orientation dimensions across the analysis window. CAGRs were derived from trend extrapolation of historical production volumes adjusted for policy intervention effects, with specific inputs including GB standard implementation timelines and dual carbon goal compliance trajectories.
Forecasts assume regulatory continuity in SAMR product safety mandates and MEE environmental directives; material policy shifts would require re-modeling. Specific risks that could revise projections include ceramic heating element supply disruptions, lithium battery cost spikes, and municipal enforcement pattern variations in key production zones. Recalibration cycles align with material shifts in national standards publication and provincial dual carbon implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Pod Vape Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
China Smoking Pipe Market