
 North America Smoking Pipe Market | 2026-2036
North America Smoking Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smoking Pipe Market Insights
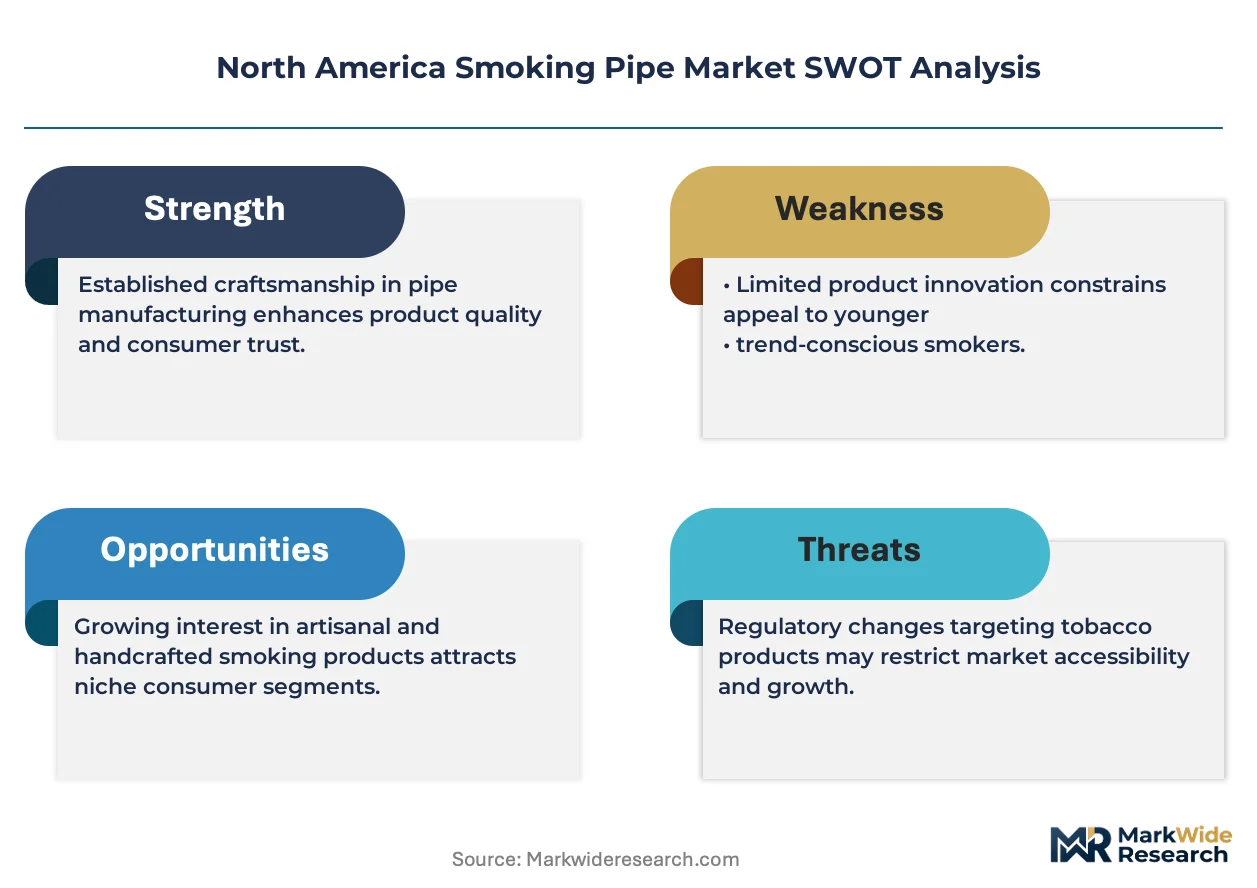
Artisan briar carving expertise is redrawing competitive boundaries across the North America Smoking Pipe Market. Missouri Meerschaum Company leverages its Missouri-based corncob specialization to dominate the accessible segment. Peterson Pipes anchors its position through Dublin-crafted heritage designs with strong distribution in Canadian specialty stores. Savinelli Pipes competes on Italian design heritage translated for North American collector tastes.
A smoking pipe is a handheld device with a bowl for combusting tobacco and a stem for drawing smoke, typically constructed from briar root, meerschaum, corn cob, or heat-resistant glass with draft-hole diameters ranging from 4mm to 6mm. Its commercial purpose centers on delivering controlled, cooled smoke for personal consumption while serving as a craft object and status symbol. Wood pipes occupy the premium margin pool among product types, sustained by aging briar stock scarcity and hand-finish labor intensity. Glass pipes represent the fastest-growing use case segment for recreational applications, driven by water-pipe crossover demand and visual artistry appeal.
The FDA Center for Tobacco Products regulates pipe tobacco labeling and marketing, constraining how manufacturers communicate with enthusiasts. State attorneys general in California and New York enforce additional point-of-sale restrictions that fragment retail access. The Consumer Product Safety Commission monitors lead content in imported finishes, shaping supplier qualification requirements. Stakeholders must monitor municipal smoke shop licensing trends and craft guild apprenticeship programs to anticipate supply elasticity and regulatory arbitrage opportunities.
Market Dynamics
The North America Smoking Pipe Market operates under acute supply inelasticity where trained briar carver scarcity constrains output expansion despite sustained collector demand. This artisan bottleneck shapes pricing power, regional distribution patterns, and competitive positioning across all market tiers.
Growth Catalysts
- Heritage Club Networks:Southeastern United States pipe clubs and regional tobacco festivals sustain enthusiast culture, generating recurring demand for limited-edition artisan releases.
- Flavor Ban Redirect:California and Massachusetts state-level tobacco flavor prohibitions push consumers toward unflavored premium briar pipes as the primary consumption vehicle.
- Crossover Glass Demand:Water-pipe recreational users migrate toward artisan glass smoking pipes, expanding the addressable collector base beyond traditional tobacco enthusiasts.
Market Restraints
- Aging Briar Scarcity:Mediterranean briar root stock requires decades to mature, limiting raw material availability and inflating input costs for premium wood pipe manufacturers.
- FDA Labeling Constraints:The FDA Center for Tobacco Products restricts how pipe tobacco and accessory manufacturers communicate product attributes, compressing marketing effectiveness.
- Heat-Resistant Glass Import Dependence:Domestic glass pipe producers rely heavily on foreign-sourced borosilicate tubing, exposing margins to tariff volatility and supply disruption.
Strategic Opportunities
- Apprenticeship Pipeline Expansion:Craft guild structured training programs in North Carolina and Virginia could alleviate carver scarcity and scale artisan output over a ten-year horizon.
- Canadian Specialty Retail:Underpenetrated distribution in Ontario and British Columbia specialty tobacconists offers expansion headroom for heritage European pipe brands.
- Visual Artistry Positioning:Collector demand for display-worthy glass pieces enables premium pricing for pipes emphasizing sculptural technique over pure functionality.
Industry Challenges
- Lead Finish Compliance:The Consumer Product Safety Commission monitors imported pipe finishes, requiring extensive supplier qualification that extends procurement timelines.
- Municipal Licensing Arbitrage:Fragmented smoke shop licensing across city and county jurisdictions creates operational complexity for multi-location retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smoking Pipe Market |
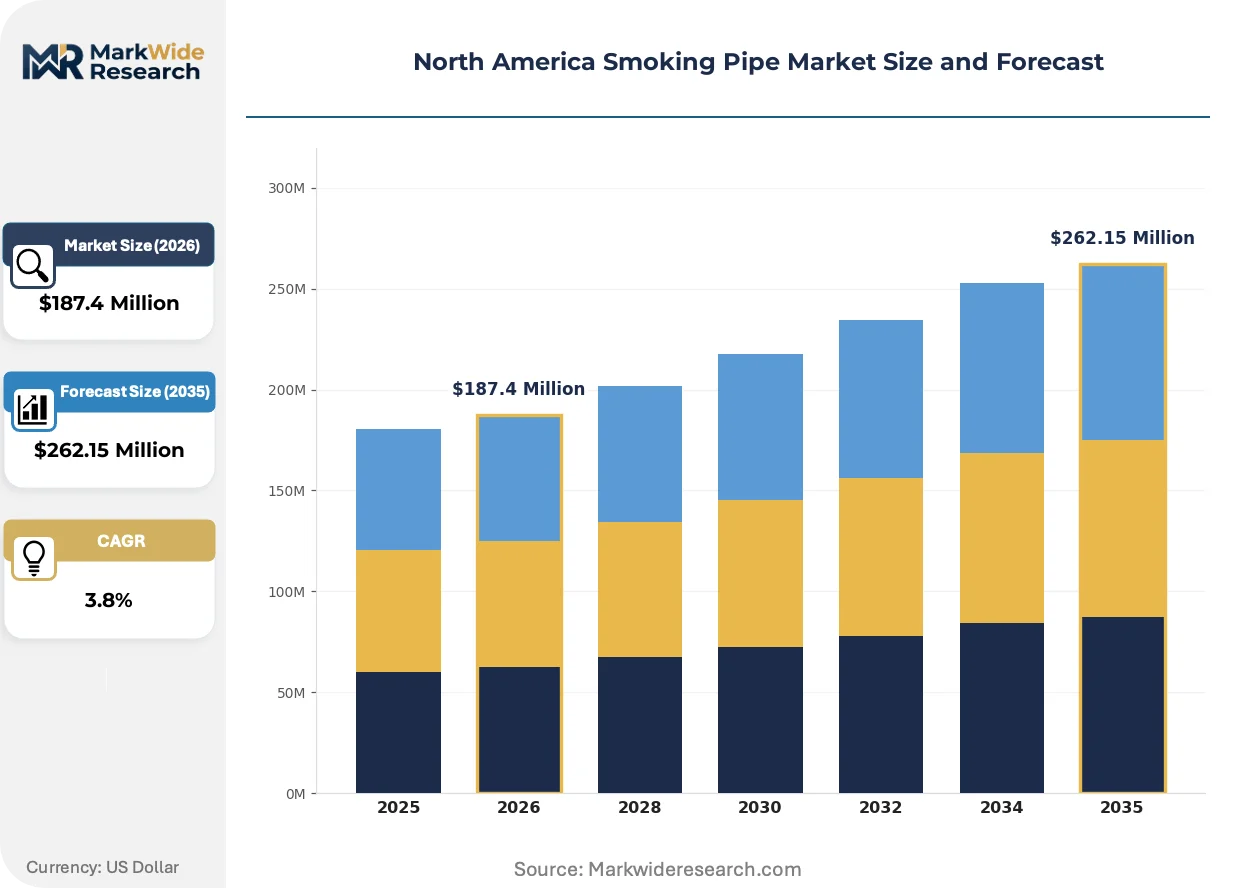
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Pipes, Glass Pipes, Metal Pipes, Ceramics Use Case: Recreational Use, Collectible Items, Novelty Use, Therapeutic Use Distribution Channel: Online Retail, Specialty Stores, Smoke Shops, Convenience Stores Customer Type: Casual Users, Enthusiasts, Collectors, Gift Buyers |
| Companies Covered | Missouri Meerschaum Company, Peterson Pipes, Savinelli Pipes, Brigham Pipes, Kirsten Pipe Co., S. M. Frank, Nording Pipes, Vauen, Brigham Enterprises Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smoking Pipe Market Trends and Innovations
Digital craft marketplaces and direct-to-collector channels are compressing traditional wholesale hierarchies. Artisan pipe makers now cultivate personal followings through social documentation of their carving process, bypassing legacy distribution gatekeepers.
Laser-assisted briar chamber engineering is fragmenting quality consistency across price tiers. High-end carvers adopt CNC-guided draft-hole precision to guarantee airflow standards, while mid-market producers leverage the same tooling to simulate hand-finish irregularities. Collector buyers increasingly distinguish authentic hand-carved pieces from machined-core products through microscopic grain pattern analysis.
The FDA Deeming Rule extension to pipe tobacco accessories is reshaping product classification and marketing compliance. Manufacturers must navigate substantial equivalence pathways for new bowl designs and stem configurations, extending product development cycles. Canadian retailers face parallel Health Canada notification requirements, creating a harmonized North American regulatory threshold that favors established players with dedicated compliance infrastructure.
Collector procurement patterns are rotating toward commission-based bespoke acquisition. Enthusiasts bypass inventory purchases to secure personalized pieces from named carvers with documented provenance. This behavior concentrates demand among reputation-established artisans and compresses turnover for undifferentiated production pipes, particularly visible at regional shows in Tennessee and Pennsylvania.
North America Smoking Pipe Market Segmentation
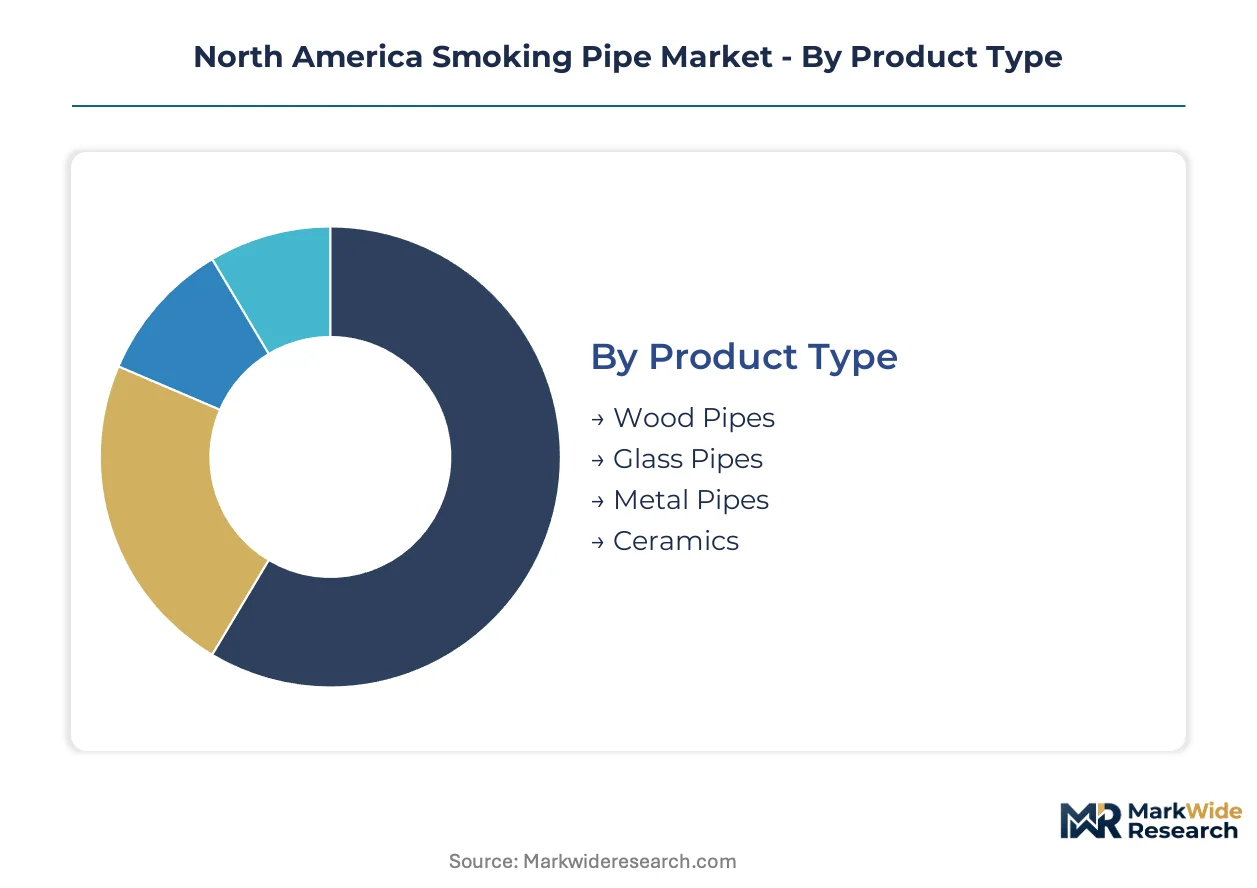
Segmentation in the North America Smoking Pipe Market reveals how artisan scarcity, regulatory fragmentation, and collector culture reshape channel economics. Understanding these divides exposes where margin pools concentrate and which customer cohorts sustain pricing power.
Product Type:
Channel mix varies sharply by material: wood pipes flow through specialty tobacconists and direct carver commissions, while glass pipes dominate smoke shop and online recreational channels.
- Wood Pipes:Crafted from Mediterranean briar root aged 50-100 years, with hand-finished bowls and precision-drilled draft holes. Demand concentrates in the southeastern United States where heritage pipe clubs sustain commissioned acquisition from named carvers, constrained by aging briar scarcity and trained artisan bottlenecks.
- Glass Pipes:Fabricated from borosilicate tubing using lampworking techniques, emphasizing visual artistry and water-pipe compatibility. Expansion concentrates among recreational users in California and Massachusetts where flavor bans redirect consumption toward unflavored premium consumption vehicles, though import dependence on foreign tubing exposes margins to tariff volatility.
- Metal Pipes:Machined aluminum or brass designs prioritizing durability and portability for casual outdoor use.
- Ceramics:Kiln-fired clay bodies offering heat retention and customizable glazing for novelty and gift applications.
Wood Pipes dominate installed base value. Glass Pipes is where expansion concentrates fastest.
Use Case:
Cost tier stratification separates commoditized novelty items from investment-grade collectibles, with therapeutic applications commanding regulatory compliance premiums.
- Recreational Use:Functional consumption emphasizing smoke cooling and draw resistance, spanning water-pipe crossover glass and portable metal designs. Volume concentrates in smoke shop channels across Texas and Florida where municipal licensing arbitrage creates distribution complexity, driven by visual artistry demand and social documentation of consumption rituals.
- Collectible Items:Investment-grade pieces from documented carvers with provenance certificates and limited-edition releases. Demand concentrates at Tennessee and Pennsylvania regional shows where enthusiasts commission bespoke acquisition directly from reputation-established artisans, bypassing traditional wholesale hierarchies.
- Novelty Use:Themed designs and gift-oriented packaging targeting occasional purchasers through convenience retail.
- Therapeutic Use:Medical cannabis compatibility and precise dosing features requiring Health Canada notification and FDA substantial equivalence pathways.
Collectible Items anchor margin pools. Recreational Use captures volume expansion.
Distribution Channel:
Customer type alignment determines channel viability: enthusiasts demand tactile evaluation while casual users prioritize accessibility.
- Online Retail:Digital craft marketplaces and direct-to-collector platforms compressing traditional wholesale hierarchies, with social documentation of carving processes cultivating personal artisan followings. Growth concentrates in commission-based bespoke acquisition where enthusiasts secure personalized pieces from named carvers, enabled by microscopic grain pattern authentication tools.
- Specialty Stores:Curated inventory with trained staff guidance, dominant in Canadian Ontario and British Columbia markets where underpenetrated distribution offers European heritage brand expansion headroom.
- Smoke Shops:Volume-oriented retail fragmented across city and county licensing jurisdictions, creating operational complexity for multi-location operators.
- Convenience Stores:Impulse-accessible metal and ceramic novelty items with minimal staff expertise requirements.
Specialty Stores dominate wood pipe transactions. Online Retail is climbing fastest for glass and commissioned pieces.
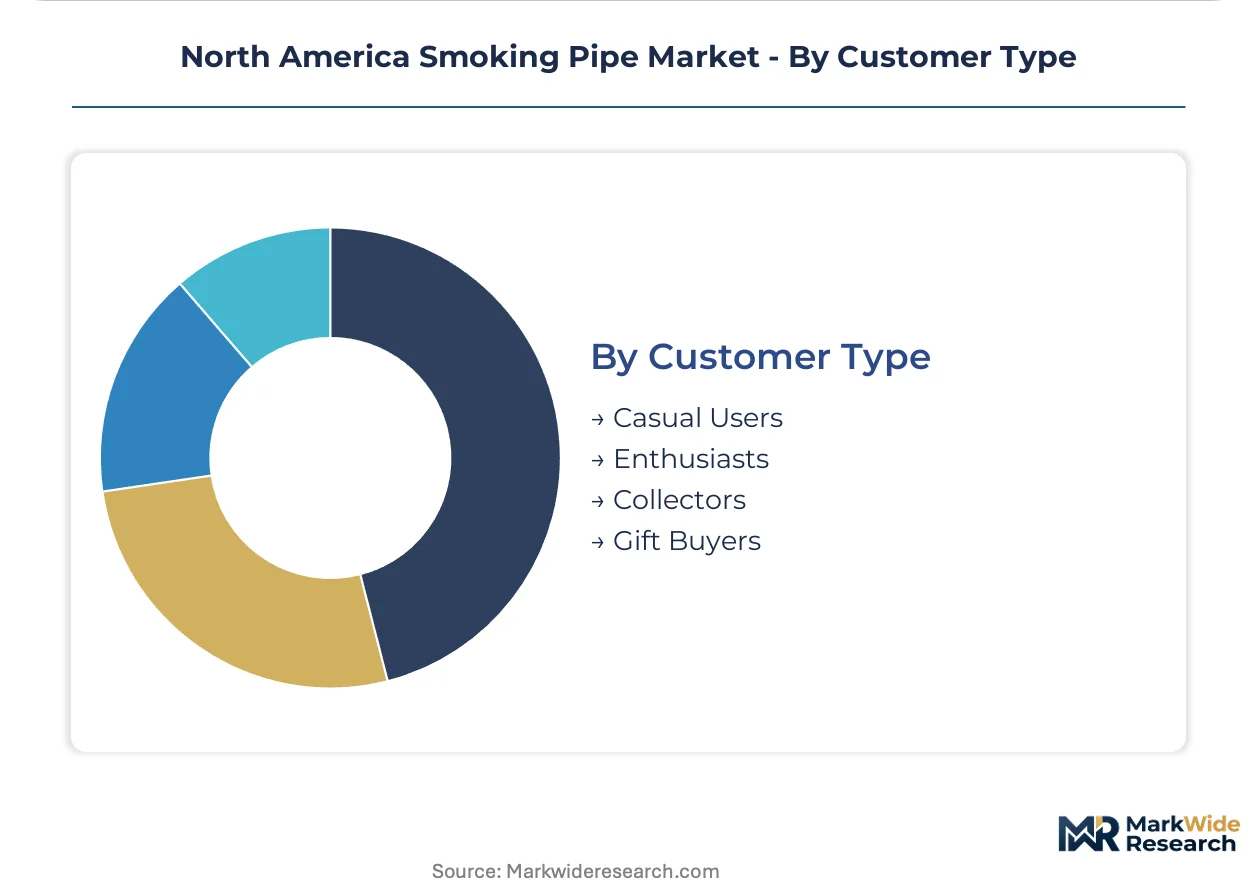
Customer Type:
Supply concentration among reputation-established artisans privileges collector and enthusiast segments with allocation priority.
- Enthusiasts:Repeat purchasers with technical knowledge of draft-hole geometry, chamber engineering, and briar grain evaluation. Demand concentrates in North Carolina and Virginia where craft guild apprenticeship programs could alleviate carver scarcity over extended horizons, sustained by regional tobacco festival culture.
- Collectors:Investment-oriented buyers seeking documented provenance and limited production runs from named artisans. Acquisition concentrates through direct commission bypassing inventory purchases, compressing turnover for undifferentiated production pipes and concentrating demand among established carvers.
- Casual Users:Functionally motivated purchasers prioritizing accessibility and durability over craftsmanship heritage.
- Gift Buyers:Occasional purchasers responding to seasonal demand with novelty and ceramic price-point accessibility.
Enthusiasts sustain recurring artisan demand. Collectors command allocation priority from scarce carver supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA Center for Tobacco Products anchors regulatory oversight across the United States, the dominant geography in this market. State-level attorneys general in California and Massachusetts enforce flavor prohibitions that redirect consumer preferences toward unflavored premium briar pipes.
United States
Heritage pipe clubs in North Carolina and Virginia sustain commissioned demand from named carvers, while Tennessee and Pennsylvania host regional tobacco festivals that concentrate collector acquisition. The FDA Deeming Rule extension to pipe tobacco accessories requires substantial equivalence pathways for new bowl designs. Digital craft marketplaces in the Southeast enable direct-to-collector channels that compress traditional wholesale hierarchies.
Canada
Ontario and British Columbia specialty tobacconists offer underpenetrated distribution headroom for heritage European pipe brands. Health Canada notification requirements for pipe tobacco accessories create parallel compliance thresholds with FDA regulations. Montreal and Vancouver clusters concentrate enthusiast demand for documented provenance pieces from reputation-established artisans.
Mexico
Mexico City Metro and Guadalajara metropolitan areas show emerging collector interest in artisan glass pipes for recreational applications. The country's national consumer protection regulator monitors imported product safety standards for finishes and materials. Northern border states experience cross-border demand dynamics from Texas and California consumer bases seeking tariff-advantaged procurement.
North America Smoking Pipe Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Missouri Meerschaum Company anchoring the accessible corncob segment through Missouri-based specialization. Peterson Pipes and Savinelli Pipes occupy the heritage European import tier with Dublin and Italian design lineages respectively. The market fragments across material-based specialization—briar carvers, glass lampworkers, and metal fabricators—each with distinct supply constraints and customer relationships. Competitive moves center on apprenticeship pipeline development to alleviate carver scarcity and direct-to-collector digital channel cultivation to bypass legacy distribution.
Within the heritage European tier, Peterson Pipes and Savinelli Pipes exemplify how transatlantic design lineage translates into North American collector positioning. Missouri Meerschaum Company occupies a distinct archetype as a geographically anchored domestic specialist with century-scale corncob craftsmanship heritage. Brigham Enterprises Inc. represents the Canadian fabrication segment with Ontario-based production serving cross-border specialty retail channels. These three anchors illustrate how geographic origin and material specialization stratify competitive boundaries across price tiers and customer acquisition modes.
| Leading Market Players |
|---|
| Missouri Meerschaum Company |
| Peterson Pipes |
| Savinelli Pipes |
| Brigham Pipes |
| Kirsten Pipe Co. |
| S. M. Frank |
| Nording Pipes |
| Vauen |
| Brigham Enterprises Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day Mediterranean briar curing cycles concentrate pricing power among established carvers with aged stockpiles, while glass pipe producers face compressed margins from foreign tubing import dependencies. This lead-time asymmetry between wood and glass segments stratifies margin capture across material tiers.
Pricing Analysis
Geographic price spreads separate southeastern United States heritage club commissions from California smoke shop retail, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on documented carver provenance and Health Canada notification status. Pricing pressure stems from FDA labeling constraints compressing marketing effectiveness for new entrants. Collectors show minimal price sensitivity; casual users in convenience channels exhibit acute elasticity.
Supply Chain Analysis
Italy and France anchor Mediterranean briar root harvesting, while China and India dominate borosilicate tubing fabrication for glass segments. Raw material dependencies include fifty-to-hundred-year aged briar stock, foreign-sourced borosilicate, and certified lead-free finishes. Supply chain risk concentrates in tariff exposure on Chinese glass tubing imports. Distribution runs through specialty tobacconists for wood pipes and fragmented smoke shop licensing jurisdictions for glass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where commission-based bespoke acquisition and provenance documentation services expand faster than production pipe turnover. Recurring revenue from authentication, restoration, and estate pipe brokerage outpaces hardware growth.
For Market Incumbents: Secure exclusive apprenticeship pipeline agreements with North Carolina and Virginia craft guilds to lock in carver supply against emerging digital-native competitors. Defend position by deepening backward integration into Mediterranean briar curing operations and acquiring Canadian specialty retail footprints in Ontario and British Columbia.
For New Entrants and Emerging Players: Lead with visual artistry positioning in glass segments where water-pipe crossover demand lacks established collector authentication infrastructure. Target underpenetrated Mexican metropolitan clusters in Mexico City and Guadalajara with tariff-advantaged cross-border fulfillment from Texas operations.
For Investors and Strategic Acquirers: Long-term, this sits as a scarcity-arbitrage play because trained carver supply inelasticity concentrates value capture among reputation-established artisans with documented output histories. Watch municipal smoke shop licensing liberalization in southeastern states as inflection signal for retail channel expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Apprenticeship Pipeline Expansion | Structured craft guild programs in Virginia alleviate artisan scarcity constraining output scaling. |
| Direct-to-Collector Digital Channel | Social documentation of carving processes cultivates personal followings bypassing wholesale hierarchies. |
| Canadian Specialty Retail Acquisition | Ontario and British Columbia tobacconists offer underpenetrated distribution headroom for heritage brands. |
| Provenance Documentation Service | Authentication and estate brokerage services capture recurring revenue from collector commission culture. |
| Health Canada Notification Pathway | Parallel FDA compliance infrastructure enables harmonized North American market access for accessories. |
Research Methodology
A standing panel of master pipe carvers, specialty tobacconist buyers, smoke shop licensing attorneys, and FDA regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA Center for Tobacco Products guidance documents, Health Canada notification databases, U.S. Customs import records for borosilicate tubing, and regional tobacco festival exhibitor directories. Bottom-up demand modeling triangulated against top-down value chain estimates.
Consistency checks validated volume and value outputs against historical import trajectories and collector auction clearing prices across the analysis window. Segmentation modeling incorporated material type, use case tier, distribution channel, and customer archetype dimensions. CAGRs derived from weighted regression across documented production volumes and price realization trends, with specific inputs including briar stock maturity cycles and municipal licensing approval rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement posture or Mediterranean climate stability for briar cultivation would require recalibration. Forecasts reflect assumptions regarding artisan training program enrollment and flavor ban policy diffusion. Recalibration cycles align with material shifts in federal accessory classification rulings and state attorney general enforcement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
Smart E-Cigarettes Market
Smoking Accessories
Pod Vape Market
Smoking Accessories
North America Cigarette Lighter Market