
 UK Smoking Pipe Market | 2026-2036
UK Smoking Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
UK Smoking Pipe Market Insights
The UK's Tobacco and Related Products Regulations is recalibrating how manufacturers approach product composition and packaging standards. Peterson Pipes leverages its Dublin-UK dual heritage to sustain brand loyalty among British collectors. Gawith Hoggarth & Co. anchors its position through in-house tobacco blending that complements pipe sales. Scandinavian Tobacco Group competes via diversified distribution across specialty stores and online retail channels.
A smoking pipe is a handheld device with a bowl for burning tobacco and a stem for drawing smoke, traditionally crafted from briar root, meerschaum, or corncob with wall thickness calibrated to manage combustion temperature. Its primary commercial purpose centers on delivering a cooled, flavored smoke experience for personal consumption or ceremonial use. Classic Briar dominates unit volume due to durability and grain aesthetics that command premium positioning. Meerschaum occupies a narrower but higher-margin niche prized by collectors for its porous, color-changing patina. The gift application segment is expanding fastest as lifestyle influencers elevate pipe smoking's social cachet.
The Medicines and Healthcare products Regulatory Agency and Trading Standards jointly enforce product safety and age-restriction compliance across UK tobacco accessories. These frameworks elevate manufacturing costs for imported pipes while creating barriers to entry for unverified suppliers. Stakeholders must monitor pending revisions to the Tobacco and Related Products Regulations that could redefine material safety thresholds or restrict certain flavor adjuncts tied to pipe tobacco pairings.
Market Dynamics
The UK's Tobacco and Related Products Regulations is compressing manufacturer margins while simultaneously creating compliance-based differentiation that favors established domestic producers over import-dependent competitors.
Growth Catalysts
- Heritage craft revival:Individual collectors in London and Edinburgh are driving demand for hand-finished briar pipes with documented provenance, expanding the addressable base beyond traditional smokers.
- TRPR compliance infrastructure:Manufacturers that invested early in the Tobacco and Related Products Regulations certification pathways now capture shelf space denied to newer entrants lacking verification documentation.
- Meerschaum patina culture:Social media documentation of color-progression aging is accelerating collector willingness to pay premiums for porous-block Turkish meerschaum over standard briar alternatives.
Market Restraints
- Briar root supply concentration:Mediterranean basin harvesting restrictions limit raw material availability, forcing UK manufacturers to absorb volatile input costs or reformulate wall-thickness specifications.
- TRPR notification burdens:The Tobacco and Related Products Regulations requires extensive product dossiers for each SKU variant, creating fixed compliance costs that disproportionately burden small-batch artisans.
- Heat-not-burn substitution:Electronic vaporization devices are capturing younger nicotine users who might otherwise transition to pipe smoking, compressing pipeline recruitment.
Strategic Opportunities
- Edinburgh specialty corridor expansion:Scotland's established pipe retail district offers underexploited capacity for experiential showrooms combining sales with restoration workshops.
- Gift segment formalization:Lifestyle influencer partnerships are elevating pipes to occasion-giving status, creating white space for curated presentation packaging and pairing accessories.
- MHRA material safety alignment:Proactive engagement with the Medicines and Healthcare products Regulatory Agency on forthcoming material thresholds could position compliant manufacturers for preferential retail placement.
Industry Challenges
- Briar grading expertise scarcity:Master craftspeople capable of evaluating root-block density and grain pattern are aging out of the workforce faster than apprenticeship programs replenish them.
- Trading Standards enforcement variance:Inconsistent age-verification interpretation across English local authorities creates operational friction for omnichannel retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Smoking Pipe Market |
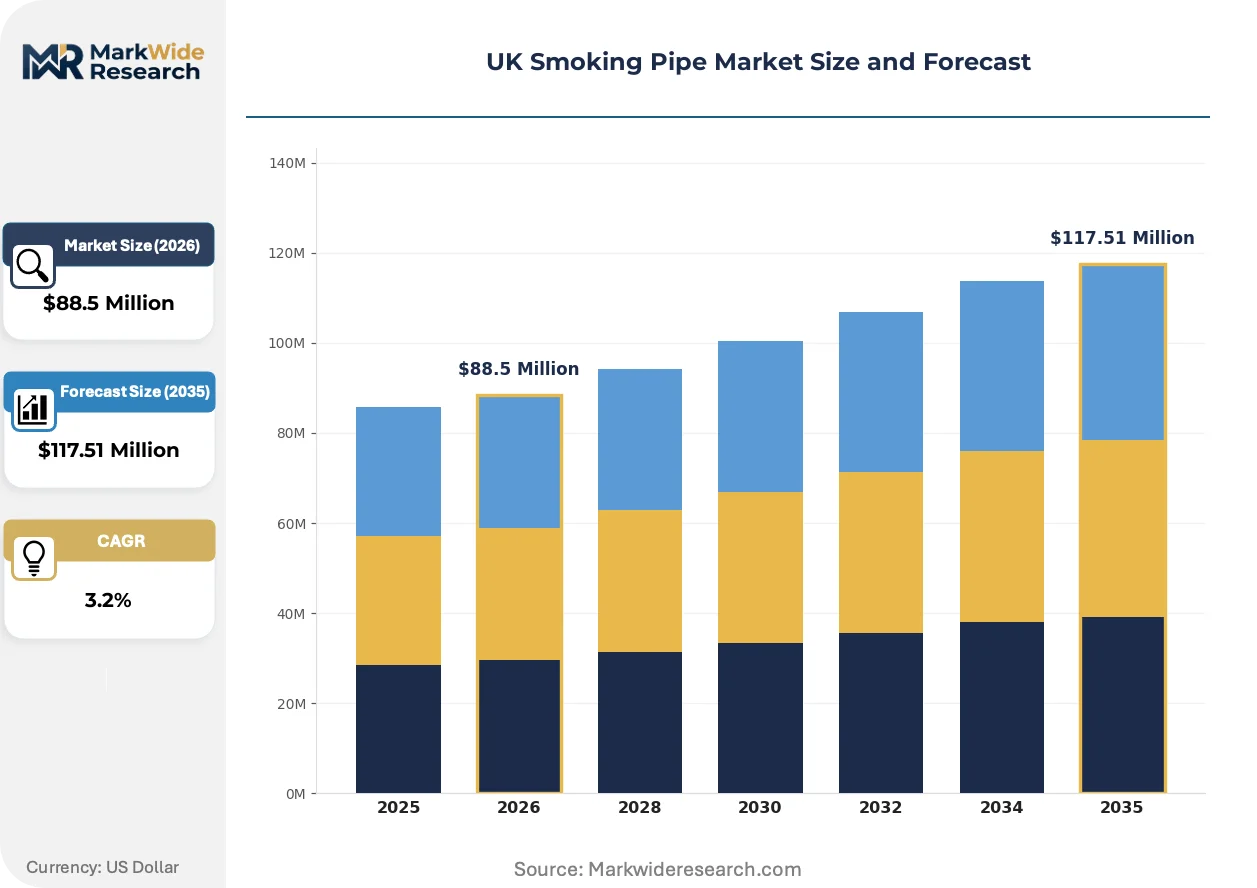
| Market Size in 2026 | $88.5 Million |
| Market Size in 2035 | $117.51 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Briar, Meerschaum, Corncob, Clay, Acrylic Application: Personal Use, Gift, Collectibles, Ceremonial, Smoking Lounges End User: Individual Enthusiasts, Specialty Retailers, Pipe Clubs, Lifestyle Influencers Distribution Channel: Specialty Stores, Online Retail, Tobacco Shops, Events & Expos |
| Companies Covered | Missouri Meerschaum Company, Brigham Pipes, Peterson Pipes, Rattray's, Nording Pipes, Scandinavian Tobacco Group, S. M. Frank, Gawith Hoggarth & Co., Savinelli Pipes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Smoking Pipe Market Trends and Innovations
Digital documentation tools and regulatory transparency requirements are reshaping how value is communicated and verified across the UK pipe value chain.
Blockchain-enabled provenance tracking is overtaking paper certificates of authenticity as the standard for high-value collector transactions. London auction houses and Edinburgh dealers are adopting distributed-ledger verification to document briar sourcing and workshop attribution. This compression of information asymmetry is enabling remote transactions that previously required physical inspection, expanding the addressable buyer pool beyond geographic proximity.
Trading Standards is intensifying scrutiny of online age-verification protocols under the Tobacco and Related Products Regulations enforcement mandate. Retailers operating hybrid physical-digital models must now demonstrate equivalent rigor across channels, driving investment in biometric and document-scanning technologies. The specialty store segment is absorbing these compliance costs most acutely, accelerating consolidation toward better-capitalized operators.
Collector purchasing is fragmenting across micro-communities organized around specific makers, materials, or regional styles rather than consolidated brand loyalty. Edinburgh's pipe shop district and London's specialty corridor are responding with appointment-only consultation models that replicate the intimacy of digital forums in physical space. This behavioral shift is most visible among buyers under forty who research extensively online before committing to high-ticket acquisitions.
UK Smoking Pipe Market Segmentation
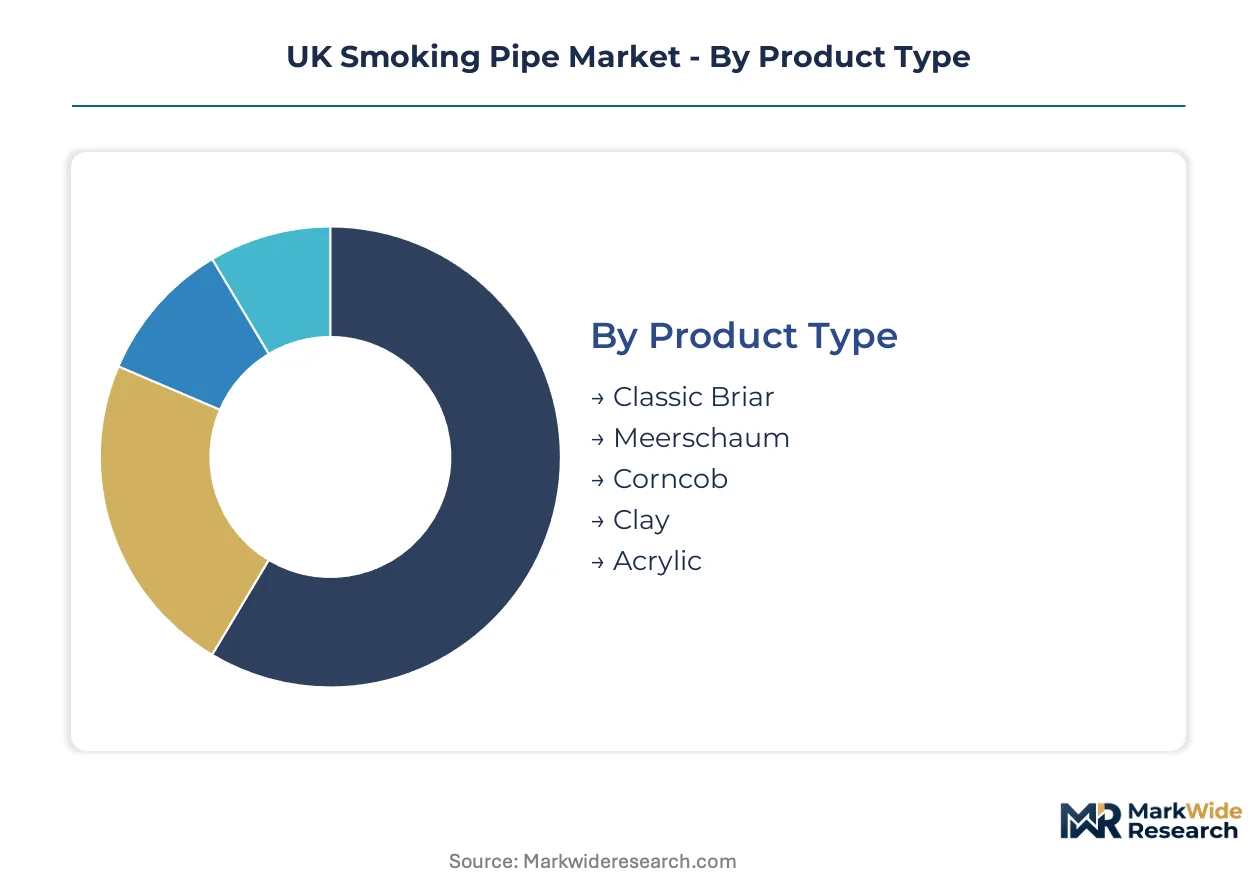
Segmentation in the UK smoking pipe market reveals divergent margin profiles across material grades and purchase occasions. Understanding these splits enables manufacturers to calibrate production runs and distribution investments against distinct buyer willingness-to-pay thresholds.
Product Type:
Classic Briar anchors unit volume while Meerschaum commands the steepest price premiums, creating a volume-versus-margin tension that shapes manufacturer portfolio strategy.
- Classic Briar:Carved from Mediterranean briar root with wall thickness calibrated for heat management and grain visibility. London's specialty retail corridor and Edinburgh's established pipe shop district concentrate demand for hand-finished pieces with documented provenance. Durability and repairability sustain replacement purchases among regular smokers.
- Meerschaum:Fashioned from porous Turkish sepiolite that develops amber patina through use. Collector willingness-to-pay premiums accelerates as social media documentation of color-progression aging spreads through micro-communities. The material's fragility limits daily-use adoption despite aesthetic cachet.
- Corncob:Entry-level segment leveraging abundant agricultural feedstock for price-accessible experimentation. Missouri-origin supply dominates despite UK finishing workshops adding value through stem fitting and bowl coating.
- Clay:Historical reproduction niche serving reenactment communities and museum gift operations. Thermal properties limit practical use to short-duration ceremonial contexts.
- Acrylic:Synthetic alternative bypassing briar supply constraints through injection-molded consistency. Trading Standards material safety documentation requirements favor standardized production over artisan variability.
Today's leader: Classic Briar. Tomorrow's challenger: Meerschaum.
Application:
Purchase occasion segmentation separates habitual consumption from episodic gifting and asset-grade collecting, each demanding distinct packaging, pricing, and channel strategies.
- Personal Use:Functional consumption segment prioritizing draw resistance, bowl capacity, and mouthpiece comfort through repeated handling. Individual enthusiasts in London and Edinburgh drive replacement cycles as bowls cake and stems oxidize.
- Gift:Occasion-driven purchases elevated by lifestyle influencer content positioning pipes as heritage objects. Curated presentation packaging and pairing accessories represent the steepest expansion trajectory as social cachet broadens beyond traditional smoker demographics.
- Collectibles:Investment-grade acquisitions requiring provenance documentation and condition verification. Blockchain-enabled authentication is compressing information asymmetry for remote transactions previously requiring physical inspection.
- Ceremonial:Ritual use in Masonic lodges, military messes, and wedding traditions sustaining demand for matched sets and presentation cases. Purchase timing clusters around organizational calendar events rather than individual preference.
- Smoking Lounges:Commercial hospitality settings requiring durable, standardized inventory with replacement availability. Volume purchasing power contrasts with individual collector selectivity.
Gift applications gain share fastest while personal use retains volume dominance.
End User:
Buyer type segmentation maps divergent research behaviors and purchase frequencies, from impulse-adjacent lifestyle adopters to methodical provenance investigators.
- Individual Enthusiasts:Core demand segment combining regular consumption with periodic collector purchases. Appointment-only consultation models in Edinburgh and London replicate digital forum intimacy for high-ticket acquisitions.
- Specialty Retailers:Inventory-curating intermediaries requiring consistent supply reliability and margin protection. TRPR notification burdens for each SKU variant disproportionately burden small-batch suppliers serving this channel.
- Pipe Clubs:Collective purchasing entities organizing group orders and estate pipe restorations. Fragmented micro-community organization around specific makers complicates consolidated brand loyalty.
- Lifestyle Influencers:Content creators driving aesthetic repositioning of pipe smoking for younger demographics. Partnership formalization creates white space for curated presentation packaging development.
Individual enthusiasts anchor current revenue. Lifestyle influencers reshape tomorrow's recruitment pipeline.
Distribution Channel:
Channel segmentation reflects enforcement intensity variance and experiential investment capacity across physical and digital touchpoints.
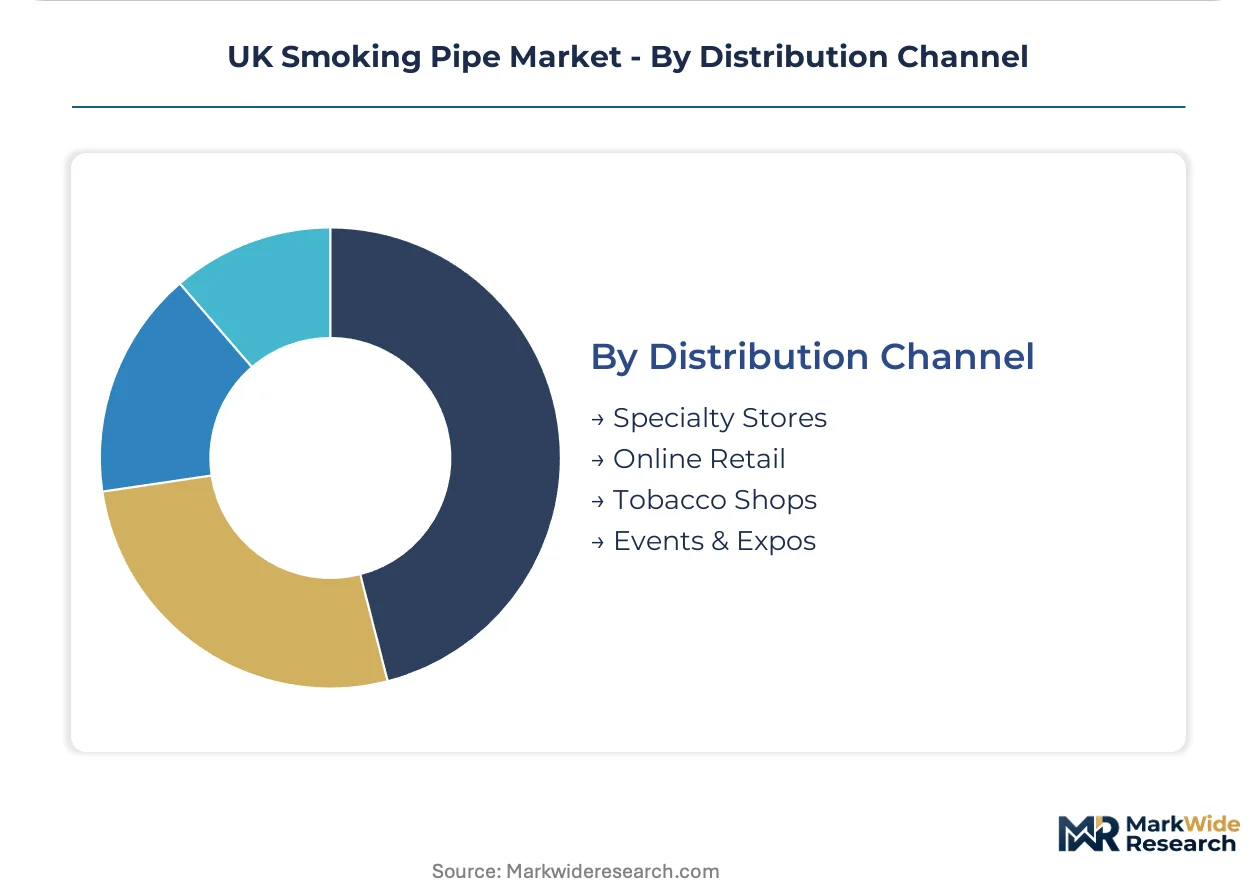
- Specialty Stores:Edinburgh's pipe shop district and London's specialty retail corridor concentrate expertise-driven transactions. Biometric age-verification investments absorb compliance costs most acutely, accelerating consolidation toward better-capitalized operators.
- Online Retail:Geographic reach expansion enabled by blockchain provenance documentation replacing physical inspection requirements. Trading Standards scrutiny of age-verification protocols intensifies under TRPR enforcement mandates.
- Tobacco Shops:Convenience-adjacent channel with lower experiential investment but broader geographic penetration. Product mix skews toward entry-price briar and corncob over collector-grade meerschaum.
- Events & Expos:Concentrated demand generation through annual gatherings enabling direct maker-collector relationships. Inventory liquidation and prototype testing functions supplement core revenue generation.
Specialty stores dominate premium placement. Online retail captures volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK smoking pipe industry traces its commercial lineage to nineteenth-century industrialization, when mechanized briar processing in London and hand-finishing traditions in Edinburgh established dual heritage centers that persist in today's specialty retail corridors.
London and the Southeast
Heritage craft revival among individual enthusiasts concentrates demand within London's specialty retail corridor, where appointment-only consultation models now replicate digital forum intimacy for high-ticket acquisitions. The Tobacco and Related Products Regulations (TRPR) enforcement by Trading Standards elevates compliance costs for specialty stores investing in biometric age-verification systems. Mayfair and Covent Garden clusters sustain premium positioning through documented provenance and restoration workshop integration.
Scotland
Edinburgh's established pipe shop district anchors collector-grade transactions for hand-finished briar with documented workshop attribution. The Medicines and Healthcare products Regulatory Agency (MHRA) material safety alignment creates preferential retail placement pathways for compliant Scottish manufacturers. Glasgow's emerging experiential showrooms combine sales with pipe restoration workshops, expanding capacity beyond Edinburgh's historic core.
Midlands
Industrial heritage in Birmingham and surrounding manufacturing centers supports component supply chains for stem fitting, bowl coating, and finishing operations serving UK-wide distribution. Trading Standards enforcement variance across English local authorities creates operational friction for omnichannel retailers headquartered in the region. Coventry and Leicester clusters specialize in acrylic and synthetic alternatives bypassing Mediterranean briar supply constraints.
North England
Yorkshire and Lancashire maintain historical tobacco blending traditions that complement pipe retail through integrated product ecosystems. MHRA pending revisions to material safety thresholds drive proactive manufacturer engagement from Manchester-based distributors. Liverpool's port infrastructure facilitates import logistics for Mediterranean briar root and Turkish meerschaum block shipments.
Wales and Northern Ireland
Smaller-scale artisan workshops in Cardiff and Belfast serve micro-community collector segments organized around specific regional styles rather than consolidated brand loyalty. TRPR notification burdens for each SKU variant disproportionately burden small-batch artisans in these sub-regions. Digital documentation tools and blockchain-enabled provenance tracking enable remote transactions that expand addressable buyer pools beyond geographic proximity.
UK Smoking Pipe Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material-grade and provenance-documentation dimensions, with collector-grade meerschaum and hand-finished briar commanding steeper price multiples than entry-level corncob and acrylic alternatives. The vendor base stratifies into heritage houses with dual-city legacies, diversified tobacco conglomerates with pipe portfolio extensions, and specialized artisans serving micro-community niches. Three archetypes dominate: Dublin-UK heritage brands leveraging transnational loyalty, vertically integrated blenders controlling complementary tobacco supply, and scale-driven distributors capturing shelf space through compliance infrastructure. Competitive moves concentrate on TRPR certification pathway investment and experiential showroom expansion.
Within the heritage-house tier, Peterson Pipes and Gawith Hoggarth & Co. exemplify dual-heritage positioning and vertical integration archetypes respectively. Peterson leverages its Dublin-UK lineage to sustain collector loyalty across British specialty retail corridors. Gawith Hoggarth anchors its market presence through in-house tobacco blending operations that complement pipe sales through integrated product ecosystems. Scandinavian Tobacco Group occupies the diversified-distribution archetype, competing across specialty stores and online retail channels with compliance infrastructure that captures shelf space denied to newer entrants lacking verification documentation.
| Leading Market Players |
|---|
| Missouri Meerschaum Company |
| Brigham Pipes |
| Peterson Pipes |
| Rattray's |
| Nording Pipes |
| Scandinavian Tobacco Group |
| S. M. Frank |
| Gawith Hoggarth & Co. |
| Savinelli Pipes |
| Others |
Pricing and Supply Chain Analysis
Captive supply of Mediterranean briar root anchors both cost predictability and premium-tier pricing power for UK manufacturers, while outsourced meerschaum block procurement from Turkish sepiolite deposits leaves porous-material specialists exposed to currency and extraction volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hand-finished briar with documented provenance from machine-turned utility pipes and entry corncob alternatives. Price differentiation rests on grain pattern density and TRPR certification tier rather than brand heritage alone. Cost compression in the mid-tier is intensifying because Trading Standards enforcement variance forces redundant compliance investment across English local authorities. Lifestyle adopters drive gift-segment premiums while habitual smokers exhibit greatest price sensitivity in replacement purchases.
Supply Chain Analysis
TRPR notification dossier requirements function as qualification gating that filters small-batch artisans from scaled distributors capable of absorbing per-SKU compliance overhead. Raw material flows draw from Mediterranean briar harvesting regions, Turkish meerschaum quarries, and Missouri corncob agricultural processing. Supply chain risk centers on single-source vulnerability for aged briar root stock with specific density characteristics. Distribution runs through Edinburgh's specialty corridor and London's appointment-only consultation showrooms for collector-grade transactions, with online retail capturing volume expansion through blockchain-enabled provenance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between UK TRPR compliance infrastructure and EU regulatory divergence creates margin expansion potential for manufacturers with dual-notification capabilities serving both jurisdictions.
For Market Incumbents: To counter heat-not-burn device substitution among younger nicotine users, Peterson Pipes and heritage houses should deepen restoration workshop integration within physical retail footprints while capturing estate pipe refurbishment revenue. Channel control through exclusive Edinburgh and London specialty store partnerships preserves margin against online price transparency.
For New Entrants and Emerging Players: Lifestyle influencer content partnerships offer the most penetrable vector for bypassing established brand loyalty among buyers under forty. White-space targets include curated gift packaging development and ceremonial occasion positioning for Masonic and military mess traditions. A direct-to-collector go-to-market angle leveraging blockchain provenance documentation enables remote transactions without physical showroom investment.
For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated blenders with captive tobacco supply because Gawith Hoggarth's integrated product ecosystem demonstrates superior retention against pure-play pipe manufacturers. Long-term viability over the next decade hinges on meerschaum patina culture sustaining collector premiums against briar commoditization. The signal to watch is MHRA material safety threshold revisions that could disqualify import-dependent competitors from retail placement.
| Strategic Initiative | Industry Significance |
|---|---|
| TRPR Certification Investment | Captures shelf space denied to newer entrants lacking verification documentation. |
| Experiential Showroom Expansion | Edinburgh and London appointment-only models replicate digital forum intimacy for high-ticket acquisitions. |
| Blockchain Provenance Integration | Compresses information asymmetry for remote meerschaum and collector-grade briar transactions. |
| Restoration Workshop Integration | Extends customer lifetime value through estate pipe refurbishment and stem replacement services. |
| Lifestyle Influencer Partnership | Repositions pipe smoking for gift occasion demographics beyond traditional smoker recruitment. |
Research Methodology
Multiple input streams — primary interviews with pipe shop proprietors, master craftspeople, and Trading Standards enforcement officers, alongside secondary validation — were reconciled to construct segment-level demand estimates. Customs records, MHRA notification databases, and Edinburgh auction house transaction logs provided volume benchmarks. Bottom-up production capacity assessments at Midlands finishing workshops and top-down expenditure analysis from collector micro-communities were triangulated against specialty retailer inventory turnover data.
Historical price progression for briar and meerschaum grades was cross-referenced against panel input from procurement leads at Scandinavian Tobacco Group and Gawith Hoggarth to model material cost pass-through elasticity. Segmentation dimensions across the projection horizon included material type, purchase occasion, buyer archetype, and distribution channel. CAGRs were derived from trend extrapolation moderated by regulatory scenario weighting, with pipe club membership trajectories and influencer content engagement rates serving as demand-side validation inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MHRA material safety revisions and Mediterranean harvesting restriction extensions. The analysis reflects assumptions regarding TRPR enforcement consistency and briar root supply continuity. A model refresh is warranted upon material change in Trading Standards age-verification protocol mandates or blockchain provenance adoption thresholds among London auction houses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
North America Cigarette Lighter Market
Smoking Accessories
Pod Vape Market
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
Ashtray Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
Smart E-Cigarettes Market