
 Herb Grinder Market | 2026-2036
Herb Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Herb Grinder Market Analytics
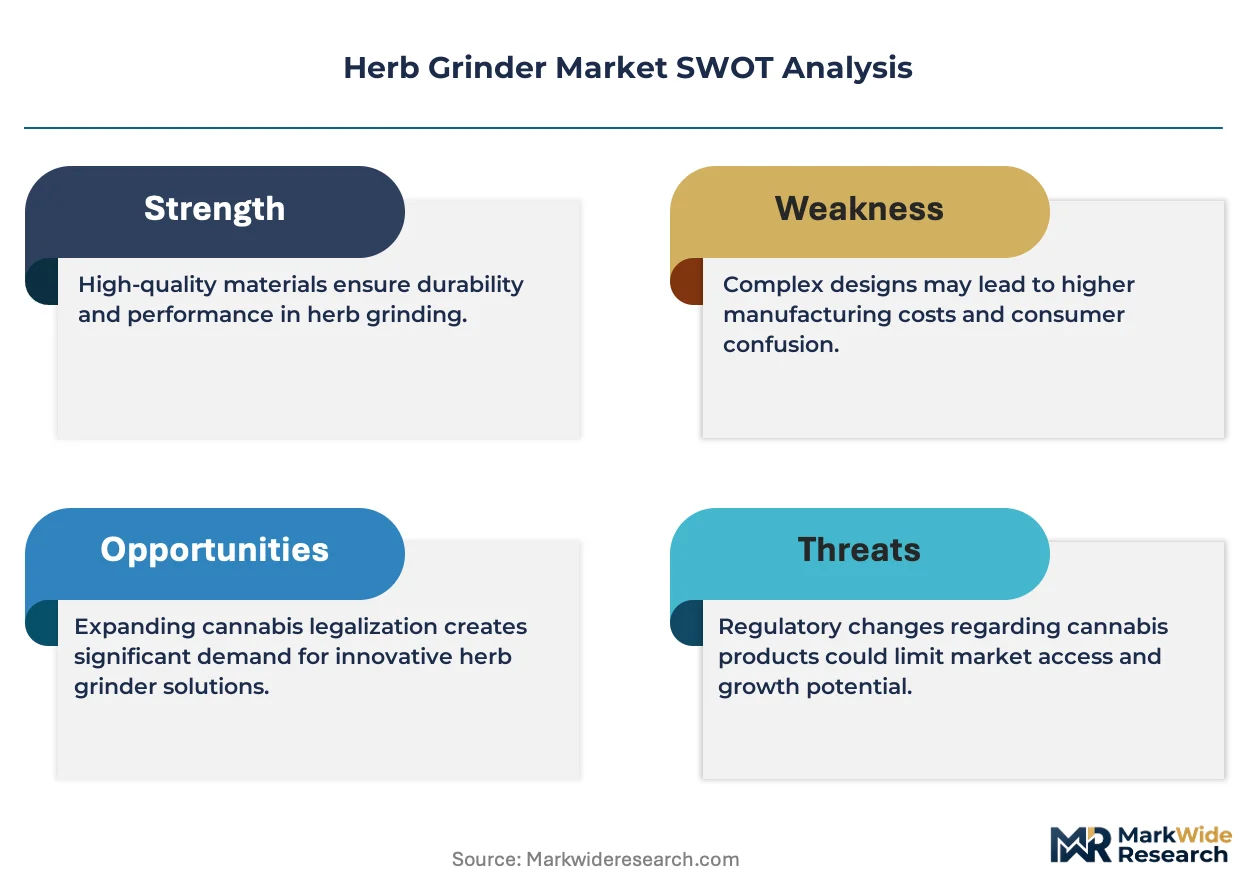
Stainless steel is expanding its share in premium grinder construction as aluminum faces scrutiny over oxidation and metallic leaching concerns. Santa Cruz Shredder leverages aerospace-grade aluminum anodizing to sustain its position in the high-end manual segment. Flower Mill differentiates through patented milling technology that replaces traditional teeth-based grinding with a shearing mechanism. Old Mate anchors its competitive stance through Australian-designed portable units optimized for domestic botanical preparation regulations.
A herb grinder is a mechanical device engineered to reduce dried plant material to uniform particle sizes, typically employing interlocking teeth, pegs, or milling surfaces with tolerances measured in millimeters to achieve consistency for combustion, vaporization, or infusion processes. Manual grinders dominate unit volume due to lower price points and zero power dependency, while electric variants capture disproportionate margin pools in commercial settings where throughput efficiency governs procurement decisions. Stainless steel construction commands premium positioning in medical cannabis channels where sterilization protocols and durability requirements exceed consumer-grade expectations.
The FDA maintains jurisdiction over grinder materials contacting ingestible substances, while state-level cannabis regulators in Colorado, California, and Michigan impose supplemental testing requirements on accessories sold within licensed dispensary channels. ISO 9001 quality management certification and EU REACH material compliance increasingly function as baseline market access credentials for cross-border trade into European medical cannabis markets. Stakeholders must monitor evolving material safety standards as jurisdictions differentiate between recreational accessory classification and medical device-adjacent regulatory treatment.
Market Dynamics
The FDA's evolving material safety standards for cannabis-contacting equipment are compressing certification timelines and forcing manufacturers toward food-grade stainless steel construction, fundamentally restructuring procurement criteria across dispensary and pharmacy channels.
Growth Catalysts
- REACH compliance expansion:EU medical cannabis markets now require full material traceability for accessories, accelerating stainless steel adoption over aluminum alloys in German pharmacy procurement.
- Electric multi-chamber throughput:California and Colorado dispensaries are scaling automated grinding stations to handle bulk flower processing, creating sustained equipment refresh cycles.
- Precision dosing protocols:Medical cannabis programs in Germany, Israel, and Australia mandate particle-size consistency for standardized dosing, favoring calibrated milling surfaces over traditional tooth designs.
Market Restraints
- Aerospace aluminum supply concentration:Anodized aluminum billet sourcing clusters with three North American suppliers, exposing grinder manufacturers to input price volatility and allocation risk.
- FDA 510(k) ambiguity:Unclear classification boundaries between recreational accessories and medical device-adjacent equipment create regulatory friction, delaying product launches and inflating compliance legal spend.
- Manual grinder durability ceiling:Tooth wear and thread stripping in consumer-grade units limit replacement intervals, compressing recurring revenue potential in the mass-market segment.
Strategic Opportunities
- Medical pharmacy channel expansion:Poland and Italy are licensing new cannabis pharmacies with sterilization mandates, creating first-mover advantage for ISO 9001-certified stainless steel suppliers.
- Home cultivation normalization:Canadian and Uruguayan residential grow regulations are legalizing small-batch processing, expanding addressable demand for precision home-use grinders.
- Battery chemistry convergence:Integration of USB-C fast-charging with brushless DC motors is electrifying portable electric grinder design, opening premium mobility segments previously served by manual units.
Industry Challenges
- Multi-jurisdiction certification stacking:Simultaneous FDA material reviews, EU REACH dossier preparation, and state-level cannabis accessory testing create timeline conflicts and resource strain for mid-size manufacturers.
- Legacy tooling amortization:CNC machining investments optimized for aluminum tooth patterns face write-down pressure as stainless steel milling and shearing architectures gain regulatory preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herb Grinder Market |
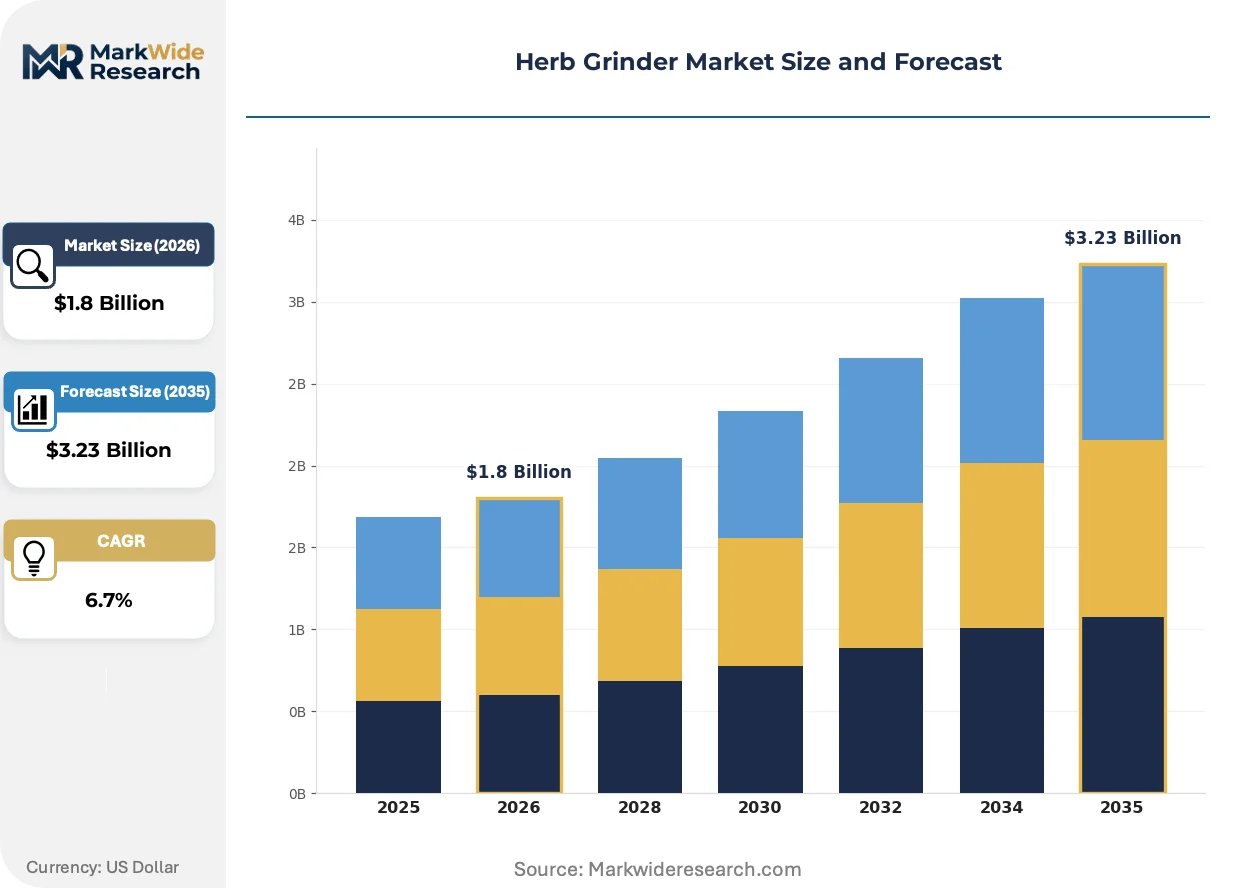
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Portable, Multi-chamber Material: Aluminum, Wood, Plastic, Stainless Steel End User: Consumer, Retailer, Distributor, Wholesaler Size: Small, Medium, Large, Extra-Large |
| Companies Covered | Grinders For Life, Santa Cruz Shredder, Flower Mill, Old Mate, Banana Bros, Wakit, Cyber Grinder, Odin, Herb Ripper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herb Grinder Market Evolving Landscape
Material science breakthroughs and regulatory precision mandates are converging to reshape grinder architecture, with electrification and shearing mechanisms displacing century-old tooth-based designs across both medical and consumer tiers.
Brushless DC motor systems paired with lithium-polymer power packs are electrifying portable grinder categories previously dominated by manual operation. California dispensary procurement teams now specify electric throughput rates for back-of-house operations, while home users in Colorado and Oregon adopt rechargeable units for consistency. This electrification is compressing price premiums between manual and electric segments, eroding the historical two-tier market structure.
EU REACH Annex XVII restrictions on nickel release rates are forcing stainless steel alloy reformulation across European medical cannabis supply chains. German grinder importers now require mill certificates documenting 316L surgical-grade composition, with batch testing protocols adding four to six weeks to fulfillment timelines. Manufacturers serving the EU market are responding by dual-certifying production lines for both FDA food-contact and ECHA REACH compliance, consolidating supplier bases to reduce testing redundancy.
Hospital and clinical buyers are consolidating grinder procurement through group purchasing organizations, displacing fragmented dispensary-level ordering. This concentration is visible in German medical cannabis pharmacy networks, where centralized sterilization services now specify equipment with validated cleaning protocols. The shift is compressing vendor counts and elevating documentation requirements above price sensitivity in contract awards.
Herb Grinder Market Segmentation
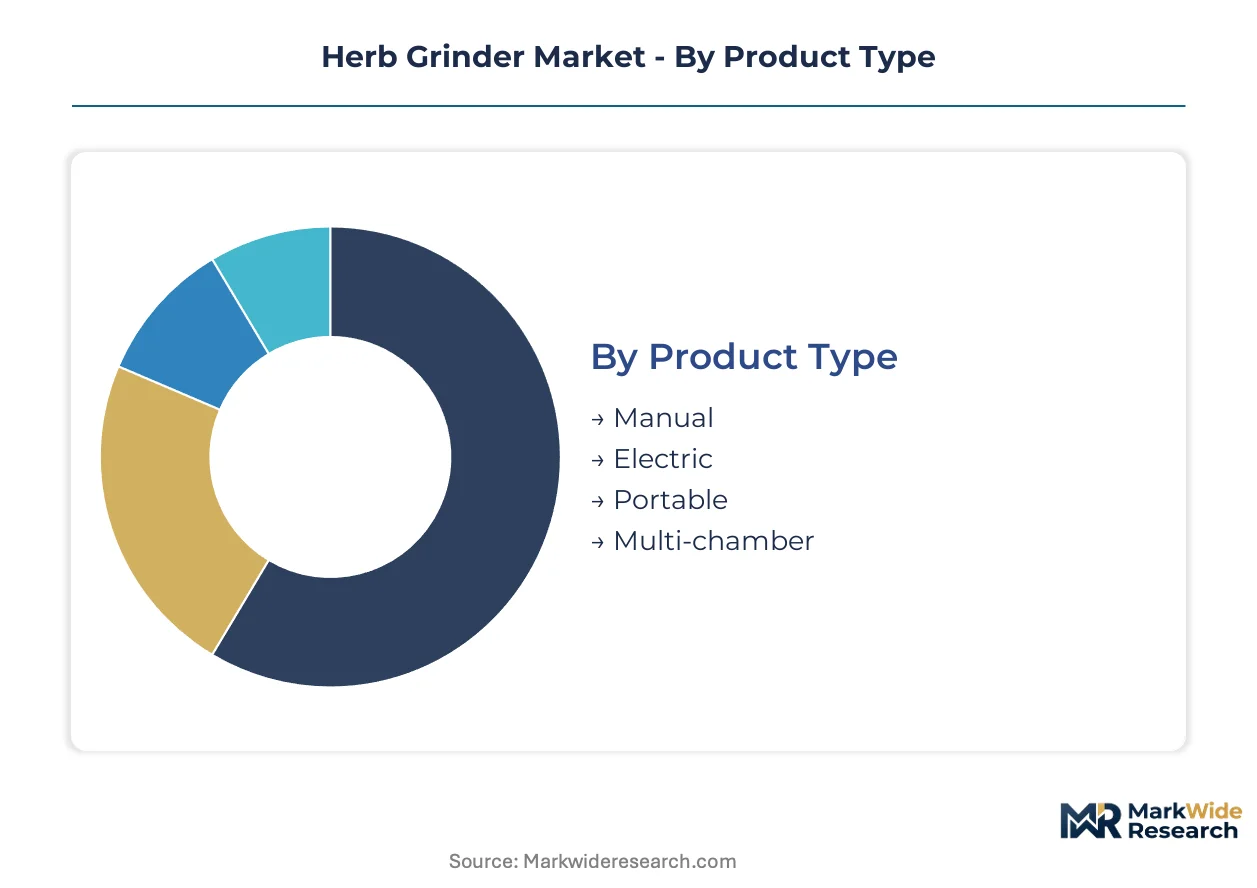
Segmentation in the herb grinder market reveals divergent capital requirements and margin structures across product architectures and material specifications. Procurement patterns in licensed dispensaries and medical pharmacies favor segments with validated compliance documentation over price-optimized alternatives.
Product Type:
Capital intensity varies sharply across product categories, with electric multi-chamber units demanding precision motor assembly and battery integration while manual variants require minimal tooling investment.
- Manual:Anodized aluminum or stainless steel bodies with interlocking tooth patterns dominate unit volume through sub-$30 price positioning. California and Colorado dispensaries stock manual units for cash-paying customers prioritizing portability over throughput.
- Electric:Brushless DC motor systems paired with lithium-polymer packs command 4-6x manual pricing. German medical cannabis pharmacies specify electric throughput rates for back-of-house processing where particle consistency governs dosing accuracy.
- Portable:Compact single-chamber designs optimized for pocket carry. Battery chemistry convergence toward USB-C fast-charging is elevating performance expectations in this segment.
- Multi-chamber:Kief separation architectures with micron-mesh screens add manufacturing complexity. Precision dosing protocols in Israel and Australia favor calibrated multi-chamber units for standardized medical preparation.
Manual grinders absorb the bulk of installed capacity; electric variants are expanding most quickly through commercial procurement channels.
Material:
Raw material selection determines regulatory pathway complexity, with stainless steel requiring mill certification and REACH dossier preparation while aluminum faces simpler anodizing verification.
- Aluminum:Aerospace-grade billet with hard-anodized surfaces retains cost advantage in consumer channels. Three North American suppliers concentrate input sourcing, exposing manufacturers to allocation risk during demand surges.
- Stainless Steel:316L surgical-grade composition satisfies FDA food-contact and EU Annex XVII nickel release limits. Polish and Italian medical cannabis pharmacies now mandate stainless steel for sterilization compatibility.
- Wood:Hardwood bodies with food-safe finishes serve botanical preparation markets with aesthetic preferences. Natural material variability complicates precision tolerance achievement.
- Plastic:Medical-grade polymers offer cost minimization for single-use or high-turnover environments. Limited durability constrains positioning outside disposable applications.
Aluminum retains dominant share in recreational channels; stainless steel is gaining share fastest through medical pharmacy procurement mandates.
End User:
Volume scale and documentation requirements differentiate end-user segments, with institutional buyers consolidating procurement through group purchasing organizations while individual consumers prioritize immediate availability.
- Consumer:Individual purchasers through dispensaries, head shops, and e-commerce platforms. Price sensitivity peaks in this segment with minimal compliance documentation requirements.
- Retailer:Licensed dispensaries in California, Colorado, and Michigan stocking accessories for resale. Inventory turns and margin preservation govern procurement decisions.
- Distributor:Regional wholesalers managing logistics for fragmented retail bases. Working capital intensity distinguishes viable distributors from marginal operators.
- Wholesaler:National-scale operators serving multi-state dispensary chains. German pharmacy networks are consolidating grinder procurement through centralized sterilization services, elevating vendor documentation requirements.
Consumer purchases generate highest unit volume; wholesaler channels are climbing the fastest through institutional procurement consolidation.
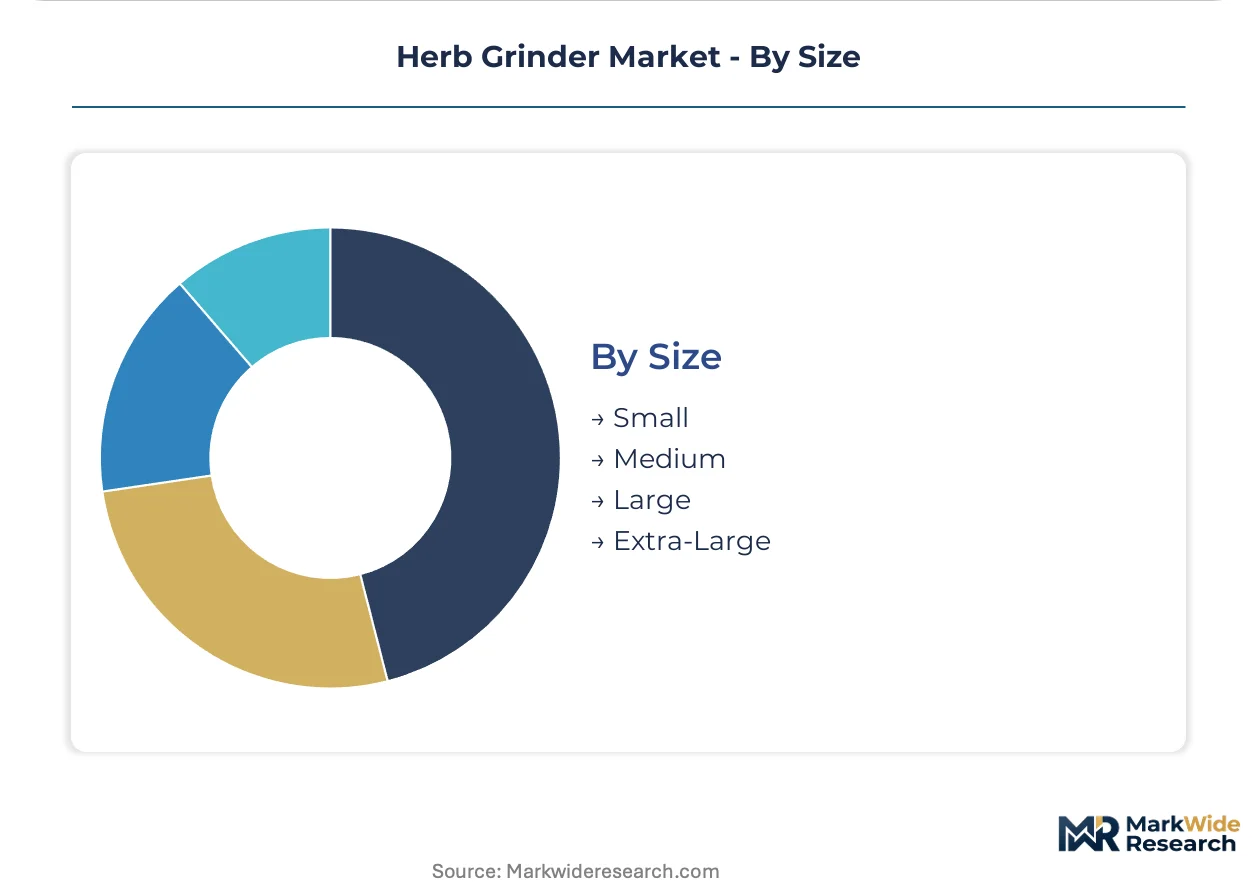
Size:
Manufacturing economies concentrate in medium and large formats where standard CNC tooling achieves optimal utilization, while small and extra-large variants require specialized fixture investment.
- Small:Pocket-diameter units under 50mm for discrete carry. Home cultivation normalization in Canada and Uruguay is expanding demand for personal-scale processing equipment.
- Medium:55-63mm diameter representing production sweet spot for manual grinder manufacturers. Thread precision and tooth alignment tolerances are most cost-effectively achieved at this scale.
- Large:70-75mm bodies for elevated capacity without commercial-grade motorization. Enthusiast segments in Oregon and Washington prefer large manual units for small-batch home processing.
- Extra-Large:80mm+ diameters and electric bulk-processing stations. California dispensary back-of-house operations specify extra-large electric throughput for flower preparation at scale.
Medium sizes command dominant production allocation; extra-large formats are expanding most quickly through commercial dispensary automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and Dongguan concentrate precision CNC machining capacity for grinder components, drawing contract manufacturers seeking tariff-efficient export channels to North American and European medical cannabis markets.
United States
California and Colorado dispensaries drive electric multi-chamber procurement for back-of-house automation, while Michigan's licensed retailers impose supplemental metals testing on accessories. FDA material safety reviews for cannabis-contacting equipment create compliance bottlenecks, particularly for aluminum alloy suppliers. Los Angeles and Denver anchor distribution networks serving fragmented state-level regulatory regimes.
Germany
Medical cannabis pharmacies in Berlin and Hamburg mandate stainless steel construction for sterilization compatibility, with centralized procurement through group purchasing organizations compressing vendor counts. ECHA REACH Annex XVII nickel release limits force alloy reformulation and batch testing protocols. The North Rhine-Westphalia industrial corridor hosts precision metalworking suppliers certified for EU medical device-adjacent standards.
Canada
Residential cultivation normalization in British Columbia and Ontario expands addressable demand for personal-scale processing equipment, with Health Canada regulations distinguishing between recreational accessory and medical preparation classifications. Vancouver and Toronto retail channels stock precision home-use grinders alongside commercial-grade units. Prairie province agricultural equipment fabricators diversify into botanical processing machinery.
Australia
TGA medical cannabis program requirements for particle-size consistency favor calibrated milling surfaces in Sydney and Melbourne pharmacy procurement. Domestic botanical preparation regulations in Queensland and New South Wales shape portable unit specifications. Perth-based metal fabricators supply stainless steel components to Asia-Pacific medical markets.
Israel
Precision dosing protocols in Tel Aviv and Jerusalem medical cannabis programs mandate standardized particle preparation, elevating documentation requirements above price sensitivity. Ministry of Health regulations align with EU material safety standards, facilitating cross-certification for export-oriented manufacturers. Haifa's precision engineering cluster supplies calibrated grinding components to European pharmacy networks.
Herb Grinder Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium manual brands commanding margin pools while OEM fabricators capture volume in private-label channels. The vendor base concentrates around three North American aerospace aluminum suppliers and a expanding tier of Chinese CNC houses certified for FDA food-contact standards. Strategic archetypes include heritage anodized-aluminum specialists, stainless steel medical-grade suppliers, and electric motor-assembly integrators. Competitive moves center on dual-certification production line investments and backward integration into billet sourcing.
Within the heritage-branded tier, Santa Cruz Shredder and Flower Mill exemplify divergent technical approaches to premium positioning, while Old Mate anchors Australian-designed portable specialization. These three occupy positions defined by material science differentiation rather than scale-driven cost minimization, with each representing a distinct regulatory-compliance archetype: aerospace-aluminum anodizing, patented shearing mechanisms, and jurisdiction-optimized portability respectively.
| Leading Market Players |
|---|
| Grinders For Life |
| Santa Cruz Shredder |
| Flower Mill |
| Old Mate |
| Banana Bros |
| Wakit |
| Cyber Grinder |
| Odin |
| Herb Ripper |
| Others |
Value Network & Pricing Analysis
EU REACH Annex XVII nickel release mandates gate qualified supply for medical-grade grinder manufacturers, compressing vendor pools capable of commanding premium-tier pricing in German and Israeli pharmacy channels. Buyers lacking mill-certified 316L surgical-grade documentation face automatic disqualification from institutional procurement, concentrating pricing power among dual-certified producers.
Pricing Analysis
Lead-time-driven pricing stratification separates qualified suppliers from spot-market alternatives, with four-week batch-tested units commanding substantial premiums over standard inventory. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and sterilization protocol compatibility. Cost compression in aluminum-tooth consumer segments intensifies as Chinese CNC houses absorb margin through volume scale. Dispensary cash customers exhibit highest price sensitivity, while German GPO buyers prioritize documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from California and Colorado dispensaries mandate multi-supplier qualification for aerospace-grade aluminum billet, mitigating allocation risk from three concentrated North American suppliers. Component sourcing draws from Shenzhen precision machining clusters, North Rhine-Westphalia metalworking corridors, and Perth-based stainless fabricators. Raw material dependencies center on 316L surgical steel alloy, lithium-polymer battery cells, and brushless DC motor assemblies. Tariff exposure on Chinese-machined components threatens margin stability. Distribution runs through licensed dispensary networks, medical pharmacy GPOs, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA food-contact material reviews and EU REACH dossier preparation erect barrier-to-entry moats favoring incumbent dual-certification holders.
For Market Incumbents: Cement procurement relationships with German and Israeli pharmacy GPOs before Polish and Italian market openings accelerate. Backward integration into aerospace aluminum billet sourcing defends against three-supplier concentration risk. Accelerate stainless steel milling architecture R&D as tooth-based designs face regulatory obsolescence.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce routes bypass dispensary licensing barriers for portable electric grinder launches. Home cultivation normalization in Canada and Uruguay offers the most penetrable white-space for personal-scale precision units. Target USB-C fast-charging integration as the distinguishing go-to-market angle against legacy manual brands.
For Investors and Strategic Acquirers: FDA 510(k) classification clarity for grinder accessories is the leading indicator that medical device-adjacent valuation multiples will apply to stainless steel suppliers. The five-to-ten-year viability window favors acquisition targets with existing ISO 9001 certification and REACH dossier infrastructure. Watch for battery chemistry convergence signaling portable electric segment maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Production Line Investment | FDA food-contact and EU REACH compliance opens German pharmacy GPO contracts. |
| Backward Integration into Billet Sourcing | Captive aerospace aluminum supply mitigates three-supplier concentration risk. |
| Brushless DC Motor Platform Development | USB-C fast-charging integration captures premium portable electric segments. |
| Shearing Mechanism Patent Portfolio | Precision dosing protocols in Israel and Australia favor non-tooth architectures. |
| Polish and Italian Pharmacy Channel Entry | First-mover sterilization-mandate compliance builds medical-grade market share. |
Research Methodology
Document review covered FDA material safety guidance, ECHA REACH Annex XVII restrictions, and German medical cannabis pharmacy procurement specifications, complemented by interviews with grinder manufacturing executives, California dispensary procurement managers, stainless steel mill certification specialists, and brushless DC motor system integrators. Secondary validation drew from customs trade databases, ISO 9001 certification registries, and EU medical device-adjacent standards documentation. Bottom-up unit volume estimates triangulated against top-down market value reconstructions.
Historical shipment data cross-referenced against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, material specification, end-user channel, and geographic regulatory cluster. CAGRs were derived through growth driver elasticity assessment and constraint boundary analysis. Industry-specific forecast inputs incorporated electric motor adoption curves and medical pharmacy sterilization mandate rollout timelines.
Inputs from German pharmacy GPOs and Israeli Ministry of Health regulators were available through the study window; gaps in real-time FDA 510(k) classification determinations introduce uncertainty bands around medical device-adjacent revenue projections. Deviation in REACH nickel release limit enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Hookah Products Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
Lighter Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
Ashtray Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
Smart E-Cigarettes Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
United States Cigarette Lighter Market