
 US Smoking Pipe Market | 2026-2036
US Smoking Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
US Smoking Pipe Market Insights
A shift from outsourced overseas production toward in-house domestic craftsmanship is restructuring supply dynamics for US pipe manufacturers. Missouri Meerschaum Company leverages its century-old corncob heritage to anchor Midwest manufacturing authenticity. Peterson Pipes competes through Irish-imported craftsmanship paired with dedicated US distribution channels. Dr. Grabow Pipes sustains volume accessibility through standardized production lines that dominate drugstore and convenience retail placement.
A smoking pipe constitutes a handheld combustion device engineered to cool and filter smoke through a bowl-stem airway, typically constructed from briar, meerschaum, corn cob, or heat-resistant glass with chamber diameters ranging from 0.75 to 1.5 inches. Wood segment production concentrates in Mediterranean briar harvesting cycles that constrain raw material availability and elevate premium pricing tiers. Glass pipes lead recreational user channels due to perceived cleanliness and customization potential, while collectors drive luxury price tier concentration through limited-edition artisan releases.
The FDA regulates pipe tobacco and associated accessories under the Family Smoking Prevention and Tobacco Control Act, requiring ingredient disclosure and marketing restrictions that elevate compliance costs for smaller manufacturers. State-level excise tax variations between jurisdictions such as North Carolina and New York create arbitrage opportunities that reshape interstate distribution patterns. Stakeholders must monitor evolving state cannabis legalization frameworks that expand glass pipe demand while potentially triggering reclassification debates at the federal level.
Market Dynamics
The US Smoking Pipe Market pivots on FDA tobacco product oversight, which restructures compliance costs and manufacturing footprints while artisanal collector demand concentrates volume in premium tiers.
Growth Catalysts
- State cannabis legalization:Expanding recreational frameworks in Michigan and Illinois accelerate glass pipe demand through dispensary retail channels.
- Heritage craft revival:Missouri Meerschaum's century-old corncob tradition anchors domestic authenticity narratives that sustain collector premiums.
- REACH-compliant Mediterranean briar:EU chemical safety standards elevate certified wood sourcing credibility among US artisan manufacturers.
Market Restraints
- Raw material concentration:Mediterranean briar harvesting cycles constrain bowl supply and inflate premium wood pricing tiers.
- FDA ingredient disclosure mandates:The Family Smoking Prevention and Tobacco Control Act elevates compliance burdens that disproportionately burden small-scale pipe makers.
- Heat-resistant glass substitution:Borosilicate alternatives displace traditional materials in recreational user segments.
Strategic Opportunities
- Southeast regional loyalty:Traditional pipe-smoking culture in North Carolina and Virginia sustains brick-and-mortar retail density underserved by digital channels.
- Excise tax arbitrage:Interstate variations between low-tax jurisdictions like North Carolina and high-tax states like New York create redistribution margin capture.
- Artisan-direct e-commerce:Instagram and TikTok storefronts bypass wholesale markups for limited-edition collector releases.
Industry Challenges
- Briar carving apprenticeship gaps:Master bowl-turning skills concentrate among aging Mediterranean craftsmen with limited US knowledge transfer pipelines.
- FDA marketing restriction navigation:Pipe tobacco accessory promotion faces evolving interpretation of "modified risk" claims that chill digital advertising.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smoking Pipe Market |
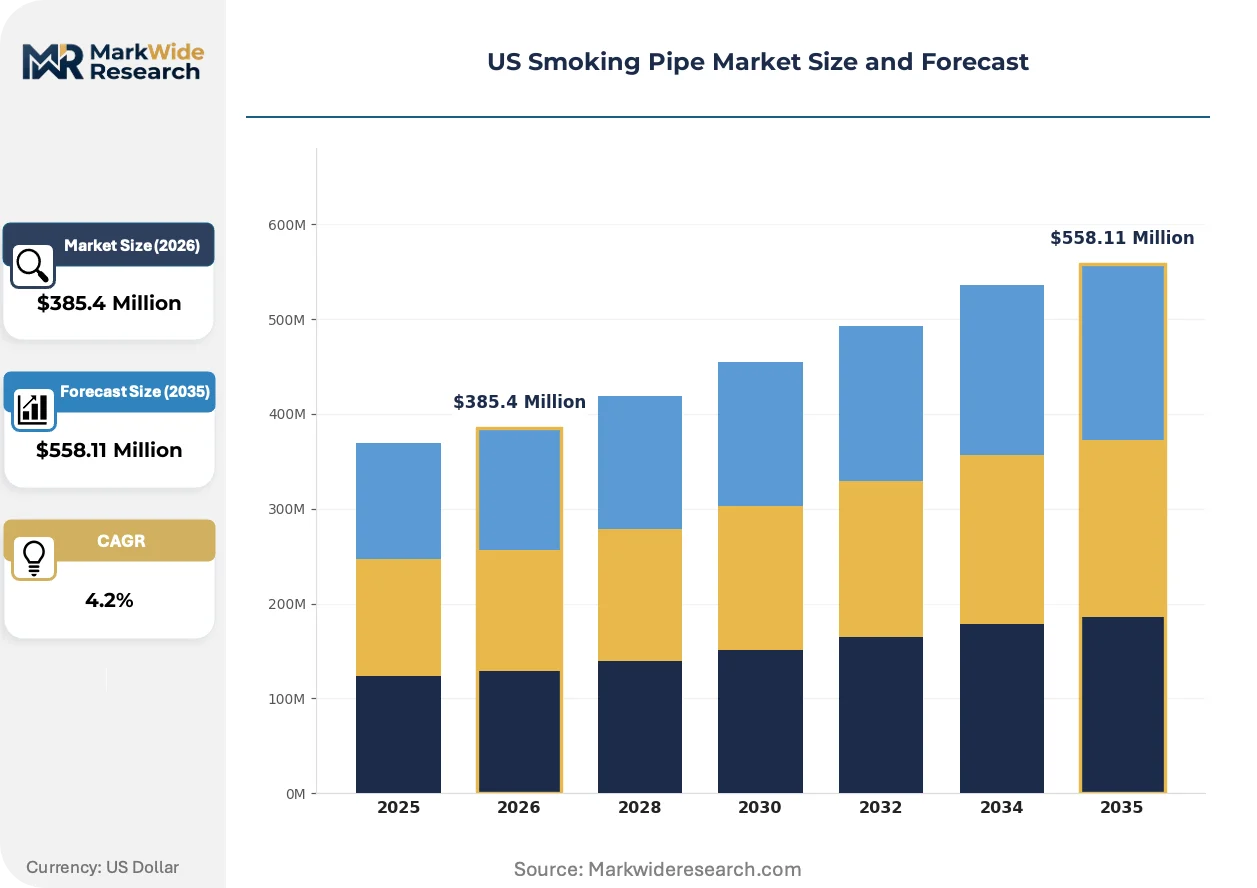
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Wood, Metal, Acrylic User Type: Recreational Users, Medical Users, Collectors, Retailers Size: Small, Medium, Large, Extra Large Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Missouri Meerschaum Company, Dr. Grabow Pipes, Peterson Pipes, Dunhill, Savinelli, Stanwell Pipes, Charatan, Baraccini Pipes, Castello, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smoking Pipe Market Trends and Innovations
Digital fabrication and regulatory reclassification are compressing traditional manufacturing timelines while reshaping channel economics for US pipe stakeholders.
Precision CNC machining is overtaking hand-carving for mid-tier briar bowl production. Recreational retailers now specify tolerances within 0.1 millimeters for stem-to-shank fits. This standardization compresses artisan lead times from weeks to days while eroding price premiums on non-limited production runs.
The FDA's Deeming Rule extension to pipe tobacco accessories forces ingredient disclosure and pre-market authorization pathways. Small manufacturers face documentation costs that favor standardized product lines over experimental blends. Glass pipe importers increasingly segregate inventory by state compliance status to preempt seizure risk.
Collector procurement gravitates toward direct-to-consumer auction platforms that disintermediate traditional tobacconist networks. Estate pipe trading on specialized forums now exceeds volume through brick-and-mortar consignment. This channel shift concentrates pricing power with condition-grading expertise held by a handful of Southern appraisal specialists.
US Smoking Pipe Market Segmentation
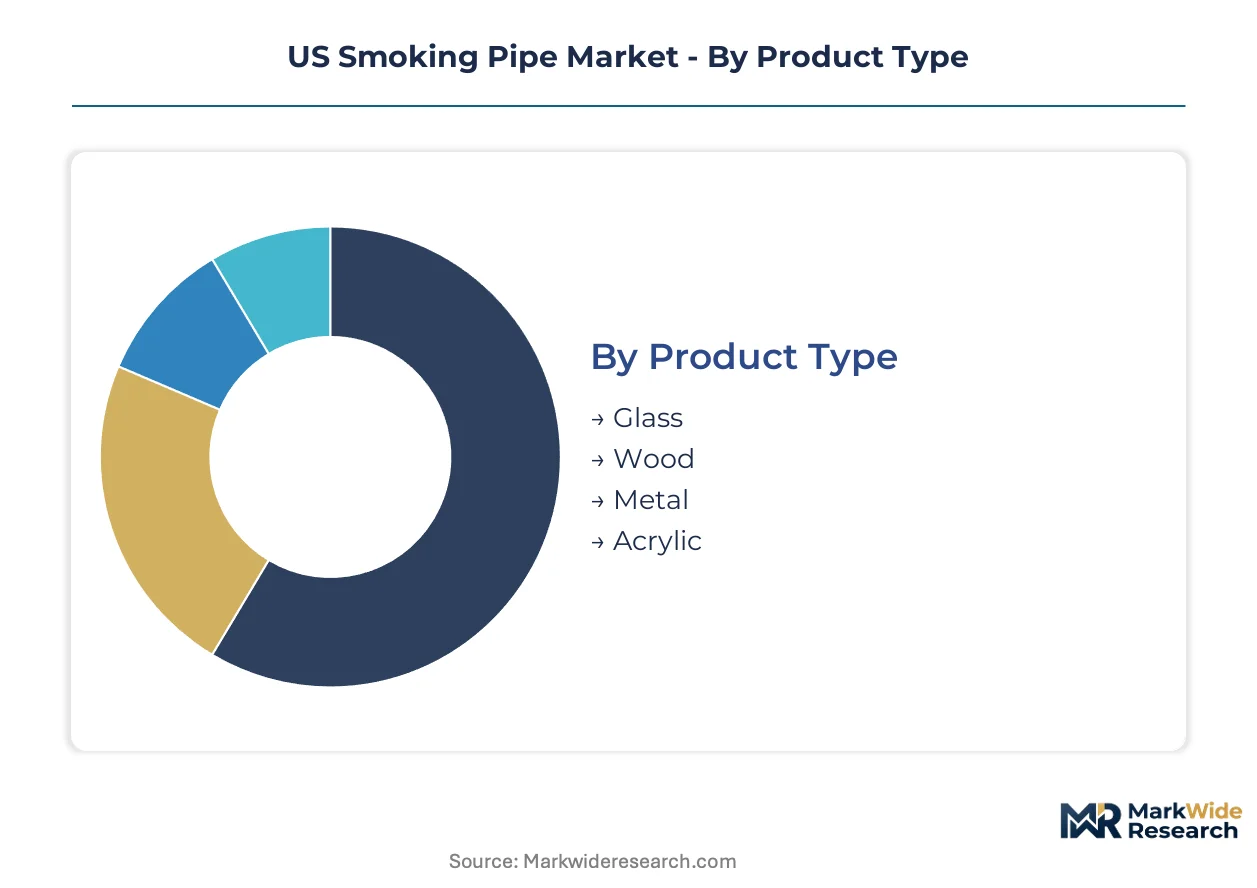
Segmentation in the US smoking pipe market reveals how material preferences, user intent, and price sensitivity fragment demand across incompatible channels. Glass pipes dominate dispensary retail while wood sustains tobacconist loyalty, with collectors and recreational users rarely overlapping in purchase behavior.
Product Type:
Material selection dictates thermal performance, maintenance requirements, and regulatory exposure for end-users navigating FDA oversight and state cannabis frameworks.
- Glass:Borosilicate construction delivers thermal shock resistance and visual cleanliness prized in Michigan and Illinois dispensary channels. Recreational cannabis legalization in these states accelerates demand through dedicated retail networks that prioritize sanitation transparency and customization options.
- Wood:Mediterranean briar and domestic hardwoods provide natural heat absorption and patina development valued by traditional pipe smokers. Southeast regional loyalty concentrates demand in North Carolina and Virginia brick-and-mortar tobacconists where heritage consumption rituals sustain premium positioning against glass alternatives.
- Metal:Aluminum and stainless steel alloys offer durability and portability for outdoor use cases with minimal breakage risk.
- Acrylic:Polycarbonate and resin compounds deliver entry-level price accessibility with color customization appealing to casual experimentation.
Glass leads on scale through cannabis retail expansion; wood leads on momentum through artisanal collector premiums.
User Type:
Procurement authority separates bulk purchasing decisions from individual consumption patterns, with retailers and collectors operating on fundamentally different margin structures and inventory turnover expectations.
- Recreational Users:Individual consumers purchasing through dispensary and headshop channels prioritize immediate availability and visual aesthetics over longevity. State cannabis frameworks in expanding markets like Illinois drive volume concentration through licensed retail infrastructure.
- Collectors:Limited-edition acquisition and estate pipe trading concentrate demand on provenance documentation and condition grading. Southern appraisal specialists now control pricing power as auction platforms disintermediate traditional tobacconist networks.
- Medical Users:Therapeutic consumption patterns prioritize dosing consistency and material safety documentation under state medical cannabis programs.
- Retailers:Inventory procurement decisions balance turn velocity against margin preservation across tax-variable jurisdictions like North Carolina versus New York.
Recreational users anchor volume throughput; collectors command margin extraction.
Size:
Chamber diameter and overall length determine portability constraints, session duration, and storage requirements that segment users across mobile versus ritual consumption contexts.
- Small:Pocket-dimension designs with chamber diameters below 0.75 inches suit discrete transport and brief consumption windows.
- Medium:Standard 0.75 to 1.0 inch chambers balance session length with handheld ergonomics for daily use.
- Large:Extended bowls above 1.0 inch accommodate prolonged sessions and social sharing contexts.
- Extra Large:Statement pieces exceeding 1.5 inches serve display and ceremonial functions with limited practical portability.
Medium dimensions dominate unit economics; small formats gain share fastest through urban portability demands.
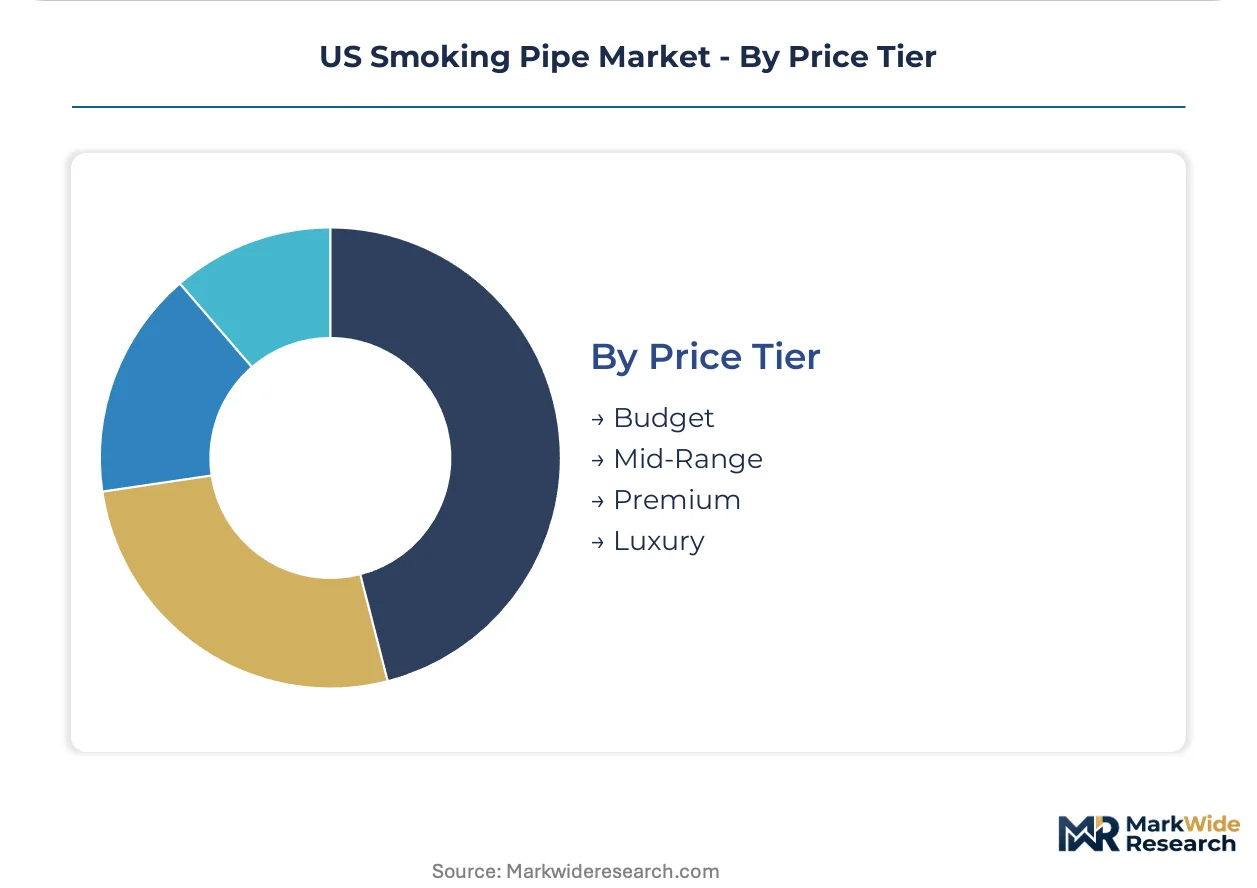
Price Tier:
Cost stratification reflects material certification, craftsmanship intensity, and distribution channel markup structures that separate mass retail from artisan-direct procurement.
- Budget:Standardized production lines from Dr. Grabow and import manufacturers dominate drugstore and convenience placement. Volume accessibility sustains market presence despite thin margins and minimal brand differentiation.
- Luxury:Limited artisan releases and estate provenance command four-figure price points through direct-to-consumer auction platforms. Instagram and TikTok storefronts bypass wholesale markups while concentrating pricing power with condition-grading expertise.
- Mid-Range:CNC-machined briar and branded glass occupy specialty retail with standardized tolerances and moderate customization.
- Premium:Hand-finished bowls and certified Mediterranean briar sourcing elevate positioning through REACH compliance documentation and heritage narratives.
Budget tiers capture transaction frequency; luxury tiers capture value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington County anchors domestic pipe production through Missouri Meerschaum Company's century-old corncob manufacturing complex. FDA tobacco oversight and state cannabis frameworks reshape demand geography across distinct regional clusters.
Southeast
Traditional pipe-smoking culture sustains brick-and-mortar tobacconist density in North Carolina and Virginia. State excise tax variations between North Carolina and neighboring jurisdictions create arbitrage-driven distribution patterns. Richmond and Raleigh-Durham clusters concentrate estate pipe appraisal expertise that now controls auction platform pricing power.
Midwest
Heritage craft revival centers on Missouri's corncob pipe manufacturing authenticity. Iowa and Illinois recreational cannabis legalization accelerates glass pipe demand through dispensary retail infrastructure. Chicago and St. Louis serve as dual distribution nodes for both traditional wood and borosilicate product flows.
Northeast
High state excise taxes in New York and Massachusetts compress retail margins and shift procurement toward cross-border channels. New York City's collector community drives direct-to-consumer auction volume for limited artisan releases. FDA marketing restriction enforcement concentrates compliance advisory services in Boston and Philadelphia legal corridors.
West
Colorado and California cannabis frameworks mature glass pipe retail through established dispensary networks. Portland and Seattle clusters specialize in heat-resistant glass customization for recreational user segments. REACH-compliant Mediterranean briar importation flows through Los Angeles customs districts for West Coast artisan manufacturers.
US Smoking Pipe Market Competitive Landscape
Global majors compete with regional champions across material specialization and distribution channel access. The vendor base separates into Irish-imported craftsmanship networks, domestic heritage manufacturers, and standardized volume producers. Three archetypes dominate: heritage-authenticity anchors, import-craft specialists, and drugstore-accessibility leaders. Capacity consolidation and artisan-direct e-commerce represent the dominant competitive moves reshaping channel economics.
Among domestic heritage manufacturers, Missouri Meerschaum Company occupies a position exemplifying century-old corncob authenticity. Dr. Grabow Pipes represents the standardized production archetype with drugstore and convenience retail dominance. Peterson Pipes, despite Irish origins, anchors the import-craft specialist tier through dedicated US distribution infrastructure.
| Leading Market Players |
|---|
| Missouri Meerschaum Company |
| Dr. Grabow Pipes |
| Peterson Pipes |
| Dunhill |
| Savinelli |
| Stanwell Pipes |
| Charatan |
| Baraccini Pipes |
| Castello |
| Others |
Pricing and Supply Chain Analysis
Collector procurement concentration among Southern estate pipe appraisal specialists anchors premium pricing power through condition-grading expertise that bypasses traditional wholesale markups. This buyer-archetype dominance forces mid-tier manufacturers to absorb Mediterranean briar cost volatility while luxury artisans capture margin through direct auction platform access.
Pricing Analysis
Input-cost pass-through from REACH-compliant Mediterranean briar certification elevates premium tier positioning while standardized CNC production compresses mid-range margins. Price differentiation hinges on heritage craftsmanship documentation and FDA compliance tier status. Cost compression in the budget segment intensifies as borosilicate glass substitution erodes wood bowl demand. Recreational users through Illinois and Michigan dispensary channels exhibit highest price sensitivity; collectors demonstrate least sensitivity due to provenance-driven acquisition logic.
Supply Chain Analysis
Single-source vulnerability sits with Mediterranean briar harvesting regions where aging master craftsmen concentrate bowl-turning skills without US knowledge transfer pipelines. Raw material flows draw from Italy, Greece, and Algeria for certified wood; borosilicate glass feeds from domestic Midwest manufacturing. Tariff exposure on Irish-imported craftsmanship through dedicated US distribution channels threatens import-craft specialist margins. Distribution runs through dual nodes: Chicago and St. Louis coordinate traditional wood and glass product flows to Southeast tobacconists and Midwest dispensaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Smoking Pipe Market functions as a stable compounder where heritage craft revival and state cannabis legalization frameworks generate steady demand expansion across incompatible user segments.
For Market Incumbents: Acquire Southern estate pipe appraisal expertise to control auction platform pricing power before digital channels fully disintermediate traditional tobacconist networks. Consolidate REACH-compliant Mediterranean briar sourcing relationships to defend against raw material concentration risks. FDA marketing restriction navigation demands dedicated compliance advisory capacity in Boston and Philadelphia legal corridors. For New Entrants and Emerging Players: The mid-range price-point gap between Missouri Meerschaum heritage positioning and Dr. Grabow standardized volume accessibility offers white-space entry through CNC-machined customization. Target Southeast regional brick-and-mortar density in North Carolina and Virginia where digital channel penetration remains weakest. Launch through Instagram and TikTok storefronts to bypass wholesale markups on limited artisan releases. For Investors and Strategic Acquirers: Heritage consumer goods companies with craft beverage or artisan tobacco portfolios represent the most active acquirer in this space. Five-to-ten year viability rests on FDA regulatory clarity and state cannabis framework maturation. Monitor federal cannabis reclassification debates as the critical inflection signal for glass pipe demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Craft Certification Program | REACH-compliant Mediterranean briar documentation elevates premium positioning among collector segments. |
| Direct-to-Consumer Auction Platform | Southern appraisal specialists capture pricing power as estate pipe trading disintermediates traditional tobacconists. |
| State Compliance Inventory Segregation | Glass pipe importers preempt FDA seizure risk through jurisdiction-specific distribution protocols. |
| CNC Machining Standardization | Precision tolerance specifications compress artisan lead times from weeks to days for mid-tier production. |
| Excise Tax Arbitrage Infrastructure | Interstate redistribution margin capture exploits variations between North Carolina and New York tax regimes. |
Research Methodology
Direct dialogue with artisan pipe manufacturers, estate pipe appraisal specialists, dispensary procurement managers, and FDA regulatory affairs consultants grounded qualitative insights in operational reality. Secondary validation drew from FDA Deeming Rule documentation, state excise tax jurisdiction records, REACH certification databases, and US customs import filings. Bottom-up demand modeling across user segments triangulated against top-down market sizing from production capacity assessments.
Segmented outputs across material type, user archetype, chamber dimension, and price tier populated the analytical framework across the projection horizon. CAGRs derived from regression analysis against historical Mediterranean briar supply cycles and state cannabis legalization adoption curves. Forecast inputs incorporated FDA compliance cost trajectories and digital channel penetration rates for collector procurement behavior.
The model assumes a particular technology adoption path; alternative pathways for precision CNC machining displacement of hand-carving would alter the outlook. Forecasts reflect documented assumptions about regulatory stability and raw material supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Lighter Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
North America Cigarette Lighter Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
Electric Pocket Lighter Market