
 Japan Smoking Accessories Market | 2026-2036
Japan Smoking Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Smoking Accessories Market Insights
A shift from single-source procurement to multi-source supplier networks is rebalancing how Japanese distributors secure smoking accessories inventory. Japan Tobacco Inc leverages its domestic manufacturing footprint to control premium lighter supply chains. S.T. Dupont competes on artisan metalwork credentials in the collector segment. Jinlin (HK) Smoking Accessories Co., Ltd. anchors budget-tier plastic ashtray availability through convenience store channels.
Japan smoking accessories encompass functional and ornamental goods including lighters, ashtrays, cigarette cases, and rolling papers, typically manufactured from metal alloys, borosilicate glass, or engineered plastics with ignition temperature tolerances exceeding 800°C for flame-producing devices. These items serve both utilitarian consumption needs and luxury gifting occasions in Japan's established tobacco culture. Lighters and ashtrays generate the dominant revenue share within product type segmentation, while glass and metal materials command superior margins due to craftsmanship premiums and durability expectations. Online retail channels are expanding fastest among distribution pathways, though specialty shops retain the highest per-transaction values through curated collector-oriented merchandising.
PMDA oversight of heated tobacco product classifications indirectly shapes accessory compatibility standards, while JIS mark requirements govern metal lighter safety specifications and child-resistance mechanisms. METI energy efficiency guidelines additionally influence electronic ignition device designs entering the Japanese market. Stakeholders must monitor how PMDA regulatory updates on next-generation tobacco products redefine accessory interface standards and compatibility obligations.
Market Dynamics
Heated tobacco device proliferation is fragmenting demand across traditional flame-based accessories and electronic-compatible formats, forcing manufacturers to dual-track their product development pipelines.
Growth Catalysts
- Heated tobacco compatibility standards:METI's evolving product safety protocols for electronic ignition devices are creating certified supplier tiers that command premium positioning in Tokyo and Osaka specialty channels.
- Collector segment concentration:Urban prefectures sustain higher-margin artisan metalwork demand through established smoking lounge cultures that prioritize craftsmanship credentials.
- Multi-source procurement normalization:Japanese distributors are diversifying supplier networks beyond single-source dependencies, expanding inventory flexibility for borosilicate glass and engineered plastic categories.
Market Restraints
- Input cost volatility in metal alloys:Nickel and brass price fluctuations compress margin stability for domestic lighter manufacturers dependent on imported raw materials.
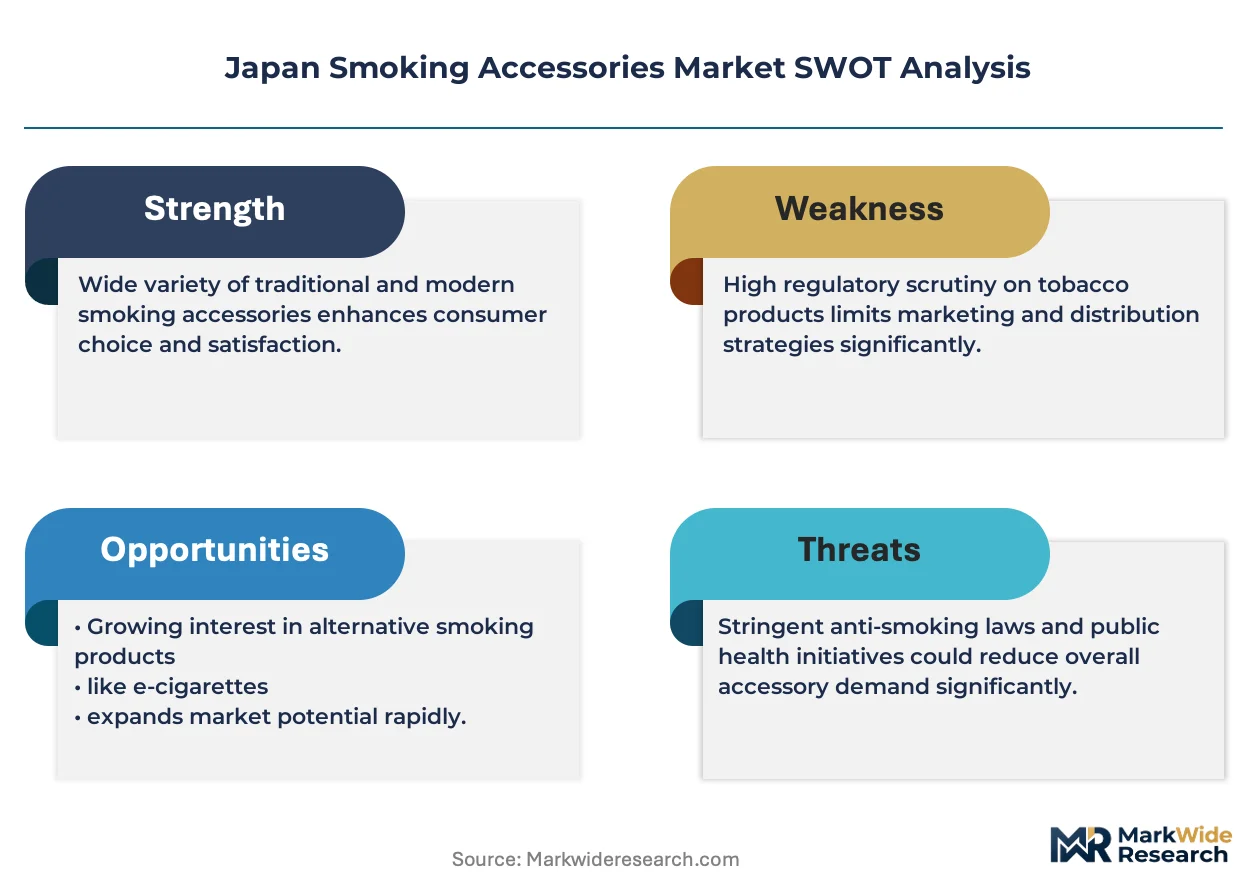
- PMDA classification friction:Ambiguous heated tobacco accessory boundaries create compliance uncertainty that delays product launches and inflates regulatory consulting expenditures.
- Substitution pressure from device-integrated solutions:Tobacco heating units with built-in ignition mechanisms reduce standalone lighter necessity among younger demographic cohorts.
Strategic Opportunities
- Hokkaido and Kyushu penetration gaps:Rural prefectures remain underserved by premium glass and metal accessory distribution, presenting whitespace for curated specialty shop expansion.
- Online channel infrastructure:Digital retail pathways are expanding fastest among distribution modes, enabling direct-to-collector relationships that bypass traditional wholesale markups.
- JIS certification premiumization:Child-resistance mechanism compliance is becoming a voluntary quality signal that separates premium positioning from convenience-tier alternatives.
Industry Challenges
- Artisan metalwork skill scarcity:Master craftsmen capable of S.T. Dupont-grade finishing are aging out of the workforce without sufficient apprenticeship pipeline replacement.
- Dual-format inventory complexity:Maintaining parallel stock for flame-based and electronic-compatible accessories strains working capital and forecasting accuracy.
- Legacy retail relationship renegotiation:Convenience store channel partners resist shelf-space reallocation toward higher-margin collector-oriented merchandise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Smoking Accessories Market |
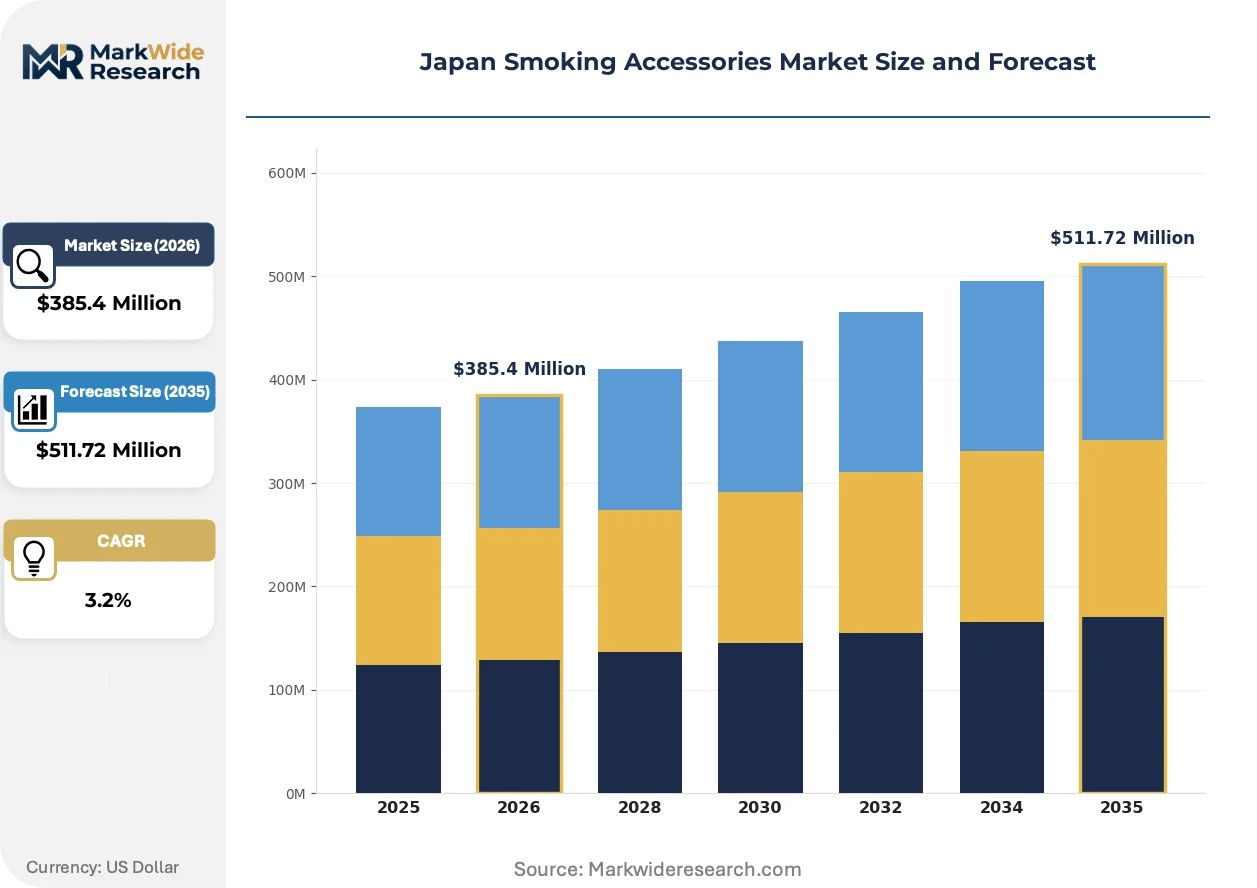
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $511.72 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarette Cases, Lighters, Ashtrays, Rolling Papers Material: Plastic, Wood, Metal, Glass Distribution Channel: Online Retail, Convenience Stores, Specialty Shops, Supermarkets Customer Type: Smokers, Collectors, Retailers, Wholesalers |
| Companies Covered | Japan Tobacco Inc, British American Tobacco PLC, Imperial Brands PLC, Philip Morris International Inc, Altria Group Inc, Scandinavian Tobacco Group A/S, Vector Group Ltd, Jinlin (HK) Smoking Accessories Co., Ltd., S.T. Dupont, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Smoking Accessories Market Trends and Innovations
Accessory design is bifurcating between utilitarian heated tobacco compatibility and ornamental craft preservation, with material science and regulatory compliance serving as the primary innovation vectors.
Borosilicate glass manufacturing is modularizing around temperature-specific performance tiers, enabling Tokyo-based specialty shops to curate collections by ignition tolerance rather than aesthetic category alone. Collector buyers are segmenting purchases across 800°C-rated functional pieces and lower-tolerance display objects. This technical stratification is compressing undifferentiated mid-market glass positioning.
METI energy efficiency guidelines are redirecting electronic ignition device designs toward lower-consumption architectures, particularly affecting battery-powered lighter formats entering the Japanese market. Manufacturers must now balance JIS safety specifications with power draw optimization. The Kansai region's manufacturing clusters are responding fastest due to proximity to compliance testing infrastructure.
Smoking lounge culture is sustaining demand rotation toward ceremonial consumption occasions, with Fukuoka and Nagoya hospitality venues driving bulk procurement of artisan ashtrays for private room installations. Traditional gift-giving occasions remain intact, though younger buyers are compressing decision cycles through digital discovery channels rather than physical specialty shop browsing. This behavioral shift is most visible in Tokyo's Shibuya and Shinjuku wards where lounge density concentrates.
Japan Smoking Accessories Market Segmentation
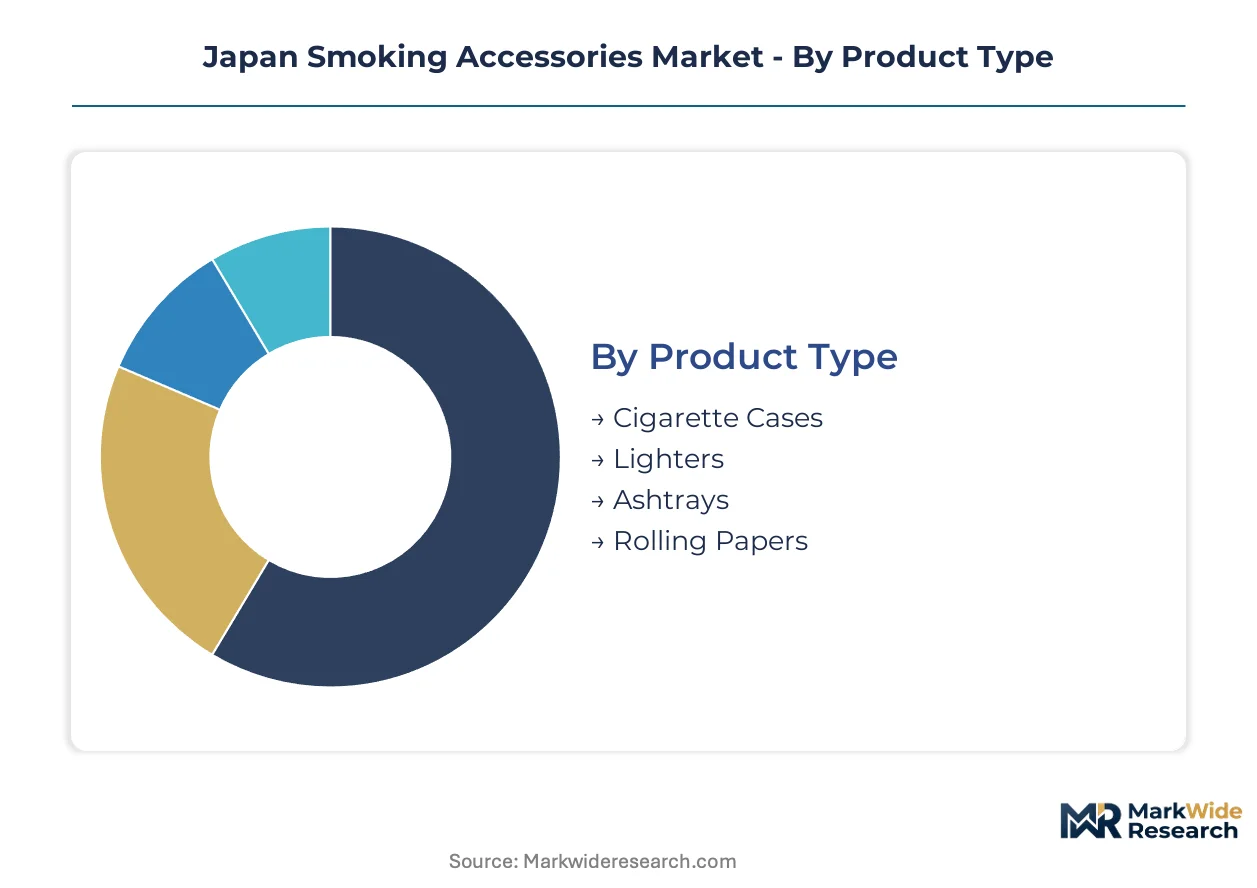
Segmentation in Japan's smoking accessories market reveals how regulatory frameworks and distribution infrastructure shape profitability across distinct buyer categories. Certification requirements from METI and PMDA create tiered compliance burdens that filter which segments can access premium channels versus mass-market retail.
Product Type:
JIS safety specifications and PMDA heated tobacco compatibility standards impose differentiated certification costs across functional categories, with ignition devices facing the most stringent testing protocols.
- Lighters:Flame-producing devices manufactured from metal alloys with ignition temperature tolerances exceeding 800°C require JIS mark certification for child-resistance mechanisms. Demand concentrates in Tokyo and Osaka specialty shops where collector buyers prioritize artisan metalwork credentials from domestic manufacturers.
- Ashtrays:Borosilicate glass and engineered metal formats serve both utilitarian consumption and ceremonial hospitality applications. Fukuoka and Nagoya smoking lounges drive bulk procurement of premium artisan pieces for private room installations, sustaining higher-margin sales despite input cost volatility in nickel and brass.
- Cigarette Cases:Functional and ornamental storage solutions typically utilizing metal alloys or leather composites. Cases face lighter regulatory burden than ignition devices, enabling faster product launch cycles.
- Rolling Papers:Consumable paper products with minimal compliance requirements beyond general product safety standards. Convenience store channels dominate volume distribution.
Leading the category by volume: Lighters. Growing fastest: Ashtrays.
Material:
Raw material sourcing patterns determine which formats can achieve JIS certification and access Tokyo-Osaka specialty retail versus convenience store distribution.
- Metal:Nickel and brass alloys command craftsmanship premiums in collector segments but face margin compression from import dependency and price volatility. Master metalworkers capable of S.T. Dupont-grade finishing are aging out without sufficient apprenticeship pipeline replacement.
- Glass:Borosilicate manufacturing modularizes around temperature-specific performance tiers, enabling technical stratification between 800°C-rated functional pieces and lower-tolerance display objects. This differentiation is compressing undifferentiated mid-market positioning.
- Plastic:Engineered polymers anchor budget-tier ashtray availability through convenience store channels with minimal regulatory friction.
- Wood:Ornamental and ceremonial applications in traditional gift-giving occasions, though volume remains constrained by durability expectations and maintenance requirements.
Metal captures the highest per-unit margins. Glass is expanding most quickly through online direct-to-collector channels.
Distribution Channel:
Channel selection dictates which customer segments manufacturers can reach and whether JIS certification serves as mandatory compliance or voluntary quality signaling.
- Specialty Shops:Curated collector-oriented merchandising in Tokyo and Osaka generates the highest per-transaction values. These channels require full JIS compliance and reward craftsmanship credentials with premium positioning.
- Online Retail:Digital pathways are expanding fastest among distribution modes, enabling direct relationships that bypass traditional wholesale markups. Younger buyers in Shibuya and Shinjuku wards compress decision cycles through digital discovery.
- Convenience Stores:Volume-focused channels resist shelf-space reallocation toward higher-margin merchandise, favoring standardized plastic and budget metal formats.
- Supermarkets:Mass-market retail with limited SKU depth, primarily serving utilitarian replacement purchases rather than collector demand.
Specialty shops dominate revenue per transaction. Online retail is gaining share fastest.
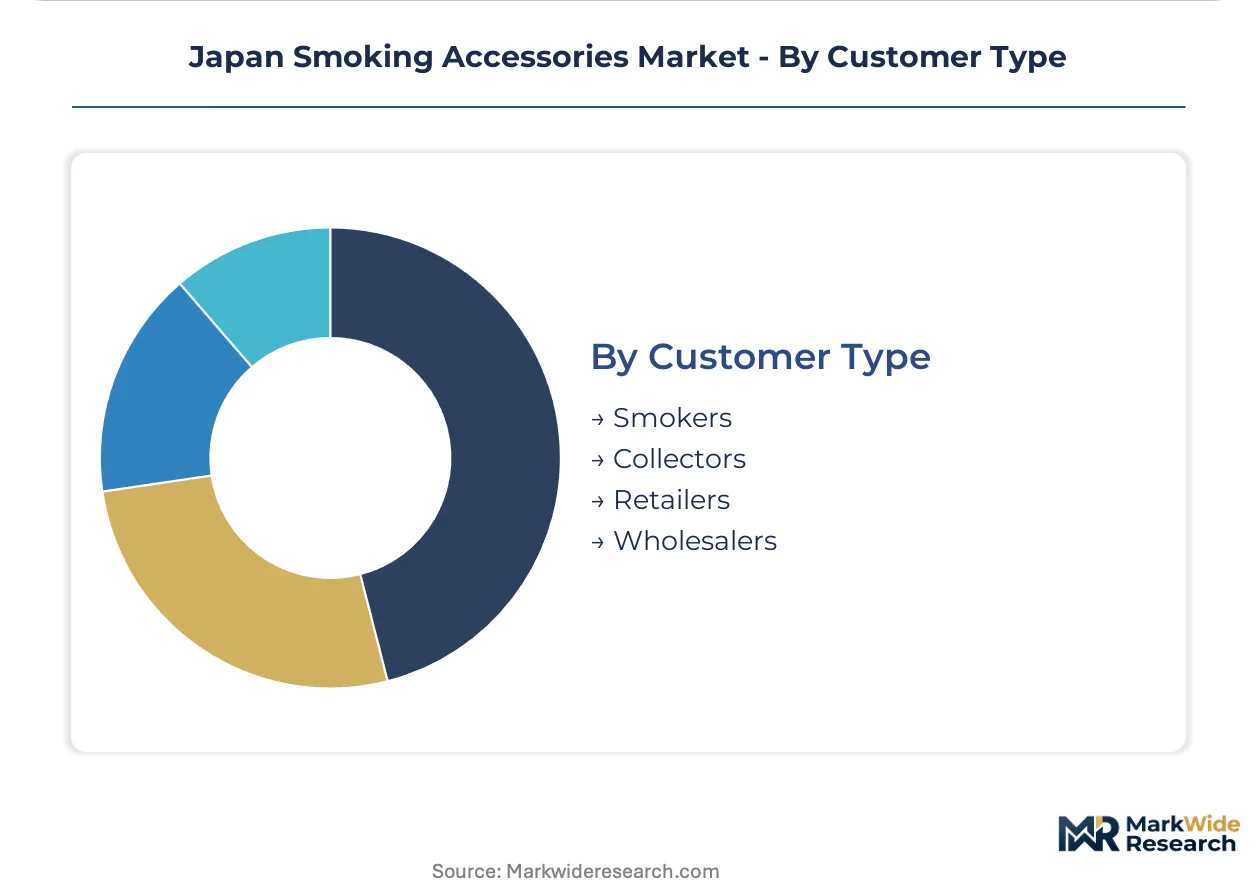
Customer Type:
Buyer identity determines price elasticity, purchase frequency, and sensitivity to METI energy efficiency guidelines versus ornamental craftsmanship.
- Collectors:Credential-focused buyers prioritizing artisan metalwork and limited-edition releases. This segment sustains higher-margin glass and metal sales through smoking lounge culture and gift-giving occasions.
- Smokers:Functional utilitarian demand split between traditional flame-based accessories and heated tobacco-compatible formats, forcing dual-track inventory complexity.
- Retailers:Inventory procurement decisions increasingly favor multi-source supplier networks to reduce single-source dependency risks.
- Wholesalers:Traditional distribution intermediaries facing margin pressure from online channel disintermediation and direct manufacturer-collector relationships.
Collectors generate the highest margins per transaction. Smokers represent the largest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban prefectures concentrate Japan's smoking accessories demand through established smoking lounge cultures and collector-oriented specialty retail channels. Regional variation reflects uneven distribution of METI compliance infrastructure and proximity to domestic manufacturing clusters.
Kanto/Tokyo
Tokyo's Shibuya and Shinjuku wards anchor the highest per-transaction values through curated specialty shop density and digital-native buyer concentration. METI's product safety testing facilities in the capital accelerate JIS certification timelines for domestic manufacturers. The Kanto manufacturing belt supplies premium metal alloy lighters to collector segments prioritizing artisan credentials.
Kansai/Osaka
Osaka specialty channels compete with Tokyo on collector-oriented glass and metal curation while leveraging lower commercial real estate costs. Proximity to Kansai-based compliance testing infrastructure enables faster electronic ignition device prototyping under METI energy efficiency guidelines. The region's hospitality sector drives bulk procurement of ceremonial ashtrays for private smoking lounge installations.
Chubu/Nagoya
Nagoya's industrial base supports precision metalworking for JIS-certified child-resistance mechanisms in premium lighter manufacturing. Local distributors are normalizing multi-source procurement networks to reduce single-source dependency risks. The sub-region's manufacturing clusters respond fastest to PMDA regulatory updates on heated tobacco accessory compatibility standards.
Kyushu
Fukuoka's smoking lounge culture sustains higher-margin artisan ashtray demand despite limited specialty shop penetration compared to eastern prefectures. The sub-region remains underserved by premium glass and metal distribution, presenting whitespace for curated retail expansion. Local hospitality venues drive ceremonial consumption occasions through bulk procurement of ornamental pieces.
Hokkaido
Sapporo's urban center concentrates regional demand while rural areas lack premium accessory distribution infrastructure. Cold climate patterns sustain indoor smoking lounge utilization rates above national averages. The sub-region's isolation from Kanto and Kansai compliance testing centers extends product launch timelines for electronic-compatible formats.
Japan Smoking Accessories Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers dual-track development for flame-based and heated tobacco-compatible formats. The vendor base stratifies across domestic tobacco conglomerates with captive manufacturing, European luxury metalwork specialists, and Asian contract producers serving mass-market channels. Three archetypes define positioning: vertically integrated domestic incumbents controlling premium supply chains, European artisan brands credentialing collector segments, and volume-focused Asian fabricators anchoring convenience retail. Competitive intensity centers on JIS certification acquisition and direct-to-collector online channel development.
Within the domestic incumbent tier, Japan Tobacco Inc leverages its manufacturing footprint to control premium lighter supply chains and influence distributor procurement patterns. Among European specialists, S.T. Dupont occupies a position exemplifying artisan metalwork credentials in collector-oriented channels. On the volume-driven end, Jinlin (HK) Smoking Accessories Co., Ltd. anchors budget-tier plastic ashtray availability through convenience store networks. These three represent the structural poles around which competitive positioning organizes: captive supply control, craftsmanship premiumization, and mass-market scale.
| Leading Market Players |
|---|
| Japan Tobacco Inc |
| British American Tobacco PLC |
| Imperial Brands PLC |
| Philip Morris International Inc |
| Altria Group Inc |
| Scandinavian Tobacco Group A/S |
| Vector Group Ltd |
| Jinlin (HK) Smoking Accessories Co., Ltd. |
| S.T. Dupont |
| Others |
Pricing and Supply Chain Analysis
Family-owned metalworking specialists in Osaka and Tokyo anchor premium lighter manufacturing, their generational ownership patterns enforcing pricing discipline through limited production runs and JIS certification investments. These tightly held operations resist volume discounting, preserving margin structures that multinational entrants struggle to replicate without equivalent artisan credentialing.
Pricing Analysis
Volume concentrates in plastic ashtrays and convenience-tier lighters while margins accrue to certified metal and borosilicate glass formats. Pricing stratifies across JIS-certified premium tiers, artisan craftsmanship premiums, and economy plastic segments. Cost compression in nickel and brass alloys is intensifying because import dependency exposes domestic fabricators to commodity volatility. Convenience store buyers exhibit highest price sensitivity; collector segments demonstrate lowest elasticity, prioritizing provenance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Tokyo and Osaka distributors now mandate multi-supplier qualification for both metal alloy and glass component procurement. Manufacturing draws from Japan's Kanto and Kansai clusters, with brass and nickel inputs sourced from China and South Korea. Single-source vulnerability persists in master craftsman availability for S.T. Dupont-grade finishing. Distribution runs through specialty shop curation for premium tiers, convenience store networks for volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive control over JIS-certified manufacturing and direct-to-collector digital channels determines sustainable margin capture.
For Market Incumbents: Extend proprietary artisan networks through apprenticeship pipeline investments before master metalworker retirement accelerates. Secure exclusive borosilicate glass sourcing agreements with Osaka-based specialty distributors to preempt new entrant shelf access. Heated tobacco device proliferation threatens flame-based accessory volumes; dual-format inventory hedges obsolescence risk. For New Entrants and Emerging Players: Launch via online direct-to-collector channels bypassing wholesale markups that incumbent relationships have locked. Hokkaido and rural Kyushu present penetrable whitespace where specialty shop density lags Tokyo-Osaka concentration. Digital-native discovery platforms compress decision cycles for younger demographic cohorts seeking ceremonial consumption objects. For Investors and Strategic Acquirers: Distressed-cycle entries favor JIS-certified mid-cap fabricators in Kansai manufacturing clusters where generational succession failures create acquisition availability. Long-term viability hinges on heated tobacco compatibility pivot capacity and online channel infrastructure ownership. METI regulatory updates on electronic ignition standards signal inflection timing for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Acquisition | Child-resistance compliance separates premium positioning from convenience-tier alternatives in Tokyo specialty channels. |
| Direct-to-Collector Digital Launch | Online retail expansion bypasses wholesale intermediaries and captures higher per-transaction values from credential-focused buyers. |
| Artisan Apprenticeship Pipeline | Master metalworker replacement secures S.T. Dupont-grade finishing capabilities against generational skill attrition. |
| Dual-Format Product Development | Parallel flame-based and heated tobacco-compatible pipelines hedge against device substitution pressure among younger smokers. |
| Hokkaido-Kyushu Distribution Expansion | Curated specialty shop penetration captures underserved rural premium demand with lower commercial real estate costs. |
Research Methodology
Trade association filings, METI product safety registrations, and PMDA heated tobacco device classifications formed the secondary backbone for market sizing and regulatory mapping. Primary interviews with specialty shop proprietors, convenience store category buyers, metal fabrication plant managers, and glass manufacturing technical directors validated demand patterns and supply constraints. Bottom-up segment enumeration triangulated against top-down trade flow analysis across the analysis window.
Historical trendline analysis established baseline growth trajectories for lighters, ashtrays, cigarette cases, and rolling papers by material tier and distribution channel. The projection framework modeled product type, material composition, customer archetype, and prefecture-level demand concentration throughout the forecast period. CAGR derivation incorporated input cost volatility assumptions for nickel and brass, METI energy efficiency guideline implementation timelines, and smoking lounge culture penetration rates.
PMDA classification ambiguity, nickel price volatility, and artisan metalworker retirement acceleration are the dominant revision risks to forecast outputs. Deviation in heated tobacco device adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
Smart E-Cigarettes Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
Pocket Lighter Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
Electric Pocket Lighter Market