
 Pod Vape Market | 2026-2036
Pod Vape Market Size, Share, and Industry Trends Forecast 2026-2036
Pod Vape Market Analytics
CE marking under the EU Tobacco Products Directive is unwinding competitive access for manufacturers lacking notified body certification. Philip Morris International leverages its IQOS pod platform and heated-tobacco R&D pipeline to sustain premium positioning in regulated European markets. British American Tobacco anchors its Vuse pod portfolio through convenience-store distribution scale across North America. JUUL Labs navigates FDA enforcement actions while competing on flavor-restricted pod formulations in the United States.
Pod vapes are compact, battery-powered aerosol devices that heat e-liquid contained in interchangeable or integrated cartridges, typically operating at 7–15 watts with coil resistances below 1.0 ohm to produce inhalable vapor for nicotine delivery or recreational use. Closed pod systems dominate volume in convenience retail due to user simplicity and manufacturer-controlled liquid formulations, while open pod systems capture enthusiast demand through customizable airflow and coil compatibility that expands margin pools for accessory sales. Flavor profiles concentrate in fruit and menthol variants where regulatory tolerance persists, though tobacco-flavored pods retain structural importance in markets with flavor restrictions.
The FDA's premarket tobacco product application process and the EU Tobacco Products Directive govern nicotine concentration limits, packaging standards, and marketing restrictions that directly shape product development cycles and retail availability. China's SAMR and national standards for e-cigarettes impose manufacturing licensing and additive disclosure requirements that affect export supply chains originating from Shenzhen manufacturing clusters. Stakeholders must monitor regulatory divergence between harm-reduction frameworks and youth-access prevention mandates to anticipate which pod formats and flavor categories will retain commercial viability.
Market Dynamics
The pod vape market is compressing around regulatory compliance velocity, where FDA premarket tobacco product application timelines and EU Tobacco Products Directive certification gates now determine which manufacturers retain shelf access versus those forced into market exit.
Growth Catalysts
- Harm-reduction policy frameworks:The UK's National Health Service smoking cessation pathways now explicitly endorse vaping as a cessation aid, channeling adult smokers toward regulated pod systems over combustible alternatives.
- Shenzhen manufacturing cluster concentration:China's SAMR licensing regime and GB 41700-2022 standards have consolidated production among certified exporters, creating supply-side scale economies that lower unit costs for compliant brands.
- Closed-system nicotine salt formulations:Protonated nicotine chemistry enables higher-concentration delivery at reduced harshness, expanding addressable demand among transitioning smokers who rejected earlier freebase nicotine devices.
Market Restraints
- Lithium-ion battery input volatility:Cobalt and lithium carbonate price swings from DRC and Chilean supply concentration compress hardware margins and complicate long-term device pricing strategies.
- FDA enforcement friction:Marketing denial orders and warning letter campaigns against non-PMTA-compliant products create inventory destruction risk and distributor liability exposure for retailers stocking gray-market devices.
- Heated-tobacco substitution threat:Philip Morris International's IQOS and British American Tobacco's glo platforms compete directly for the same adult smoker transition demographic with alternative aerosol technologies.
Strategic Opportunities
- German pharmacy channel expansion:The EU's most populous member state permits nicotine-containing e-cigarettes in regulated pharmacy retail, creating a compliance-premium channel absent in convenience-store dominant markets.
- Biometric age-verification integration:Fingerprint-locked pod devices paired with retail POS authentication systems address youth-access prevention mandates while differentiating premium hardware tiers.
- Tobacco-flavor R&D investment:Markets with flavor restrictions—Massachusetts, New Jersey, the EU—reward sophisticated tobacco-derivative formulations that replicate cigarette sensory profiles without crossing additive prohibition lines.
Industry Challenges
- Notified body certification timelines:EU Tobacco Products Directive compliance requires CE marking through accredited third-party assessors, where queue congestion extends product launch windows by 12-18 months.
- Supply chain reconfiguration friction:SAMR export licensing and additive disclosure requirements force Western brands to rebuild supplier relationships with Shenzhen manufacturers holding dual domestic-international certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pod Vape Market |
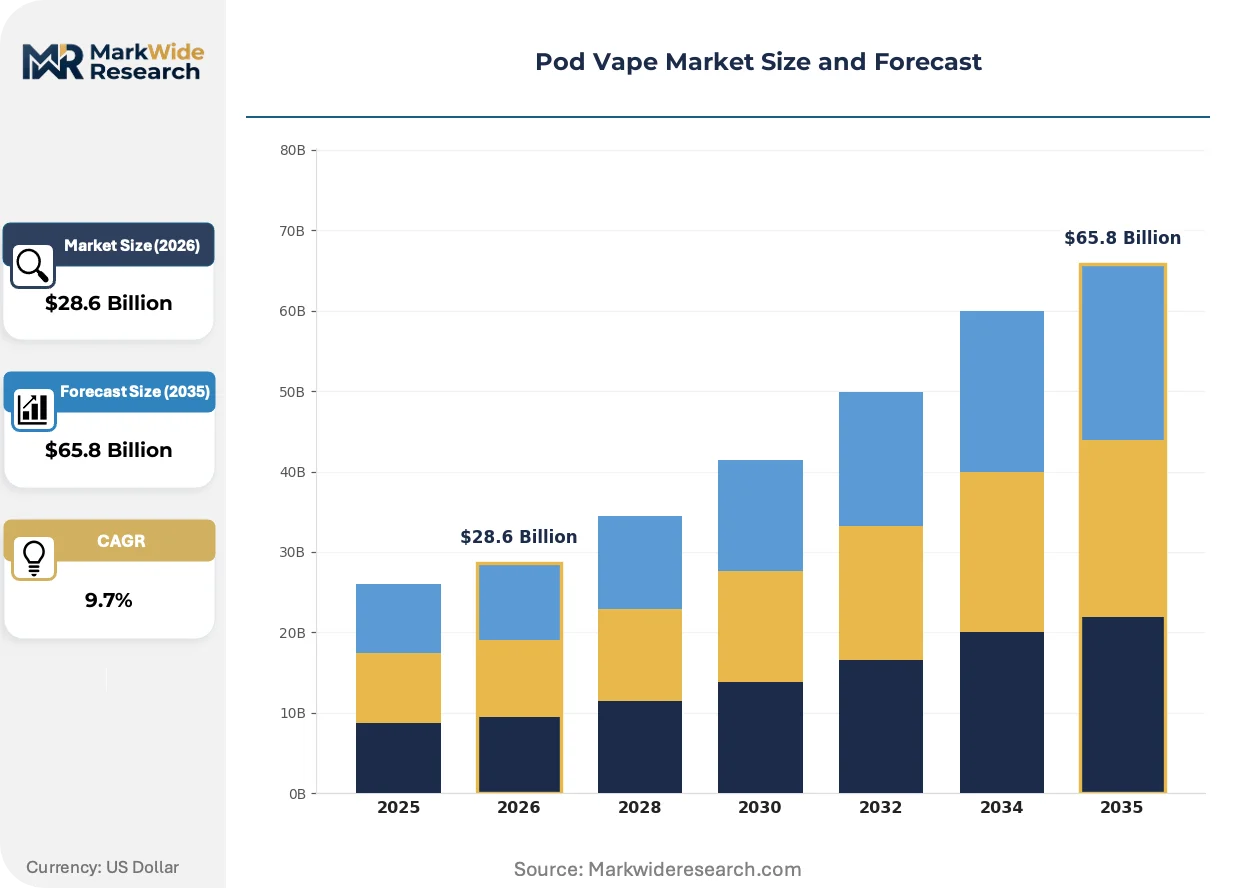
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Pod Systems, Open Pod Systems, Refillable Pods, Disposable Pods Flavor Profile: Tobacco, Menthol, Fruit, Dessert, Beverage Nicotine Strength: Zero Nicotine, Low Nicotine, Medium Nicotine, High Nicotine Distribution Channel: Online Retail, Specialty Vape Shops, Convenience Stores, Supermarkets |
| Companies Covered | Philip Morris International, British American Tobacco, Altria Group, JUUL Labs, SMOK, Vaporesso, Voopoo, Uwell, Innokin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pod Vape Market Evolving Landscape
Pod vape hardware and liquid chemistry are diverging along regulatory fault lines, with manufacturers pursuing distinct technical strategies for flavor-restricted versus flavor-permissive jurisdictions while integrating connected-device capabilities for compliance verification.
Ceramic coil heating elements are supplanting traditional cotton-wick metal coil architectures in premium closed pod systems. Adult smokers transitioning from combustibles prioritize consistent vapor temperature and reduced dry-hit incidence. The technology is supplanting legacy cotton-wick platforms in devices targeting the UK and EU premium segments where user experience differentiation commands retail price premiums.
REACH chemical registration and EU Tobacco Products Directive notification requirements are tightening additive disclosure and emissions testing protocols for e-liquid formulations. Manufacturers must submit toxicological dossiers for each flavor variant, compressing SKU proliferation and favoring large firms with dedicated regulatory affairs functions. The policy is reshaping competitive positioning in Germany, France, and the Netherlands where national enforcement of EU directives has accelerated.
Subscription-based auto-replenishment models are displacing traditional convenience-store purchase patterns among committed adult vapers. Direct-to-consumer platforms with integrated age-verification and compliance documentation capture recurring revenue streams. This behavioral shift concentrates in the United States and United Kingdom where e-commerce regulatory clarity permits nicotine product shipment subject to signature-verified delivery protocols.
Pod Vape Market Segmentation
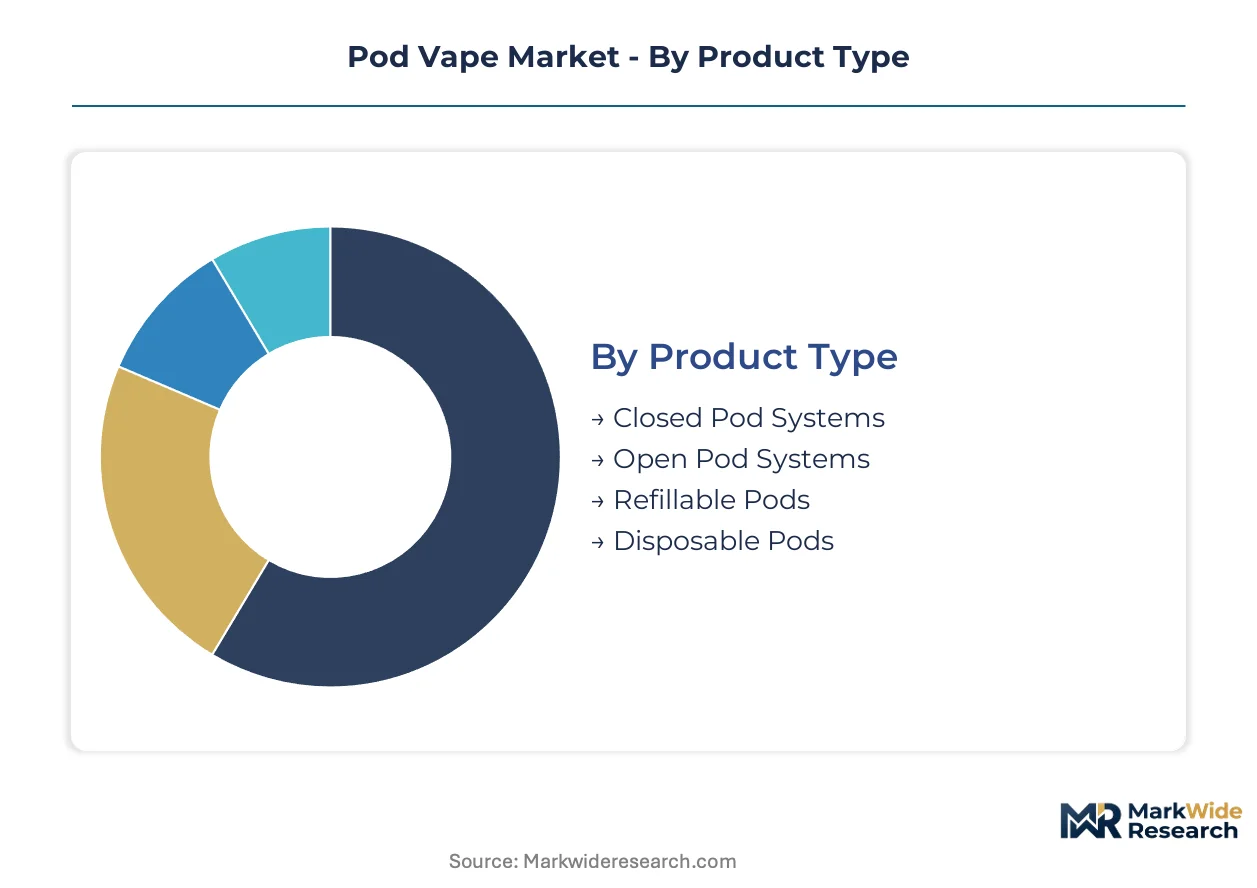
Pod vape segmentation reveals how regulatory pressure and channel economics fragment demand across hardware formats and liquid formulations. Manufacturers must align product architecture with specific jurisdiction requirements and retail access points to maintain commercial viability.
Product Type:
Closed pod systems flow through convenience retail chains where manufacturer-controlled liquid cartridges simplify compliance documentation. Open systems concentrate in specialty vape shops and direct-to-consumer channels where enthusiast customization drives accessory attach rates.
- Closed Pod Systems:Pre-filled, non-refillable cartridges integrate with proprietary battery devices. Demand concentrates in the United States and United Kingdom convenience-store networks where FDA and Medicines and Healthcare products Regulatory Agency traceability requirements favor manufacturer-sealed supply chains.
- Open Pod Systems:User-refillable reservoirs accommodate third-party e-liquids with adjustable airflow controls. Germany and France specialty retail channels show strongest volume as EU Tobacco Products Directive notification requirements push consumers toward established brands with toxicological dossier compliance.
- Refillable Pods:Modular cartridge designs accept repeated filling cycles with replaceable coil heads. Shenzhen manufacturing clusters supply the majority of hardware to European and North American markets.
- Disposable Pods:Single-use integrated devices with non-rechargeable batteries. UK pharmacy channel pilots and Nordic convenience retail show emerging placement.
Closed pod systems dominate installed base. Open pod systems are where expansion concentrates.
Flavor Profile:
Cost tier stratification separates premium synthetic formulations from standard tobacco derivatives, with flavor tolerance directly determining addressable geography.
- Tobacco:Standardized leaf-extract and synthetic formulations replicate combustible cigarette sensory profiles. Massachusetts and New Jersey markets mandate this category exclusively, while EU markets require additive disclosure under REACH registration protocols.
- Menthol:Cooling agents combined with tobacco or fruit bases. Regulatory tolerance persists in the United Kingdom and Germany despite EU-wide flavor restriction proposals.
- Fruit:Berry, citrus, and tropical synthetic flavor profiles. United States market access now requires FDA premarket tobacco product application authorization.
- Dessert:Vanilla, custard, and bakery-inspired formulations. Concentrates in online retail channels with age-verification protocols.
- Beverage:Coffee, cola, and cocktail-inspired variants. Limited retail presence outside specialty vape shop channels.
Tobacco and menthol categories anchor revenue stability. Fruit formulations are climbing the fastest where regulatory windows remain open.
Nicotine Strength:
Customer type segmentation separates transitioning smokers seeking cigarette-equivalent delivery from recreational users and cessation-focused consumers.
- High Nicotine:Protonated nicotine salt formulations at concentrations above 18mg/ml deliver cigarette-comparable absorption kinetics. United Kingdom National Health Service smoking cessation pathways explicitly endorse this tier for adult smoker transition.
- Medium Nicotine:6-12mg/ml freebase or salt formulations balance satisfaction with consumption reduction objectives. Germany pharmacy channel placement requires this concentration band for smoking cessation product classification.
- Low Nicotine:1-5mg/ml formulations support tapering protocols. Expanding most quickly in United Kingdom and Scandinavian markets with mature vaping populations.
- Zero Nicotine:Flavored e-liquid without alkaloid content. China domestic market shows concentration as GB 41700-2022 standards restrict nicotine-containing product marketing.
High nicotine commands volume share among transitioning smokers. Zero nicotine is gaining share fastest in Asia-Pacific regulatory environments.
Distribution Channel:
Geography determines channel viability, with national regulator stances on e-commerce nicotine shipment creating divergent retail structures.
- Convenience Stores:Impulse-access retail with limited SKU breadth and age-verification at point-of-sale. United States and United Kingdom volume concentrates here where tobacco retail licensing frameworks extend to vaping products.
- Specialty Vape Shops:Staff-assisted consultation with device troubleshooting and flavor sampling. France and Netherlands markets sustain this channel through national enforcement of EU Tobacco Products Directive retail registration requirements.
- Online Retail:Direct-to-consumer platforms with integrated age-verification and subscription auto-replenishment. United States and United Kingdom regulatory clarity permits signature-verified delivery protocols.
- Supermarkets:Mass-market retail with standardized planogram placement. German pharmacy-adjacent placement and Nordic grocery chains show emerging traction.
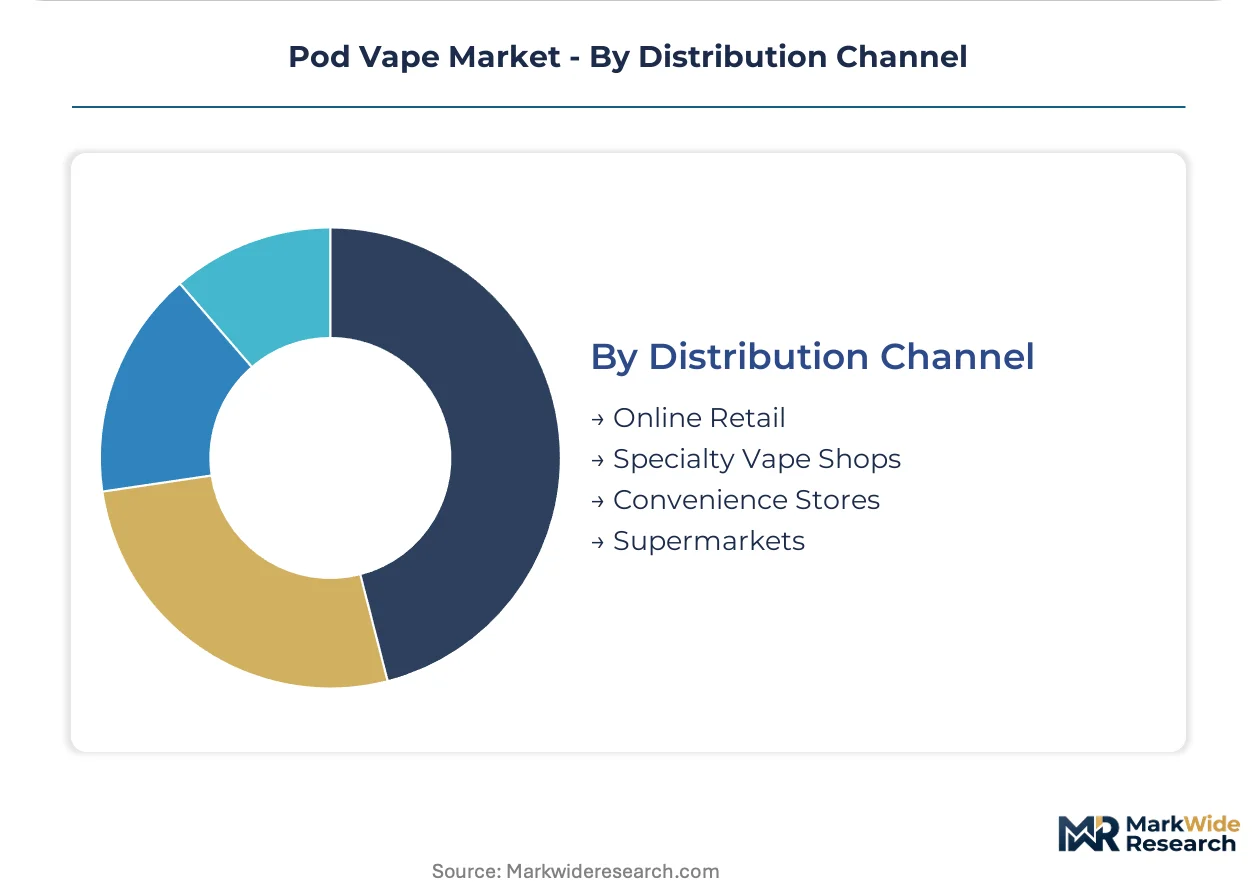
Convenience stores dominate transaction frequency. Online retail is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket tobacco product application requirements and EU Tobacco Products Directive certification gates are reshaping competitive access across major jurisdictions, concentrating viable manufacturing among notified-body-certified producers in Shenzhen, European notified body jurisdictions, and FDA-authorized US facilities.
United States
Adult smoker transition demand flows through convenience-store networks where tobacco retail licensing frameworks extend to vaping products. FDA marketing denial orders and warning letter campaigns against non-PMTA-compliant products create inventory destruction risk for retailers stocking gray-market devices. California and New York Metro markets sustain the highest volume concentration as state-level flavor restrictions fragment addressable demand between compliant tobacco-menthol formulations and contested fruit-variant enforcement zones.
United Kingdom
National Health Service smoking cessation pathways explicitly endorse vaping as a cessation aid, channeling adult smokers toward regulated pod systems with nicotine salt formulations above 18mg/ml. Medicines and Healthcare products Regulatory Agency traceability requirements favor manufacturer-sealed supply chains in convenience retail. London and Southeast England concentrate specialty vape shop density where staff-assisted consultation drives device troubleshooting and flavor sampling attach rates.
Germany
Pharmacy channel placement permits nicotine-containing e-cigarettes in regulated retail, creating a compliance-premium channel absent in convenience-store dominant markets. EU Tobacco Products Directive notification requirements and REACH chemical registration compress SKU proliferation among large firms with dedicated regulatory affairs functions. North Rhine-Westphalia and Bavaria sustain the strongest specialty retail volume as national enforcement of EU directives accelerates retail registration requirements.
China
SAMR licensing regime and GB 41700-2022 standards have consolidated production among certified exporters, creating supply-side scale economies that lower unit costs for compliant brands. Shenzhen manufacturing clusters supply the majority of hardware to European and North American markets as dual domestic-international certification becomes mandatory for export access. Pearl River Delta facilities dominate ceramic coil heating element production for premium closed pod systems targeting UK and EU premium segments.
France
National enforcement of EU Tobacco Products Directive retail registration requirements sustains specialty vape shop channels with staff-assisted consultation and flavor sampling. ANSM pharmaceutical regulator oversight intersects with EU-wide additive disclosure protocols, favoring established brands with toxicological dossier compliance. Île-de-France and Auvergne-Rhône-Alpes concentrate demand as REACH emissions testing protocols reshape competitive positioning toward large regulatory affairs functions.
Pod Vape Market Competitive Landscape
Listed leaders compete with private specialists across hardware manufacturing and liquid formulation segments, producing a tiered structure where scale-driven tobacco conglomerates anchor premium positioning while Shenzhen-based private specialists capture enthusiast customization demand. The vendor base separates into three strategic archetypes: multinational tobacco conglomerates with heated-tobacco R&D pipelines, dedicated vaping hardware specialists with Shenzhen manufacturing integration, and private-label assemblers serving regional distributor networks. Dominant competitive moves include notified body certification queue positioning for EU market retention and direct-to-consumer platform development with integrated age-verification protocols.
Within the multinational tobacco conglomerate tier, Philip Morris International and British American Tobacco exemplify archetypes leveraging IQOS and Vuse pod platforms to sustain premium positioning in regulated European markets. Among US-based specialists, JUUL Labs occupies a position navigating FDA enforcement actions while competing on flavor-restricted pod formulations. These three entities represent distinct strategic postures: heated-tobacco integration, convenience-store distribution scale, and regulatory compliance velocity under enforcement pressure.
| Leading Market Players |
|---|
| Philip Morris International |
| British American Tobacco |
| Altria Group |
| JUUL Labs |
| SMOK |
| Vaporesso |
| Voopoo |
| Uwell |
| Innokin |
| Others |
Value Network & Pricing Analysis
Ninety-day CE marking queues through European notified bodies compress pricing power for manufacturers without pre-positioned certification inventory, concentrating margin capture among Shenzhen exporters holding dual SAMR-EU accreditation while forcing uncertified competitors toward distressed pricing in gray-market channels.
Pricing Analysis
Certification level creates the primary spread between premium and value tiers, with FDA-authorized and CE-marked devices commanding retail premiums against uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and ceramic coil technology inclusion. Cost compression in the economy tier intensifies as Shenzhen manufacturing scale economies propagate through export channels. Convenience-store buyers exhibit highest price sensitivity, while pharmacy-channel purchasers accept compliance premiums for traceability documentation.
Supply Chain Analysis
Port congestion at Shenzhen-Yantian and Los Angeles-Long Beach trade lanes extends inbound logistics cycles for lithium-ion battery cells and ceramic heating substrates. Hardware production concentrates in China, South Korea, and Malaysia, drawing from cobalt DRC supply and Chilean lithium carbonate feedstocks. Single-source vulnerability sits with Malaysian chip packaging facilities serving coil control circuitry. Distribution runs through manufacturer-direct container programs to regional fulfillment centers bypassing distributor markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated convenience-store chains and pharmacy networks that now demand compliance documentation as table stakes, fragmenting negotiating leverage for uncertified manufacturers while concentrating volume commitments among dual-certified suppliers.
For Market Incumbents: Compound regulatory certification velocity into channel exclusivity by pre-positioning notified body queue slots for EU Tobacco Products Directive renewal cycles and SAMR license maintenance. Deepen backward integration into ceramic coil substrate production to defend margin position against lithium and cobalt input volatility. Heated-tobacco substitution from Philip Morris International and British American Tobacco demands accelerated nicotine salt formulation R&D to retain adult smoker transition demand.
For New Entrants and Emerging Players: Biometric age-verification hardware integration represents an under-served service layer where incumbents have under-invested, creating entry space for fingerprint-locked device architectures paired with retail POS authentication systems. German pharmacy channel expansion offers the most penetrable geography given compliance-premium pricing tolerance and limited incumbent presence. Direct-to-consumer subscription platforms with integrated age-verification provide the clearest go-to-market angle bypassing convenience-store gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational tobacco conglomerates seeking to divest non-core vaping assets under FDA enforcement pressure, particularly flavor-restricted pod portfolios requiring remediation investment. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone, favoring targets with dedicated toxicological dossier capabilities and notified body relationships. The signal to watch is FDA marketing denial order reversal rates as inflection indicator for enforcement trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Pre-Positioning | CE marking through accredited EU assessors secures pharmacy channel access in Germany and France. |
| Ceramic Coil Manufacturing Integration | In-house production of heating substrates reduces dependency on Malaysian packaging facilities. |
| Biometric Age-Verification Hardware Launch | Fingerprint-locked devices address youth-access mandates while differentiating premium tiers. |
| Pharmacy Channel Partnership Development | German regulatory framework permits nicotine product placement absent in convenience retail. |
| Subscription Auto-Replenishment Platform Buildout | Direct-to-consumer recurring revenue captures margin expansion beyond retail distribution. |
Research Methodology
Desk research of FDA premarket tobacco product application filings, EU Tobacco Products Directive notification databases, SAMR licensing registries, and Shenzhen customs export records preceded structured interviews with regulatory affairs directors at notified body consulting firms, procurement managers at US convenience-store chains, pharmacy category buyers in Germany, and ceramic coil substrate suppliers in the Pearl River Delta. Primary fieldwork with hardware manufacturers and liquid formulators combined with secondary validation against REACH chemical registration data and Medicines and Healthcare products Regulatory Agency traceability protocols. Bottom-up demand modeling across distribution channels triangulated against top-down market sizing from manufacturing output data.
Variance decomposition separates volume drivers from price assumptions across the projection horizon. Segmentation dimensions modeled include product architecture, flavor category tolerance, nicotine concentration tier, and distribution channel regulatory status. CAGRs derive from installed base replacement cycles and adult smoker transition rates by jurisdiction. Forecast inputs incorporate ceramic coil adoption curves and lithium carbonate contract pricing trajectories.
Material uncertainties — FDA enforcement intensity escalation, EU flavor restriction harmonization, and SAMR export license revocation events — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and channel access continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Lighter Market
Smoking Accessories
North America Cigarette Lighter Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
Japan Smoking Accessories Market
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
US Smoking Pipe Market