
 Performing Art Companies Market | 2026-2036
Performing Art Companies Market Size, Share, and Industry Trends Forecast 2026-2036
Performing Art Companies Market Outlook
ISO 9001 quality management certification is rotating as a baseline credential for institutional touring contracts, filtering which production houses qualify for government and corporate venue procurement. Live Nation Entertainment leverages its owned-venue network across multiple continents to control distribution economics for major touring acts. Cirque du Soleil Entertainment Group sustains proprietary acrobatic training protocols that differentiate its physical-theatre format from conventional circus competitors. The Walt Disney Company anchors family-oriented theatrical licensing through its character IP portfolio and permanent resident show operations.
Performing art companies are organizations that produce, present, or manage live theatrical, musical, dance, or multimedia entertainment for public or private audiences, typically operating with production budgets ranging from under one hundred thousand dollars for regional theatre to over fifty million dollars for permanent resident spectacles. Their commercial purpose centers on aggregating creative labor, technical production assets, and audience access into repeatable live entertainment experiences that generate revenue through direct ticket sales, institutional subsidies, or brand licensing arrangements. Theater companies within the Company Type segment occupy the largest revenue pool due to established venue infrastructure and subscription loyalty programs, while Multimedia productions represent the fastest-growing category as projection mapping and real-time visual engine technology reduce physical set construction costs. The Revenue Model dimension shows Sponsorship and Grants gaining structural importance as corporate ESG commitments and public cultural funding offset volatility in discretionary ticket purchasing.
US OSHA workplace safety standards govern performer rigging and stage crew exposure limits, while EU F-Gas Regulation constrains theatrical refrigeration and fog-effect equipment deployed in touring productions across member states. The EU AI Act introduces emerging compliance obligations for automated lighting and sound systems that use machine-learning-driven audience responsiveness. Stakeholders must monitor how fragmented national labor classifications for gig-based performers reshape payroll cost structures and cross-border touring viability.
Market Dynamics
Real-time visual engine technology is compressing production timelines and reducing physical asset requirements across touring theatrical productions, fundamentally altering capital deployment patterns for performing art companies.
Growth Catalysts
- EU Creative Europe funding:Cross-border touring productions receive prioritized public investment, expanding venue access for mid-scale theater companies across member states.
- Corporate ESG commitments:Institutional sponsorship budgets are redirecting toward cultural programming as measurable community impact investments, stabilizing revenue volatility for resident companies.
- Germany's theater cluster:Concentrated demand around Berlin and Hamburg creates network effects for technical crew specialization and shared production infrastructure.
Market Restraints
- EU F-Gas Regulation:Refrigeration and fog-effect equipment constraints increase touring production technical compliance costs across member states.
- Performer rigging certification:US OSHA workplace safety standards impose specialized training overhead that fragments crew mobility between productions.
- Discretionary ticket purchasing:Consumer sensitivity to entertainment expenditure creates demand volatility that institutional subsidies only partially offset.
Strategic Opportunities
- EU AI Act compliance:Automated lighting and sound systems using machine-learning audience responsiveness face emerging regulatory frameworks that first-movers can shape.
- Projection mapping convergence:Integration with real-time visual engines enables immersive multimedia productions at reduced physical set construction cost.
- Subscription loyalty programs:Theater companies can deepen audience retention through tiered membership structures that pre-commit revenue.
Industry Challenges
- Gig-based performer classification:Fragmented national labor regulations reshape payroll cost structures and cross-border touring viability.
- ISO 9001 certification timeline:Quality management credential requirements filter institutional contract eligibility, compressing preparation windows for smaller production houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performing Art Companies Market |
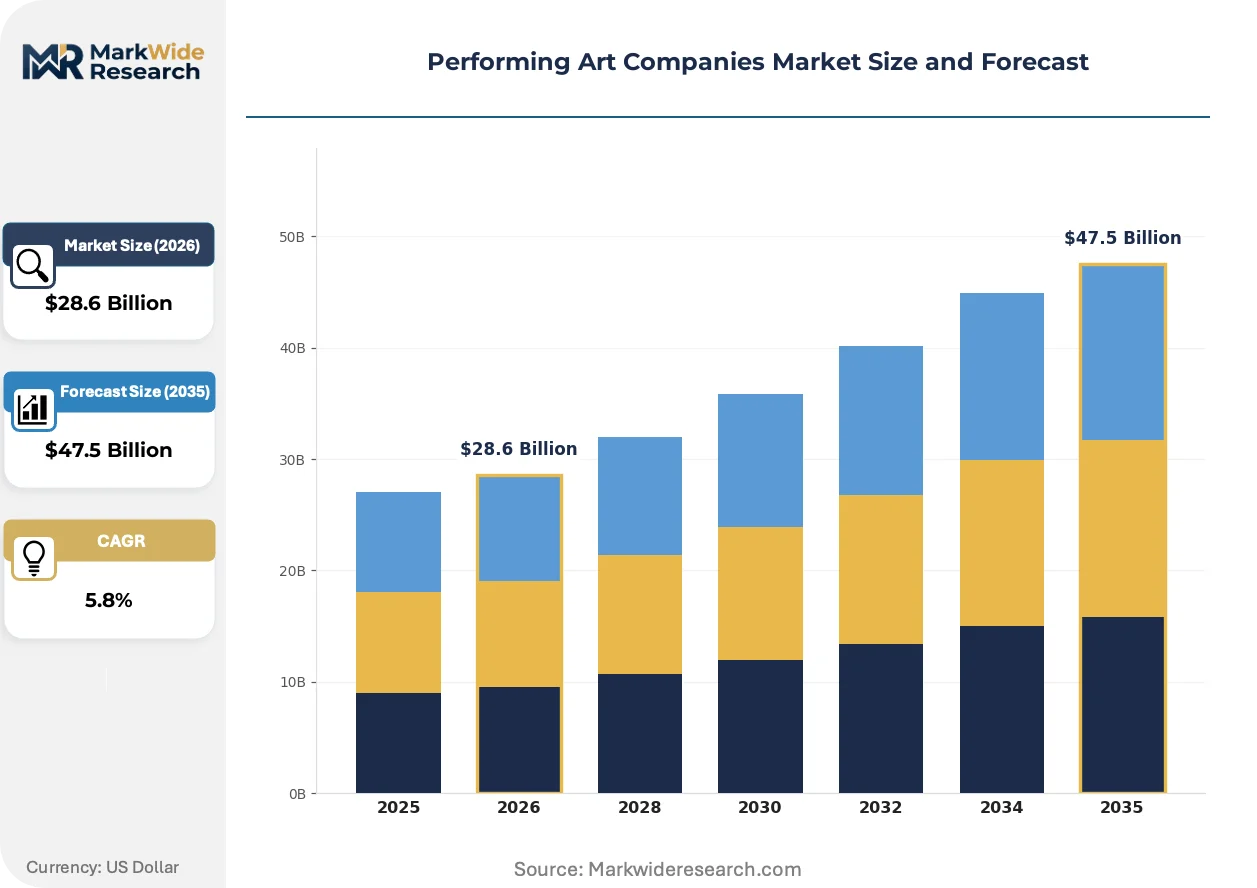
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Company Type: Theater, Dance, Music, Multimedia Revenue Model: Subscription, Ticket Sales, Sponsorship, Grants Performance Type: Live Shows, Workshops, Festivals, Tours Audience Demographic: Students, General Public, Art Enthusiasts, Families |
| Companies Covered | Live Nation Entertainment, Cirque du Soleil Entertainment Group, The Walt Disney Company, AEG Presents (Anschutz Entertainment Group), Ambassador Theatre Group, Shubert Organization, Nederlander Organization, Stage Entertainment, Metropolitan Opera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performing Art Companies Market Strategic Shifts
Technological substitution in production methods, regulatory adaptation to automated systems, and evolving corporate buyer behavior are restructuring how performing art companies develop and distribute live entertainment.
Projection mapping combined with real-time Unreal Engine rendering is displacing conventional physical set construction for mid-scale touring productions. Regional theater companies in the UK and Netherlands are adopting these tools to reduce load-in times and freight costs. The structural consequence is compressing the minimum viable production budget threshold, enabling more frequent repertoire rotation.
The EU AI Act introduces compliance obligations for machine-learning-driven audience-responsive lighting and sound systems. Theatrical equipment manufacturers must now document algorithmic decision-making transparency for automated cue systems. Touring productions deploying adaptive environmental controls face heightened technical documentation requirements, particularly in France and Germany where national regulators are issuing supplementary guidance.
Corporate entertainment buyers are consolidating vendor relationships into multi-year live performance packages rather than transactional single-event procurement. This concentration favors production houses with ISO 9001 certification and owned venue networks. The shift is most pronounced in the United States, where Fortune 500 companies are centralizing cultural programming under centralized procurement functions with ESG reporting mandates.
Performing Art Companies Market Segmentation
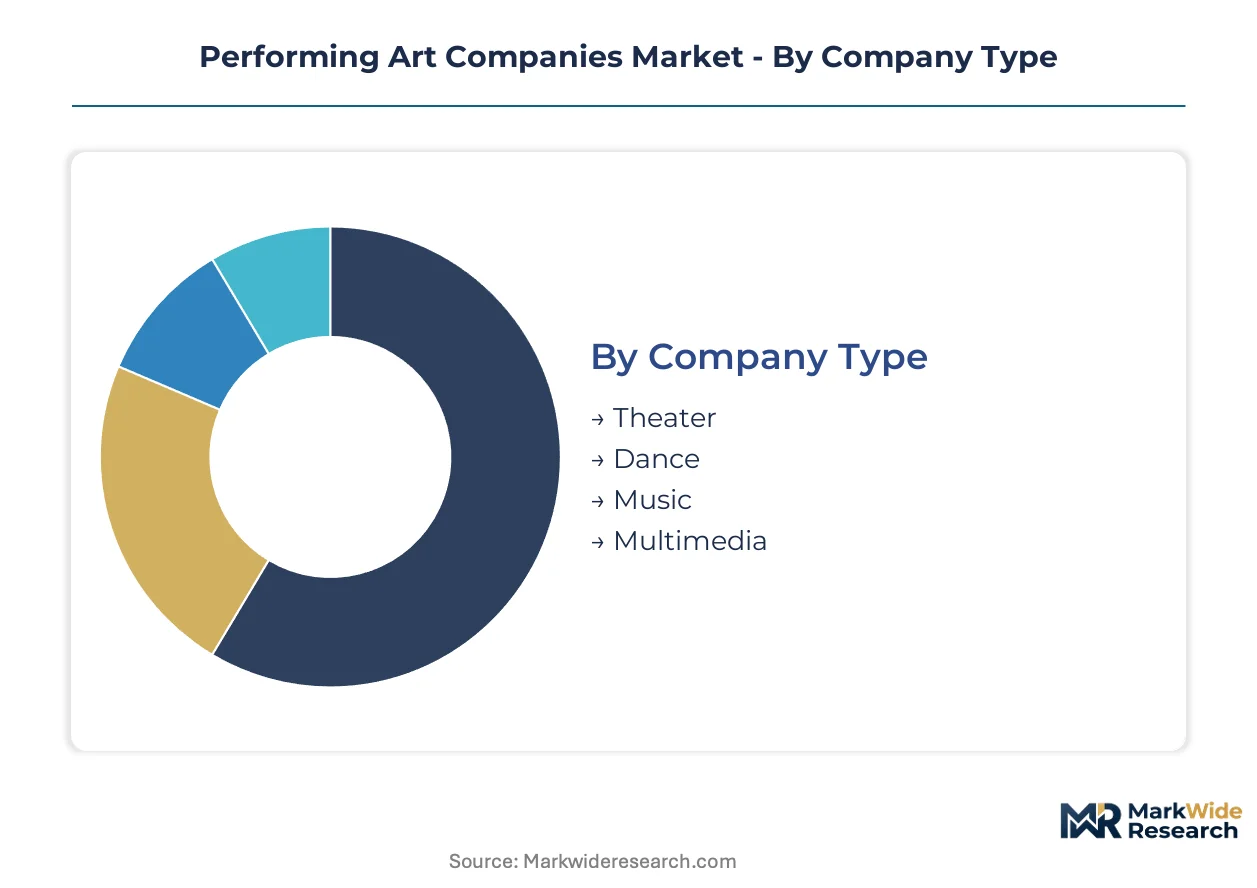
Segmentation in performing art companies determines capital allocation, regulatory exposure, and venue procurement eligibility. Each dimension shapes how production houses structure touring logistics, audience development, and subsidy dependence.
Company Type:
Regulatory differentiation separates physical-risk categories for performer safety compliance and equipment certification standards.
- Theater:Resident companies operate permanent venue infrastructure with subscription loyalty programs. Demand concentrates in Germany's Berlin-Hamburg cluster where shared technical crew specialization reduces production overhead.
- Multimedia:Productions deploy projection mapping and real-time visual engines to displace physical set construction. Adoption is climbing the fastest in UK and Netherlands regional companies seeking reduced load-in times and freight expenditure.
- Dance:Touring ballet and contemporary companies face specialized rigging certification requirements under US OSHA standards that fragment crew mobility.
- Music:Orchestral and opera companies anchor institutional subsidy dependence with cross-border EU Creative Europe funding access.
Established volume favors Theater; emerging adoption favors Multimedia.
Revenue Model:
Margin stability varies sharply across pre-commitment versus discretionary income exposure.
- Subscription:Pre-committed audience revenue stabilizes cash flow for resident theater companies with tiered membership structures.
- Sponsorship:Corporate ESG commitments redirect cultural programming budgets toward measurable community impact investments, particularly among Fortune 500 procurement functions.
- Ticket Sales:Direct consumer purchasing faces volatility from discretionary entertainment expenditure sensitivity that institutional subsidies only partially offset.
- Grants:Public cultural funding from EU Creative Europe prioritizes cross-border touring productions for mid-scale companies.
Pre-commitment revenue favors Subscription; ESG-aligned expansion favors Sponsorship.
Performance Type:
Supply chain configuration determines freight cost exposure and technical crew specialization requirements.
- Tours:Cross-border productions face EU F-Gas Regulation compliance for refrigeration and fog-effect equipment, elevating technical documentation burdens.
- Live Shows:Permanent resident spectacles anchor family-oriented theatrical licensing through character IP portfolios and owned-venue network control.
- Workshops:Educational programming targets student demographics with reduced production budget thresholds and simplified rigging requirements.
- Festivals:Temporary aggregation of multiple companies creates shared infrastructure economies but fragments ISO 9001 certification eligibility across vendors.
Scale concentration favors Live Shows; regulatory complexity favors Tours.
Audience Demographic:
Customer lifetime value diverges across institutional access programs versus discretionary household expenditure.
- Families:Character IP licensing and permanent resident shows capture repeat attendance with intergenerational programming.
- Students:Educational discount structures build long-term subscription conversion pipelines for regional theater companies.
- General Public:Broad demographic targeting requires diversified repertoire rotation that compresses production timeline flexibility.
- Art Enthusiasts:Niche programming commands premium pricing but limits venue scalability and corporate sponsorship alignment.
Volume depth favors Families; conversion pipeline value favors Students.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate entertainment procurement functions concentrate in the United States and Germany, where Fortune 500 headquarters and dense theater clusters generate concentrated demand for live performance packages.
United States
Fortune 500 corporate entertainment buyers anchor institutional procurement volumes with multi-year live performance contracts. OSHA workplace safety standards govern performer rigging certification requirements that fragment crew mobility between touring productions. New York City's Broadway district and Los Angeles entertainment corridor concentrate resident theater companies with permanent venue infrastructure.
Germany
Theater subscription loyalty programs in Berlin and Hamburg sustain pre-committed audience revenue pools for resident companies. EU F-Gas Regulation constrains refrigeration and fog-effect equipment deployed in touring productions, elevating technical compliance documentation burdens. The Berlin-Hamburg theater cluster generates network effects for technical crew specialization and shared production infrastructure.
United Kingdom
Regional theater companies adopt projection mapping and real-time visual engines to reduce load-in times and freight expenditure on touring productions. The country's national cultural funding bodies channel public investment toward cross-border touring through bilateral agreements with EU member states. London's West End anchors permanent resident spectacles with owned-venue network control over distribution economics.
France
Automated lighting and sound systems with machine-learning audience responsiveness face emerging compliance obligations under the EU AI Act. National regulators issue supplementary guidance for algorithmic decision-making transparency in theatrical cue systems. Paris-based production houses concentrate technical documentation expertise for adaptive environmental controls in touring shows.
Netherlands
Mid-scale theater companies leverage reduced physical set construction costs from projection mapping convergence to enable more frequent repertoire rotation. The country's national theater infrastructure receives prioritized access to EU Creative Europe funding for cross-border productions. Amsterdam and Rotterdam host shared technical production facilities that lower overhead for touring companies.
Performing Art Companies Market Competitive Environment
Player mix skews toward integrated venue operators with owned-network control over distribution economics. The market structure concentrates around production houses with permanent resident show capabilities and touring logistics expertise. Three archetypes dominate: character IP licensors with family-oriented theatrical programming, acrobatic physical-theatre specialists with proprietary training protocols, and venue-network operators with multi-continent presence. Competitive moves center on multi-year corporate entertainment procurement contracts and ISO 9001 quality management certification acquisition for institutional venue eligibility.
Within the integrated venue-operator tier, Live Nation Entertainment and AEG Presents exemplify network-scale distribution control across multiple continents. Cirque du Soleil Entertainment Group occupies a position representing proprietary format differentiation through specialized physical-theatre training infrastructure. The Walt Disney Company anchors the character IP licensing archetype with permanent resident show operations and intergenerational audience development capabilities.
| Leading Market Players |
|---|
| Live Nation Entertainment |
| Cirque du Soleil Entertainment Group |
| The Walt Disney Company |
| AEG Presents (Anschutz Entertainment Group) |
| Ambassador Theatre Group |
| Shubert Organization |
| Nederlander Organization |
| Stage Entertainment |
| Metropolitan Opera |
| Others |
Value Chain & Pricing Dynamics
Real-time visual engine technology replacing conventional physical set construction simultaneously redistributes production geography toward UK and Netherlands regional companies and compresses pricing tiers for mid-scale touring productions.
Pricing Analysis
Cost-plus contracts with crew labor indexation dominate touring production agreements, with pricing stratifying across ISO 9001-certified premium houses, established resident companies, and emerging multimedia specialists. Price differentiation hinges on certification tier and owned-venue network scale. Pricing pressure stems from corporate procurement consolidation demanding multi-year performance packages. Regional theater companies exhibit highest price sensitivity; integrated venue operators with permanent resident shows demonstrate lowest.
Supply Chain Analysis
Inventory compression for projection mapping hardware has collapsed lead times from twelve weeks to under four, enabling faster repertoire rotation. Supply concentrates in Germany, United Kingdom, and Netherlands for technical crew specialization and shared production facilities. Raw material dependencies span aluminum truss systems, LED projection arrays, and automated lighting rigs. Single-source vulnerability for proprietary visual engine software licenses threatens touring continuity. Distribution runs through owned-venue networks for major acts and festival aggregators for mid-scale companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from immersive digital entertainment formats that capture discretionary household expenditure once reserved for live performance.
For Market Incumbents: Compound venue network control through exclusive multi-year corporate entertainment contracts that lock in Fortune 500 procurement functions. Deepen ISO 9001 certification barriers to filter institutional contract eligibility against emerging multimedia competitors. Prioritize backward integration into proprietary training protocols that protect physical-theatre format differentiation.
For New Entrants and Emerging Players: Mid-scale cross-border touring gaps in EU Creative Europe funding pipelines offer service-layer entry points where established houses under-invest. Target Netherlands and UK regional markets with projection mapping-enabled productions at reduced capital thresholds. Pursue tiered subscription membership structures that pre-commit audience revenue before scaling to permanent resident operations.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors integrated venue operators with owned-network distribution economics. Long-term viability across the analysis window rests on controlling permanent resident show IP and corporate procurement relationships. Watch automated lighting compliance documentation under EU AI Act as inflection indicator for regulatory adaptation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Acquisition | Quality management credentials filter government and corporate venue procurement eligibility for institutional contracts. |
| Projection Mapping Technology Integration | Unreal Engine rendering reduces physical set construction costs and load-in times for touring productions. |
| Multi-Year Corporate Entertainment Contracts | Fortune 500 ESG-aligned procurement consolidates vendor relationships into stable revenue commitments. |
| Cross-Border EU Creative Europe Funding Access | Prioritized public investment expands venue access for mid-scale theater companies across member states. |
| Proprietary Training Protocol Development | Specialized acrobatic and physical-theatre infrastructure protects format differentiation from conventional competitors. |
Study Parameters
The analysis maps theater companies, multimedia productions, dance companies, and music ensembles, each validated through production house executives, venue procurement managers, corporate entertainment buyers, and technical crew specialists. Primary interviews with these stakeholders combined with secondary validation against EU Creative Europe funding disclosures, OSHA regulatory filings, SEC 10-K entertainment segment reports, and national theater subscription databases. Bottom-up production budget modeling and top-down venue revenue aggregation provided triangulation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include company type, revenue model, performance format, and audience demographic clusters. CAGRs were derived from production budget trajectory analysis and venue capacity utilization trends. Forecast inputs incorporated EU AI Act compliance timeline assumptions and corporate ESG commitment intensity indicators.
Underlying assumptions cover discretionary entertainment expenditure stability and cross-border touring regulatory continuity, with deviation risk concentrated in gig-based performer labor reclassification and automated systems compliance costs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Music Production Software Market
Media and Entertainment
Global Special Effects Fog and Smoke Machines Market
Media and Entertainment
Online Art Market
Media and Entertainment
Game Streaming Market
Media and Entertainment
Brazil Animation, VFX and Post Production Market
Media and Entertainment
Online Virtual Youtuber Model Market
Media and Entertainment
Digital Comics Distribution and Consumption Platforms Market
Media and Entertainment
Asia Pacific Video Streaming Market
Media and Entertainment
Gaming Accessories Market
Media and Entertainment
Online Comic Market
Media and Entertainment
Playstation Network (PSN) Market
Media and Entertainment
Global Live Event Ticketing Market
Media and Entertainment
Global Subscription-Based Gaming Market
Media and Entertainment
Internet Advertising Market
Media and Entertainment
India Gaming Market
Media and Entertainment
North America Gaming Hardware and Accessories Market