
 Global Live Event Ticketing Market | 2026-2036
Global Live Event Ticketing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Live Event Ticketing Market Foresight
Primary ticket distribution is tilting toward mobile-first architectures as venues and promoters reclaim control over inventory. Ticketmaster leverages exclusive venue partnerships to sustain its position across North American stadiums and arenas. CTS Eventim anchors European market share through integrated software-box office systems in Germany and Austria. SeatGeek differentiates via API-first partnerships with leagues and teams, competing directly against AXS's venue-embedded technology stack.
Live event ticketing encompasses the issuance, distribution, and validation of admission rights for time-bound entertainment experiences, typically encoded as QR codes, NFC tokens, or blockchain-verified digital assets with embedded transfer restrictions. The system serves commercial purpose by enabling yield management, audience identity capture, and secondary market monetization for event rights holders. Concerts and sports matches command the largest revenue pools within event type segmentation, while mobile tickets and dedicated apps are displacing print-at-home and will-call methods across delivery and sales channel dimensions. Corporate clients and fan clubs represent underdeveloped margin pools relative to individual consumer volume.
The EU Digital Services Act and GDPR impose algorithmic transparency and data handling standards on platform operators, while the US FTC monitors deceptive pricing and speculative ticket listing practices. Brazil's ANCINE and Saudi Arabia's General Entertainment Authority each shape local market access through event licensing and foreign promoter requirements. Stakeholders must monitor regulatory divergence between jurisdictions that treat ticket resale as consumer protection territory versus those framing it as free commerce.
Market Dynamics
Venue operators and sports franchises are reclaiming inventory control through exclusive platform partnerships, compressing secondary market margins while embedding dynamic pricing algorithms directly into primary distribution systems.
Growth Catalysts
- EU Digital Services Act:Algorithmic transparency mandates for secondary marketplaces are forcing platform operators to disclose ranking parameters, reducing speculative listing practices and restoring consumer trust in digital channels.
- Mobile-first architecture:Stadium operators across Germany, Brazil, and Saudi Arabia are mandating QR code and NFC token validation, eliminating print-at-home fraud vectors and accelerating real-time yield management.
- Fan identity capture:Promoters are monetizing first-party data pools through embedded CRM systems, converting transactional ticket sales into recurring membership revenue streams with personalized upsell pathways.
Market Restraints
- Exclusive venue contracts:Long-term technology partnerships between arena operators and primary distributors create switching friction that locks out competing platform entrants in concentrated metropolitan markets.
- GDPR compliance costs:Cross-border data handling requirements impose architectural constraints on fan profile aggregation, particularly for events drawing audiences from multiple European jurisdictions.
- Blockchain verification overhead:Distributed ledger ticket authentication adds per-transaction computational costs that scale unfavorably for high-volume, low-margin comedy club and theater segments.
Strategic Opportunities
- Corporate hospitality packages:Underdeveloped B2B segments in Saudi Arabia's entertainment infrastructure buildout offer margin expansion through bundled premium seating and experiential add-ons.
- API-first league partnerships:Sports federations are opening data feeds to third-party developers, enabling embedded ticket discovery within streaming platforms and fantasy sports applications.
- Brazilian regulatory modernization:ANCINE's evolving event licensing framework creates first-mover advantages for platforms integrating with national identity verification systems.
Industry Challenges
- Legacy box office integration:Decades-old venue management software requires costly middleware development to connect with modern mobile distribution stacks, delaying rollout timelines.
- Real-time pricing expertise:Shortage of revenue management specialists with live entertainment sector experience constrains franchise ability to execute dynamic models at stadium scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Live Event Ticketing Market |
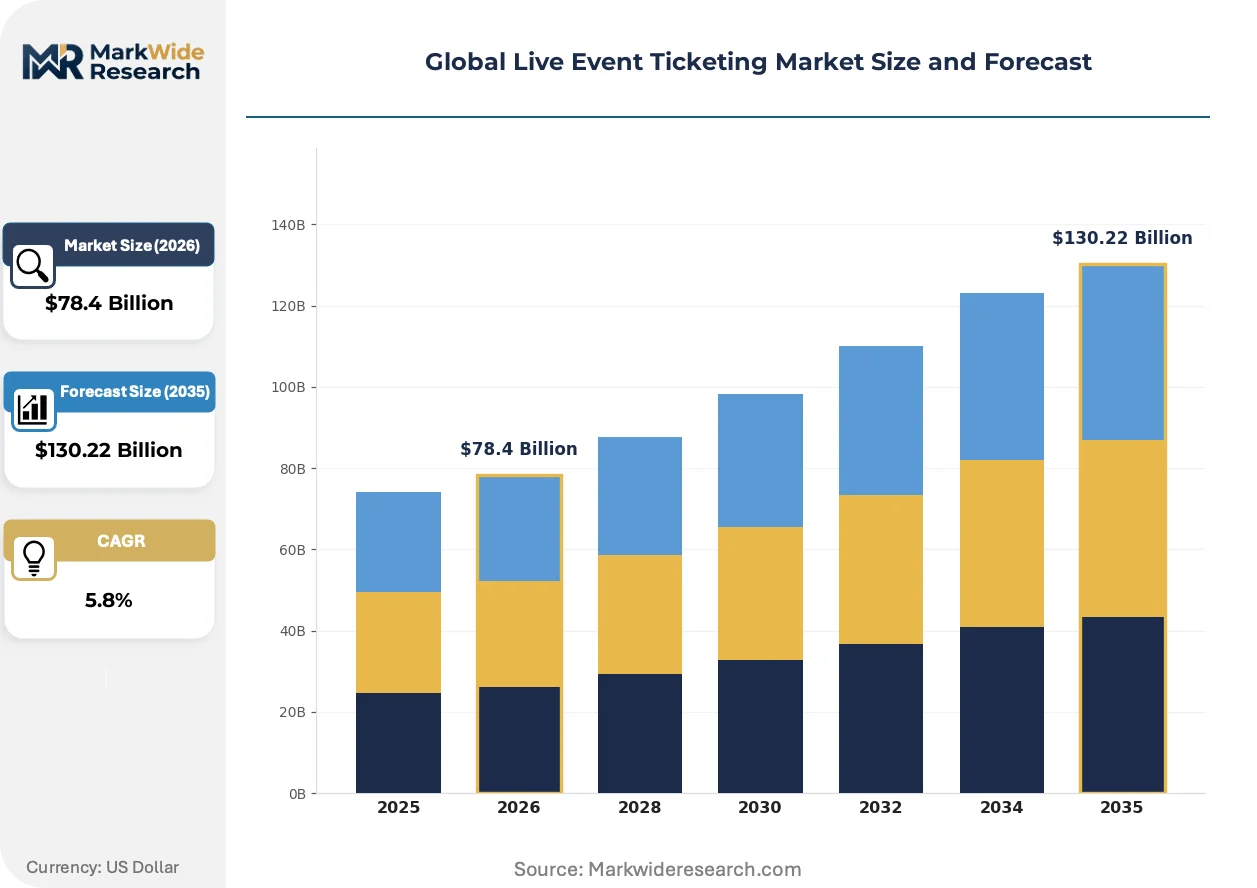
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Concerts, Sports Matches, Theatre Shows, Festivals, Conferences Ticket Delivery Method: Mobile Tickets, Print-at-Home, Will Call, Kiosk Pickup, Postal Delivery Customer Type: Individual Consumers, Corporate Clients, Event Organizers, Fan Clubs, Travel Agents Sales Channel: Official Box Office, Online Platforms, Third-party Resellers, Venue Counters, Mobile Apps |
| Companies Covered | StubHub, Vivid Seats, Ticketmaster, CTS Eventim, TEG Ticketek, Eventbrite, AXS, Tixr, SeatGeek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Live Event Ticketing Market Shifts & Advancements
Distributed ledger and artificial intelligence systems are rewriting how admission rights are issued, verified, and transferred between holders, compressing the gap between primary release and secondary market activity.
Blockchain-based ticketing infrastructure is virtualizing ownership records through non-fungible token standards with programmable transfer restrictions. Major festivals and sports leagues in the United States and Netherlands are piloting these systems to eliminate scalping while preserving fan resale flexibility. This architecture is virtualizing the traditional split between primary distribution and aftermarket trading, enabling promoters to capture royalty streams on peer-to-peer transactions.
The EU Digital Services Act's algorithmic accountability provisions are compelling secondary platforms to expose how search results rank ticket listings. Operators serving European audiences must now document the parameters governing visibility, including price proximity and seller verification status. German and Austrian marketplace incumbents are responding by restructuring recommendation engines to prioritize consumer-facing transparency metrics over revenue-optimized placement.
Fan club presale access is displacing general on-sale windows as the dominant acquisition pathway for high-demand events. Music promoters in the United Kingdom and Australia are allocating inventory majority shares to verified fan databases, reducing bot-driven sellouts while building direct marketing channels. This behavior concentrates purchase intent earlier in the event lifecycle, compressing the window between announcement and revenue recognition.
Global Live Event Ticketing Market Segmentation
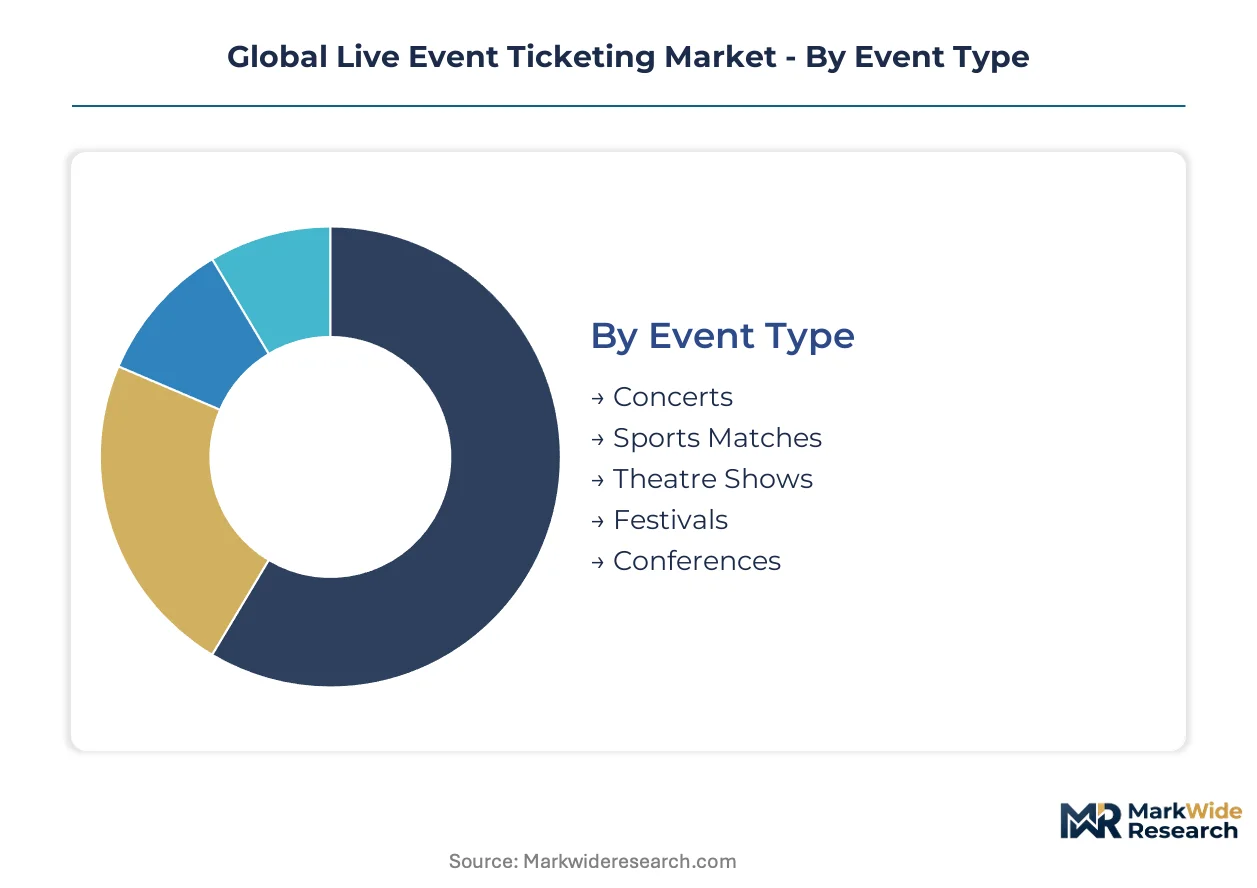
Event type, delivery method, customer profile, and sales channel each shape yield management strategies and technology stack requirements differently. Promoters optimize pricing algorithms and inventory allocation based on how these dimensions intersect for specific venue configurations and audience demographics.
Event Type:
Use cases span intimate theater experiences to stadium-scale sports fixtures, each demanding distinct capacity planning and fraud prevention protocols.
- Concerts:High-frequency touring cycles and artist fanbase variability drive demand for dynamic pricing models that adjust to real-time inventory velocity. Arena operators in Germany and the United States deploy surge algorithms during on-sale windows to capture maximum revenue from limited capacity.
- Sports Matches:Season-long scheduling predictability enables franchise-controlled subscription models and corporate hospitality bundling. Season ticket holders in Brazil and Saudi Arabia represent locked-in revenue bases that reduce per-match yield volatility.
- Theatre Shows:Fixed run lengths and seated configurations prioritize early-booking incentives over last-minute discounting.
- Festivals:Multi-day passes and camping add-ons create complex SKU management across tiered experience packages.
- Conferences:B2B attendee tracking requirements integrate registration systems with enterprise CRM platforms.
The dominant share belongs to Concerts, while Sports Matches is closing the gap fastest.
Ticket Delivery Method:
Cost tiers separate premium fraud-resistant formats from legacy distribution channels bearing higher operational overhead.
- Mobile Tickets:QR codes and NFC tokens enable real-time transfer restrictions and identity-linked validation at venue gates. Stadium operators across Saudi Arabia mandate mobile-only entry to eliminate counterfeit paper vectors.
- Print-at-Home:PDF attachments with barcode generation remain viable for corporate procurement workflows requiring expense documentation.
- Will Call:Identity-verified window pickup persists for international visitors lacking local mobile payment credentials.
- Kiosk Pickup:Self-service terminal deployment concentrates in legacy venues with incomplete mobile infrastructure retrofit budgets.
- Postal Delivery:Commemorative hard tickets serve premium hospitality segments where physical artifact value exceeds convenience.
Mobile Tickets commands the volume base, with Kiosk Pickup gaining share fastest among venues completing hardware refresh cycles.
Customer Type:
Application maturity varies sharply between transactional individual purchases and relationship-driven corporate contracting.
- Individual Consumers:Price-sensitive buyers responding to flash sales and fan club presale windows. GDPR compliance complexity rises when EU residents purchase tickets for events in Brazil or Saudi Arabia.
- Corporate Clients:Bundled hospitality packages with dedicated account management yield per-seat multiples above individual consumer averages. Saudi Arabia's entertainment infrastructure buildout targets this underdeveloped segment.
- Event Organizers:Promoter-direct procurement of block inventory for allocation to sub-distributors.
- Fan Clubs:Verified member databases enable bot-resistant presale access and recurring subscription revenue.
- Travel Agents:Package tour operators combining admission with accommodation and transport for destination events.
Individual Consumers anchor transaction volume, while Corporate Clients is expanding most quickly in emerging entertainment markets.
Sales Channel:
Margin concentration follows control over inventory access and data capture depth.
- Official Box Office:Primary issuer systems embedded directly into venue technology stacks capture full service fees and first-party customer data. CTS Eventim's integrated software-box office deployments in Germany and Austria exemplify this model.
- Online Platforms:Aggregator interfaces compete on discovery convenience while surrendering margin to primary distributor commissions.
- Third-party Resellers:Secondary marketplaces face EU Digital Services Act algorithmic transparency mandates that compress speculative listing practices.
- Venue Counters:Walk-up sales capture unsold inventory with minimal customer acquisition cost.
- Mobile Apps:League and team-branded applications embed ticket discovery within content and fantasy sports engagement loops.
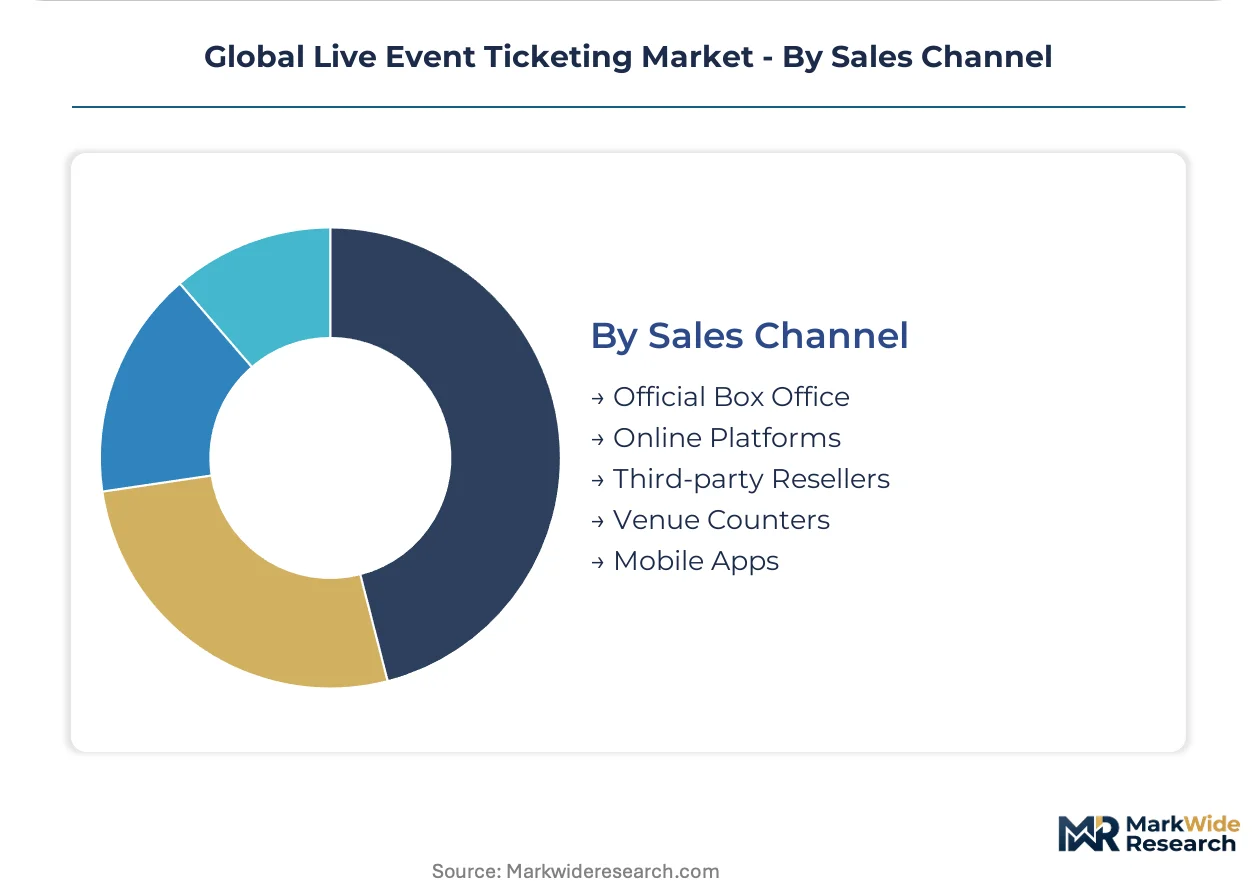
Official Box Office retains the dominant position, with Mobile Apps climbing the fastest as sports federations open API partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where venue-operator contracts and integrated software-box office systems command premium service fees, while Brazil and Saudi Arabia build out infrastructure to capture comparable yield.
United States
Stadium-scale sports franchises and touring concert promoters drive primary ticket volume through exclusive platform partnerships. The FTC monitors speculative listing practices and deceptive pricing disclosures on secondary marketplaces. Los Angeles and New York anchor venue concentration where mobile-first validation systems displace legacy print-at-home methods.
Germany
Integrated software-box office deployments across arena networks enable real-time yield management and fan identity capture. GDPR compliance requirements shape data handling architectures for cross-border event audiences. Munich and Berlin host dense venue clusters where dynamic pricing algorithms adjust inventory velocity during on-sale windows.
Brazil
ANCINE's evolving event licensing framework concentrates demand for platforms integrating with national identity verification systems. The regulator's foreign promoter requirements shape local market access for international touring acts. São Paulo and Rio de Janeiro anchor entertainment infrastructure buildout targeting underdeveloped corporate hospitality segments.
Saudi Arabia
The General Entertainment Authority's licensing mandates accelerate venue construction and primary distribution system deployment. Foreign promoter requirements and event approval processes structure market entry for international platforms. Riyadh and Jeddah concentrate stadium and arena development where mobile-only ticket validation eliminates counterfeit vectors.
United Kingdom
Verified fan databases and presale access windows displace general on-sale methods for high-demand music events. Consumer protection authorities scrutinize secondary market transparency and speculative listing practices. London anchors venue density where promoter-direct inventory control compresses aftermarket margins.
Global Live Event Ticketing Market Competitive Landscape
Venue-embedded primary distributors and API-first platform specialists split the market between inventory control and discovery convenience. The structure concentrates around exclusive contracts with arena operators and sports franchises that create switching friction for competing entrants. Three archetypes dominate: integrated software-box office operators, mobile-native API platforms, and secondary marketplace aggregators. Competitive moves center on exclusive venue technology partnerships and dynamic pricing algorithm licensing.
Among North American platform operators, Ticketmaster and SeatGeek occupy distinct strategic positions. Ticketmaster exemplifies the venue-embedded archetype through exclusive stadium and arena partnerships that capture full service fees and first-party data. SeatGeek represents the API-first specialist model, embedding ticket discovery within league-branded mobile applications and fantasy sports engagement loops. CTS Eventim anchors European market structure as a Germany-based integrated operator controlling software-box office deployments across German and Austrian venue networks.
| Leading Market Players |
|---|
| StubHub |
| Vivid Seats |
| Ticketmaster |
| CTS Eventim |
| TEG Ticketek |
| Eventbrite |
| AXS |
| Tixr |
| SeatGeek |
| Others |
Supply & Pricing Matrix
Transatlantic data corridor costs compress margin structures for platforms serving EU audiences with US-based infrastructure, concentrating pricing power with venue-embedded operators in Germany and Austria while forcing API-first competitors to absorb cross-border compliance overhead into service fees.
Pricing Analysis
The customization-premium spread separates venue-embedded primary distribution from white-label API configurations, with dynamic pricing algorithm licensing commanding recurring SaaS-tiered revenue against transactional per-ticket fees for standard marketplace access. Price differentiation rests on fan identity capture depth and real-time yield management sophistication, while cost compression in secondary market commissions intensifies as EU algorithmic transparency mandates eliminate speculative listing markups. Individual consumers exhibit highest price sensitivity to service fee stacking, whereas corporate hospitality buyers prioritize bundled experiential add-ons over per-seat economics.
Supply Chain Analysis
Export-control regime restrictions on facial recognition and biometric validation technologies limit hardware vendor options for stadium access systems, tethering procurement to approved supplier lists in the United States, Germany, and South Korea. Raw material dependencies center on NFC chipsets, QR generation middleware, and encrypted cloud storage capacity. Single-source vulnerability concentrates in legacy box office software requiring costly middleware bridges to mobile-first stacks. Distribution runs through exclusive venue technology partnerships that lock out competing platform entrants in concentrated metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is accelerating as sports federations open API ecosystems, with interoperability between streaming content and ticket discovery rewriting competitive moats around data feed access rather than inventory control alone.
For Market Incumbents: Harden exclusive venue contract structures against API-first disintermediation by embedding dynamic pricing algorithms deeper into stadium technology stacks. Acquire fan identity verification specialists to defend against biometric authentication challengers entering through mobile-native partnerships. Prioritize backward integration into middleware development to accelerate legacy box office retrofit timelines.
For New Entrants and Emerging Players: Saudi Arabia's entertainment infrastructure buildout offers the most penetrable geography for corporate hospitality platform specialization, with underdeveloped B2B segments yielding per-seat multiples above individual consumer averages. Target API partnerships with national identity verification systems in Brazil to capture first-mover advantage under ANCINE's evolving licensing framework. Lead go-to-market through league-branded mobile applications embedding ticket discovery within fantasy sports engagement loops.
For Investors and Strategic Acquirers: Mobile-native API platforms with proven league data feed integrations represent the priority acquisition archetype, with revenue visibility extending through recurring SaaS licensing rather than transactional fee dependency. Long-term viability favors operators controlling both primary distribution infrastructure and fan identity data pools. Watch for inflection signals in sports federation API standardization announcements that would validate interoperability-centered business models.
| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Pricing Algorithm Licensing | CTS Eventim and Ticketmaster monetize yield management software to venue operators beyond ticket distribution. |
| API-First League Partnership | SeatGeek embeds discovery within NBA and NFL mobile applications, capturing fan engagement upstream of purchase intent. |
| Blockchain Verification Pilot | Dutch festivals and US sports leagues test NFT-based ownership with programmable transfer restrictions to eliminate scalping. |
| Corporate Hospitality Platform Buildout | Saudi Arabia's General Entertainment Authority licensing creates margin expansion through bundled premium seating and experiential add-ons. |
| Fan Identity Verification Integration | Brazil's ANCINE framework rewards platforms connecting to national identity systems with streamlined foreign promoter approval. |
Research Methodology
Operator-level perspectives from venue technology directors, sports franchise revenue managers, festival promoters, secondary marketplace compliance officers, and API platform product leads anchored the qualitative base. Secondary validation drew from EU Digital Services Act regulatory filings, FTC enforcement actions, ANCINE licensing bulletins, General Entertainment Authority permits, and venue operator technology procurement disclosures. Bottom-up transaction volume modeling triangulated against top-down entertainment industry revenue estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning event type, delivery method, customer profile, and sales channel. Modeled variables included mobile ticket penetration velocity, dynamic pricing algorithm adoption curves, and corporate hospitality package attach rates. CAGRs derived from historical venue capacity expansion, touring cycle frequency, and platform commission structure evolution.
Macroeconomic conditions sit as an overlay; deviation in discretionary entertainment spending, cross-border event tourism recovery, or cloud infrastructure cost inflation would shift the trajectory. Material shifts in EU algorithmic transparency enforcement intensity or Saudi entertainment licensing liberalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
India Event Services Market
Events and Festivals
Online Event Ticketing Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Professional Speaker Market
Events and Festivals
Europe Event Pro-Av Services Market
Events and Festivals
Event Services Market
Events and Festivals
Global Special Effects Fog and Smoke Machines Market
Events and Festivals
Events Market
Events and Festivals
Indoor Entertainment Center Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
Event Photography Service Market
Events and Festivals
K-Pop Events Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Global Family Entertainment Center Market
Events and Festivals
Photo Booth Market
Events and Festivals
Global Exhibition Market