
 North America Performing Art Companies Market | 2026-2036
North America Performing Art Companies Market Size, Share, and Industry Trends Forecast 2026-2036
North America Performing Art Companies Market Outlook
Multi-source talent procurement is broadening across the North America Performing Art Companies Market as houses diversify beyond exclusive resident companies. The Walt Disney Company leverages its vertically integrated production pipeline across theatrical and streaming distribution. Live Nation Entertainment anchors continental touring logistics through venue control and promoter networks. The Shubert Organization dominates Broadway real estate holdings, sustaining pricing power across forty-plus theaters.
Performing art companies encompass organizations that produce live theatrical, musical, dance, and comedy presentations for ticketed audiences, requiring specialized acoustical engineering, rigging systems, and union-scale labor coordination to deliver scheduled repertory seasons. Theater companies within the Company Type classification capture the largest revenue share due to permanent venue infrastructure and subscription renewal economics. Contemporary programming within the Performance Genre dimension is expanding fastest as houses program immersive and hybrid digital-physical formats to attract younger Audience Segment cohorts.
The National Endowment for the Arts and Canadian Heritage shape funding eligibility through grant compliance requirements, while U.S. Occupational Safety and Health Administration and Canadian Centre for Occupational Health and Safety standards govern performer and crew workplace conditions. Stakeholders must monitor how municipal zoning for cultural districts and evolving visa classifications for international performers alter operational feasibility across production calendars.
Market Dynamics
Corporate entertainment buyers are consolidating programming decisions under centralized procurement offices, compressing vendor negotiation cycles and favoring multi-venue contracts over house-by-house engagements across the North America Performing Art Companies Market.
Growth Catalysts
- Canada's federal cultural infrastructure tax credits:These incentives reduce capital costs for venue renovation and equipment upgrades, accelerating facility modernization timelines in Toronto and Vancouver.
- Streaming co-production treaties:Cross-border content agreements between Canadian and U.S. distributors expand revenue pools for theatrical properties with filmed adaptation potential.
- Immersive format technology:Projection mapping and spatial audio systems enable non-traditional venues to host performing arts programming without permanent infrastructure investment.
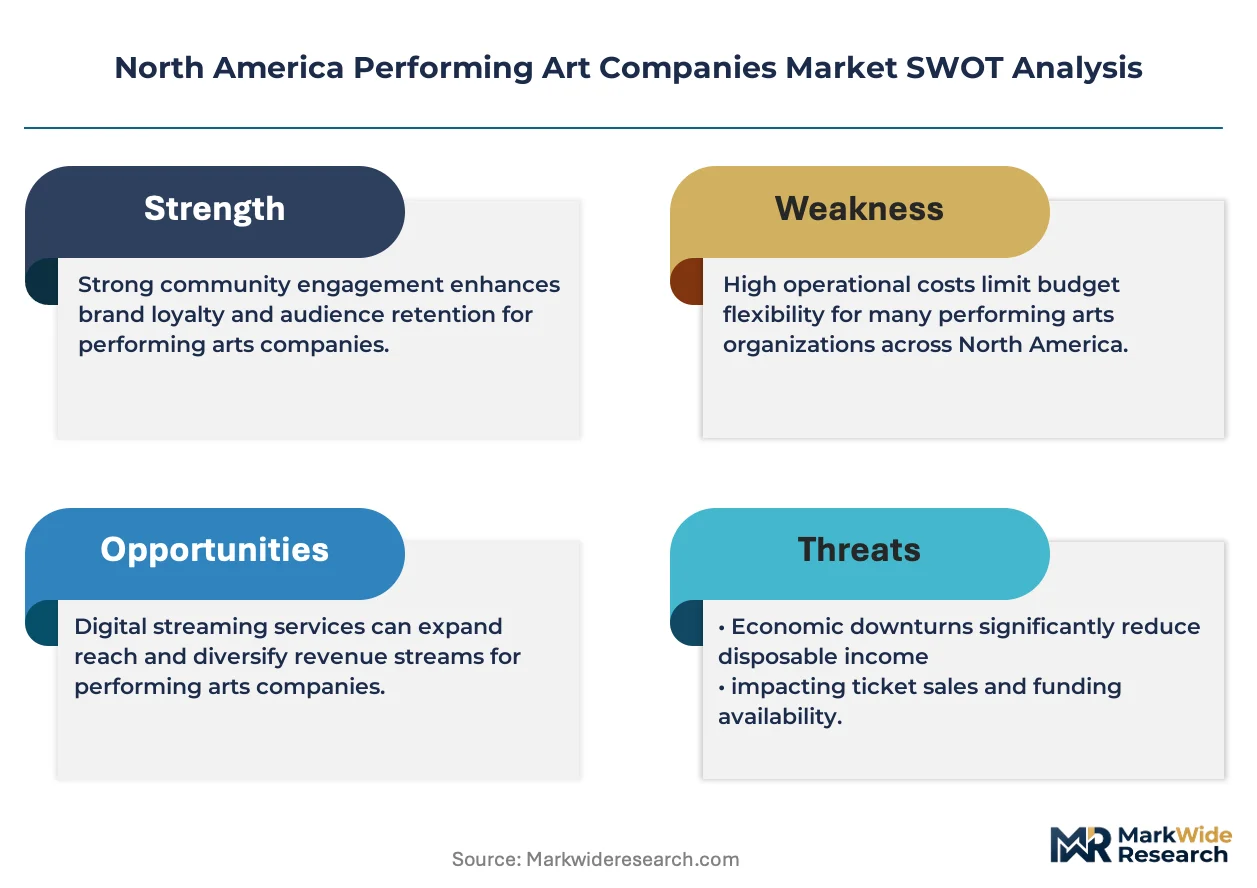
Market Restraints
- Union-scale labor coordination:IATSE and Actors' Equity Association minimums elevate production costs above non-union regional competitors, constraining pricing flexibility for mid-tier houses.
- Specialized acoustical engineering scarcity:Qualified theatrical acoustic consultants concentrate in New York, Los Angeles, and Chicago, creating bottlenecks for venue construction in secondary markets.
- Commercial real estate pressure:Rising lease rates in Manhattan's Theater District and downtown Toronto force companies to allocate larger revenue shares to occupancy costs.
Strategic Opportunities
- Mexico City corridor expansion:Underdeveloped performing arts infrastructure in Mexico's capital region presents first-mover advantages for touring productions and venue development.
- Hybrid digital-physical subscriptions:Bundled access to live performances plus streaming archives captures younger Audience Segment cohorts with fragmented attendance patterns.
- Municipal cultural district zoning:Tax abatement programs in Austin, Nashville, and Montreal's Quartier des Spectacles reduce operational overhead for companies locating within designated boundaries.
Industry Challenges
- Rigging systems certification timelines:OSHA and Canadian Centre for Occupational Health and Safety inspection backlogs delay production openings, compressing revenue-generating run lengths.
- International performer visa classifications:U.S. O-1 and P-3 visa processing variability disrupts casting for productions with cross-border talent requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Performing Art Companies Market |
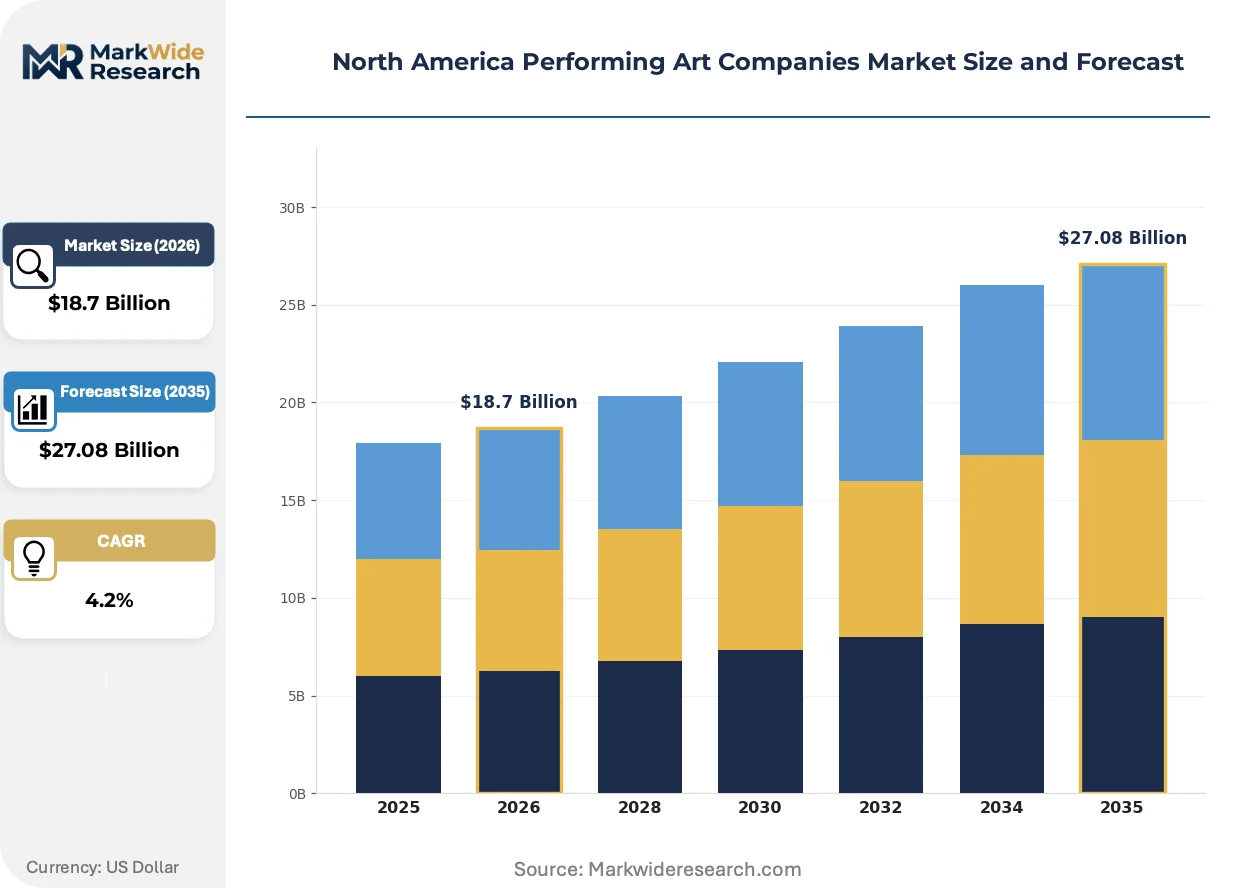
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Company Type: Theater, Dance, Music, Comedy Performance Genre: Classical, Contemporary, Experimental, Cultural Audience Segment: Families, Adults, Students, Tourists Funding Source: Government Grants, Sponsorships, Ticket Sales, Donations |
| Companies Covered | Paramount Global, The Madison Square Garden Company, The Walt Disney Company, The Shubert Organization, Broadway Across America, Live Nation Entertainment, Comcast Corporation, The Metropolitan Opera, Cirque du Soleil, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Performing Art Companies Market Strategic Shifts
Production pipelines are bifurcating between spectacle-driven immersive experiences and stripped-down, flexible touring formats, forcing companies to choose capital intensity strategies rather than pursuing both simultaneously.
Projection-mapped scenic environments are overtaking traditional physical set construction in mid-scale theatrical productions. Regional houses in Denver, Seattle, and Montreal adopt these systems to reduce load-in labor and storage costs. The technology is overtaking conventional scenery shops as the default production method for limited-run engagements.
The U.S. National Endowment for the Arts has tightened grant compliance requirements around accessibility accommodations and community engagement metrics. Companies must now document ADA-compliant seating ratios and free-ticket distribution to qualify for federal funding. Small and mid-size theaters in the Midwest and Southeast face the steepest administrative burden from these reporting obligations.
Subscription models are fragmenting into single-ticket aggregation platforms. Younger audiences in the New York metropolitan area purchase through TodayTix and Goldstar rather than committing to season packages. This shift concentrates pricing power with algorithmic discount channels and erodes the cash-flow predictability that sustained resident company economics for decades.
North America Performing Art Companies Market Segmentation
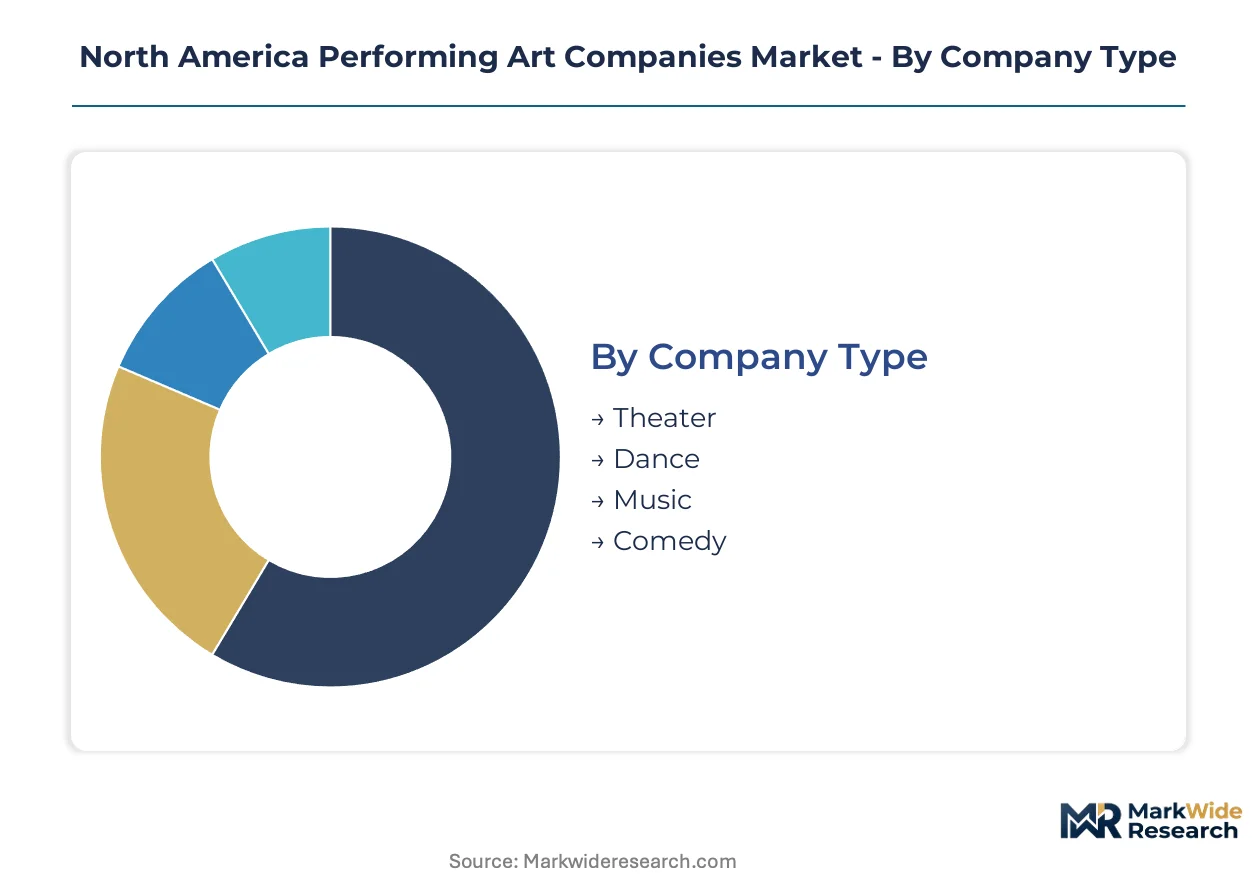
Segmentation in the North America Performing Art Companies Market reveals how capital intensity, audience development costs, and venue infrastructure requirements vary dramatically across organizational models. Understanding these divides allows stakeholders to align programming decisions with sustainable revenue architecture.
Company Type:
Theater companies operate as permanent resident institutions with dedicated venue infrastructure, while dance, music, and comedy organizations range from embedded presenting series to standalone touring entities.
- Theater:Permanent venue infrastructure anchors subscription renewal economics and multi-year artistic planning. Broadway houses in Manhattan and resident theaters in Chicago concentrate the highest revenue density due to real estate scarcity and tourist foot traffic.
- Dance:Repertory companies maintain year-round dancer contracts with specialized flooring and rigging requirements. Toronto and Vancouver companies leverage Canada's federal cultural infrastructure tax credits to modernize facilities.
- Music:Orchestras and opera companies face acute pressure from aging subscriber bases and pension obligations.
- Comedy:Stand-up clubs and improv theaters operate with lower fixed costs and shorter programming cycles.
Theater leads volumes today; comedy is gaining share fastest.
Performance Genre:
Genre classification determines production cost structures, union labor requirements, and the feasibility of hybrid digital-physical distribution strategies.
- Classical:Shakespearean repertory and canonical opera demand specialized performer training and extended rehearsal periods. The Metropolitan Opera and Stratford Festival sustain audience loyalty through institutional heritage.
- Contemporary:New plays and devised work attract younger demographics with flexible staging and immersive technology. Projection-mapped scenic environments reduce load-in costs for limited-run engagements in Denver and Montreal.
- Experimental:Interdisciplinary work occupies non-traditional venues with lower occupancy overhead.
- Cultural:Indigenous and diaspora programming accesses dedicated grant streams from the National Endowment for the Arts and Canadian Heritage.
Classical retains the largest subscriber base; contemporary climbs the fastest among younger cohorts.
Audience Segment:
Audience classification shapes pricing architecture, accessibility requirements, and the viability of bundled subscription models versus single-ticket aggregation.
- Families:Matinee programming and educational outreach require ADA-compliant facilities and child-safe rigging certification. Disney Theatrical Productions dominates this segment with spectacle-driven touring shows.
- Adults:Evening subscriptions generate the most predictable cash flow for resident companies. Corporate entertainment buyers in the New York metropolitan area consolidate procurement decisions for this cohort.
- Students:Rush ticketing and educational matinees build long-term audience pipelines.
- Tourists:Transient demand concentrates in Broadway and Las Vegas with minimal loyalty effects.
Adults provide the revenue foundation; students show the steepest expansion trajectory as houses invest in pipeline development.
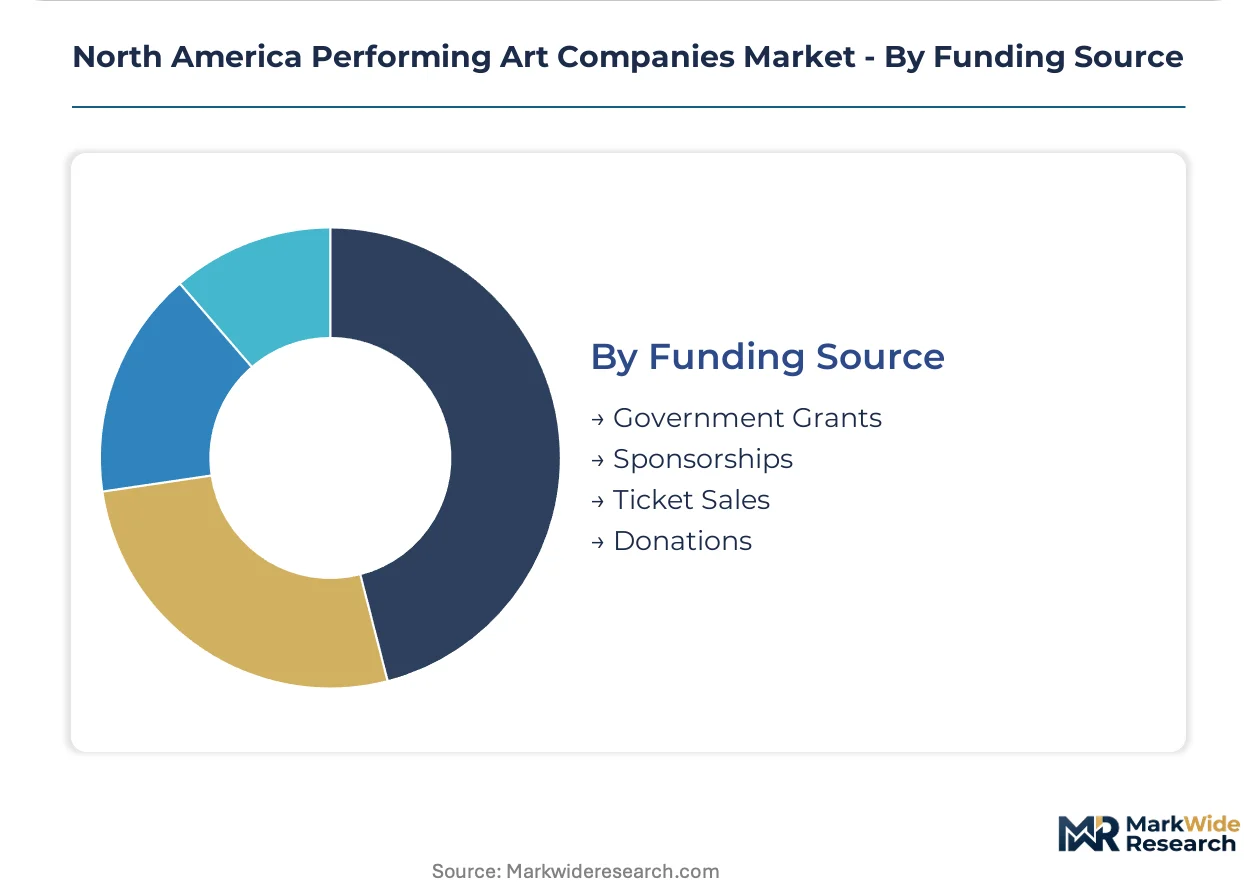
Funding Source:
Capital composition determines organizational risk tolerance, programming autonomy, and vulnerability to macroeconomic cycles or political shifts.
- Government Grants:NEA and Canadian Heritage funding requires documented accessibility accommodations and community engagement metrics. Small Midwest theaters face administrative burden from compliance reporting.
- Sponsorships:Corporate partnerships concentrate in financial services and technology sectors seeking entertainment procurement for client cultivation.
- Ticket Sales:Earned revenue exposes companies to demand volatility and algorithmic discount platform erosion.
- Donations:Individual giving sustains operating reserves for companies with established development infrastructure.
Ticket sales dominate current revenue mixes; sponsorships are expanding most quickly as corporate entertainment budgets rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York City metropolitan area concentrates the highest revenue density in North American performing arts, anchored by Broadway's theater district real estate scarcity and sustained tourist foot traffic.
United States
Corporate entertainment buyers in Manhattan consolidate procurement decisions under centralized offices, compressing vendor negotiation cycles. OSHA governs performer and crew workplace conditions through rigging systems certification requirements. Chicago's resident theater district sustains subscription renewal economics through permanent venue infrastructure and multi-year artistic planning.
Canada
Federal cultural infrastructure tax credits reduce capital costs for venue renovation in Toronto and Vancouver, accelerating facility modernization timelines. Canadian Heritage shapes funding eligibility through grant compliance requirements around accessibility accommodations. Montreal's Quartier des Spectacles leverages municipal cultural district zoning to reduce operational overhead for companies locating within designated boundaries.
Mexico
Underdeveloped performing arts infrastructure in Mexico City presents first-mover advantages for touring productions seeking untapped audience development. The country's national cultural ministry administers venue construction permits and performer work authorization protocols. Guadalajara's emerging theater district attracts regional capital as secondary market demand for contemporary programming expands.
North America Performing Art Companies Market Competitive Environment
Global majors compete with regional champions across venue control and touring logistics, creating a tiered structure where real estate holdings and promoter networks determine pricing power. The vendor base spans vertically integrated entertainment conglomerates, specialized theatrical producers, and venue-centric operators. Three archetypes dominate: spectacle-driven family entertainment producers, subscription-based resident theater companies, and algorithmic ticketing platform operators. Competitive moves concentrate on venue acquisition and multi-venue contract consolidation.
Within the vertically integrated tier, The Walt Disney Company and Comcast Corporation exemplify conglomerate-scale operations spanning theatrical production and streaming distribution. Live Nation Entertainment anchors continental touring logistics through venue control and promoter network density. The Shubert Organization occupies a distinct position in Broadway real estate, sustaining pricing power across forty-plus theaters through concentrated Manhattan holdings.
| Leading Market Players |
|---|
| Paramount Global |
| The Madison Square Garden Company |
| The Walt Disney Company |
| The Shubert Organization |
| Broadway Across America |
| Live Nation Entertainment |
| Comcast Corporation |
| The Metropolitan Opera |
| Cirque du Soleil |
| Others |
Value Chain & Pricing Dynamics
Union-scale rigger and stagehand concentration in Manhattan and Chicago creates labor-cost differentials that separate Broadway premium pricing from regional house economy tiers across the North America Performing Art Companies Market. IATSE minimum wage floors in New York City compress margins for mid-tier productions while elevating ticket-price floors, forcing secondary markets toward scaled-down touring formats or non-union alternatives.
Pricing Analysis
Input-cost pass-through from specialized acoustical engineering and rigging certification dominates pricing architecture in this market. Three-tier pricing structure across premium orchestra, standard mezzanine, and economy rear-balcony levels reflects union labor intensity and venue real estate costs rather than performance quality alone. Pricing pressure stems from algorithmic discount platforms like TodayTix eroding subscription yield, particularly for adult segment buyers in the New York metropolitan area. Corporate entertainment buyers show lowest price sensitivity due to consolidated procurement budgets, while student rush-ticket purchasers drive volume at compressed margins.
Supply Chain Analysis
Workforce availability for theatrical acoustic consultants and certified rigging engineers concentrates in the United States, Canada, and Mexico's emerging production hubs. Production inputs draw from specialized scenic construction shops in Toronto, projection-mapped technology vendors in Los Angeles, and touring logistics coordinators in Chicago. Single-source vulnerability around OSHA and Canadian Centre for Occupational Health and Safety inspector certification creates bottlenecks that delay production openings. Distribution runs through Live Nation Entertainment's venue network and Broadway Across America's touring circuits, with municipal cultural district zoning in Austin and Montreal creating alternative channel nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as audience development costs rise and corporate entertainment buyers consolidate procurement toward multi-venue contracts with premium production specifications.
For Market Incumbents: Deploy venue control as the primary defensive lever. Acquire or secure long-term leases in municipal cultural districts with tax abatement eligibility to offset commercial real estate pressure in Manhattan and Toronto. Deepen backward integration into projection-mapped scenic technology to reduce load-in labor dependencies and defend margin position against algorithmic discount platform erosion. For New Entrants and Emerging Players: Begin with immersive format technology deployment in Mexico City's underdeveloped venue infrastructure, where first-mover advantages exist for touring productions and facility development. Target student segment pipeline development through educational matinee programming and hybrid digital-physical subscription bundles. Pursue municipal cultural district zoning in Austin, Nashville, or Guadalajara as the go-to-market anchor for operational cost reduction. For Investors and Strategic Acquirers: Entertainment conglomerates with streaming distribution arms are the most active acquirer in this space, seeking theatrical properties with filmed adaptation potential under cross-border co-production treaties. Long-term viability hinges on real estate holdings in tourist-concentrated corridors and resident company subscription renewal infrastructure. Watch rigging systems certification timeline compression as the signal for operational feasibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Venue Acquisition in Cultural Districts | Municipal tax abatements in Austin and Montreal reduce occupancy cost exposure for resident companies. |
| Hybrid Digital-Physical Subscription Launch | Bundled access captures younger Audience Segment cohorts with fragmented attendance patterns. |
| Immersive Format Technology Investment | Projection-mapped scenic environments reduce load-in labor and storage costs for limited-run engagements. |
| Multi-Venue Contract Consolidation | Corporate entertainment buyers favor centralized procurement offices over house-by-house vendor negotiations. |
| Streaming Co-Production Treaty Utilization | Cross-border agreements between Canadian and U.S. distributors expand revenue pools for theatrical adaptations. |
Study Parameters
Multiple input streams — executive interviews with theater company artistic directors and venue operators, regulatory filings with OSHA and Canadian Heritage, and subscription platform transaction data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged resident company managing directors, IATSE local union representatives, corporate entertainment procurement officers, and municipal cultural development authorities. Secondary validation drew from National Endowment for the Arts grant disbursement records, Canadian federal tax credit utilization databases, and SEC filings for publicly traded entertainment conglomerates.
Historical venue utilization rates were cross-referenced against panel input from subscription platform operators and touring logistics coordinators to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include Company Type, Performance Genre, Audience Segment, and Funding Source, with hybrid digital-physical format adoption tracked as an industry-specific overlay. CAGRs were derived from trend extrapolation of facility modernization timelines and corporate entertainment budget expansion patterns.
Several conditions sit outside the modeled scope, including abrupt shifts in international performer visa classifications and municipal zoning reclassifications for cultural districts. Forecasts reflect assumptions around sustained tourist foot traffic in Broadway and sustained federal cultural infrastructure tax credit renewal in Canada. Material deviation in union-scale labor negotiation outcomes or OSHA inspection backlog resolution warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Global Roller Coaster Market
Media and Entertainment
PC Games Market
Media and Entertainment
Russia OOH and DOOH Market
Media and Entertainment
Pay TV Operator Market
Media and Entertainment
Camera Jib Market
Media and Entertainment
Finland OOH and DOOH Market
Media and Entertainment
China in-Game Advertising Market
Media and Entertainment
Events and Exhibition Market
Media and Entertainment
LED Billboard Market
Media and Entertainment
US Newspaper Market
Media and Entertainment
Subscription Background Music Service Market
Media and Entertainment
Drone Wedding Photography Market
Media and Entertainment
Electronic Dance Music (EDM) Market
Media and Entertainment
Media Monitoring Tools Market
Media and Entertainment
Asia-Pacific Animation Market
Media and Entertainment
Japan Virtual Reality Gaming Market