
 United Kingdom E-Commerce Logistics Market | 2026-2036
United Kingdom E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom E-Commerce Logistics Market Insights
Modular packaging configurations is decoupling bulk freight from final-mile unitization across UK e-commerce supply chains. Royal Mail leverages its universal service obligation infrastructure to sustain next-day coverage in rural postcodes where competitors withdraw. Amazon Logistics dominates same-day fulfillment through captive warehouse networks ringing London, Birmingham, and Manchester. DPD UK differentiates via precise one-hour delivery windows backed by proprietary predictive routing algorithms.
United Kingdom e-commerce logistics encompasses the integrated movement, storage, and fulfillment of goods ordered through digital channels, typically involving automated sortation systems processing 15,000–25,000 parcels per hour and warehouse management software coordinating inventory across multi-node distribution networks. Its primary commercial purpose is collapsing order-to-delivery cycle times while minimizing cost-per-parcel for online retailers. Last mile delivery anchors the highest cost-to-serve segment, absorbing roughly half of total logistics expenditure as urban congestion and failed delivery attempts erode margins. Automation solutions within warehouse management represent the fastest-expanding technology category, driven by labor scarcity in regions such as the East Midlands where fulfillment center density has outstripped local workforce supply. Cloud-based platforms connecting inventory management to order fulfillment are maturing into table-stakes infrastructure, with margin pools shifting toward artificial intelligence applications for demand forecasting and dynamic route optimization.
The UK's Plastic Packaging Tax, enforced by HM Revenue and Customs, is reshaping material specifications for outbound shipping cartons and void fill across fulfillment networks. Health and Safety Executive guidelines governing warehouse automation and manual handling establish operational parameters for robotic deployment in dense storage environments. Trading Standards and the Competition and Markets Authority scrutinize delivery time claims and subscription pricing transparency, constraining how carriers advertise service levels. Stakeholders must monitor whether proposed revisions to driver working-time regulations tighten capacity during peak seasonal windows.
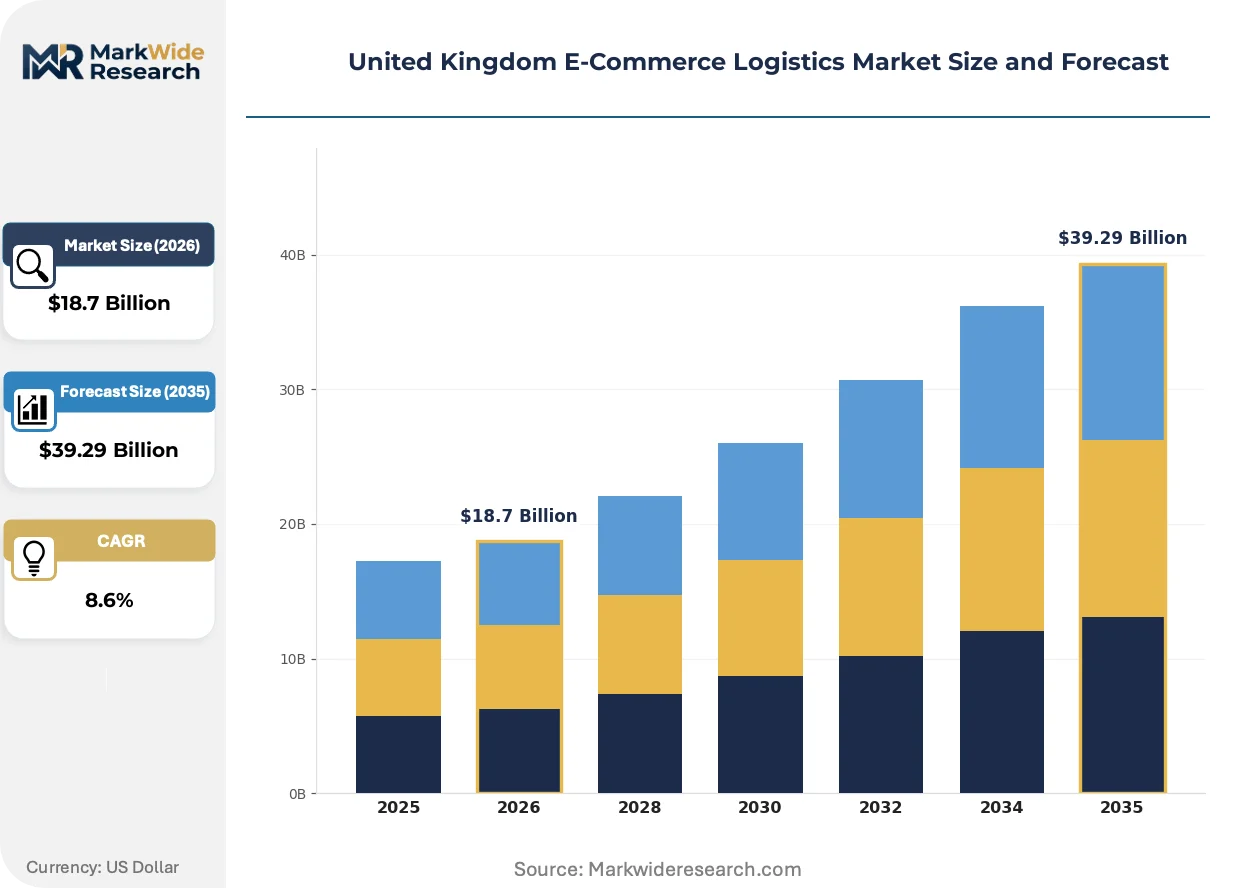
Market Dynamics
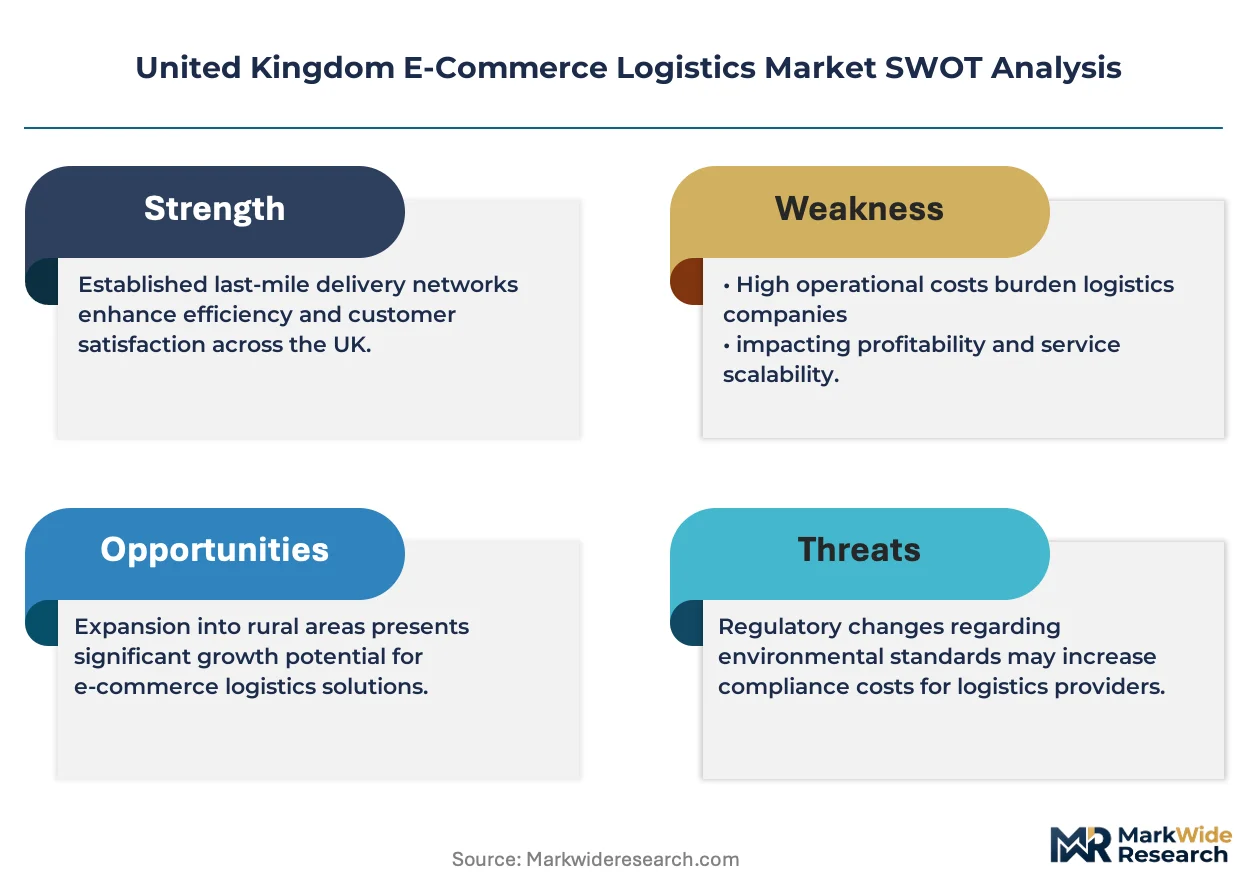
HM Revenue and Customs' Plastic Packaging Tax is compressing margin structures across UK fulfillment networks, forcing rapid material substitution in outbound shipping cartons and void fill specifications. Automated sortation investments are accelerating along England's Midlands logistics corridor as labor scarcity intensifies near dense fulfillment clusters.
Growth Catalysts
- Regulatory pressure on plastic packaging:HM Revenue and Customs enforces minimum recycled content thresholds, driving demand for paper-based alternatives and reusable shipping systems across fulfillment operations.
- Same-day delivery expectations:Urban consumers in Greater London, Birmingham, and Manchester now demand sub-24-hour fulfillment, expanding captive warehouse networks and micro-fulfillment node deployment.
- Automated sortation throughput:Systems processing 15,000–25,000 parcels per hour are displacing manual handling in the East Midlands where workforce availability lags facility expansion.
Market Restraints
- Input cost volatility in corrugated board:Pulp price fluctuations and energy-intensive production compress packaging margins for outbound shipping materials.
- Supply concentration in motorway-adjacent land:Automated hub development clusters near M1, M6, and M25 junctions, driving land price premiums and site scarcity in the West Midlands.
- Technical limitation in rural last-mile economics:Low parcel density outside urban corridors prevents automated route optimization from achieving cost parity with universal service obligation networks.
Strategic Opportunities
- Underpenetrated Scottish Highlands and Islands:Remote postcode fulfillment remains dependent on legacy postal infrastructure, creating white space for drone-enabled or locker-based delivery models.
- Regulatory tailwind from extended producer responsibility reforms:Packaging waste regulations incentivize return-loop logistics and reusable container pooling systems.
- Technology convergence of AI routing and electric vehicle fleets:Predictive algorithms paired with zero-emission last-mile vehicles unlock congestion-charge-exempt operations in London's Ultra Low Emission Zone.
Industry Challenges
- Technical workforce scarcity in robotics maintenance:Automated storage and retrieval systems require specialized technicians that outpace regional training pipeline output in the East Midlands.
- Capex intensity in warehouse management software integration:Legacy enterprise resource planning systems demand substantial retrofit expenditure to connect with cloud-based inventory platforms.
- Compliance timeline compression for driver working-time regulations:Proposed revisions to transport regulations threaten peak-season capacity planning flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom E-Commerce Logistics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehouse Management, Last Mile Delivery, Inventory Management, Order Fulfillment Customer Type: Small Businesses, Large Enterprises, Online Marketplaces, Third-Party Retailers Technology: Automation Solutions, Tracking Systems, Cloud-Based Platforms, Artificial Intelligence End User: Retailers, Manufacturers, Distributors, E-Tailers |
| Companies Covered | Royal Mail, Evri, DPD UK, DHL Parcel UK, Amazon Logistics, FedEx UK, Yodel, UPS UK, Parcelforce Worldwide, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom E-Commerce Logistics Market Trends and Innovations
Artificial intelligence applications are migrating from experimental pilots to production-grade infrastructure across UK fulfillment networks, compressing decision cycles in demand forecasting and dynamic routing. Cloud-native warehouse management platforms are maturing into table-stakes architecture, shifting competitive differentiation toward predictive capabilities.
Autonomous mobile robots are consolidating fragmented picking workflows in dense storage environments. Third-party logistics providers and mid-market retailers are deploying these systems at accelerating pace to offset labor availability gaps. The technology is consolidating previously siloed manual handling processes into continuous, software-orchestrated fulfillment flows that reduce order-to-ship intervals.
HM Revenue and Customs' Plastic Packaging Tax is mandating minimum 30% recycled content in plastic shipping materials. Fulfillment operators are reformulating void fill specifications and trialing paper-based alternatives to avoid per-tonne tax liability. Fashion and apparel retailers with high return volumes face disproportionate compliance burden as outbound and reverse logistics packaging volumes compound.
Subscription commerce is restructuring inventory commitment patterns across UK e-commerce. Beauty and pet food verticals are shifting from transactional replenishment to scheduled auto-delivery, compressing forecasting horizons and demanding predictive replenishment algorithms. This pattern concentrates in Greater London where urban density supports consolidated delivery rounds and locker network utilization.
United Kingdom E-Commerce Logistics Market Segmentation
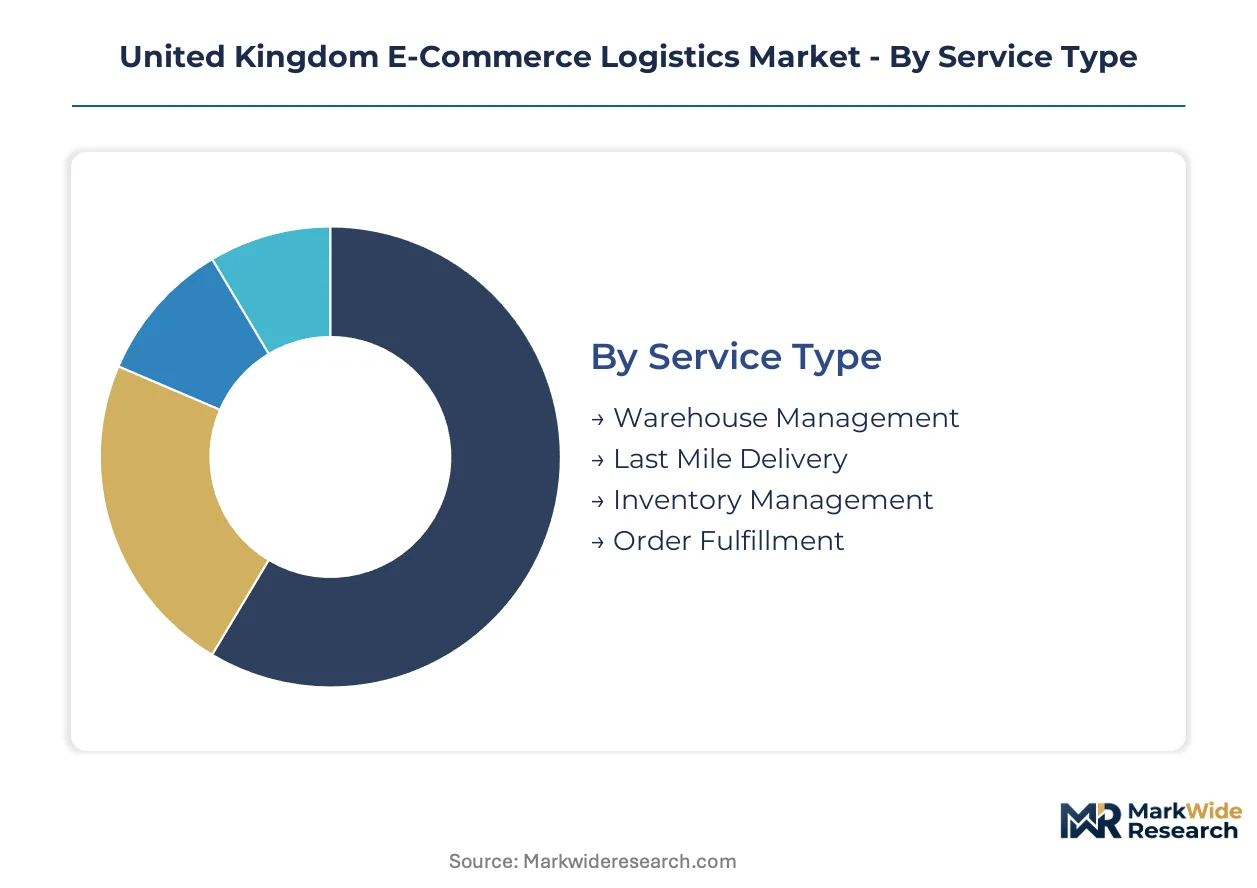
E-commerce logistics segmentation in the United Kingdom reveals how service specialization, customer scale, and technology maturity create distinct competitive arenas. Each dimension shapes capital deployment patterns and margin structures differently across England's Midlands corridor and Greater London fulfillment clusters.
Service Type:
Volume-intensive warehousing commands premium pricing in the East Midlands where labor scarcity bites deepest, while last-mile delivery absorbs disproportionate cost-to-serve in rural postcodes.
- Warehouse Management:Automated storage and retrieval systems coordinate inventory across multi-node distribution networks, processing 15,000–25,000 parcels per hour at motorway-adjacent hubs near M1 and M6 junctions. Demand concentrates in the West Midlands where Royal Mail and Amazon Logistics compete for captive warehouse space. HM Revenue and Customs' Plastic Packaging Tax is forcing rapid retrofit of void fill specifications within these facilities.
- Last Mile Delivery:Final-mile unitization decouples from bulk freight through predictive routing algorithms and micro-fulfillment node deployment. DPD UK differentiates via precise one-hour delivery windows in Greater London, Birmingham, and Manchester, though low parcel density in Scottish Highlands and Islands prevents cost parity with universal service obligation networks.
- Inventory Management:Cloud-native platforms connect stock visibility to order fulfillment across fragmented retail networks.
- Order Fulfillment:Subscription commerce patterns in beauty and pet food verticals compress forecasting horizons for scheduled auto-delivery.
Today's leader: Warehouse Management. Tomorrow's challenger: Last Mile Delivery.
Customer Type:
Enterprise scale determines automation access, with large operators capturing robotic throughput advantages that mid-market players cannot replicate.
- Large Enterprises:Captive warehouse networks ring London, Birmingham, and Manchester, enabling same-day fulfillment through direct-to-consumer infrastructure. Amazon Logistics dominates this tier with proprietary sortation hubs and electric vehicle fleets exempt from London's Ultra Low Emission Zone charges.
- Online Marketplaces:Platform aggregators consolidate merchant inventory into shared fulfillment pools, demanding predictive replenishment algorithms for auto-delivery scheduling. Beauty and pet food verticals concentrate in Greater London where urban density supports consolidated delivery rounds.
- Small Businesses:Third-party logistics dependency limits automation access in the East Midlands.
- Third-Party Retailers:Fashion and apparel specialists face disproportionate packaging compliance burden from high return volumes.
Margin pools favor Large Enterprises now. Online Marketplaces are climbing the fastest as subscription commerce restructures inventory commitment patterns.
Technology:
Cloud infrastructure has matured into table-stakes architecture, shifting differentiation toward artificial intelligence applications for demand forecasting and dynamic route optimization.
- Artificial Intelligence:Predictive algorithms compress decision cycles in demand forecasting and dynamic routing, migrating from experimental pilots to production-grade infrastructure. DPD UK deploys proprietary predictive routing to back one-hour delivery windows, while cloud-based platforms integrate AI for congestion-charge-exempt electric vehicle fleet deployment in London.
- Automation Solutions:Autonomous mobile robots consolidate fragmented picking workflows in dense storage environments, offsetting labor availability gaps in the East Midlands where workforce supply lags facility expansion. Specialized technician scarcity constrains maintenance capacity for automated storage and retrieval systems.
- Cloud-Based Platforms:Native architecture connects inventory management to order fulfillment across multi-node networks.
- Tracking Systems:Real-time visibility infrastructure supports precise delivery window commitments.
Automation Solutions anchor current investment. Artificial Intelligence represents the steepest expansion trajectory as margin pools shift toward predictive capabilities.
End User:
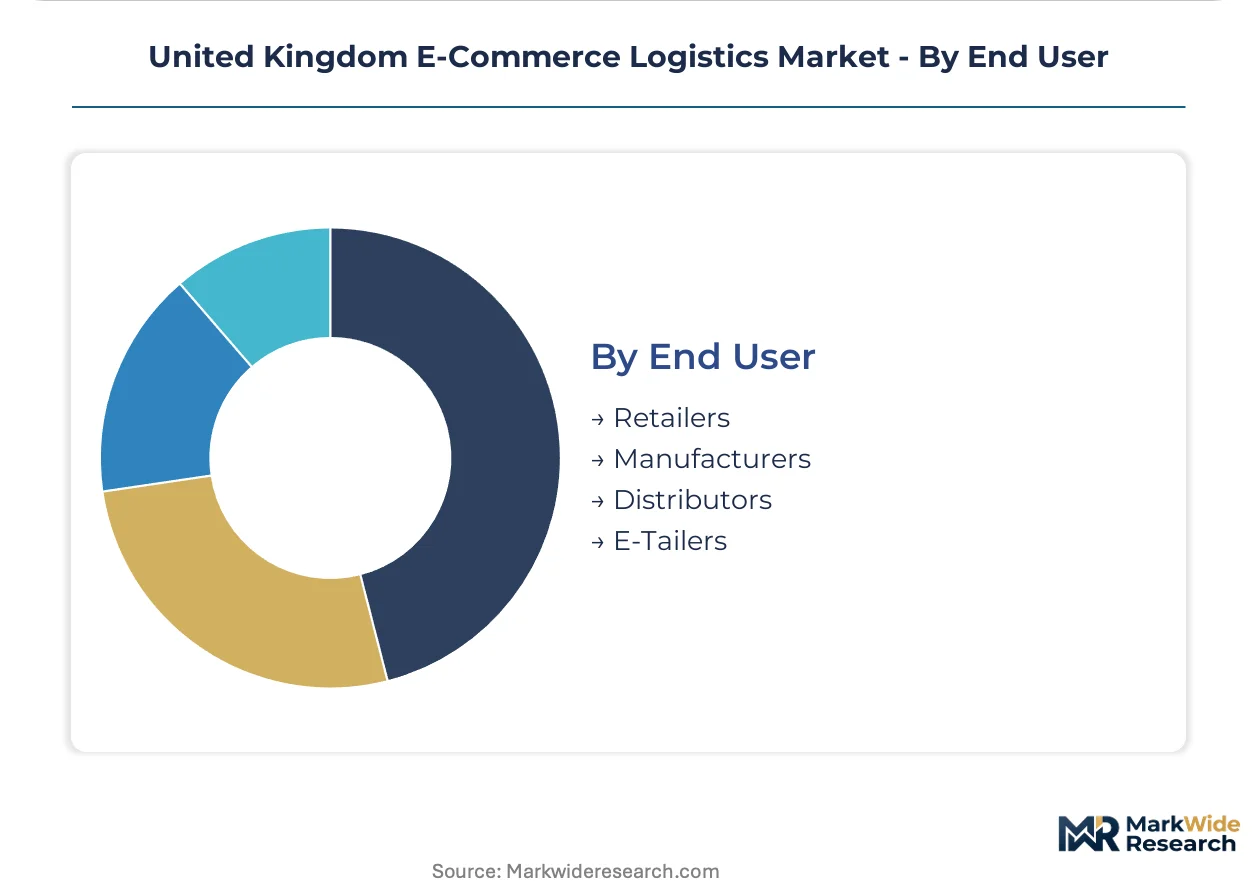
Retail-facing fulfillment dominates parcel volume, though manufacturer direct-to-consumer channels are eroding traditional distributor intermediation.
- E-Tailers:Pure-play digital merchants operate without physical store networks, collapsing order-to-delivery cycle times through micro-fulfillment node deployment in Greater London. Fashion and apparel e-tailers expanding across England's Midlands logistics corridor face compounded packaging volumes from high return rates under Plastic Packaging Tax compliance.
- Retailers:Omnichannel operators integrate online and physical inventory pools, demanding warehouse management software coordination across legacy enterprise resource planning systems that require substantial retrofit expenditure.
- Manufacturers:Direct-to-consumer fulfillment networks bypass traditional distribution tiers.
- Distributors:Wholesale intermediaries face margin compression from disintermediation.
E-Tailers set the pace today. Manufacturers are gaining share fastest as brand-owned fulfillment displaces wholesale channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's e-commerce logistics infrastructure traces its modern lineage to Royal Mail's universal service obligation network established in the 17th century, later scaled through motorway corridor development and automated sortation investments across England's industrial heartland.
London and the Southeast
Greater London generates the highest parcel density in the UK, with same-day delivery expectations driving micro-fulfillment node deployment. HM Revenue and Customs' Plastic Packaging Tax compliance costs concentrate here due to high fashion and beauty e-tailer volumes. The M25 ring hosts captive warehouse networks where Amazon Logistics and DPD UK compete for urban last-mile dominance.
West Midlands
The M6 and M1 motorway junctions anchor England's densest automated sortation hub cluster. Automated storage and retrieval systems process 15,000–25,000 parcels per hour where workforce availability lags facility expansion. Health and Safety Executive guidelines govern robotic deployment in these dense storage environments.
East Midlands
Technical workforce scarcity for robotics maintenance constrains automated fulfillment growth despite surging facility investment. Trading Standards scrutiny of delivery time claims affects carrier advertising strategies here. The region's fulfillment center density has outstripped local workforce supply, pushing wage premiums upward.
North England
Manchester and Leeds function as secondary fulfillment poles with motorway-adjacent land commanding premiums. Competition and Markets Authority oversight of subscription pricing transparency constrains how carriers structure service offerings. Electric vehicle fleet deployment accelerates to access congestion-charge-exempt operations.
Scottish Highlands and Islands
Low parcel density outside urban corridors prevents automated route optimization from achieving cost parity with Royal Mail's universal service obligation. Proposed revisions to driver working-time regulations threaten peak-season capacity planning flexibility. Remote postcode fulfillment remains dependent on legacy postal infrastructure with white space for drone-enabled delivery models.
United Kingdom E-Commerce Logistics Market Competitive Landscape
The competitive structure tilts toward integrated parcel networks with captive infrastructure. Royal Mail's universal service obligation sustains rural coverage where competitors withdraw, while Amazon Logistics and DPD UK dominate urban same-day corridors through proprietary sortation and predictive routing. Three archetypes define the field: universal service obligation carriers, captive e-commerce platforms, and independent parcel specialists. Capacity expansion along motorway corridors and strategic partnerships for last-mile technology licensing represent the dominant competitive moves.
Within the universal service obligation tier, Royal Mail and Parcelforce Worldwide occupy positions sustained by regulatory mandate and rural network density. Among independent parcel specialists, DPD UK exemplifies precision delivery window differentiation, while Evri represents mid-market volume aggregation. Amazon Logistics anchors the captive platform archetype with vertically controlled fulfillment networks. Yodel and DHL Parcel UK sit within the independent specialist tier competing on cost-positioned B2C delivery.
| Leading Market Players |
|---|
| Royal Mail |
| Evri |
| DPD UK |
| DHL Parcel UK |
| Amazon Logistics |
| FedEx UK |
| Yodel |
| UPS UK |
| Parcelforce Worldwide |
| Others |
Pricing and Supply Chain Analysis
HM Revenue and Customs' Plastic Packaging Tax is forcing fulfillment operators to reformulate void fill specifications and trial paper-based alternatives, compressing packaging margins and accelerating material substitution across outbound shipping operations. This regulatory pressure reshapes supplier selection criteria and concentrates procurement power among operators with scale to absorb compliance retrofit costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates UK e-commerce logistics, with premium tiers commanding substantial markups for sub-24-hour fulfillment and precise delivery windows in Greater London. Price differentiation hinges on delivery speed guarantees and geographic coverage density, with urban corridors showing least price sensitivity due to same-day delivery expectations. Cost compression in standard-tier B2C delivery is intensifying because of input volatility in corrugated board and energy-intensive production. Small businesses and third-party retailers exhibit highest price sensitivity, while large enterprises with captive infrastructure capture volume discounts that mid-market players cannot replicate.
Supply Chain Analysis
Reverse logistics flows from fashion and apparel e-tailers generate disproportionate packaging volumes under Plastic Packaging Tax compliance, compounding cost structures as outbound and return shipments both attract regulatory scrutiny. Geographic supply concentration for automated sortation equipment rests on Germany, China, and the USA, with UK fulfillment networks drawing from these manufacturing hubs for robotic systems processing 15,000–25,000 parcels per hour. Corrugated board, lithium-ion batteries for electric vehicle fleets, and specialized robotics components constitute critical input dependencies. Single-source vulnerability in motorway-adjacent land near M1, M6, and M25 junctions constrains hub expansion. Distribution runs through captive warehouse networks ringing London, Birmingham, and Manchester, with micro-fulfillment nodes penetrating dense urban postcodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scotland's remote postcode fulfillment gap against England's Midlands corridor density creates a geographic-arbitrage opportunity, with HM Revenue and Customs' Plastic Packaging Tax applying uniformly while last-mile economics diverge sharply by parcel density.
For Market Incumbents: Anchor defensive positioning through captive warehouse network expansion along England's Midlands logistics corridor and accelerated electric vehicle fleet deployment to secure congestion-charge-exempt operations in London's Ultra Low Emission Zone. Threats from Amazon Logistics' vertically controlled fulfillment networks demand countermeasures via proprietary predictive routing algorithm investment and micro-fulfillment node density in Greater Manchester and Birmingham. Certification in reusable container pooling systems under extended producer responsibility reforms represents a critical lever for margin defense. For New Entrants and Emerging Players: Direct-to-consumer platform integration offers the most penetrable route for mid-market retailers seeking automation access without captive infrastructure investment. White space concentrates in Scottish Highlands and Islands drone-enabled delivery models and locker-based fulfillment networks where Royal Mail's universal service obligation currently dominates. Target underpenetrated subscription commerce verticals in pet food and beauty with predictive replenishment algorithm partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with independent parcel specialists possessing proprietary routing technology and dense urban last-mile coverage in Birmingham and Manchester. Long-term viability favors operators with demonstrated compliance adaptation to HM Revenue and Customs packaging regulations and scalable cloud-native warehouse management platforms. Monitor proposed revisions to driver working-time regulations as the critical inflection signal for peak-season capacity planning flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Hub Expansion | Systems processing 15,000–25,000 parcels per hour offset labor scarcity in the East Midlands. |
| Electric Vehicle Fleet Deployment | Zero-emission last-mile vehicles unlock congestion-charge-exempt operations in London's Ultra Low Emission Zone. |
| Reusable Container Pooling Systems | Extended producer responsibility reforms incentivize return-loop logistics and packaging waste reduction. |
| Predictive Routing Algorithm Investment | Proprietary AI enables precise one-hour delivery windows that differentiate against universal service obligation networks. |
| Micro-Fulfillment Node Penetration | Urban density in Greater London supports consolidated delivery rounds and locker network utilization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fulfillment center operations directors, last-mile carrier network planners, warehouse automation procurement leads, and HM Revenue and Customs compliance officers with secondary validation. Trade data from UK customs records, Health and Safety Executive automation guidelines, Competition and Markets Authority subscription pricing rulings, and motorway corridor development filings anchored supply-side assessment. Bottom-up facility capacity counts and top-down parcel volume estimates were triangulated against carrier disclosure patterns.
Segment-weighting approaches distributed value and volume across service type, customer scale, technology maturity, and end-use vertical dimensions throughout the forecast period. CAGRs were derived from facility investment pipelines, labor availability projections, and regulatory compliance cost trajectories. Automated sortation throughput expansion rates and electric vehicle fleet penetration curves in London's Ultra Low Emission Zone served as industry-specific forecast inputs.
Driver working-time regulation revisions, pulp price volatility in corrugated board, and autonomous vehicle regulatory clearance delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about facility expansion timelines and technology adoption curves. Practitioners should monitor proposed transport regulation changes, packaging tax threshold adjustments, and robotics technician training pipeline output for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
Asia Pacific E-Commerce Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market