
 Nicotinic Acid Market | 2026-2036
Nicotinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Nicotinic Acid Market Foresight
Asset-light contract manufacturing and third-party API leasing is rewriting competitive entry barriers in nicotinic acid production. Lonza Group AG leverages its Swiss fermentation infrastructure to sustain high-purity pharmaceutical-grade output. Jubilant Life Sciences anchors Indian cost positions through backward integration into pyridine chemistry. Vertellus Specialties controls North American supply of specialty-grade material for niche pharmaceutical applications.
Nicotinic acid, also designated as vitamin B3 or pyridine-3-carboxylic acid, is a water-soluble organic compound with the molecular formula C6H5NO2, synthesized primarily via oxidation of 3-picoline or niacinamide hydrolysis for use in lipid modification and nutritional fortification. The compound serves dual industrial purposes: as an active pharmaceutical ingredient in dyslipidemia management and as a mandatory flour and grain fortificant in national food programs. Powder formulations dominate bulk pharmaceutical procurement due to lower unit costs and easier downstream processing into tablets and capsules. Extended-release oral forms command premium positioning in the application segment, as cardiovascular protocols favor controlled niacin delivery to minimize flushing side effects. The nutraceuticals channel shows faster volume expansion than mature food-fortification contracts, driven by direct-to-consumer supplement brands seeking USP-grade material.
FDA enforces USP monograph standards for nicotinic acid purity and dissolution profiles, while EMA and national European regulators apply REACH chemical safety protocols to imported bulk material. China's NMPA and SAMR jointly oversee pharmaceutical-grade niacin registration, creating a bifurcated compliance landscape between nutritional and drug-classified supply chains. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as divergence in impurity limits threatens cross-border API shipments and contract manufacturing location decisions.
Market Dynamics
Pharmaceutical-grade purity mandates from FDA and EMA are compressing supplier margins while simultaneously consolidating procurement toward fermentation-based producers with captive pyridine supply.
Growth Catalysts
- REACH chemical safety protocols:European ECHA registration requirements for imported bulk material are filtering out low-purity traders, tightening supply discipline and rewarding compliant API manufacturers with contract renewals.
- Extended-release formulation demand:Cardiovascular therapy protocols favor controlled niacin delivery systems that minimize flushing side effects, pulling pharmaceutical-grade powder procurement toward specialized compaction-ready grades.
- Shandong-Tianjin production cluster:Chinese fermentation infrastructure expansion feeds both domestic nutraceutical consumption and export API contracts to Southeast Asian generic drug manufacturers.
Market Restraints
- 3-picoline feedstock volatility:Pyridine derivative pricing swings directly compress niacinamide hydrolysis economics, forcing Indian contract manufacturers to absorb margin compression or pass through costs.
- Single-source fermentation capacity:Swiss and German pharmaceutical-grade suppliers control limited high-purity bioreactor slots, creating allocation risk for Q4 API procurement cycles.
- Niacinamide substitution in fortification:Food-grade applications increasingly accept amide-form vitamin B3 where acid-form functionality is non-critical, displacing nicotinic acid volume in mature grain programs.
Strategic Opportunities
- Direct-to-consumer nutraceutical channels:USP-grade material demand from supplement brands bypasses traditional pharmaceutical distributor markups, enabling margin capture for certified producers.
- Indian PLI scheme alignment:Pharmaceutical-grade API production incentives under India's active pharmaceutical ingredient subsidy program reduce capital recovery timelines for fermentation facility investments.
- Continuous manufacturing integration:Convergence of flow chemistry with real-time release testing compresses batch-to-batch variability, qualifying suppliers for just-in-time oral solid dosage contracts.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent impurity limits between USP, EP, and ChP standards force dual-filed documentation for cross-border shipments, extending regulatory approval timelines.
- Specialized fermentation workforce scarcity:Bioprocess engineering talent capable of maintaining pharmaceutical-grade aseptic operations concentrates in Basel and Basel-area training pipelines.
- Legacy quality management system upgrades:Paper-based batch records at mid-scale Indian producers require capital-intensive digitization to meet EMA Annex 11 computerized system validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nicotinic Acid Market |
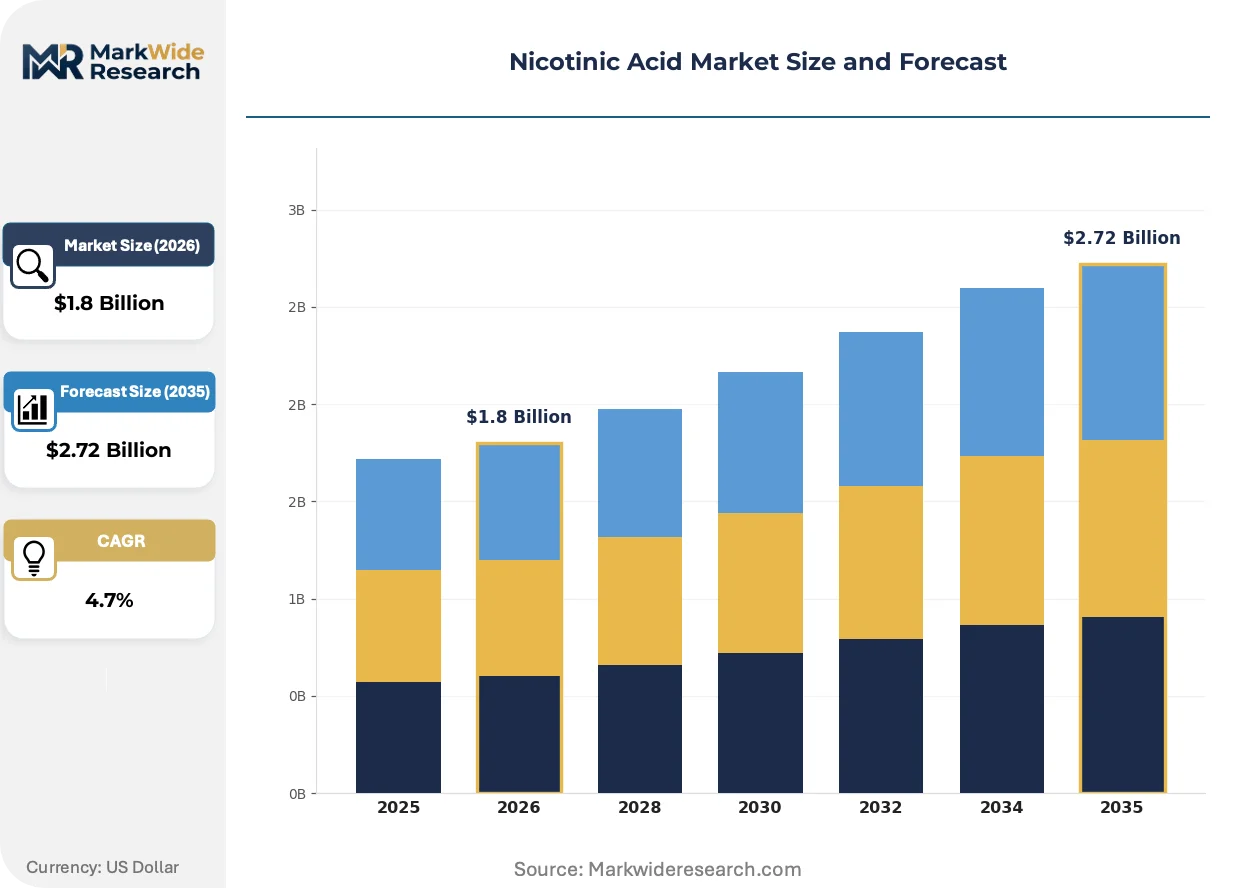
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Capsules Application: Pharmaceuticals, Nutraceuticals, Dietary Supplements, Food Industry Form: Immediate Release, Extended Release, Oral, Injectable End User: Hospitals, Clinics, Pharmacies, Research Institutions |
| Companies Covered | Lonza Group AG, Jubilant Life Sciences Limited, Vertellus Specialties Inc., DSM Nutritional Products, Shandong Hongda Biotechnology Co., Ltd., BASF SE, Glanbia plc, Resonance Specialties Limited, Tianjin Zhongrui Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nicotinic Acid Market Shifts & Advancements
Process analytical technology deployment is compressing release testing timelines while regulatory data integrity mandates force quality system modernization across contract manufacturing networks.
Continuous flow oxidation of 3-picoline is digitizing batch record review by embedding spectroscopic PAT sensors directly into reactor loops. European generic drug manufacturers are adopting these systems fastest, qualifying real-time release protocols that bypass traditional 14-day quarantine holds. This compression is enabling just-in-time API procurement models that reduce working capital requirements for oral solid dosage facilities.
EMA's updated Annex 1 sterile manufacturing guidance extends environmental monitoring requirements to pharmaceutical-grade niacin facilities handling high-potency lipid-modifying APIs. Bulk material importers must now demonstrate closed-system transfer technology for powder handling operations. Swiss and Irish contract manufacturers are responding fastest, retrofitting isolator-based dispensing suites ahead of 2025 inspection cycles.
Hospital procurement consortia are consolidating annual niacin contracts into multi-year framework agreements with inflation-linked price adjustment mechanisms. Group purchasing organizations in Germany and France are displacing spot-market spot buys with committed volume tiers. This behavioral shift concentrates supplier qualification efforts toward large-scale fermentation producers with demonstrated pharmacovigilance track records.
Nicotinic Acid Market Segmentation
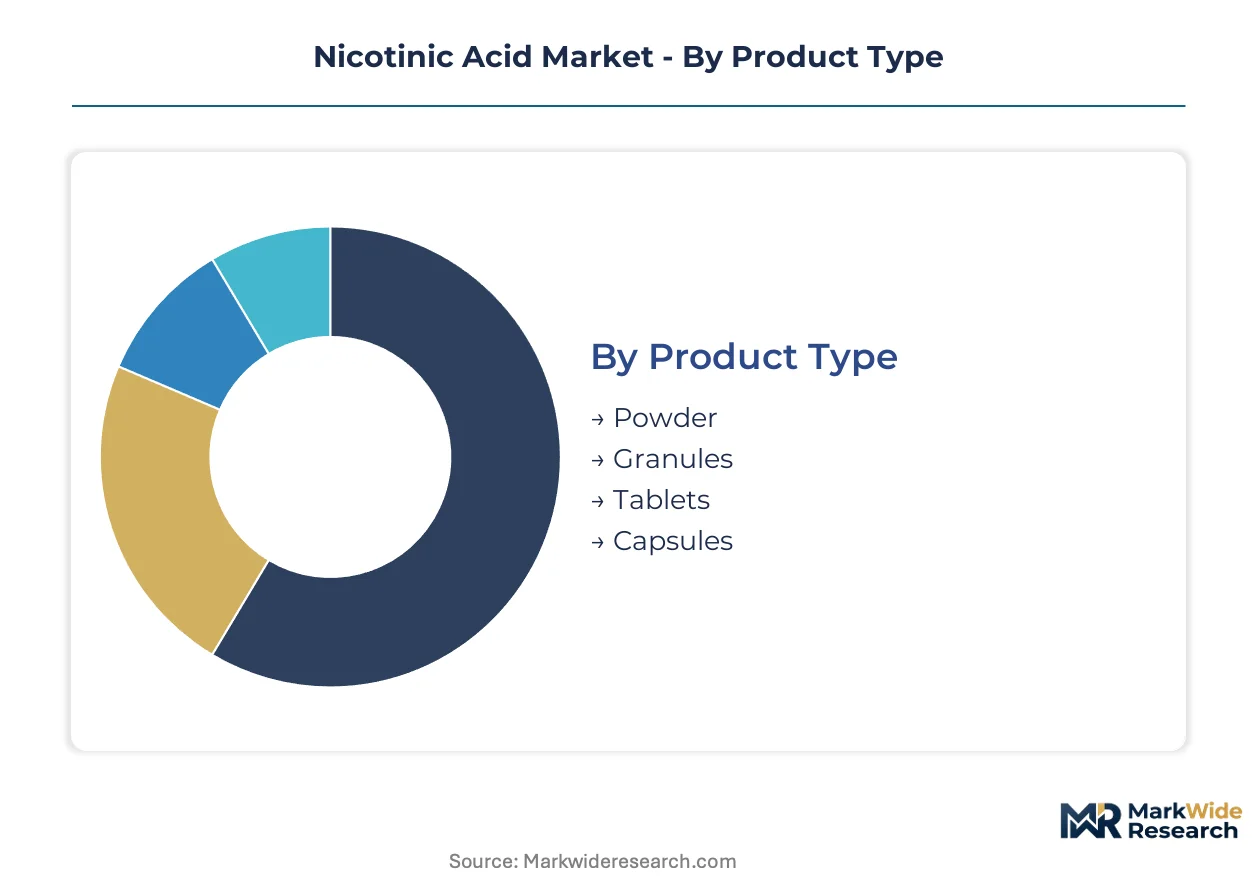
Segmentation in nicotinic acid markets separates commodity-grade material from certified pharmaceutical supply chains. Procurement specifications diverge sharply between food fortification programs and extended-release cardiovascular therapies.
Product Type:
After-sales service intensity concentrates in powder and granule supply contracts, where technical support for compaction behavior and dissolution profile troubleshooting determines supplier retention.
- Powder:Fine-milled crystalline material dominates bulk pharmaceutical procurement due to lower unit processing costs and easier downstream tableting. Demand concentrates in Shandong and Tianjin production clusters feeding both domestic nutraceutical consumption and Southeast Asian generic drug export contracts, with REACH-compliant documentation requirements filtering out non-certified traders.
- Granules:Agglomerated particles improve flowability for high-speed capsule filling operations and reduce dust exposure during handling. Hospital procurement consortia in Germany and France favor granule supply for centralized compounding pharmacies, pulling procurement toward fermentation producers with demonstrated pharmacovigilance track records.
- Tablets:Pre-compressed dosage forms bypass downstream manufacturing complexity for direct dispensing.
- Capsules:Gelatin and HPMC shell formulations accommodate acid-sensitive patient populations.
By volume, Powder leads. By growth pace, Granules is ahead.
Application:
Application segmentation tracks divergent purity mandates between nutritional and therapeutic classifications.
- Pharmaceuticals:USP-grade material for dyslipidemia management requires dissolution profile validation and impurity testing against FDA monograph standards. Extended-release oral forms command premium positioning as cardiovascular protocols favor controlled niacin delivery to minimize flushing side effects, concentrating procurement toward Swiss and Irish contract manufacturers with isolator-based dispensing suites.
- Nutraceuticals:Direct-to-consumer supplement brands seek USP-grade material bypassing traditional pharmaceutical distributor markups, enabling margin capture for certified producers. Volume expansion outpaces mature food-fortification contracts as digital-native brands scale subscription-based vitamin offerings.
- Dietary Supplements:Sports nutrition and wellness positioning drives capsule and tablet demand.
- Food Industry:Mandatory flour and grain fortification programs specify acid-form or amide-form vitamin B3 based on national nutrition policies.
Pharmaceuticals captures the highest purity premiums. Nutraceuticals expands most quickly.
Form:
Form differentiation aligns with pharmacokinetic requirements and side-effect mitigation strategies.
- Immediate Release:Rapid dissolution profiles suit acute deficiency correction and cost-sensitive food fortification. Niacinamide substitution increasingly displaces acid-form material where functionality is non-critical, compressing volume in mature grain programs.
- Extended Release:Polymer-matrix formulations enable controlled niacin delivery over 8-12 hours, minimizing prostaglandin-mediated flushing that limits patient adherence. Cardiovascular therapy protocols in hospital systems favor these systems, pulling pharmaceutical-grade powder procurement toward specialized compaction-ready grades.
- Oral:Tablets and capsules dominate outpatient dispensing convenience.
- Injectable:Parenteral formulations serve critical care settings with malabsorption conditions.
Oral forms dominate prescription volume. Extended Release gains share fastest.
End User:
End-user concentration reflects procurement centralization trends and regulatory inspection intensity.
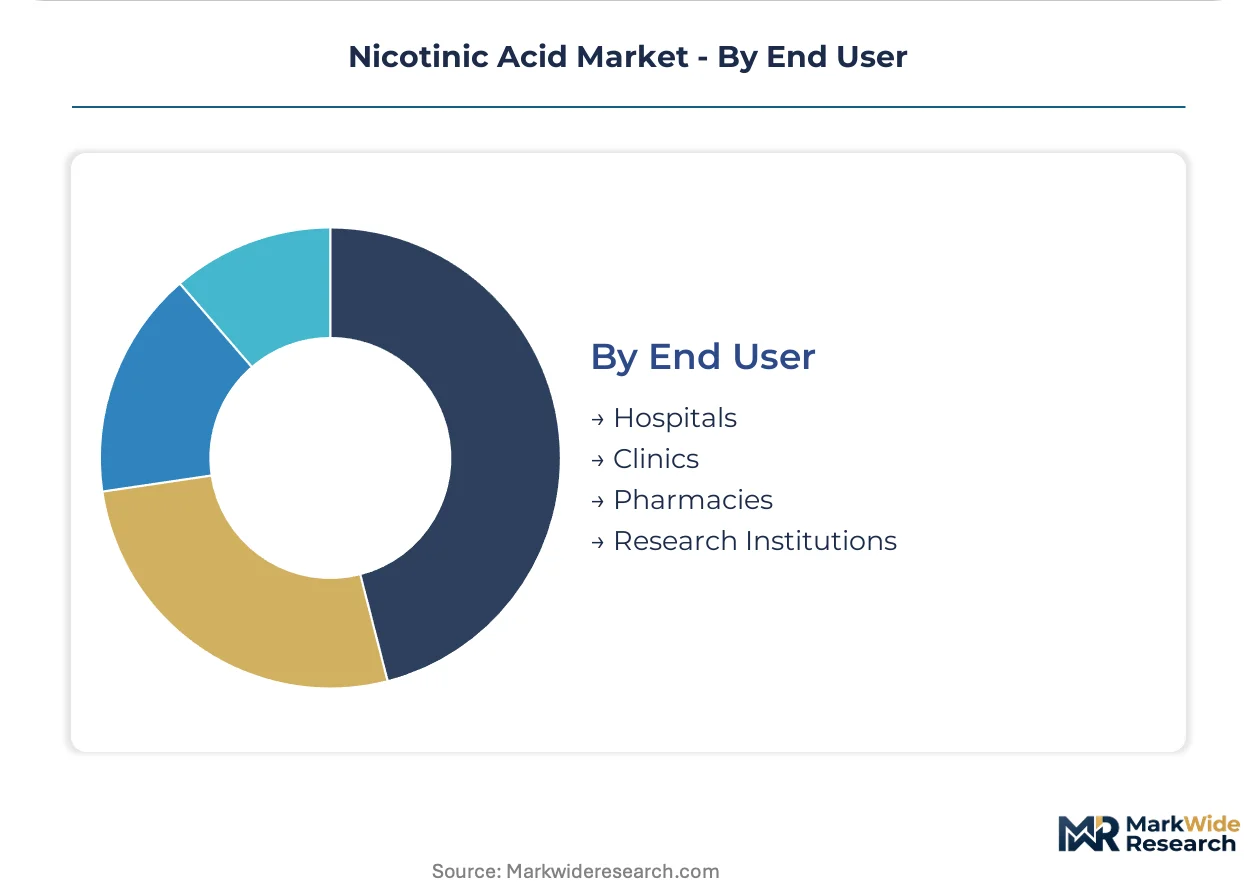
- Hospitals:Group purchasing organizations consolidate annual niacin contracts into multi-year framework agreements with inflation-linked price adjustment mechanisms, displacing spot-market purchases with committed volume tiers. EMA Annex 1 sterile manufacturing guidance extends environmental monitoring requirements to high-potency lipid-modifying API handling.
- Clinics:Outpatient cardiovascular practices prescribe extended-release formulations for long-term dyslipidemia management, with prescription patterns tracked through national health data systems in France and Germany.
- Pharmacies:Retail dispensing captures both prescription niacin and over-the-counter supplement sales.
- Research Institutions:Clinical trial material supply requires batch-specific documentation and stability data.
Hospitals lead procurement scale. Clinics show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in nicotinic acid track divergent regulatory maturity across production clusters. China maintains net export dominance while European and North American markets absorb pharmaceutical-grade imports under tightening purity mandates.
China
Shandong and Tianjin fermentation facilities supply both domestic nutraceutical consumption and Southeast Asian generic drug contracts. NMPA and SAMR jointly oversee pharmaceutical-grade niacin registration, creating bifurcated compliance pathways between nutritional and drug-classified supply chains. The Shandong-Tianjin production cluster anchors Asia-Pacific API export volume.
United States
FDA enforces USP monograph standards for purity and dissolution profiles, compressing supplier margins toward fermentation-based producers. Hospital procurement consortia consolidate annual contracts into multi-year framework agreements with inflation-linked adjustments. Swiss and Irish contract manufacturers capture premium-tier supply through isolator-based dispensing suites.
Germany
EMA and ECHA apply REACH chemical safety protocols to imported bulk material, filtering out low-purity traders. Group purchasing organizations displace spot-market purchases with committed volume tiers. Bavaria and North Rhine-Westphalia house specialized compaction-ready grade processors serving cardiovascular therapy protocols.
India
CDSCO registration requirements and PLI scheme incentives reduce capital recovery timelines for fermentation facility investments. Jubilant Life Sciences anchors cost positions through backward integration into pyridine chemistry. Maharashtra and Gujarat clusters feed both domestic formulation demand and export API contracts to regulated markets.
Switzerland
Swissmedic oversees pharmaceutical-grade material with environmental monitoring requirements extending to high-potency lipid-modifying API handling. Basel-area bioprocess engineering talent concentrates in limited high-purity bioreactor operations. Lonza Group AG leverages Swiss fermentation infrastructure to sustain premium positioning.
Nicotinic Acid Market Competitive Landscape
On the supply side, the industry is consolidating toward fermentation-based producers with captive pyridine supply and documented pharmacovigilance track records. Three strategic archetypes dominate: Swiss and German pharmaceutical-grade specialists, Indian cost-optimized contract manufacturers, and Chinese scale-driven fermentation exporters. Competitive moves center on capacity expansion in isolator-based dispensing suites and strategic partnerships for just-in-time oral solid dosage contracts.
Within the pharmaceutical-grade tier, Lonza Group AG exemplifies Swiss fermentation infrastructure positioning, while Jubilant Life Sciences occupies the Indian backward-integrated archetype. Vertellus Specialties represents North American specialty-grade material control for niche pharmaceutical applications.
| Leading Market Players |
|---|
| Lonza Group AG |
| Jubilant Life Sciences Limited |
| Vertellus Specialties Inc. |
| DSM Nutritional Products |
| Shandong Hongda Biotechnology Co., Ltd. |
| BASF SE |
| Glanbia plc |
| Resonance Specialties Limited |
| Tianjin Zhongrui Pharmaceutical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Shandong and Tianjin fermentation capacity concentration positions Chinese producers to capture margin pools in pharmaceutical-grade API contracts, while downstream formulators in Germany and Switzerland absorb purity-premium markups under tightening EMA documentation requirements.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical-grade material commanding substantial premiums over food-fortification grades due to USP monograph compliance costs. Price differentiation hinges on certification tier and volume scale, with extended-release formulation buyers showing least price sensitivity. Cost compression in standard-grade supply is intensifying because niacinamide substitution displaces acid-form volume in mature grain programs.
Supply Chain Analysis
Extended payment terms from European hospital procurement consortia are forcing working capital discipline onto fermentation producers with limited high-purity bioreactor slots. Supply concentrates in China, India, and Switzerland, with 3-picoline feedstock, pyridine derivatives, and specialized bioprocess equipment anchoring upstream dependencies. Single-source fermentation capacity creates allocation risk for Q4 API procurement cycles. Distribution runs through pharmaceutical distributor networks for regulated markets and direct-to-consumer channels for nutraceutical brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers, as EMA and FDA purity mandates force multi-year qualification timelines that lock in incumbent supplier relationships.
For Market Incumbents: Entrench market position by retrofitting isolator-based dispensing suites ahead of EMA Annex 1 inspection cycles, and deepen backward integration into pyridine chemistry to insulate margins from 3-picoline feedstock volatility. The threat of niacinamide substitution in food-grade applications demands channel control toward higher-margin pharmaceutical contracts.
For New Entrants and Emerging Players: Build out direct-to-consumer nutraceutical supply capabilities, as this segment shows fastest volume expansion and lowest regulatory entry barriers compared to pharmaceutical-grade certification. White-space concentrates in USP-grade material for digital-native supplement brands seeking subscription-based vitamin offerings, with a go-to-market angle emphasizing bypass of traditional pharmaceutical distributor markups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian contract manufacturers holding PLI scheme alignment and fermentation facility investments. Long-term viability favors producers with demonstrated pharmacovigilance track records and captive pyridine supply. The signal to watch is hospital procurement consortia consolidation into multi-year framework agreements, which would accelerate supplier tier concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Dispensing Suite Retrofit | EMA Annex 1 compliance qualifies suppliers for high-potency lipid-modifying API contracts in German hospital systems. |
| Backward Integration into Pyridine Chemistry | Jubilant Life Sciences anchors cost positions through in-house production of 3-picoline feedstock derivatives. |
| Direct-to-Consumer Channel Expansion | USP-grade material sales to supplement brands bypass traditional pharmaceutical distributor markups and capture margin. |
| Continuous Manufacturing Technology Adoption | Flow chemistry with real-time release testing qualifies suppliers for just-in-time oral solid dosage contracts. |
| Multi-Year Framework Agreement Negotiation | Group purchasing organizations in France and Germany displace spot-market purchases with committed volume tiers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, customs trade data, and pharmaceutical procurement databases. Interviews with fermentation plant managers, API procurement leads at generic drug manufacturers, regulatory affairs directors, and hospital GPO contracts managers informed supply-side capacity and demand-side qualification requirements. Bottom-up volume modeling triangulates against top-down market sizing from trade flow analysis.
Forecast inputs span pharmaceutical-grade versus food-grade tier splits, powder versus granule versus extended-release form factors, and regional regulatory cluster adoption patterns. Segmentation dimensions include application classification, end-user concentration, and purity certification level. CAGRs derive from trend extrapolation of procurement pattern shifts and capacity expansion announcements across the analysis window. Industry-specific inputs incorporate REACH registration timelines and PLI scheme incentive trajectories.
Sensitivities concentrate around pharmacopeial harmonization gaps between USP, EP, and ChP standards, 3-picoline derivative pricing volatility, and niacinamide substitution rates in food fortification. Forecasts reflect assumptions on regulatory inspection intensity and fermentation capacity utilization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Botanical CO2 Extracts Market
Extracts
Turpentine Market
Extracts
Yucca Extract Material Market
Extracts
Bidens Pilosa Extract Market
Extracts
Cassia Extract Market
Extracts
Essential Oil Isolates Market
Extracts
Aloe Vera Derivatives Market
Extracts
Algae Extracts Market
Extracts
Botanicals Market
Extracts
Global Herbal Extract Market
Extracts
Lavender Oil Market
Extracts
China Cedar Wood Oil Market
Extracts
Sandalwood Oil Market
Extracts
Helichrysum Oil Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Global Marigold Flower Extract Market