
 Botanical CO2 Extracts Market | 2026-2036
Botanical CO2 Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical CO2 Extracts Market Analysis
Organic and pharmacopeia-grade certification tiers is unwinding conventional commodity positioning across the Botanical CO2 Extracts Market. FLAVEX Naturextrakte GmbH leverages its German toll-manufacturing infrastructure to serve premium fragrance houses with certified organic outputs. Givaudan anchors global flavor procurement through captive supercritical CO2 capacity in multiple European sites. Synthite Industries Ltd dominates spice-derived extract supply from its Kerala processing base, competing on volume scale for oleoresin and essential oil fractions.
Botanical CO2 extracts are concentrated plant-derived preparations obtained using carbon dioxide in supercritical or subcritical states, typically yielding terpene-rich fractions with residual solvent levels below pharmaceutical-grade thresholds of 50 ppm. Supercritical CO2 extraction operates at temperatures above 31°C and pressures exceeding 74 bar, preserving heat-sensitive volatile compounds for applications in high-end cosmetics, natural flavor modulation, and therapeutic aromatherapy formulations. Essential oils and flavor extracts represent the deepest margin pools, with supercritical methods commanding price premiums over subcritical and cold-press alternatives due to cleaner spectral profiles and extended shelf stability. Pharmaceutical-grade packaging in amber glass bottles sustains oxidation-sensitive terpenoid integrity, while bulk drum formats serve food and beverage compounders with shorter formulation cycles and lower per-unit extraction costs.
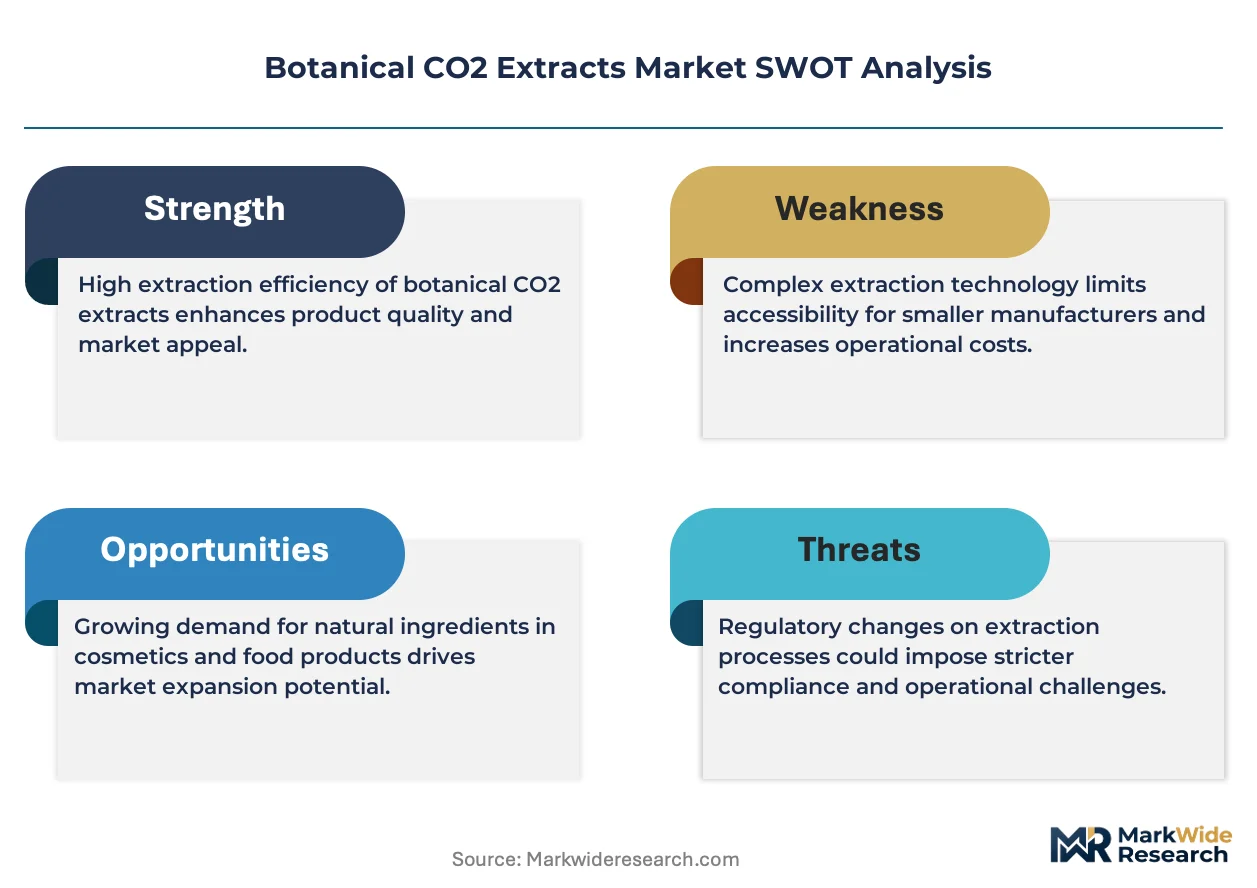
EMA pharmacopeial monographs and REACH registration requirements in Europe impose strict residual solvent and heavy-metal thresholds that filter out conventional hexane extractors from premium supply chains. FDA GRAS self-affirmation pathways and USDA organic certification in the United States create parallel compliance ladders that segment market access by end-use application. Stakeholders must monitor evolving EPA solvent-discharge rules and EU F-Gas Regulation impacts on CO2 supply chain costs, as regulatory divergence between jurisdictions reshapes competitive positioning for cross-border extract suppliers.
Market Dynamics
REACH solvent limits and EU Green Deal carbon-accounting rules are compressing conventional hexane extraction capacity while concentrating premium supply chains around German toll-processors with certified organic outputs.
Growth Catalysts
- Clean-label cosmetics procurement:Fragrance houses in France and Italy are mandating CO2-extracted terpenes for fine fragrance formulations, displacing petrochemical synthetics in prestige product lines.
- REACH residual solvent thresholds:ECHA enforcement of sub-50 ppm limits is disqualifying conventional solvent extractors from EU pharmaceutical and food-grade supply chains.
- Supercritical CO2 equipment scale-up:Modular extraction skids with automated pressure-temperature profiling are reducing batch-to-batch variability for mid-volume botanical processors.
Market Restraints
- CO2 supply chain cost volatility:EU F-Gas Regulation restrictions on industrial CO2 sourcing are elevating feedstock costs for extractors dependent on beverage-industry byproduct streams.
- Equipment capex intensity:High-pressure vessel fabrication and ASME certification requirements limit entry for processors below 500-liter extraction capacity.
- Substitution by cold-press and molecular distillation:Citrus and seed oil processors in Spain and California are bypassing CO2 methods where heat-sensitive compound preservation is less critical.
Strategic Opportunities
- USDA organic certification arbitrage:Indian and Sri Lankan spice processors are capturing premium export margins by qualifying CO2 oleoresins for US organic labeling.
- Therapeutic aromatherapy channel expansion:Direct-to-practitioner distribution is bypassing conventional flavor-house intermediaries for small-batch chamomile and frankincense extracts.
- Pharmacopeia-grade standardization:EMA monograph alignment for cannabis-derived CO2 extracts is opening prescription-access pathways in Germany and Australia.
Industry Challenges
- Supercritical fluid engineering talent scarcity:PhD-level expertise in thermodynamic modeling and phase-behavior optimization commands premium compensation in Bavaria and Baden-Württemberg processing clusters.
- Multi-certification timeline compression:Simultaneous pursuit of organic, kosher, halal, and pharmaceutical-grade audits extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical CO2 Extracts Market |
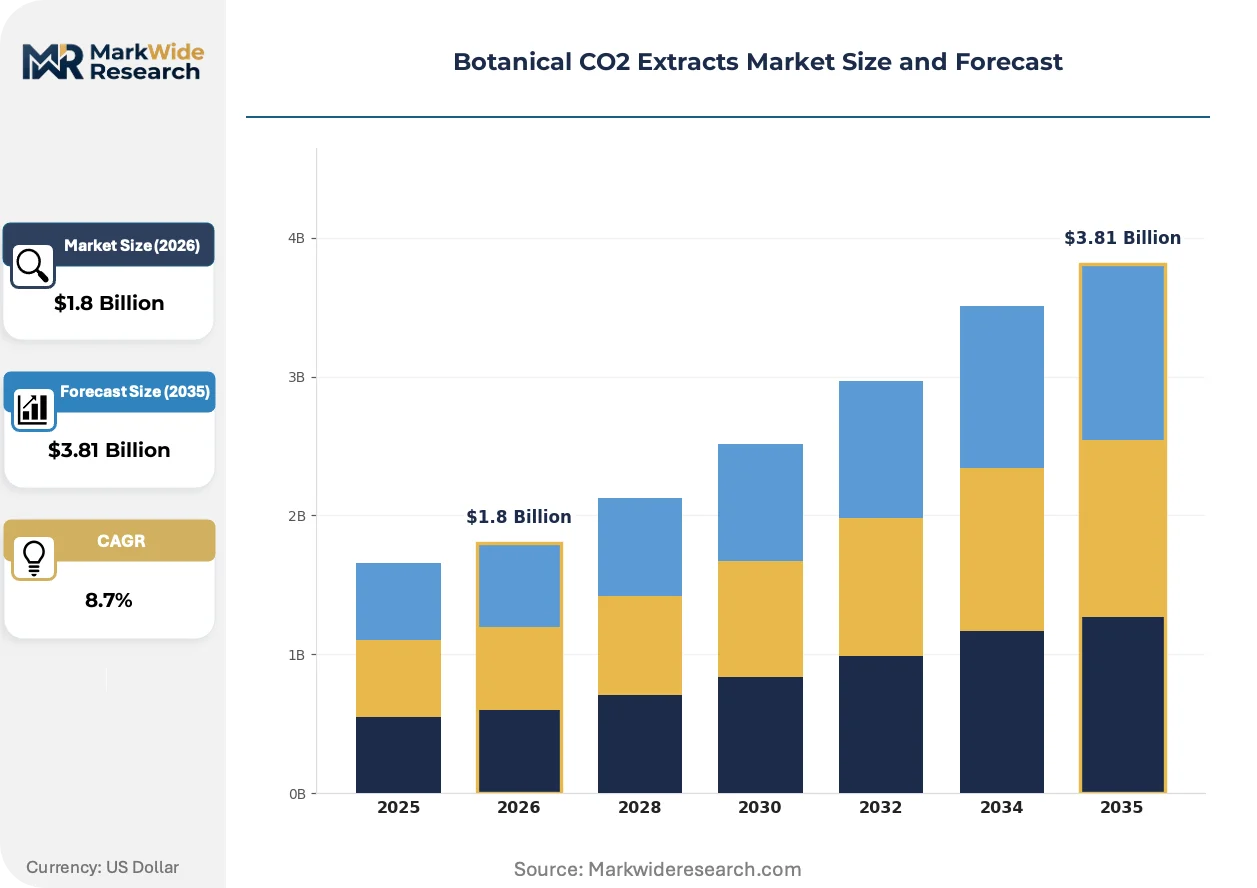
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Supercritical CO2, Subcritical CO2, Cold Press, Hydrodistillation End User: Cosmetics, Food & Beverage, Pharmaceutical, Aromatherapy Packaging Type: Glass Bottles, Bulk Drums, Plastic Containers, Sachets Product Type: Essential Oils, Flavor Extracts, Fragrance Oils, Others |
| Companies Covered | FLAVEX Naturextrakte GmbH, Givaudan, Blue Sky Botanics, Eden Botanicals, Synthite Industries Ltd, Kancor Ingredients Limited, VidyaHerbs, Naturex, Arjuna Natural Extracts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical CO2 Extracts Market Emerging Trajectories
Fractionation technology advances and regulatory chemistry disclosure mandates are rewriting extraction economics while fragmenting buyer procurement patterns across end-use verticals.
Subcritical CO2 fractionation with inline terpene recovery is decomposing the traditional essential oil distillation value chain. German fragrance compounders are retrofitting existing supercritical lines with split-stream separators to isolate sesquiterpene fractions for niche perfume applications. This capability compression is collapsing the historical premium commanded by steam-distilled absolutes in high-end formulations.
EU F-Gas Regulation phase-down schedules are forcing CO2 extractors to secure dedicated biogenic or captured industrial CO2 supply contracts rather than spot-market beverage-industry offtake. ECHA registration dossiers now require full supply-chain carbon-footprint disclosure for REACH-registered substances. Premium cosmetic brands in France are responding by specifying renewable-source CO2 in raw-material procurement specifications.
Certification-driven supplier consolidation is restructuring procurement relationships in natural flavor procurement. Mid-sized food manufacturers are bypassing traditional oleoresin distributors to contract directly with Kerala-based processors holding dual USDA organic and FSSC 22000 certification. This disintermediation is most pronounced in North American savory flavor applications where clean-label claims require documented extraction method transparency.
Botanical CO2 Extracts Market Segmentation
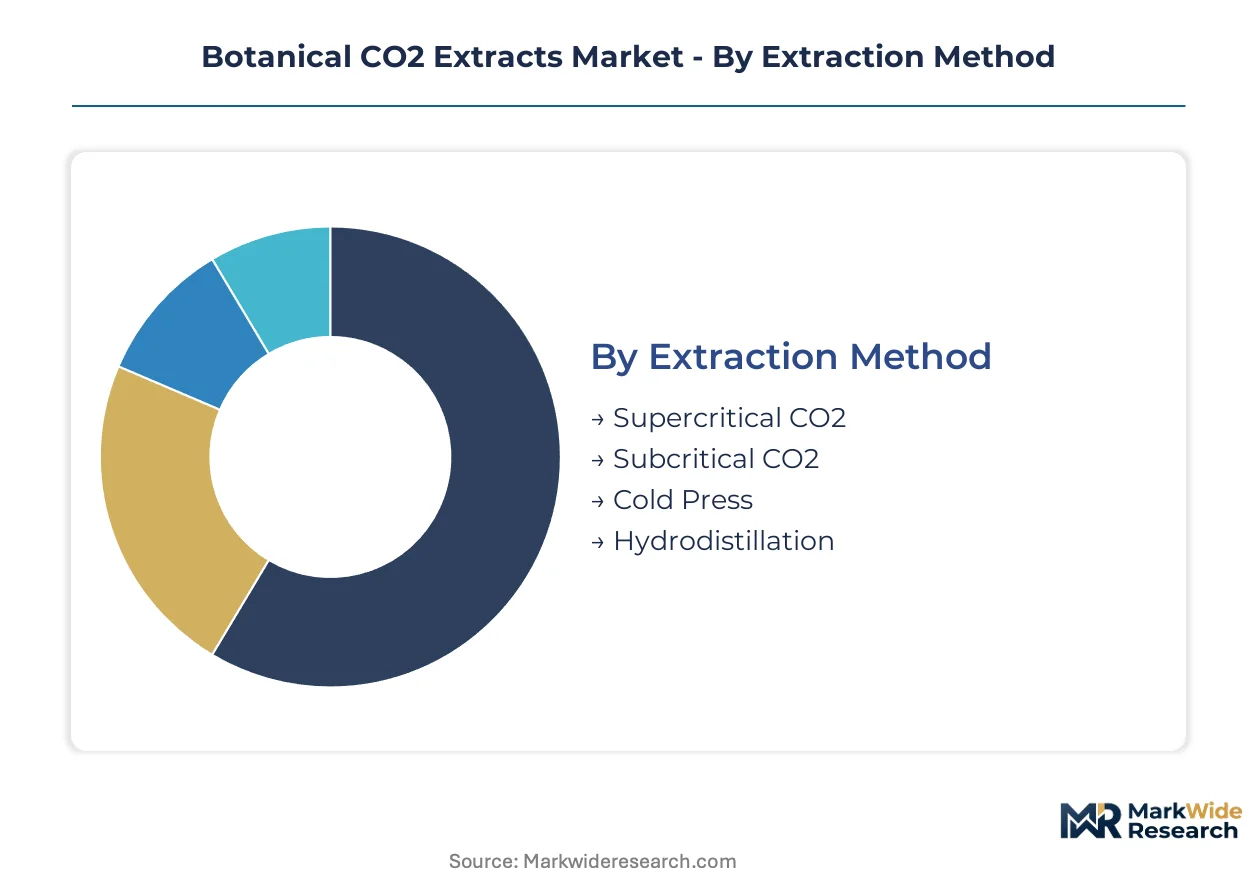
Channel economics in the Botanical CO2 Extracts Market diverge sharply by segment. Supercritical methods command premium shelf positioning in cosmetics, while bulk drum formats serve high-volume food compounders with compressed margins.
Extraction Method:
Supercritical CO2 dominates prestige cosmetics channels, whereas subcritical variants and legacy methods compete on cost in industrial flavor procurement.
- Supercritical CO2:Operates above 31°C and 74 bar, preserving heat-sensitive terpenes with residual solvents below 50 ppm. French fragrance houses mandate this method for fine perfume formulations, paying premiums over conventional extraction.
- Subcritical CO2:Runs at lower temperatures and pressures, reducing energy costs while sacrificing some volatile compound recovery. German toll-processors deploy this for mid-tier cosmetic ingredient batches where spectral purity requirements relax.
- Cold Press:Mechanical crushing without solvent contact serves Spanish citrus processors seeking rapid throughput for seed oils with lower terpene sensitivity.
- Hydrodistillation:Steam-based separation persists in traditional aromatherapy supply chains, though ECHA residual solvent thresholds are compressing its pharmaceutical applicability.
By volume, hydrodistillation still leads. By growth pace, supercritical CO2 is climbing the fastest as REACH enforcement tightens.
End User:
Margin structures vary threefold across end-use verticals, with cosmetics and pharmaceuticals capturing value that food manufacturers compress through scale procurement.
- Cosmetics:Clean-label formulations in prestige skincare and fine fragrance drive the steepest price premiums. Italian and French beauty houses specify CO2-extracted terpenes to displace petrochemical synthetics.
- Food & Beverage:Savory flavor compounders in North America source organic-certified oleoresins directly from Kerala processors, bypassing traditional distributors to secure extraction method transparency.
- Pharmaceutical:EMA pharmacopeial monographs and sub-50 ppm residual solvent limits filter out conventional extractors from prescription-access pathways in Germany and Australia.
- Aromatherapy:Direct-to-practitioner distribution channels are opening for small-batch chamomile and frankincense extracts, circumventing flavor-house intermediaries.
Food & Beverage generates the highest absolute volume. Cosmetics delivers the strongest margin expansion trajectory.
Packaging Type:
Packaging selection tracks oxidation sensitivity and batch size, with amber glass commanding 4-6x unit premiums over bulk formats.
- Glass Bottles:Amber pharmaceutical-grade bottles preserve terpenoid integrity for high-value essential oils and therapeutic formulations with extended shelf requirements.
- Bulk Drums:Stainless steel or coated steel formats serve food and beverage compounders with shorter formulation cycles and lower per-unit extraction costs.
- Plastic Containers:HDPE and PET variants penetrate mid-market cosmetic ingredient distribution where oxygen barrier requirements moderate.
- Sachets:Single-use foil laminates support sample distribution and travel-size aromatherapy retail, though terpene permeation limits shelf life.
Bulk drums dominate tonnage. Glass bottles are expanding most quickly as cosmetic brands emphasize oxidation-sensitive ingredient integrity.
Product Type:
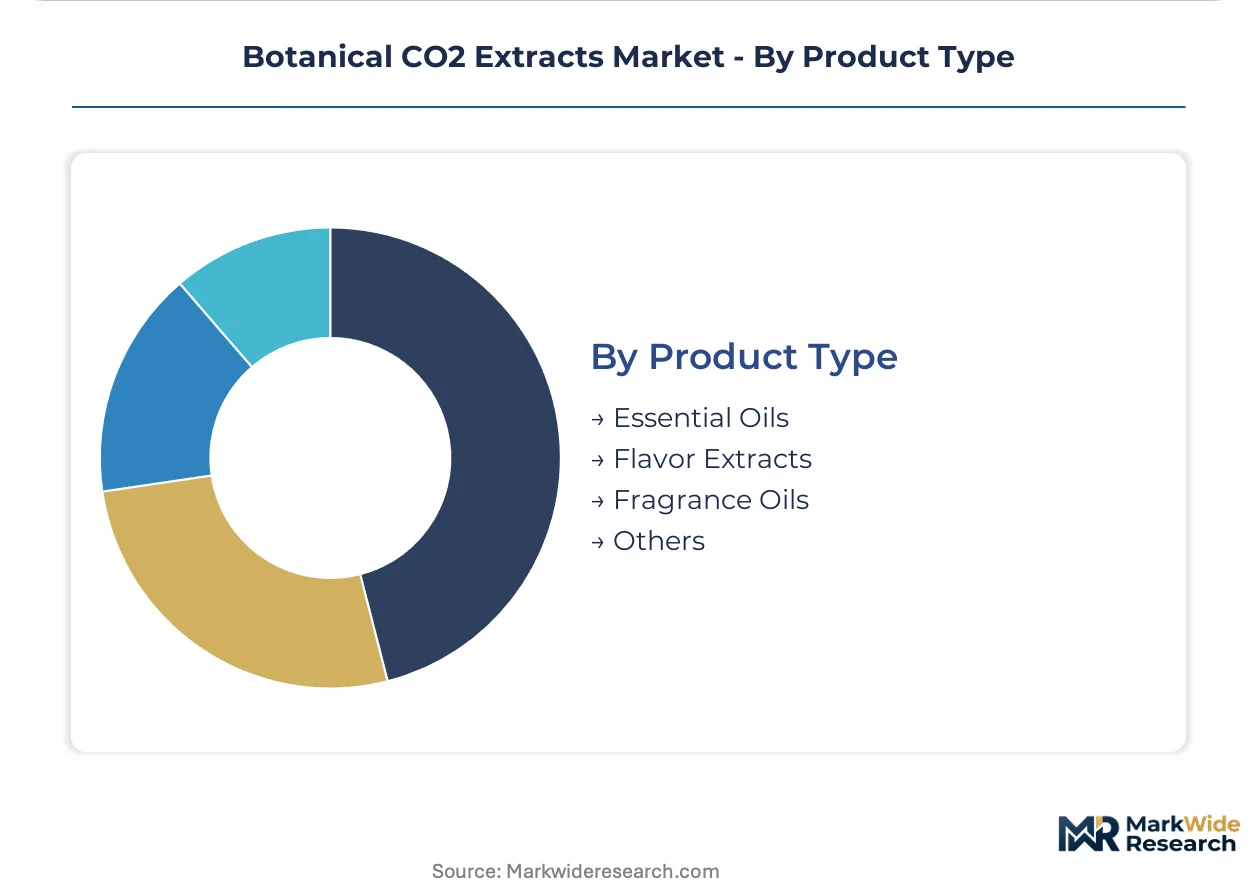
Product-tier pricing stratifies by compound complexity and regulatory burden, with essential oils and flavor extracts capturing the deepest margin pools.
- Essential Oils:Terpene-rich fractions from supercritical CO2 extraction command price premiums over cold-press alternatives due to cleaner spectral profiles. German fragrance compounders retrofit lines with split-stream separators to isolate sesquiterpene fractions for niche perfume applications.
- Flavor Extracts:Oleoresin and essential oil fractions from spice-derived feedstocks compete on volume scale from Kerala processing bases. USDA organic certification arbitrage allows Indian and Sri Lankan processors to capture premium export margins.
- Fragrance Oils:Synthetic-natural hybrid formulations serve mass-market personal care, though clean-label displacement is compressing this segment's growth.
- Others:Residual categories include color extracts and nutraceutical precursors with emerging pharmacopeia-grade standardization requirements.
Flavor extracts lead by volume throughput. Essential oils are gaining share fastest as supercritical methods displace conventional absolutes in high-end formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in certified organic CO2 extracts, importing raw botanicals from India and Sri Lanka while exporting finished pharmacopeia-grade fractions to France and Italy. The United States and China balance substantial domestic processing capacity against growing imports of spice-derived oleoresins. Australia and Japan represent net import markets where therapeutic-grade demand outstrips local supercritical extraction infrastructure.
Germany
REACH enforcement and EMA pharmacopeial standards filter out conventional hexane extractors from pharmaceutical supply chains. The EU F-Gas Regulation tightens industrial CO2 sourcing, elevating feedstock costs for processors dependent on beverage-industry byproduct streams. Bavaria and Baden-Württemberg host concentrated toll-processing capacity serving French fragrance houses and Italian cosmetic compounders with certified organic outputs.
United States
FDA GRAS self-affirmation pathways and USDA organic certification create parallel compliance ladders segmenting market access by end-use application. EPA solvent-discharge rules reshape competitive positioning for cross-border extract suppliers. California citrus processors bypass CO2 methods where heat-sensitive compound preservation is less critical, while Pacific Northwest aromatherapy distributors expand direct-to-practitioner channels for small-batch extracts.
India
Spice-derived oleoresin exports from Kerala capture premium margins through USDA organic certification arbitrage. FSSAI food safety standards and DGFT export promotion schemes support processor scaling for North American savory flavor applications. Synthite Industries Ltd anchors volume-scale supply from its Kerala processing base, competing on extraction throughput for essential oil fractions.
China
NMPA pharmaceutical-grade registration requirements and SAMR food safety standards impose dual compliance burdens on domestic extractors. MIIT industrial policy supports supercritical equipment manufacturing for mid-volume botanical processors. Yangtze River Delta cosmetic ingredient compounders specify CO2-extracted terpenes to displace petrochemical synthetics in prestige skincare formulations.
France
ANSM cosmetic ingredient disclosure mandates and CNIL data governance requirements add regulatory layers to supply chain documentation. Fine fragrance houses in Grasse mandate CO2-extracted sesquiterpenes for niche perfume applications, paying premiums over conventional absolutes. Île-de-France beauty brands specify renewable-source CO2 in raw-material procurement specifications, responding to ECHA carbon-footprint disclosure requirements.
Botanical CO2 Extracts Market Vendor Landscape
Concentration sits with German toll-manufacturing specialists and Indian spice-derived volume processors, while mid-tier cosmetic ingredient suppliers fragment across regional clusters. Three archetypes dominate: certified organic toll-processors serving premium fragrance houses, scale-driven oleoresin exporters from South Asian spice belts, and integrated flavor houses with captive supercritical capacity. Competitive moves center on pharmacopeia-grade certification acquisition and direct procurement relationships bypassing traditional distributors.
Within the German toll-manufacturing tier, FLAVEX Naturextrakte GmbH exemplifies the certified organic specialist archetype serving premium fragrance compounders. Givaudan occupies a position among integrated flavor houses with captive supercritical CO2 infrastructure across multiple European sites. Synthite Industries Ltd represents the scale-driven South Asian processor competing on volume throughput from its Kerala extraction base.
| Leading Market Players |
|---|
| FLAVEX Naturextrakte GmbH |
| Givaudan |
| Blue Sky Botanics |
| Eden Botanicals |
| Synthite Industries Ltd |
| Kancor Ingredients Limited |
| VidyaHerbs |
| Naturex |
| Arjuna Natural Extracts |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for pharmacopeia-grade amber glass packaging concentrate pricing power with German toll-processors serving French fragrance houses. Inventory buffers at Kerala spice processing bases compress margins for bulk oleoresin exports while amplifying premiums for certified organic outputs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Botanical CO2 Extracts Market. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with USDA organic and REACH-registered tiers commanding substantial premiums over conventional hexane-extracted alternatives. Cost compression in mid-tier cosmetic ingredient batches is intensifying because German toll-processors retrofit subcritical lines to compete with supercritical purity claims. Food and beverage compounders sourcing bulk drum formats exhibit highest price sensitivity, while prestige skincare houses specifying amber glass packaging demonstrate minimal elasticity.
Supply Chain Analysis
Ninety-day inventory cycles for biogenic CO2 feedstock expose extractors to EU F-Gas Regulation supply disruptions. Manufacturing gravity centers on Germany, India, and China, with Bavarian toll-processors importing raw botanicals from Kerala spice belts and Sri Lankan organic estates. Supercritical CO2 extraction equipment draws from specialized ASME-certified vessel fabricators in Baden-Württemberg and Yangtze River Delta clusters. Single-source vulnerability concentrates in beverage-industry CO2 byproduct streams now restricted under EU phase-down schedules. Distribution runs through direct procurement relationships where mid-sized North American manufacturers bypass traditional oleoresin distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Botanical CO2 Extracts Market functions as a service-attach opportunity where certification audit services and pharmacopeia-grade compliance consulting expand faster than extraction hardware sales.
For Market Incumbents: Secure backward integration into biogenic CO2 sourcing to insulate against EU F-Gas Regulation feedstock disruptions. Expand ASME-certified vessel capacity in Baden-Württemberg to capture toll-processing demand from Italian cosmetic compounders facing REACH residual solvent enforcement. Certification investment in dual USDA organic and EMA pharmacopeia tiers defends margin position against Kerala-based volume competitors. For New Entrants and Emerging Players: USDA organic certification fast-track programs in Sri Lankan spice processing zones unlock white-space capture in North American savory flavor procurement. Therapeutic aromatherapy direct-to-practitioner channels in Australia offer penetrable entry with minimal incumbent saturation. Go-to-market execution should emphasize split-stream terpene fractionation capabilities for niche perfume applications. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between FDA GRAS self-affirmation and EMA pharmacopeial monographs creates persistent margin premiums for dual-certified processors. Acquisition targets should display captive supercritical capacity with existing REACH registration dossiers. Monitor EU F-Gas Regulation biogenic CO2 supply contract announcements as inflection indicator for feedstock cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeia-Grade Certification Investment | EMA monograph alignment opens prescription-access pathways in Germany and Australia. |
| Backward Integration into Biogenic CO2 Sourcing | Dedicated supply contracts insulate Bavarian processors from EU F-Gas Regulation cost spikes. |
| Direct-to-Practitioner Channel Expansion | Aromatherapy distribution bypasses flavor-house intermediaries for chamomile and frankincense extracts. |
| Split-Stream Fractionation Retrofit | German fragrance compounders isolate sesquiterpene fractions for niche perfume premiums. |
| USDA Organic Certification Arbitrage | Kerala and Sri Lankan processors capture export margins in North American clean-label procurement. |
Methodological Framework
A standing panel of supercritical equipment engineers, fragrance house procurement directors, Kerala spice processing plant managers, and EMA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA registration dossiers, EU F-Gas Regulation implementation reports, USDA organic certification databases, and customs trade records for oleoresin exports. Bottom-up capacity modeling at named processing facilities triangulated against top-down demand segmentation by end-use vertical.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled extraction method, end-use application, packaging format, and certification tier dimensions. CAGRs were derived from segment-level growth rate synthesis. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and REACH residual solvent enforcement timelines.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or biogenic CO2 supply contract availability would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and equipment scale-up rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Kelp Extracts Market
Extracts
Pectin Powder Market
Extracts
Lemongrass Oil Market
Extracts
Myrrh Powder Market
Extracts
Aloe Vera Extract Market
Extracts
Cochineal Extract Market
Extracts
Helichrysum Oil Market
Extracts
White Willow Bark Extract Market
Extracts
Yucca Extract Material Market
Extracts
Tagetes Oil Market
Extracts
Black Fungus Extract Market
Extracts
Clary Sage Oil Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Nigella Sativa Extract Market
Extracts
Antioxidants Reagent Market
Extracts
Cornflower Extract Market