
 Milk Powder Packaging Market | 2026-2036
Milk Powder Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Powder Packaging Market Foresight
Aftermarket service revenue from filling-line integration and technical support contracts is tilting toward packaging equipment suppliers as dairy processors outsource capital-intensive retrofits. Tetra Pak International SA leverages its aseptic system installed base to lock in long-term service agreements across emerging markets. Ball Corporation anchors North American metal can demand through backward integration into aluminum supply and beverage-can scale economies repurposed for nutritional powders. Mondi PLC differentiates via kraft-paper barrier innovations that target plastic-reduction mandates without sacrificing shelf life.
Milk powder packaging encompasses engineered containment systems designed to exclude moisture, oxygen, and light from dehydrated dairy products, typically employing multi-layer structures with aluminum oxide or ethylene vinyl alcohol barrier films and nitrogen-flushing protocols to preserve lipid stability and protein solubility over 12–24 month storage cycles. Flexible pouches now command the fastest expansion among packaging types as retail formats shrink toward single-serve and trial-size units in urban convenience channels. Paperboard-composite materials lead value contribution among material segments, reflecting premium positioning in infant formula and organic product lines where print quality and sustainability signaling justify higher unit economics.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications jointly shape material compliance pathways, with the former driving recyclability redesign and the latter governing migration limits for adhesives and coatings in infant-nutrition applications. BIS certification requirements in India add a third compliance layer for exporters targeting that country's growing dairy processing sector. Stakeholders must monitor how diverging extended-producer-responsibility schemes across the European Union, United States, and India reshape total cost of ownership for multi-material laminate structures.
Market Dynamics
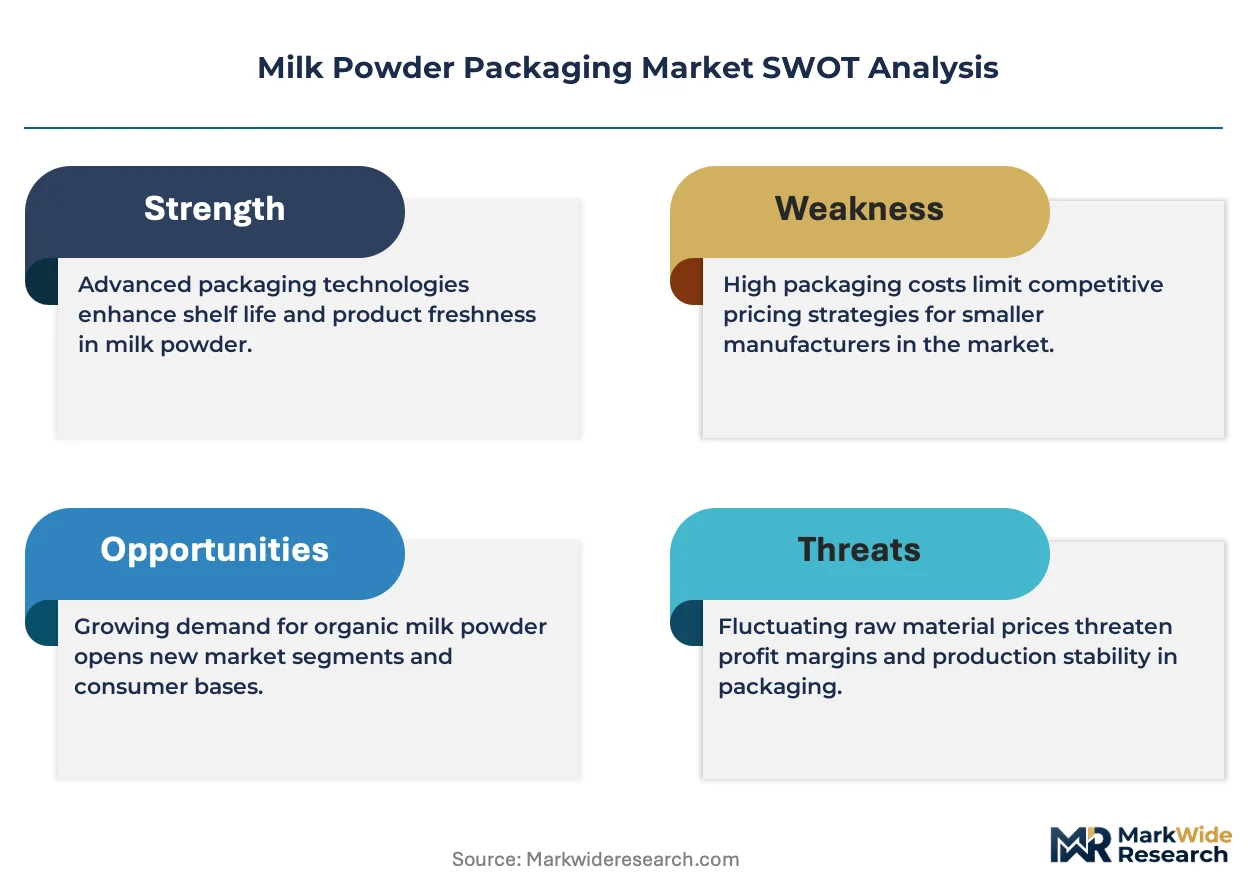
The EU Packaging and Packaging Waste Regulation is compressing design cycles for multi-layer laminates as converters race to meet material recovery targets without compromising barrier performance for lipid-sensitive powders.
Growth Catalysts
- Urban retail modernization in Nigeria:Convenience store expansion in Lagos and Abuja is pulling single-serve flexible pouch formats into formerly bulk-dominated distribution channels.
- REACH-compliant adhesive innovation:Solvent-free laminating technologies are unlocking infant formula export eligibility into European markets previously blocked by migration limit violations.
- Aseptic nitrogen-flushing protocols:Extended shelf-life guarantees are enabling dairy processors to penetrate inland African markets with limited cold chain infrastructure.
Market Restraints
- Aluminum oxide supply concentration:Barrier film substrate availability tightens around Southeast Asian chemical vapor deposition capacity, exposing converters to input volatility.
- Extended producer responsibility cost layering:Germany's VerpackG and France's AGEC laws impose parallel compliance fees on identical laminate structures, inflating total cost of ownership.
- Paperboard moisture sensitivity:Kraft-paper composite formats face technical ceilings in tropical humidity zones, restricting premium positioning in equatorial African markets.
Strategic Opportunities
- Ethiopian dairy processing expansion:State-led industrial park development around Addis Ababa is creating first-mover advantage for packaging equipment-integrated service providers.
- India PLI scheme for food processing:Capital subsidy windows are lowering entry barriers for converters establishing domestic laminate production to serve BIS-certified infant nutrition brands.
- Digital printing convergence with barrier substrates:Variable-data-enabled pouch production is virtualizing SKU proliferation economics for regional dairy brands testing flavor variants.
Industry Challenges
- Migration testing timeline compression:FDA food-contact substance notification cycles now exceed 18 months for novel adhesive chemistries, delaying product launches.
- Legacy filling line incompatibility:Retrofitting nitrogen-flush stations into existing vertical form-fill-seal equipment demands mechanical engineering talent scarce in Vietnam's packaging corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Powder Packaging Market |
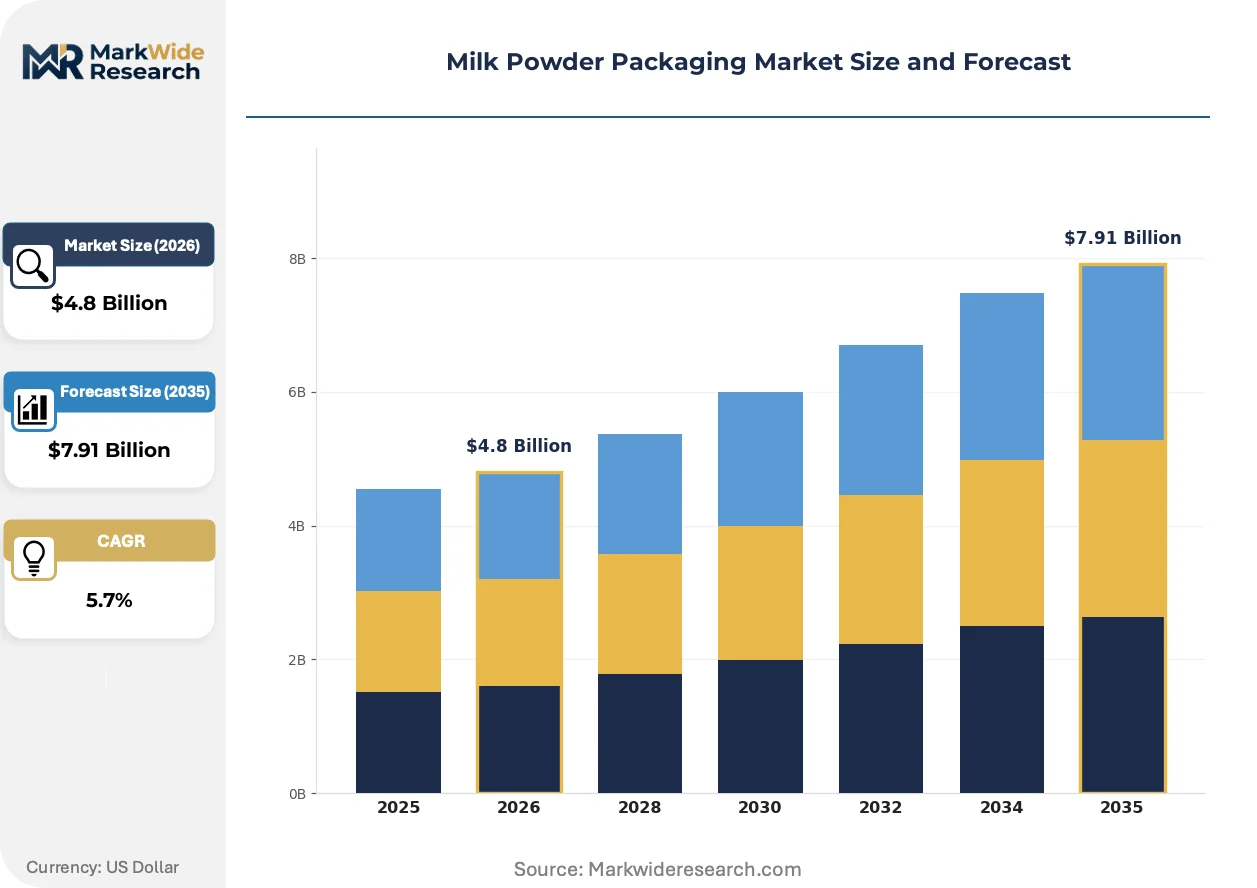
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Pouches, Rigid Containers, Tetra Packs, Sachets Material: Plastic, Paperboard, Metal, Composite Closure Type: Screw Caps, Snap-On Lids, Zip Lock, EPE Liners Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores |
| Companies Covered | Ball Corporation, SIG Combibloc Group Ltd, Tetra Pak International SA, Indevco Group, Elopak AS, Mondi PLC, Pactiv Evergreen Inc., Consolidated Container Company LLC, Stanpac Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Powder Packaging Market Shifts & Advancements
Active barrier technologies and regulatory compliance automation are converging to redefine competitive advantage in shelf-stable dairy containment systems.
Digital twin platforms for packaging line simulation are virtualizing commissioning timelines for aseptic powder filling installations. Infant formula manufacturers in the Netherlands and Ireland are deploying these tools to validate nitrogen-flush uniformity before physical equipment arrival. The technology is compressing capital deployment risk for greenfield plants in regulatory-stringent jurisdictions.
REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing laminate converters to requalify entire adhesive portfolios. Industrial consequence includes accelerated migration toward water-based and UV-cured bonding chemistries. Infant nutrition brands exporting into Germany and Scandinavia are responding by mandating full material substance inventories from tier-two suppliers.
Direct procurement relationships between dairy processors and specialty film coaters are displacing traditional converter-mediated sourcing in Southeast Asia. Vietnamese and Indonesian dairy brands are negotiating aluminum oxide deposition capacity directly with Japanese chemical suppliers. This pattern is most visible in Ho Chi Minh City and Jakarta, where lead times for high-barrier substrates previously stretched six months through distributor channels.
Milk Powder Packaging Market Segmentation
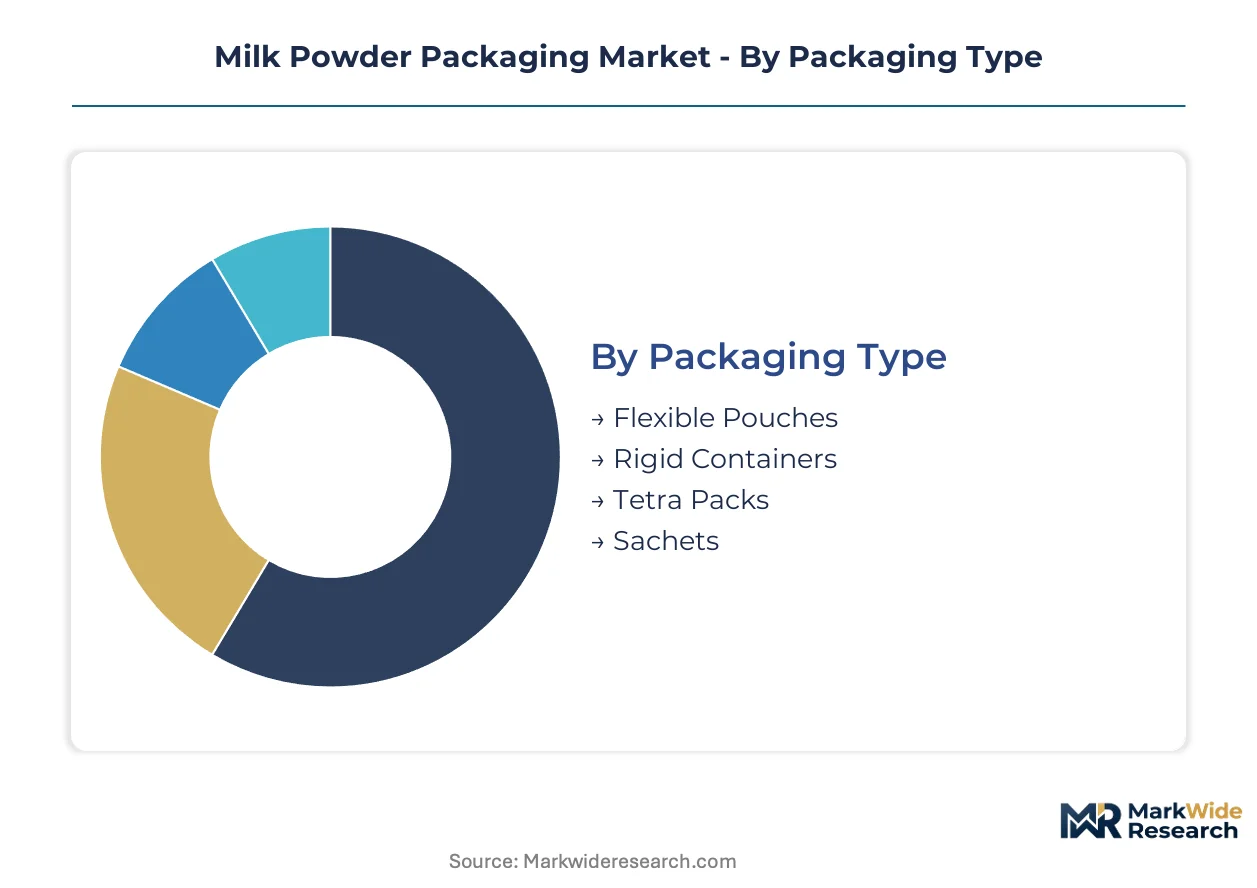
Packaging format selection in milk powder applications determines equipment service intensity, barrier engineering requirements, and regulatory compliance pathways across infant formula, nutritional supplements, and commodity dairy segments. Segment boundaries increasingly blur as converters develop hybrid structures combining flexible pouch convenience with rigid container protection levels.
Packaging Type:
After-sales service contracts concentrate around formats with aseptic filling complexity and nitrogen-flush integration, locking dairy processors into long-term technical support relationships with equipment suppliers.
- Flexible Pouches:Multi-layer laminates with aluminum oxide barrier films and resealable zipper interfaces dominate single-serve urban retail formats. Demand concentrates in Nigerian convenience channels where Lagos retailers stock trial-size units for price-sensitive consumers navigating dairy import dependency.
- Rigid Containers:HDPE or PET canisters with induction-sealed membranes provide maximum moisture exclusion for premium infant formula. German and Dutch manufacturers specify these formats for EU Packaging and Packaging Waste Regulation compliance, accepting higher unit costs for material recovery eligibility.
- Tetra Packs:Aseptic brick structures with laminated paperboard-aluminum-polyethylene composites serve bulk institutional procurement in African markets with limited cold chain reach.
- Sachets:Simple three-side-seal foil laminates target lowest-cost distribution in rural bulk channels across Ethiopia and Kenya.
By volume, rigid containers lead. By growth pace, flexible pouches are expanding most quickly.
Material:
Cost tier stratification separates premium sustainability signaling from functional barrier economics, with paperboard composites commanding price premiums and plastic laminates serving volume applications.
- Paperboard:Kraft-paper barrier composites with EVOH or aluminum oxide coatings target plastic-reduction mandates in European organic and premium infant formula lines. Mondi PLC's innovations here address REACH Article 33 disclosure requirements while preserving 24-month shelf stability.
- Composite:Multi-material laminates combining plastic, paper, and metal layers optimize barrier performance for lipid-sensitive powders. Vietnamese dairy processors source these directly from Japanese chemical vapor deposition suppliers, bypassing traditional converter channels to secure aluminum oxide capacity.
- Plastic:Monolayer or co-extruded polyethylene structures serve cost-optimized commodity milk powder in bulk formats across price-sensitive African markets.
- Metal:Tinplate or aluminum cans anchor North American nutritional powder demand through Ball Corporation's backward-integrated aluminum supply chain repurposed from beverage scale economies.
By revenue contribution, paperboard leads. By application breadth, composite materials are gaining share fastest.
Closure Type:
Application-driven selection matches convenience requirements against contamination risk, with infant formula mandating tamper-evident integrity and commodity powders accepting simpler reseal mechanisms.
- Screw Caps:Polypropylene or HDPE threaded closures with induction-sealed membranes provide hermetic integrity for premium infant formula canisters. FDA food-contact substance notifications govern adhesive migration limits in these applications, extending qualification timelines.
- Zip Lock:Integrated resealable tracks in flexible pouch formats enable portion control without dedicated tools. Nigerian urban retail expansion pulls these into single-serve convenience store distribution previously dominated by bulk formats.
- Snap-On Lids:Press-fit polyethylene covers serve intermediate protection levels in institutional-size rigid containers for foodservice applications.
- EPE Liners:Expanded polyethylene foam inserts provide cushioning and moisture buffering in export-oriented bulk packaging for cross-border African trade.
By installed base, screw caps lead. By format growth correlation, zip lock closures are climbing the fastest.
Distribution Channel:
Customer type fragmentation separates institutional procurement discipline from impulse-driven retail experimentation, with channel selection determining pack size architecture and branding investment levels.
- Convenience Stores:Small-format urban retail in Lagos and Abuja drives single-serve flexible pouch demand as Nigerian dairy distribution modernizes away from bulk channels. These outlets prioritize shelf-ready merchandising and price-point accessibility for emerging middle-class consumers.
- Online Retailers:Direct-to-consumer platforms enable SKU proliferation for regional flavor variants through digital printing convergence with barrier substrates. Indian PLI scheme subsidies support domestic converter capacity serving BIS-certified brands in this channel.
- Supermarkets:Organized retail chains in South Africa and Kenya stock full size ranges from economy bulk to premium infant formula, requiring packaging suppliers to manage tiered portfolio complexity.
- Specialty Stores:Pharmacy and nutrition-focused outlets in European markets emphasize organic certification and sustainability signaling, favoring paperboard-composite formats with full material substance inventories.
By transaction volume, supermarkets lead. By channel expansion velocity, convenience stores are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply between price-sensitive bulk procurement in African markets and premium infant formula segments in Europe where sustainability compliance commands cost premiums. Nigerian buyers prioritize unit economics in flexible pouch formats while German and Dutch purchasers absorb higher paperboard-composite costs for regulatory alignment.
Nigeria
Urban retail modernization in Lagos and Abuja is pulling single-serve flexible pouch formats into convenience store channels previously dominated by bulk distribution. The country's Standards Organisation of Nigeria maintains evolving food-contact material specifications that converters must navigate for import eligibility. Industrial packaging demand concentrates around Port Harcourt and Kano where dairy processors retrofit nitrogen-flush capacity for extended shelf-life distribution.
Germany
Premium infant formula manufacturers specify rigid HDPE canisters with induction-sealed membranes to satisfy EU Packaging and Packaging Waste Regulation recovery targets. The country's VerpackG extended producer responsibility framework imposes parallel compliance fees on multi-material laminates, inflating total cost of ownership for converters. Production gravity sits in North Rhine-Westphalia where paperboard-composite innovation clusters serve organic and sustainability-signaled product lines.
India
BIS certification requirements for food-contact substances in infant nutrition applications are accelerating domestic laminate production capacity under PLI scheme capital subsidies. The FSSAI governs migration limits for adhesives and coatings, extending qualification timelines for novel chemistries. Converter expansion concentrates in Maharashtra and Gujarat where regional dairy brands test SKU proliferation through digital printing convergence with barrier substrates.
Vietnam
Dairy processors in Ho Chi Minh City are negotiating aluminum oxide deposition capacity directly with Japanese chemical suppliers, bypassing traditional distributor channels to secure high-barrier film substrates. The country's Ministry of Health maintains food safety standards that align with regional export requirements for Southeast Asian distribution. Technical talent scarcity for nitrogen-flush retrofit engineering limits vertical form-fill-seal equipment upgrade velocity in the Mekong Delta packaging corridor.
United States
Ball Corporation anchors North American nutritional powder demand through backward-integrated aluminum supply chains repurposed from beverage-can scale economies. FDA food-contact substance notifications govern adhesive migration limits, with notification cycles now exceeding eighteen months for novel chemistries. Canister manufacturing concentrates in Colorado and Ohio where metal packaging infrastructure serves both dairy and adjacent nutritional supplement segments.
Milk Powder Packaging Market Competitive Landscape
Capability concentration sits with specialized barrier film innovators; scale advantage sits with diversified packaging conglomerates with beverage-can or aseptic system installed bases. The market structures around three tiers: integrated material suppliers controlling substrate deposition technology, equipment-locked service providers monetizing filling-line retrofits, and regional converters competing on digital printing agility. Dominant competitive moves include strategic partnerships between dairy processors and specialty film coaters, plus capacity expansion in nitrogen-flush-compatible flexible pouch formats.
Among diversified packaging conglomerates, Tetra Pak International SA and Ball Corporation exemplify contrasting scale strategies. Tetra Pak leverages aseptic system installed bases to lock in long-term service agreements across emerging markets, while Ball Corporation repurposes beverage-can aluminum supply chains for nutritional powder applications. Mondi PLC occupies a position within the sustainability-driven tier, anchoring paperboard-composite innovation for plastic-reduction mandates without sacrificing barrier performance. These three represent the archetype spectrum from equipment-integrated services through metal packaging scale to fiber-based barrier engineering.
| Leading Market Players |
|---|
| Ball Corporation |
| SIG Combibloc Group Ltd |
| Tetra Pak International SA |
| Indevco Group |
| Elopak AS |
| Mondi PLC |
| Pactiv Evergreen Inc. |
| Consolidated Container Company LLC |
| Stanpac Inc. |
| Others |
Supply & Pricing Matrix
Aluminum oxide deposition capacity concentration in Japanese and Southeast Asian chemical vapor deposition facilities determines both the spread between premium barrier-laminate pricing and commodity-grade alternatives and the geographic clustering of converter operations around Ho Chi Minh City and Jakarta. This single-source dependency for high-barrier substrates forces dairy processors into long-term offtake commitments or spot-market exposure, with pricing tiers widening as REACH Article 33 disclosure requirements add compliance cost layering.
Pricing Analysis
Long-term offtake contracts dominate procurement for infant formula-grade laminates, while spot purchasing persists in commodity milk powder segments. Three-tier pricing structure across premium, standard, and economy levels separates EU-compliant paperboard composites with full substance inventories from multi-material laminates and monolayer polyethylene formats. Pricing pressure stems from parallel extended producer responsibility fees in Germany and France inflating total cost of ownership for identical structures. Nigerian convenience store buyers exhibit highest price sensitivity, while Dutch and German organic infant formula purchasers absorb sustainability premiums.
Supply Chain Analysis
Upstream feedstock for aluminum oxide barrier films draws from chemical vapor deposition capacity concentrated in Japan, South Korea, and Taiwan. Raw material dependencies center on ethylene vinyl alcohol resins, kraft-paper substrates, and nitrogen-flush equipment components. Single-source vulnerability around Southeast Asian deposition capacity exposes converters to six-month lead time volatility when distributor channels are bypassed. Distribution runs through converter-mediated sourcing for standard grades and direct processor-to-coater relationships for premium barrier specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The milk powder packaging market sits in early-cycle expansion as shelf-stable nutrition demand penetrates African markets with limited cold chain infrastructure, creating first-mover advantage for integrated equipment-service providers.
For Market Incumbents: Pre-empt emerging entrant encroachment by locking in exclusive aluminum oxide deposition capacity through backward integration into Japanese chemical supplier relationships. Fortify position against flexible pouch commoditization by embedding nitrogen-flush technical support into long-term service agreements that raise switching costs for dairy processors in Nigeria and Ethiopia.
For New Entrants and Emerging Players: Establish a beachhead in Ethiopian dairy processing through packaging equipment-integrated service offerings targeting state-led industrial park development around Addis Ababa. Exploit white-space in digital printing convergence with barrier substrates for Indian regional brands testing SKU proliferation under PLI scheme subsidies, using direct-to-converter relationships to bypass established distributor channels.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation material recovery targets reshape the acquisition landscape toward paperboard-composite innovators with proven barrier performance. Long-term viability centers on converters with REACH-compliant adhesive portfolios and established BIS certification pathways for Indian market access. Monitor FDA food-contact substance notification cycle compression as the signal indicating regulatory chokepoint severity for novel chemistry deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Oxide Supply | Captive deposition capacity insulates Japanese chemical supplier relationships from spot-market volatility. |
| Digital Printing Convergence with Barrier Substrates | Variable-data-enabled production virtualizes SKU economics for Indian regional dairy brands. |
| Long-term Equipment Service Agreements | Nitrogen-flush technical support embedding raises switching costs for Nigerian dairy processors. |
| REACH-Compliant Adhesive Portfolio Requalification | Water-based and UV-cured chemistries unlock infant formula export eligibility into German markets. |
| Direct Processor-to-Coater Relationships | Bypassing distributor channels compresses lead times for high-barrier films in Vietnamese packaging corridors. |
Research Methodology
Desk research of EU regulatory filings, FDA food-contact substance notifications, and Indian BIS certification databases preceded structured interviews with packaging equipment engineering directors, laminate converter procurement leads, dairy processor supply chain managers, and infant formula regulatory affairs specialists. Secondary validation drew from trade customs data, SEC filings of diversified packaging conglomerates, and extended producer responsibility fee schedules across European jurisdictions. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Assumptions held fixed include EU Packaging and Packaging Waste Regulation recovery target timelines and FDA notification cycle durations, while aluminum oxide capacity expansion rates and Nigerian urban retail modernization velocity were varied across sensitivity bands. Segmentation dimensions encompassed packaging format, material substrate, closure mechanism, and distribution channel, with regional regulatory stringency as an overlay factor. CAGRs were derived from installed base growth projections and replacement cycle analysis across the projection horizon, incorporating nitrogen-flush equipment penetration rates and digital printing adoption curves as industry-specific inputs.
Stress conditions across aluminum oxide supply disruption severity, REACH Article 33 enforcement intensity, and Nigerian foreign exchange volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that BIS certification timeline extensions or FDA notification cycle compression could materially revise trajectory. Cross-checking against FSSAI migration limit updates and Standards Organisation of Nigeria specification evolution is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
Europe Dairy Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Latin America Dairy Packaging Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Dairy Containers Market