
 Europe Dairy Packaging Market | 2026-2036
Europe Dairy Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dairy Packaging Market Foresight
Portion-size modularization is rebalancing buyer choice across fresh dairy aisles, as single-serve and multi-pack configurations displace bulk formats. Tetra Laval International S.A. anchors aseptic carton technology for extended-shelf-life milk throughout Nordic supply chains. Huhtamaki Group leverages molded fiber expertise to capture yogurt cup contracts with private-label retailers. Greiner Packaging International GmbH specializes in thin-walled polypropylene tubs for fresh cheese applications across Central European dairies.
Europe dairy packaging encompasses the design, material selection, and fabrication of primary and secondary containers for fluid milk, fermented products, and fresh cheeses, typically incorporating oxygen-barrier layers, UV-blocking additives, and tamper-evident closures to preserve nutritional integrity and prevent spoilage. Its commercial purpose centers on extending distribution radius while satisfying retailer shelf-life requirements and consumer convenience expectations. Paper-based materials lead in milk volumes through aseptic carton dominance, while plastic pouches represent the fastest-growing configuration in yogurt segments driven by lightweighting and format flexibility. Glass jars retain premium positioning in artisan cheese and specialty cream segments where brand differentiation commands higher margin pools.
EMA food-contact material guidelines, EU Green Deal packaging waste directives, and F-Gas Regulation refrigerant standards collectively reshape material compliance costs and carbon-accounting obligations for dairy packagers operating across member states. REACH chemical restrictions on certain plastic additives further narrow the approved substance palette for direct food-contact layers. Stakeholders must monitor evolving Extended Producer Responsibility fee structures and deposit-return scheme expansions as these mechanisms increasingly determine total cost of ownership for format selection decisions.
Market Dynamics
EU Green Deal packaging waste directives and F-Gas Regulation refrigerant standards are compressing format choices across European dairy supply chains, forcing simultaneous transitions in barrier materials and cold-chain infrastructure.
Growth Catalysts
- Single-serve pouch adoption:German Greek yogurt producers are expanding portion-controlled flexible formats that reduce per-unit material intensity while meeting convenience demand in urban retail.
- Fiber-based barrier innovation:EMA food-contact guidelines are accelerating molded fiber cup deployments for fresh cheese applications across private-label retail channels.
- Normandy cluster concentration:France's dairy processing hub generates specialized demand for oxygen-barrier aseptic cartons with extended distribution radius requirements.
Market Restraints
- Polypropylene feedstock volatility:Thin-walled tub production for Central European fresh cheese faces margin pressure from propylene monomer price swings tied to naphtha-cracking economics.
- Deposit-return scheme fragmentation:Divergent national EPR fee structures across Germany, France, and Italy complicate pan-European format standardization and total cost forecasting.
- Glass jar substitution ceiling:Premium artisan cheese segments resist material switching due to brand equity tied to traditional packaging aesthetics and shelf presence.
Strategic Opportunities
- Italy Parmigiano-Reggiano zone:Protected designation-of-origin cheese production creates demand for tamper-evident, humidity-controlled rigid packaging with provenance authentication features.
- CSRD carbon-accounting alignment:Mandatory Scope 3 disclosure requirements position fiber-based formats for preferential selection by dairy processors seeking supply chain emission reductions.
- Direct-to-consumer chilled delivery:E-commerce subscription models for specialty fermented products are opening insulated pouch configurations bypassing traditional retail shelf-life constraints.
Industry Challenges
- Multi-layer film recycling infrastructure:EVOH and metallized barrier layers in extended-shelf-life milk cartons lack viable mechanical recycling pathways, creating compliance gaps with EU packaging waste targets.
- Aseptic line retrofit capex:Dairy processors face capital intensity for converting existing filling equipment to handle fiber-based barrier materials without compromising sterilization validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dairy Packaging Market |
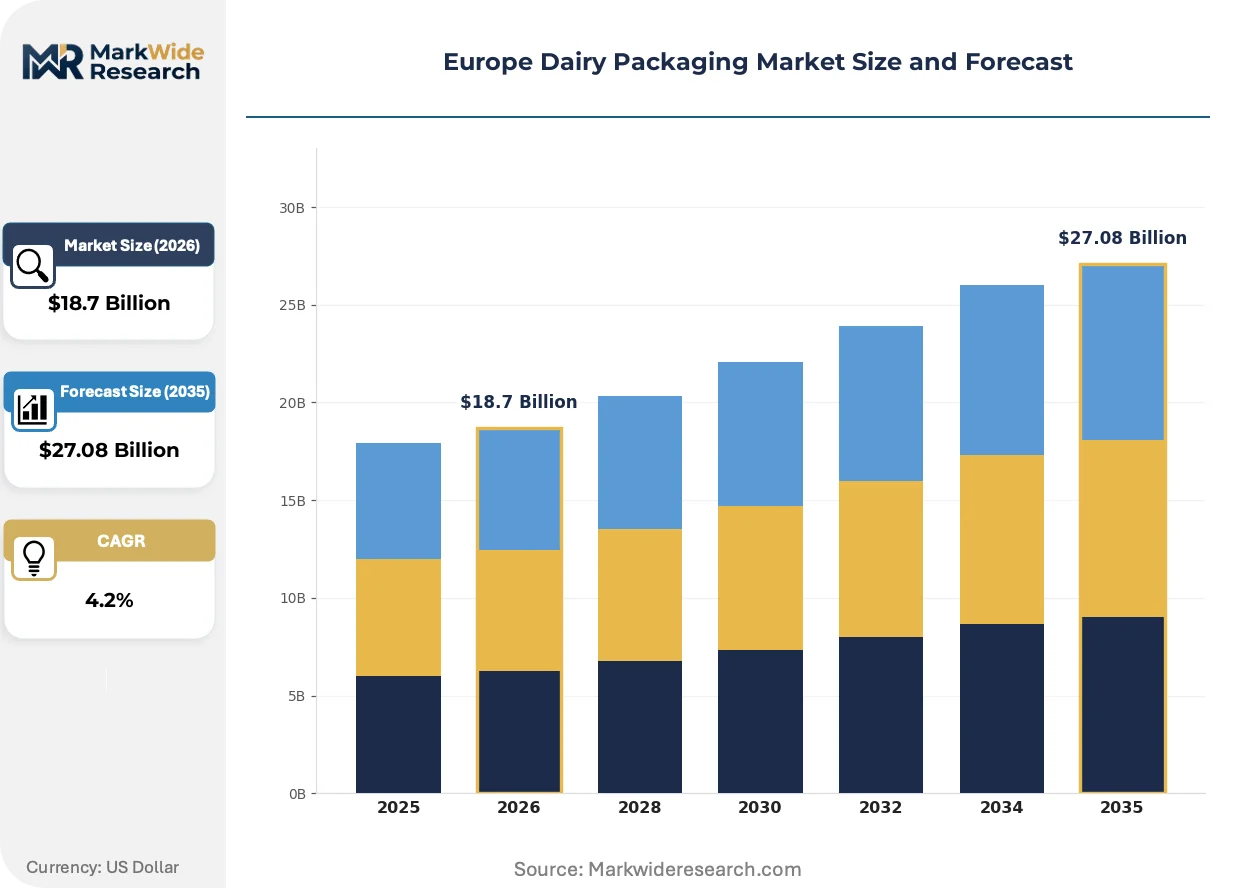
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Cream Material: Plastic, Paper, Glass, Metal Packaging Type: Bottles, Tetra Packs, Pouches, Jars End User: Retailers, Food Service, Direct Sales, E-Commerce |
| Companies Covered | Schur Flexibles Holding GesmbH, Stora Enso Oyj, Amcor Limited, Crown Holdings, Inc, Ball Corporation, Huhtamaki Group, Greiner Packaging international GmbH, Sealed Air Corp., Tetra Laval International S.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dairy Packaging Market Shifts & Advancements
Barrier material substitution and format lightweighting are restructuring competitive advantage across European dairy packaging, with sustainability-linked procurement criteria now filtering supplier selection.
High-barrier molded fiber technology is expanding into fresh yogurt cup applications previously dominated by polypropylene. Private-label retailers in Germany and France are piloting these formats for store-brand Greek yogurt lines. The shift is compressing virgin plastic volume commitments while demanding new heat-seal integrity standards for cold-chain distribution.
REACH chemical restrictions on certain phthalate plasticizers and bisphenol-derived coatings are narrowing the approved substance palette for direct food-contact layers. Dairy packagers must reformulate lacquers and adhesives used in aseptic carton structures. Nordic fluid milk processors are most affected, given their reliance on extended-shelf-life distribution to sparse population centers.
Buyer consolidation among European supermarket chains is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Dairy processors now source packaging specifications through centralized procurement functions rather than regional plant-level decisions. This pattern is most visible in the Netherlands and Belgium, where retail concentration has advanced furthest.
Europe Dairy Packaging Market Segmentation
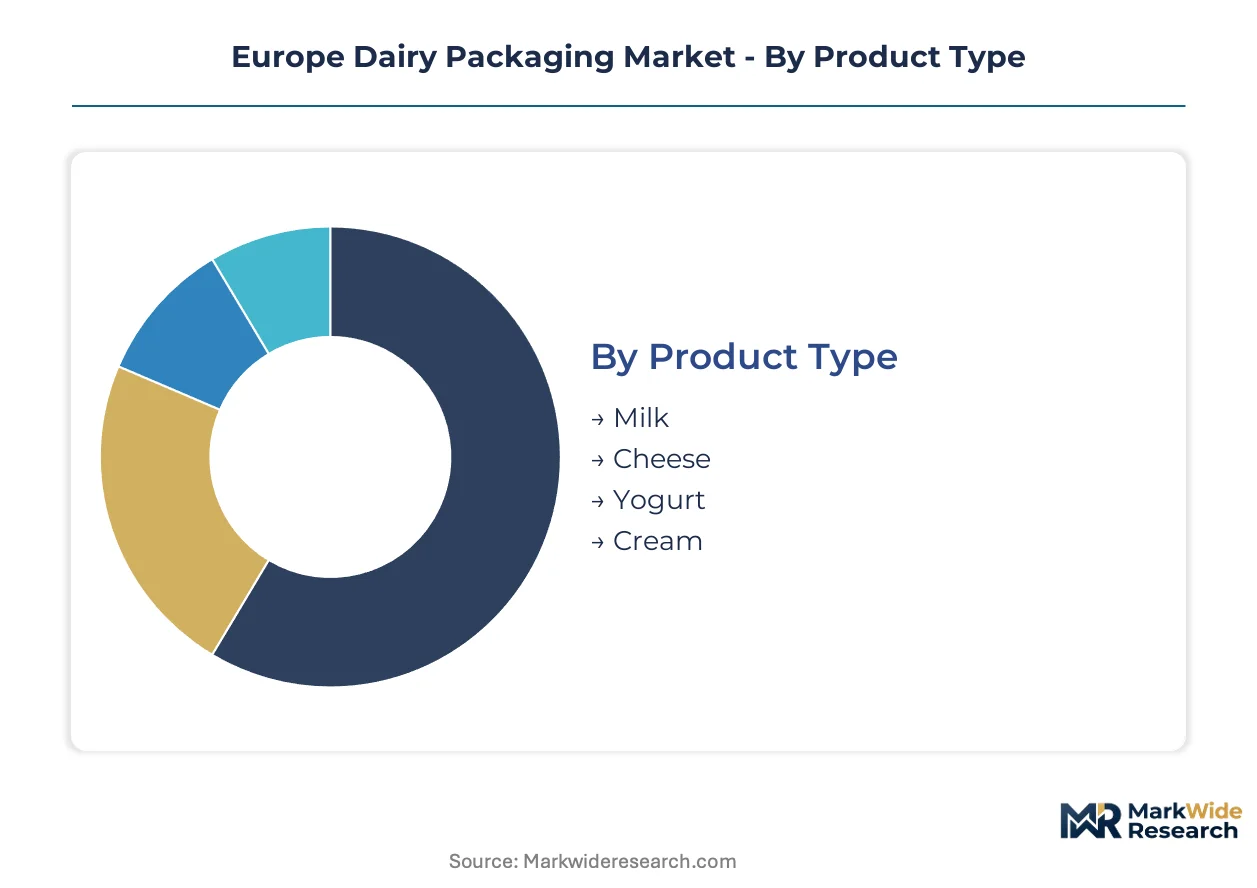
Format selection in Europe dairy packaging hinges on shelf-life requirements, cold-chain infrastructure, and retailer EPR compliance obligations. Material and configuration choices cascade through total cost of ownership calculations as processors balance barrier performance against circularity mandates.
Product Type:
Buyers prioritize oxygen-barrier specifications and distribution radius when selecting formats for specific dairy categories.
- Milk:Aseptic carton structures with EVOH barrier layers dominate extended-shelf-life distribution across Nordic supply chains. Tetra Laval filling lines anchor production economics for ambient milk volumes throughout Germany and France.
- Yogurt:Greek yogurt producers in Germany are expanding portion-controlled pouch formats that reduce per-unit material intensity. Single-serve configurations are climbing the fastest as urban retail shifts toward convenience-oriented packaging.
- Cheese:Fresh cheese applications in Central Europe rely on thin-walled polypropylene tubs with modified atmosphere capabilities.
- Cream:Specialty cream segments retain glass jar positioning where brand differentiation commands premium shelf placement.
Milk leads on scale; yogurt leads on momentum.
Material:
Carbon-accounting obligations under CSRD disclosure requirements are redirecting procurement toward fiber-based alternatives.
- Plastic:Polypropylene feedstock volatility from naphtha-cracking economics compresses margins for thin-walled tub production. REACH restrictions on phthalate plasticizers narrow formulation options for direct food-contact layers.
- Paper:High-barrier molded fiber technology is displacing virgin plastic in fresh yogurt cup applications across German and French private-label retail. EMA food-contact guidelines validate these transitions for cold-chain distribution.
- Glass:Artisan cheese segments in Italy's Parmigiano-Reggiano zone resist material switching due to provenance authentication requirements.
- Metal:Aerosol cream dispensers and specialty closures retain niche positioning in food service channels.
Paper is gaining share fastest; plastic retains volume dominance.
Packaging Type:
Retailer consolidation across the Netherlands and Belgium is compressing supplier negotiation cycles and unbundling technical service from material contracts.
- Bottles:HDPE and PET formats serve fresh milk distribution with shorter shelf-life requirements in France's Normandy cluster.
- Tetra Packs:Aseptic carton technology enables extended distribution radius for fluid milk throughout sparse Nordic population centers. F-Gas Regulation compliance costs accelerate fiber-based barrier transitions.
- Pouches:Flexible formats reduce logistics cube and material intensity for portion-controlled yogurt in German urban retail.
- Jars:Rigid glass and plastic jar configurations serve humidity-controlled requirements for protected designation-of-origin cheese production.
Tetra Packs anchor volume; pouches show steepest expansion trajectory.
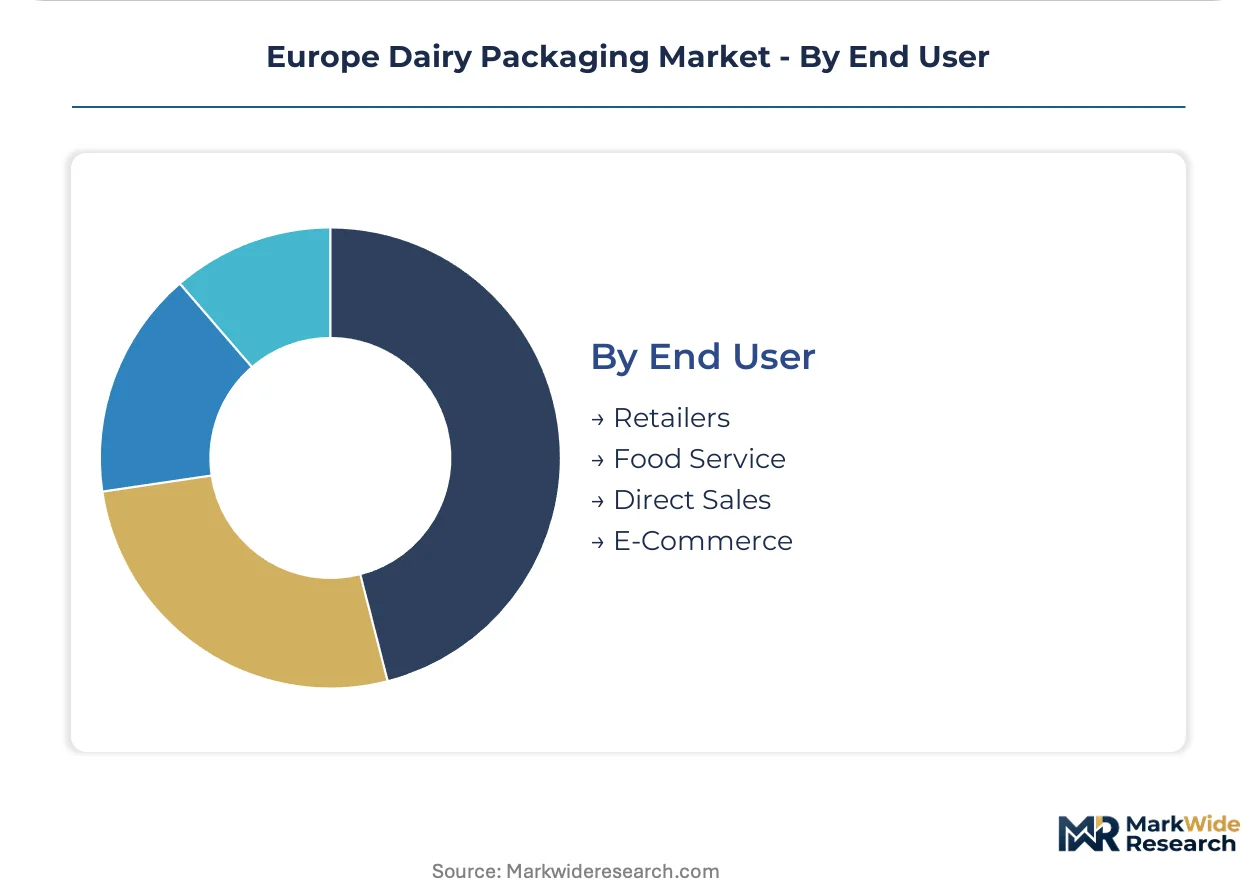
End User:
Channel-specific shelf-life constraints and handling protocols dictate format specifications and barrier investments.
- Retailers:Centralized procurement functions in Dutch and Belgian supermarket chains now source packaging specifications rather than regional plant-level decisions. EPR fee structures and deposit-return schemes determine total cost of ownership calculations.
- Food Service:Bulk dispensing formats and portion-control systems dominate institutional dairy delivery with simplified barrier requirements.
- Direct Sales:Farm-gate and farmers' market channels favor reusable glass return systems with localized distribution economics.
- E-Commerce:Subscription models for specialty fermented products are opening insulated pouch configurations that bypass traditional retail shelf-life constraints.
Retailers command procurement scale; e-commerce is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy packaging technology first achieved industrial scale in Nordic supply chains during the 1950s aseptic carton revolution, then diffused through German and French processing networks as extended-shelf-life distribution became economically viable.
Germany
Greek yogurt producers in Bavaria and Baden-Württemberg are expanding portion-controlled pouch formats for urban retail channels. The national packaging act implements Extended Producer Responsibility fee structures that elevate total cost of ownership for virgin plastic formats. Berlin-Brandenburg dairy clusters are piloting fiber-based barrier cups for private-label retailers under EMA food-contact validation protocols.
France
Normandy's concentrated dairy processing hub generates specialized demand for oxygen-barrier aseptic cartons with distribution radius requirements spanning sparse rural populations. The national anti-waste law accelerates deposit-return scheme expansions for rigid packaging formats. Île-de-France supermarket chains are compressing supplier negotiation cycles through centralized procurement functions.
Italy
Protected designation-of-origin cheese production in Emilia-Romagna creates demand for tamper-evident, humidity-controlled rigid packaging with provenance authentication features. REACH chemical restrictions on phthalate plasticizers narrow formulation options for direct food-contact layers. Lombardy-based processors face margin pressure from propylene monomer price volatility tied to naphtha-cracking economics.
Netherlands
Retail concentration in the Randstad has advanced furthest among European markets, unbundling technical service from material supply contracts. The national climate agreement imposes carbon-accounting disclosure requirements that redirect procurement toward fiber-based alternatives. Brabant dairy cooperatives are retrofitting aseptic filling lines to handle molded fiber barrier materials without compromising sterilization validation.
Sweden
Nordic fluid milk processors rely most heavily on extended-shelf-life distribution to sparse population centers, making F-Gas Regulation compliance costs particularly acute for cold-chain infrastructure. The national environmental code accelerates fiber-based barrier transitions beyond EU baseline requirements. Stockholm-Uppsala dairy networks are piloting high-barrier molded fiber technology for fresh yogurt applications previously dominated by polypropylene.
Europe Dairy Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology sophistication, with integrated material innovators commanding pricing power over converters dependent on merchant substrate supply. The vendor base organizes into three functional tiers: multinational packaging conglomerates with captive R&D infrastructure, regional specialists leveraging molded fiber or thin-walled plastic expertise, and commodity converters competing on throughput scale. Strategic archetypes include aseptic system integrators, fiber-based barrier innovators, and flexible format lightweighting specialists. Dominant competitive moves encompass vertical integration into substrate production and strategic partnerships with dairy processors for co-developed sustainable formats.
Among Nordic-based material innovators, Stora Enso Oyj exemplifies the fiber-based barrier transition archetype through its molded fiber technology deployments. Tetra Laval International S.A occupies a position as the aseptic system integration anchor across extended-shelf-life milk networks. Huhtamaki Group represents the flexible format lightweighting specialist tier through its pouch and cup manufacturing presence in Central European dairy supply chains.
| Leading Market Players |
|---|
| Schur Flexibles Holding GesmbH |
| Stora Enso Oyj |
| Amcor Limited |
| Crown Holdings, Inc |
| Ball Corporation |
| Huhtamaki Group |
| Greiner Packaging international GmbH |
| Sealed Air Corp. |
| Tetra Laval International S.A |
| Others |
Supply & Pricing Matrix
Propylene monomer costs from naphtha-cracking economics cascade through thin-walled polypropylene tub production, compressing margins for Central European fresh cheese packagers while fiber-based alternatives capture premium positioning in German and French private-label retail channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aseptic carton barrier systems from molded fiber cups and commodity polypropylene tubs. Price differentiation hinges on EMA food-contact certification grade and volume scale commitments to Nordic fluid milk networks. Cost compression in standard-tier virgin plastic formats is intensifying because REACH chemical restrictions narrow approved additive palettes. Private-label retailers exhibit highest price sensitivity; artisan cheese processors in Italy's Parmigiano-Reggiano zone demonstrate lowest sensitivity due to provenance authentication requirements.
Supply Chain Analysis
Deposit-return scheme flows and EPR fee structures create reverse-logistics complexity across Germany, France, and Italy, where divergent national implementations fragment pan-European format standardization. Raw material supply draws from Nordic pulp and paper clusters, German petrochemical complexes, and Italian glass manufacturing regions. Single-source vulnerability concentrates in EVOH barrier layer supply for extended-shelf-life milk cartons. Distribution runs through centralized procurement functions at Dutch and Belgian supermarket chains that unbundle technical service from material contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
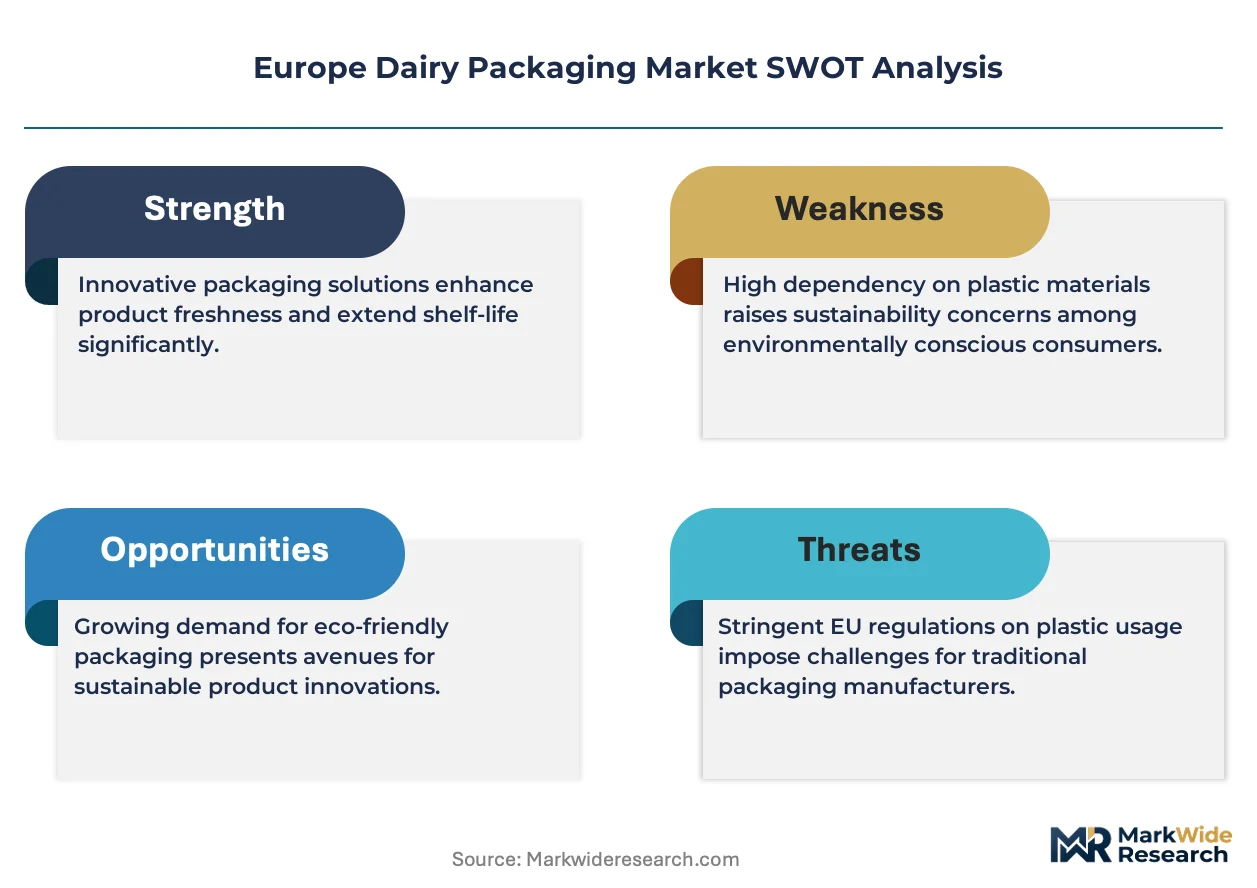
Margin expansion opportunities concentrate in fiber-based barrier transitions and premium-tier authentication packaging for protected designation-of-origin cheese segments, where CSRD carbon-accounting disclosure requirements redirect procurement toward lower-emission formats.
For Market Incumbents: Extend aseptic system integration capabilities into molded fiber barrier validation protocols before dairy processors complete line retrofits in the Netherlands and Sweden. Backward integration into pulp substrate production secures supply continuity as Nordic fiber demand accelerates. Capacity addition in Brabant dairy cooperatives captures Netherlands climate agreement procurement shifts. For New Entrants and Emerging Players: Private-label retailers in Germany and France present the most penetrable channel partnership opportunity for high-barrier molded fiber cup suppliers. White-space targets include direct-to-consumer chilled delivery subscription models and e-commerce insulated pouch configurations for specialty fermented products. Co-development partnerships with Bavarian Greek yogurt processors offer validated entry into portion-controlled flexible formats. For Investors and Strategic Acquirers: Consolidation pressure builds where fiber-based barrier technology capabilities concentrate among Nordic material innovators and regional molded fiber specialists. Long-term viability favors integrated substrate producers with captive R&D infrastructure over commodity converters dependent on merchant supply. Acquisition target archetype: regional specialists with EMA-validated food-contact barrier portfolios. Monitor F-Gas Regulation compliance cost trajectories as inflection indicator for cold-chain infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Substrate Production | Nordic fiber demand from Tetra Laval and Stora Enso anchors supply security for dairy barrier transitions. |
| Aseptic Line Retrofit for Molded Fiber Validation | Brabant dairy cooperatives unlock Netherlands climate agreement procurement preferencing through sterilization protocol adaptation. |
| Co-Developed Sustainable Format Partnership | Huhtamaki Group's pouch expertise combined with German retailer private-label specifications accelerates portion-controlled adoption. |
| Extended Producer Responsibility Compliance Investment | German packaging act fee structures elevate total cost of ownership calculations for virgin plastic formats against fiber alternatives. |
| Premium Tier Authentication Packaging Launch | Italy's Parmigiano-Reggiano zone humidity-controlled rigid packaging commands margin pools through provenance verification features. |
Research Methodology
Direct dialogue with dairy procurement directors, packaging R&D leads, private-label category buyers, and aseptic filling line engineers grounded qualitative insights in operational reality. Secondary validation drew from EMA food-contact guidelines, EU Green Deal packaging waste directive filings, F-Gas Regulation compliance disclosures, and CSRD carbon-accounting submission frameworks. Bottom-up volume modeling across format types triangulated with top-down market sizing from trade association production statistics.
Segment-level outputs across the projection horizon reflect material substitution trajectories, regulatory compliance cost pass-through assumptions, and retailer consolidation patterns in Benelux markets. Modeled dimensions span product category, barrier technology tier, material substrate type, and end-user channel structure. CAGRs emerged from logistic curve fitting to historical format adoption rates and policy-driven inflection timing.
Revisions become necessary when EPR fee structure harmonization advances beyond current national fragmentation, F-Gas Regulation enforcement intensity shifts cold-chain infrastructure investment cycles, or REACH chemical restriction expansions accelerate beyond phthalate plasticizer scope. Practitioners should monitor Nordic deposit-return scheme implementation timelines and Italian protected designation-of-origin packaging specification updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Dairy Containers Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Latin America Dairy Packaging Market