
 Milk Packaging Market | 2026-2036
Milk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Packaging Market Analysis
PET is consolidating share from glass in ambient milk distribution, driven by weight reduction and logistics efficiency. Tetra Pak International S.A. leverages its aseptic carton heritage to defend premium positions in extended-shelf-life segments. SIG Combibloc Group AG anchors European food-service supply through on-the-go format specialization. Amcor plc competes in multi-layer bottle structures for flavored milk variants.
Milk packaging encompasses the engineered containment, preservation, and distribution systems for liquid dairy products, typically employing barrier-coated paperboard, blow-molded thermoplastics, or surface-treated glass with specified oxygen transmission rates below 1 cc per square meter per day to prevent lipid oxidation and microbial proliferation. Its primary commercial purpose is to maintain nutritional integrity while enabling efficient cold-chain or ambient supply chain transit from processor to retail endpoint. Carton board formats lead in ambient UHT channels across Europe and Asia, while PET bottles capture growth in refrigerated single-serve and flavored milk segments where clarity and resealability command shelf appeal. HDPE dominates bulk institutional containers in North American school and hospital feeding programs, where cost per unit and drop resistance outweigh premium presentation requirements.
The FDA governs food-contact substance notifications for polymer migration limits in US milk packaging, while the EU's Packaging and Packaging Waste Regulation mandates recyclability thresholds and recycled content minimums that reshape material selection across European supply chains. India's BIS certification requirements for food-grade plastics and the country's extended producer responsibility frameworks under the Plastic Waste Management Rules impose compliance costs that favor larger converters with testing infrastructure. Stakeholders must monitor evolving extended producer responsibility schemes and fiber-based barrier coating breakthroughs to align capital allocation with regulatory trajectories and retailer sustainability procurement criteria.
Market Dynamics
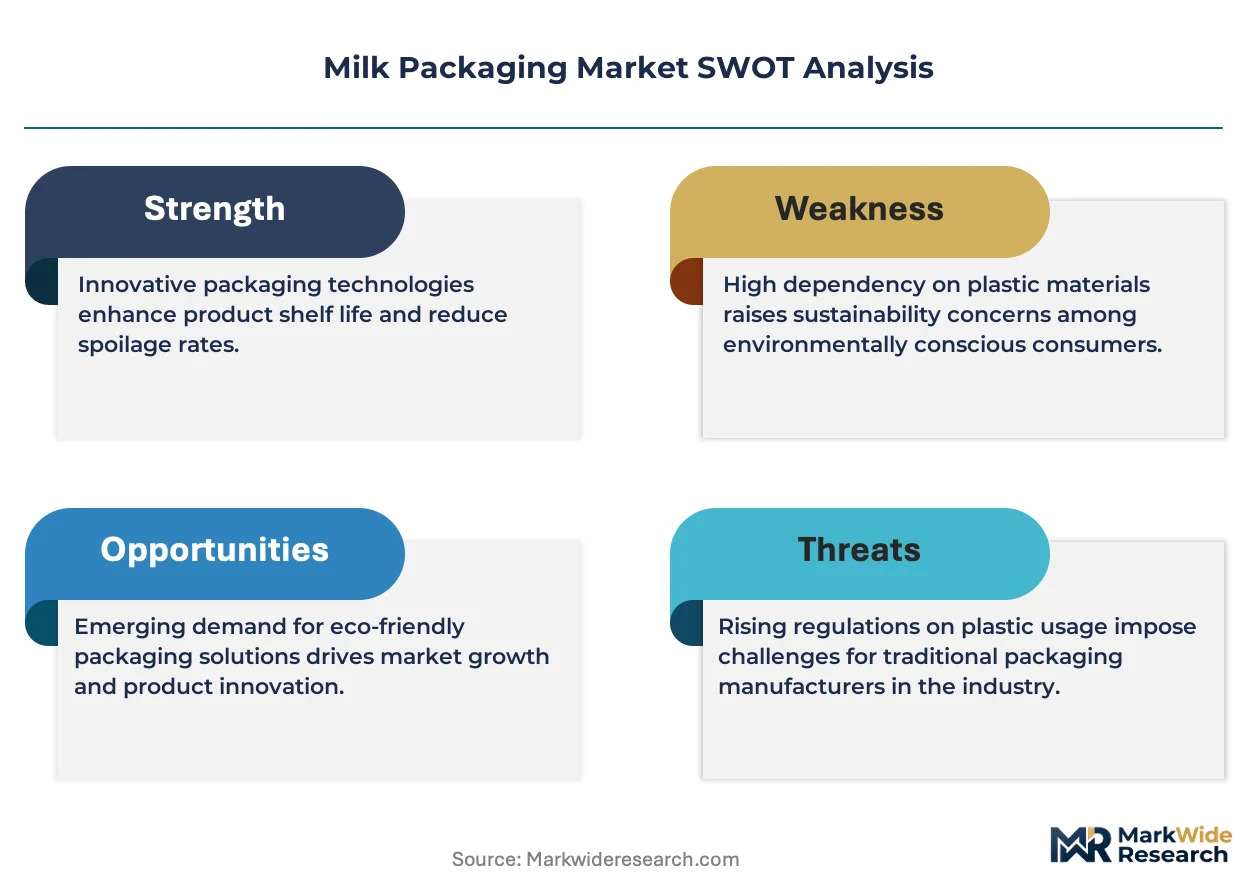
The EU's Packaging and Packaging Waste Regulation is compressing material transition timelines, forcing converters to abandon multi-layer plastics for fiber-based barriers ahead of technical readiness.
Growth Catalysts
- Institutional UHT adoption:Food-service channels in India and Brazil are standardizing aseptic carton procurement for ambient milk distribution, eliminating cold-chain dependency in school feeding programs.
- REACH-compliant barrier coatings:European converters are qualifying polyethylene-free paperboard for dairy contact, unlocking premium shelf-space access under retailer sustainability scorecards.
- Flavored milk SKU proliferation:Beverage brands are demanding PET clarity and resealability for protein-fortified variants, expanding addressable packaging value per liter beyond commodity white milk.
Market Restraints
- Recycled PET feedstock scarcity:FDA food-contact clearance for post-consumer rPET remains bottlenecked by contamination detection limits, constraining circular material supply for dairy bottles.
- Aluminum foil barrier dependence:Aseptic cartons retain metallized layers incompatible with European paper recycling streams, creating compliance exposure under PPWR recyclability thresholds.
- HDPE resin price volatility:Bulk institutional container contracts in North America face margin compression when ethylene feedstock costs spike, favoring longer-term fixed-price agreements.
Strategic Opportunities
- Indian cold-chain infrastructure:Organized dairy retail expansion in Maharashtra and Gujarat is creating demand for temperature-indicating smart packaging that signals spoilage risk to consumers.
- Biodegradable polymer pilots:PLA and PHA barrier trials for short-shelf-life fresh milk are qualifying under BIS compostability standards, positioning early movers for municipal waste policy alignment.
- Direct-to-subscription channels:E-commerce milk delivery platforms in urban China are specifying custom-format pouch packaging with ergonomic handles, bypassing traditional retail shelf constraints.
Industry Challenges
- Multi-material separation expertise:Converter engineering teams lack proficiency in delaminating aseptic carton layers for fiber recovery, slowing PPWR compliance execution.
- Migration testing backlog:FDA food-contact substance notifications for novel barrier coatings face 18-month review queues, delaying product launches for export-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Packaging Market |
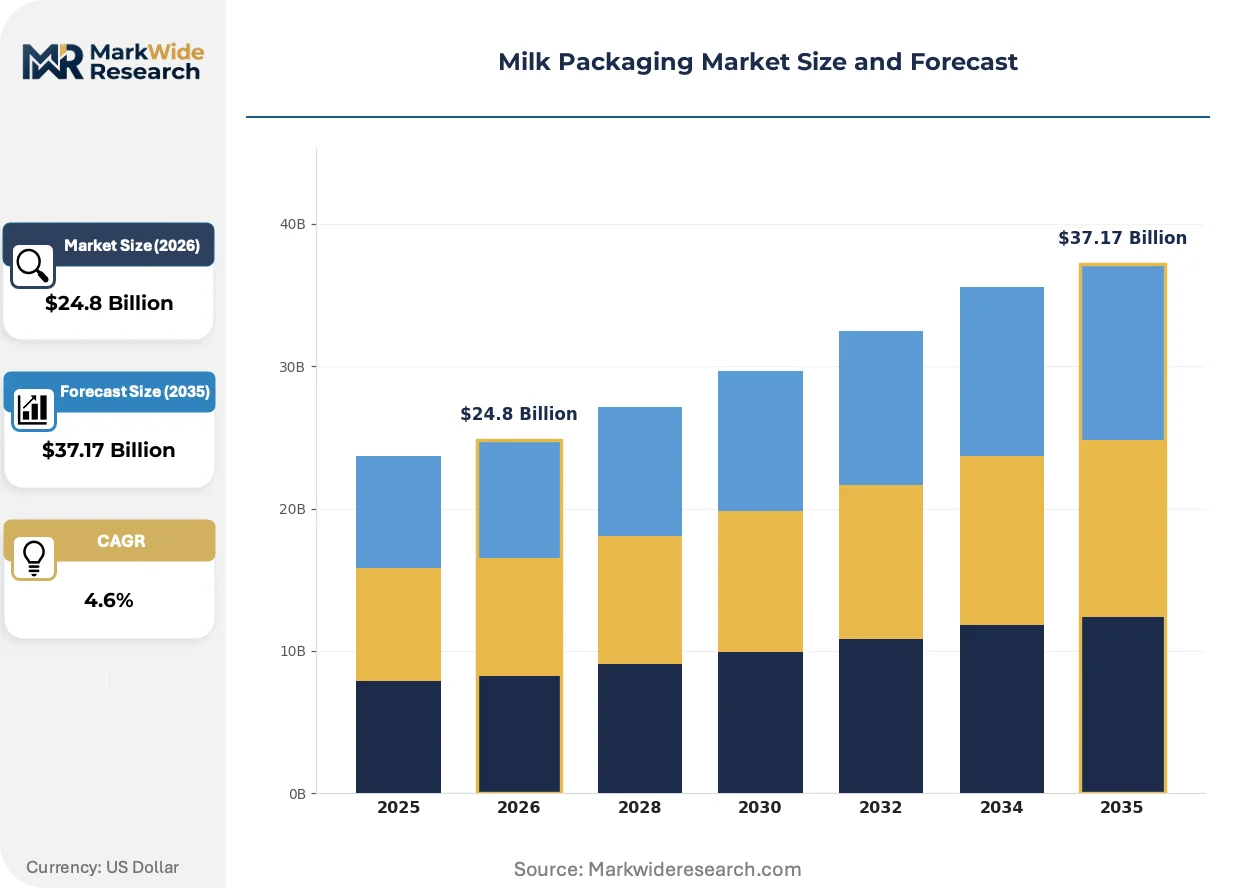
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cartons, Plastic Bottles, Glass Bottles, Pouches Material: PET, HDPE, LDPE, Carton Board Closure Type: Cap, Screw Cap, Spout, Heat Seal Distribution Channel: Retail, Online, Direct Sales, Food Service |
| Companies Covered | Tetra Pak International S.A., SIG Combibloc Group AG, Ball Corporation, Amcor plc, Elopak AS, Nippon Paper Industries Co. Ltd., Crown Holdings Inc., Nampak, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Packaging Market Emerging Trajectories
Automation of packaging lines is compressing changeover times between SKUs, while regulatory pressure on material circularity is accelerating substitution trials. These forces are reshaping capital allocation and technical roadmaps simultaneously.
Digital printing with water-based inks is automating versioning for regional dairy brands. Mid-size cooperatives in Germany and the Netherlands are adopting inline decoration to replace pre-printed sleeves, cutting inventory obsolescence for seasonal promotions. This technology is automating the economics of short-run packaging, eroding minimum-order-quantity advantages historically held by large converters.
The EU's Packaging and Packaging Waste Regulation mandates 70% recyclability thresholds by 2030. This is forcing Tetra Pak and SIG to accelerate fiber-polymer separation R&D, with pilot facilities in Sweden and Switzerland now processing post-consumer cartons into pulp feedstock. Aseptic carton producers are responding by pre-qualifying aluminum-free barrier structures for 2026 commercialization.
Retailers are consolidating supplier panels around sustainability certification tiers. French and British supermarket chains now require dairy packaging to carry OPRL or How2Recycle labels, disqualifying unmarked SKUs from shelf placement. This behavioral shift concentrates procurement authority with converters possessing in-house testing infrastructure and multi-territory label compliance capabilities.
Milk Packaging Market Segmentation
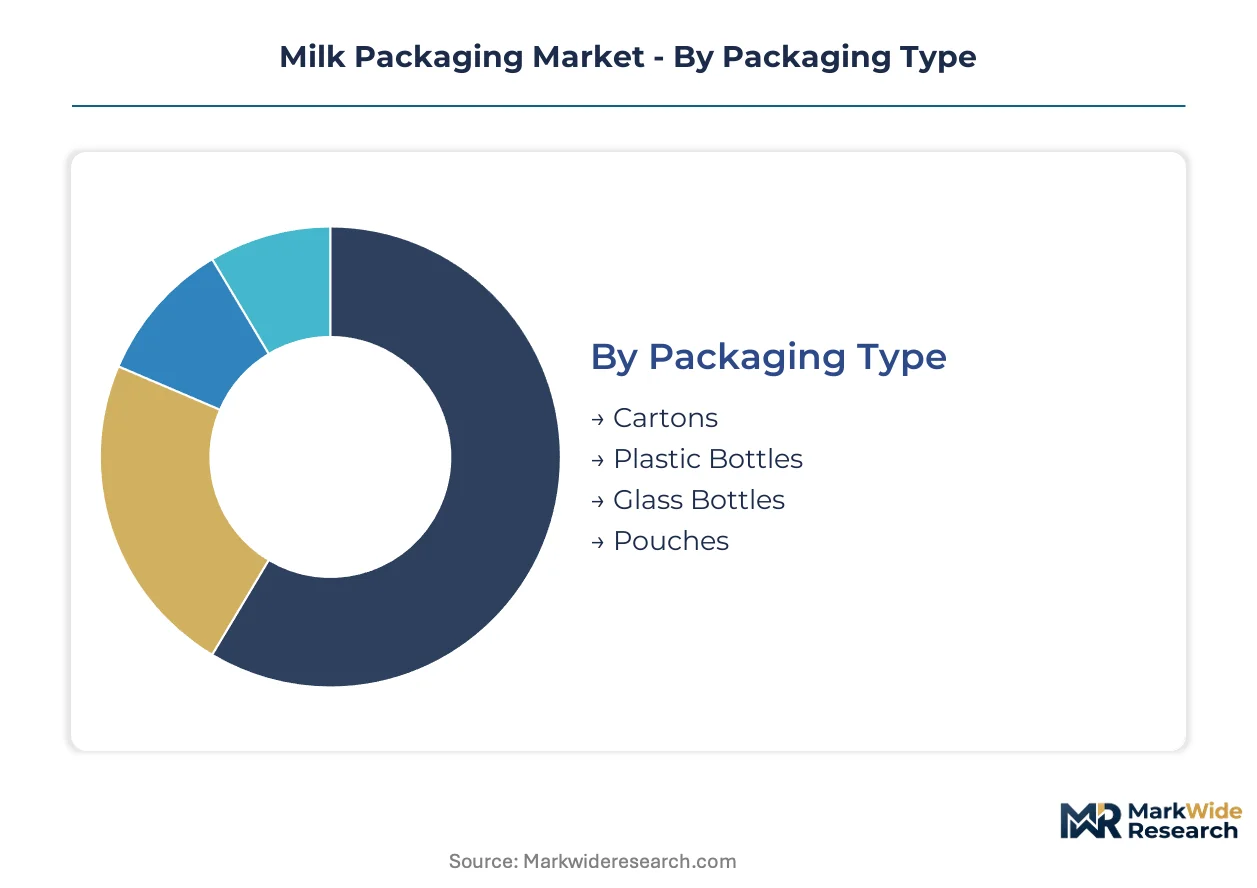
Milk packaging procurement decisions hinge on shelf-life requirements, cold-chain availability, and retail format constraints. Material selection and closure design directly determine logistics costs and consumer convenience premiums across ambient and chilled distribution networks.
Packaging Type:
Carton systems demand the heaviest upfront capital for aseptic filling lines and barrier coating equipment, while blow-molded formats require lower tooling investments but higher per-unit resin costs.
- Cartons:Multi-layer paperboard structures with aluminum or polymer barriers dominate UHT milk distribution in Europe and India. European retailers now mandate OPRL recyclability labeling, forcing converters to qualify fiber-polymer separation technologies ahead of PPWR deadlines.
- Plastic Bottles:Blow-molded PET and HDPE containers capture refrigerated single-serve and flavored milk segments where clarity and resealability command shelf appeal. FDA food-contact clearance for post-consumer rPET remains bottlenecked by contamination detection limits.
- Glass Bottles:Surface-treated returnable formats persist in premium organic channels and deposit-return markets, particularly in Germany and Switzerland. Weight and fragility penalties limit expansion beyond local dairy cooperatives.
- Pouches:Flexible multi-layer films with spout fitments serve institutional food-service volumes and emerging e-commerce subscription channels in urban China. Ergonomic handle specifications are bypassing traditional retail shelf constraints.
Cartons absorb the bulk of installed capacity; pouches are expanding most quickly.
Material:
Resin selection tracks price volatility and regulatory migration limits, with converters prioritizing feedstock security over performance optimization in volatile ethylene markets.
- PET:Amorphous polyester with oxygen scavenger additives delivers sub-1 cc/m²/day transmission rates for extended-shelf-life flavored milks. Clarity specifications from beverage brands are displacing HDPE in premium refrigerated segments.
- HDPE:High-density polyethylene dominates bulk institutional containers in North American school and hospital feeding programs. Ethylene feedstock cost spikes compress margins on fixed-price annual contracts.
- LDPE:Low-density variants serve as seal layers and pouch films for short-shelf-life fresh milk in Indian organized retail. BIS certification requirements for food-grade plastics favor larger converters with testing infrastructure.
- Carton Board:Barrier-coated paperboard qualifies for European retailer sustainability scorecards under REACH-compliant polyethylene-free formulations. Aluminum-free structures are pre-qualifying for commercialization ahead of PPWR recyclability thresholds.
Carton board claims the steepest expansion trajectory as fiber-based barriers displace multi-layer plastics; LDPE faces margin pressure from biopolymer substitution trials.
Closure Type:
Closure engineering investments concentrate on tamper-evidence and resealability features that reduce spoilage returns in warm-climate distribution.
- Cap:Snap-fit polyethylene closures for HDPE institutional containers prioritize drop resistance and cost efficiency over repeated reseal cycles.
- Screw Cap:Threaded polypropylene designs enable oxygen barrier maintenance across multiple openings for family-size PET bottles in Brazilian retail.
- Spout:Integrated fitment systems for flexible pouches support on-the-go consumption in Chinese e-commerce channels with ergonomic drinking geometry.
- Heat Seal:Induction-sealed foil membranes provide tamper evidence for aseptic cartons in Indian school feeding programs eliminating cold-chain dependency.
Screw caps retain the largest installed base; spouts are gaining share fastest through pouch format proliferation.
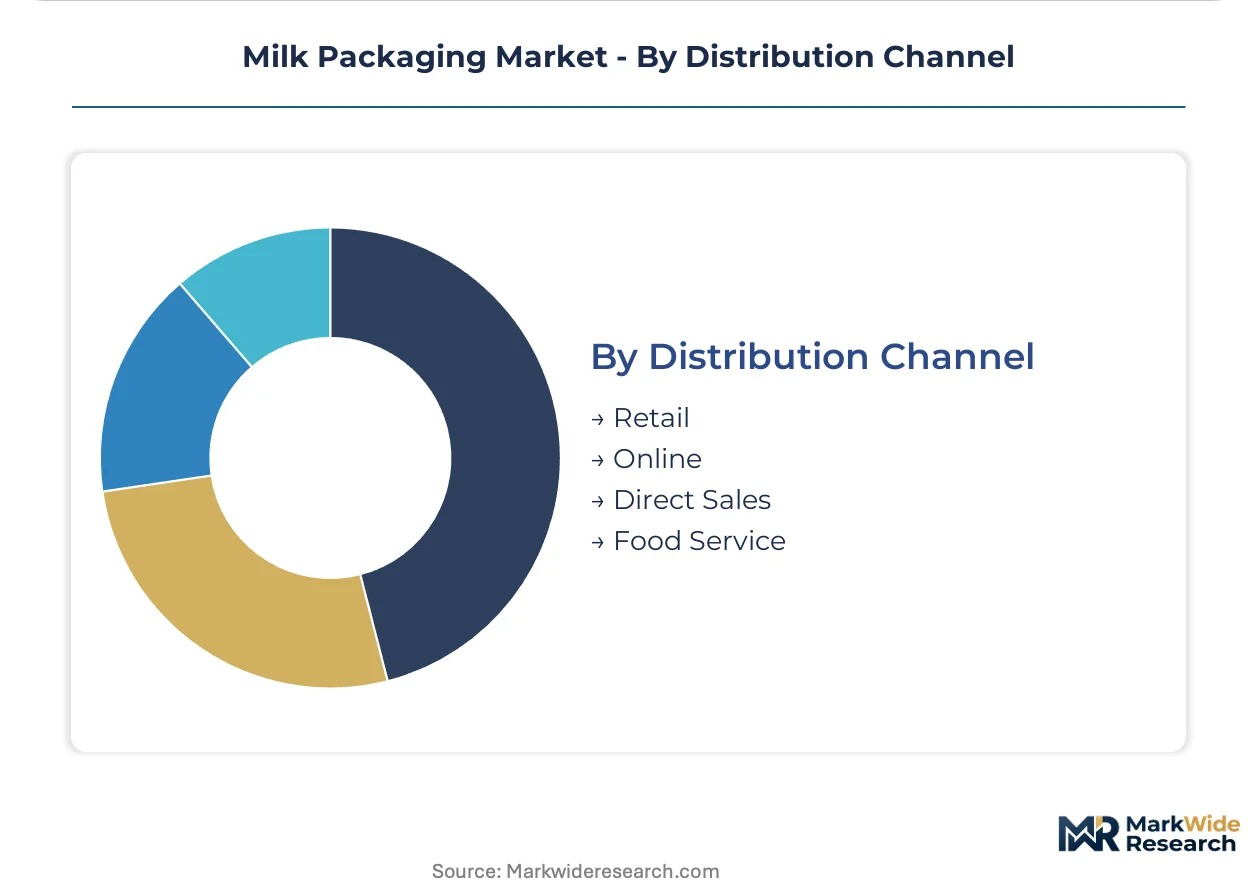
Distribution Channel:
Channel selection determines packaging format specifications, with food-service procurement consolidating around ambient stability and retail demanding shelf differentiation.
- Retail:Supermarket chains in France and Britain require OPRL or How2Recycle labels, disqualifying unmarked SKUs and concentrating procurement with certified converters.
- Online:E-commerce platforms specify custom-format pouches with damage-resistant secondary packaging for last-mile delivery in tier-one Chinese cities.
- Direct Sales:Subscription dairy services in urban India are piloting temperature-indicating smart packaging that signals spoilage risk to consumers.
- Food Service:Institutional channels in Brazil and India standardize aseptic carton procurement for ambient milk distribution in school feeding programs.
Retail commands the majority of packaging volume; food service is climbing the fastest as UHT adoption eliminates cold-chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the most significant demand-side momentum as organized dairy retail and cold-chain investments reshape procurement patterns across institutional and consumer channels.
India
School feeding programs and urban subscription services drive aseptic carton and smart packaging demand. BIS certification requirements for food-grade plastics favor larger converters with testing infrastructure. Maharashtra and Gujarat host the densest converter clusters, where temperature-indicating packaging pilots signal spoilage risk to consumers.
Germany
Deposit-return systems sustain surface-treated glass bottle circulation in premium organic segments. The EU's Packaging and Packaging Waste Regulation mandates 70% recyclability thresholds by 2030, compressing material transition timelines. Bavaria anchors fiber-polymer separation R&D, with pilot facilities processing post-consumer cartons into pulp feedstock.
United States
Bulk institutional procurement for school and hospital feeding programs dominates HDPE container demand. FDA food-contact substance notifications for polymer migration limits constrain recycled feedstock adoption. The Midwest corridor houses the principal blow-molding capacity serving North American dairy cooperatives.
Brazil
Food-service channels standardize aseptic carton procurement to eliminate cold-chain dependency in ambient milk distribution. ANVISA governs food-contact safety standards for imported packaging materials. São Paulo-state dairy processors concentrate procurement authority for flavored milk SKU proliferation in PET formats.
China
E-commerce subscription platforms specify custom-format pouch packaging with ergonomic handles for last-mile delivery in tier-one cities. SAMR enforces GB standards for food-contact materials. The Yangtze River Delta hosts the fastest-growing converter capacity for protein-fortified variant packaging.
Milk Packaging Market Vendor Landscape
Capacity expansion dominates the current landscape as converters accelerate fiber-based barrier coating investments ahead of regulatory deadlines. The vendor base stratifies into three tiers: multinational integrated packaging groups with aseptic filling line partnerships, regional paperboard specialists qualifying aluminum-free structures, and commodity resin converters serving institutional bulk channels. Strategic archetypes include heritage aseptic technology licensors, European sustainability-first converters, and Asian scale-driven fabricators. M&A activity and geographic licensing agreements represent the dominant competitive moves.
Within the heritage technology tier, Tetra Pak International S.A. and SIG Combibloc Group AG exemplify aseptic carton licensors defending premium positions through extended-shelf-life segment specialization. Amcor plc occupies a position among multi-layer structure specialists addressing flavored milk clarity requirements. These three anchors illustrate the competitive tension between fiber-based barrier innovation and plastic clarity optimization across diverging regulatory environments.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| SIG Combibloc Group AG |
| Ball Corporation |
| Amcor plc |
| Elopak AS |
| Nippon Paper Industries Co. Ltd. |
| Crown Holdings Inc. |
| Nampak |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
EU retailer sustainability scorecards mandating OPRL recyclability labeling are forcing converters to qualify fiber-polymer separation technologies ahead of PPWR deadlines, compressing margins on aluminum-free barrier R&D while elevating pricing power for certified suppliers with in-house testing infrastructure.
Pricing Analysis
Commodity bulk contracts for HDPE institutional containers trade on razor-thin margins against long-term fixed-price agreements, while aseptic carton formats with REACH-compliant polyethylene-free coatings command premium positioning through retailer sustainability certification tiers. Price differentiation separates aluminum-free fiber structures from metallized legacy formats, with Brazilian food-service procurement showing lowest sensitivity due to cold-chain elimination value, and North American school feeding programs exhibiting highest price elasticity on resin cost pass-through.
Supply Chain Analysis
Converter engineering talent shortages in Maharashtra, Gujarat, and Bavaria are constraining fiber-polymer separation pilot scale-up, forcing Tetra Pak and SIG to anchor R&D recruitment in Swiss and Swedish technical clusters. Raw material flows draw from Nordic pulp feedstock, Middle Eastern ethylene derivatives, and Indian BIS-certified resin grades, with aluminum foil barrier dependence creating single-source vulnerability under PPWR recyclability thresholds. Distribution feeds through dairy processor direct procurement in Europe and organized retail consolidation in Indian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum-free barrier coating commercialization timelines represent the binding capacity constraint, with pilot-to-scale gaps propping pricing premiums for qualified converters through the projection horizon.
For Market Incumbents: Extend aseptic filling line partnerships into Indian organized retail corridors before regional paperboard specialists secure BIS certification advantages. Accelerate fiber-polymer separation R&D hiring in Bavaria and Sweden to defend margin position against SIG's Swiss pilot scale-up. Channel control through direct dairy processor relationships remains the priority lever against emerging PLA barrier entrants. For New Entrants and Emerging Players: E-commerce subscription platforms in tier-one Chinese cities offer the most penetrable white-space, with ergonomic pouch handle specifications bypassing legacy converter minimum-order-quantity advantages. Target temperature-indicating smart packaging pilots in Maharashtra and Gujarat through direct-to-subscription channel partnerships with urban Indian dairy services. A go-to-market angle anchored on BIS compostability standard pre-qualification positions early movers for municipal waste policy alignment. For Investors and Strategic Acquirers: Re-rating potential sits with European sustainability-first converters given REACH-compliant barrier coating qualification timelines and retailer panel consolidation around OPRL certification. Long-term viability over a five-to-ten year window favors regional paperboard specialists with aluminum-free structures pre-qualified for commercialization. The signal to watch is FDA food-contact substance notification queue lengths for novel barrier coatings, with eighteen-month backlogs indicating inflection timing for export-oriented supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum-Free Barrier Qualification | REACH-compliant polyethylene-free structures unlock premium shelf access under French and British retailer scorecards. |
| Fiber-Polymer Separation R&D Scale-Up | Bavarian pilot facilities processing post-consumer cartons into pulp feedstock anchor EU PPWR compliance execution. |
| Direct-to-Subscription Channel Partnership | Urban Indian dairy services piloting temperature-indicating smart packaging bypass traditional retail shelf constraints. |
| BIS Certification Infrastructure Investment | Testing capabilities for food-grade plastics favor larger converters under India's Plastic Waste Management Rules. |
| Ergonomic Pouch Format Development | Custom specifications with integrated spout fitments capture Chinese e-commerce last-mile delivery requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving aseptic filling line engineers, dairy processor procurement directors, converter sustainability leads, and retailer category managers. FDA food-contact substance notification databases, EU PPWR implementation guidance, Indian BIS certification registries, and Chinese SAMR GB standards provided segmentation validation. Bottom-up capacity assessments triangulated against top-down spending pattern analysis across ambient and chilled distribution channels.
Granularity extended to packaging type, material grade, closure configuration, and distribution channel across the analysis window, with separate modeling for UHT institutional procurement versus refrigerated retail formats. CAGRs derived from installed filling line capacity expansion schedules, cold-chain infrastructure investment trajectories, and regulatory compliance timeline assumptions. Forecast inputs incorporated aluminum-free barrier commercialization readiness, rPET feedstock scarcity constraints, and fiber-polymer separation technology maturation curves.
The model holds under sustained EU PPWR implementation and Indian organized retail expansion; deviation in FDA notification queue lengths, ethylene feedstock volatility, or BIS compostability standard acceleration would shift converter capital allocation priorities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Europe Dairy Packaging Market
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Dairy Containers Market
Dairy Packaging
Latin America Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Dairy Packaging Market