
 North America Dairy Packaging Market | 2026-2036
North America Dairy Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Packaging Market Analytics
Barrier-coated paperboard technology is reconfiguring how extended-shelf-life dairy products reach retail shelves without refrigeration dependency. Amcor Limited leverages multilayer extrusion expertise to dominate high-barrier lidding films for Greek yogurt cups. Tetra Pak International SA anchors aseptic carton supply chains across major Midwest dairy cooperatives. Berry Global Group Inc specializes in injection-stretch blow-molded HDPE bottles for flavored milk distribution networks.
North America dairy packaging encompasses engineered containment systems designed to preserve microbiological stability, nutritional integrity, and sensory quality of fluid milk, cultured products, and cheese from processing through consumption. Aseptic cartons incorporate aluminum oxide or ethylene vinyl alcohol barrier layers measuring 5-12 microns to achieve 90-180 day ambient shelf life. Carton formats capture the largest volume share due to their compatibility with high-speed filling lines and square-cube shipping efficiency. Flexible pouches represent the fastest-expanding segment as processors target single-serve portable consumption occasions in convenience channels. Glass bottles retain premium positioning within direct-to-home delivery and specialty retail segments where material authenticity commands price premiums.
FDA food-contact substance notifications govern migration limits for adhesives and coatings in dairy packaging under 21 CFR 170-189. USDA organic certification requirements restrict packaging material origins and prohibit certain synthetic barrier chemistries for seal-bearing products. State-level extended producer responsibility frameworks in California and Oregon are forcing redesigns toward mono-material recyclability. Stakeholders must monitor how FDA bioengineered food disclosure rules intersect with dairy labeling to anticipate downstream packaging graphics requirements.
Market Dynamics
Barrier-coated paperboard is compressing aluminum-oxide dependency in extended-shelf-life formats as FDA food-contact notification timelines tighten material substitution windows across Upper Midwest processing corridors.
Growth Catalysts
- USDA Organic Seal Standards:Tightening compliance timelines for seal-bearing products are accelerating demand for certified barrier materials in Wisconsin and Minnesota cooperatives.
- Single-Serve Flexible Pouches:Portable consumption occasions in convenience channels are pulling processors toward lightweight, high-speed fillable formats.
- California EPR Frameworks:Extended producer responsibility mandates are forcing redesigns toward mono-material recyclability ahead of other states.
Market Restraints
- Ethylene Vinyl Alcohol Resin Concentration:Barrier-layer feedstock supply clusters among three global chemical suppliers, exposing processors to input cost volatility.
- Aluminum Oxide Technical Limitations:Current deposition thicknesses of 5-12 microns create oxygen transmission rate floors that constrain ultra-long ambient shelf life targets.
- FDA Notification Friction:Food-contact substance review timelines for novel bio-based coatings extend commercialization cycles by 18-24 months.
Strategic Opportunities
- Underpenetrated Direct-to-Home Delivery:Glass bottle authenticity positioning remains underdeveloped in Texas and Florida metro corridors outside legacy Northeast networks.
- Plant-Based Dairy Convergence:Aseptic carton technology developed for fluid milk is migrating into oat and almond protein stabilization formats.
- Oregon EPR Tailwinds:State-level packaging redesign grants are subsidizing mono-material pilot lines for cooperative processors.
Industry Challenges
- Multilayer Extrusion Skill Scarcity:High-barrier lidding film production requires polymer rheology expertise concentrated among aging technician cohorts in Minnesota.
- Legacy Filling Line Integration:Square-cube carton formats face mechanical incompatibility with round-bottle infrastructure at smaller Wisconsin dairies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Packaging Market |
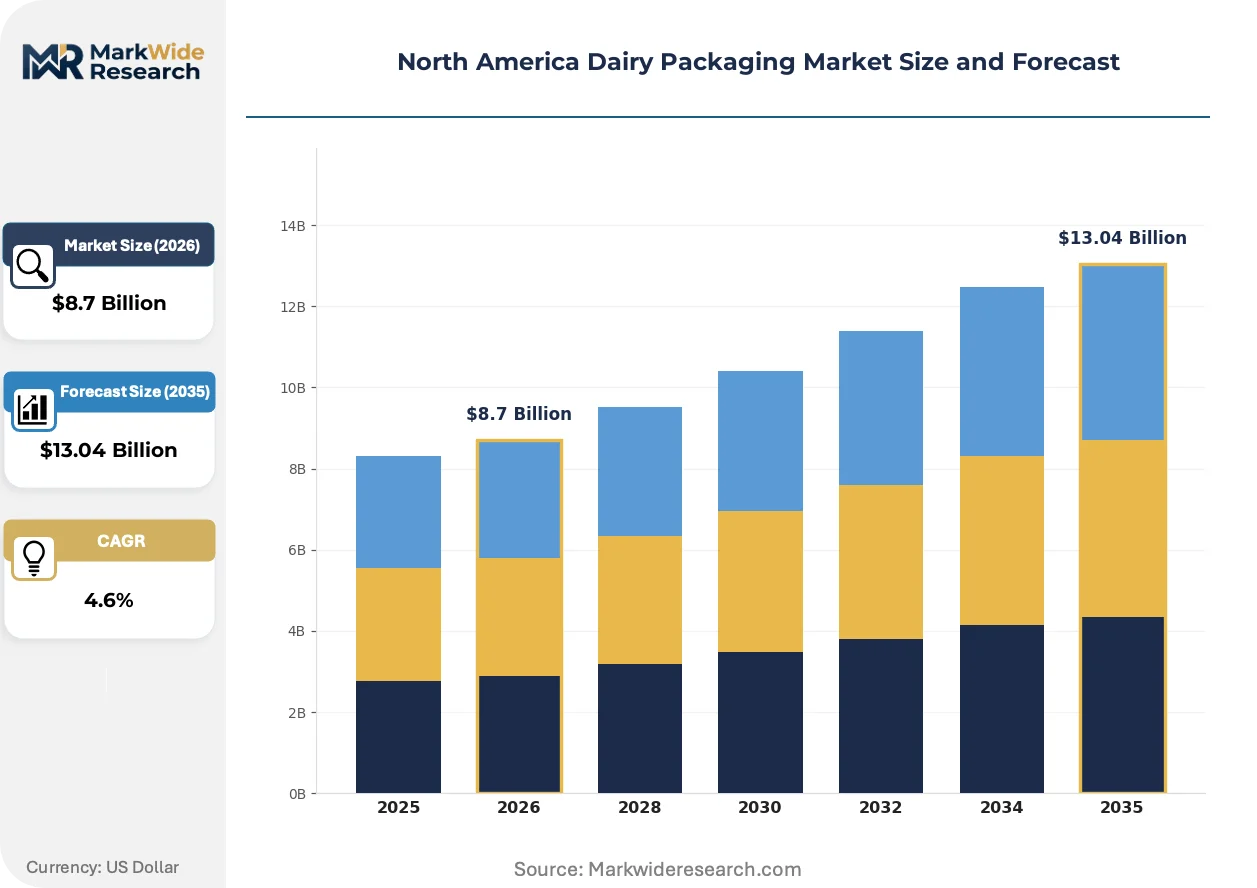
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartons, Bottles, Pouches, Tetra Packs Material: Plastic, Paper, Glass, Metal End User: Retail, Foodservice, E-commerce, Direct Sales Packaging Type: Flexible, Rigid, Bulk, Single-Serve |
| Companies Covered | Berry Global Group Inc, Amcor Limited, Huhtamaki Group, Tetra Pak International SA, Ball Corporation, Sealed Air Corporation, International Paper Company, Winpak Ltd, Saudi Basic Industries Corporation (SABIC), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Packaging Market Evolving Landscape
Material science and regulatory compliance are compressing format innovation cycles as processors balance shelf-life extension against recyclability mandates.
Aluminum oxide vapor deposition serves as the primary oxygen barrier in aseptic carton construction. Upper Midwest organic processors are adopting thinner 5-micron layers to reduce material intensity. The technology is migrating from conventional dairy into plant-based protein stabilization formats where thermal processing demands differ.
California's extended producer responsibility framework mandates post-consumer recycled content thresholds for rigid containers. Oregon and Washington are harmonizing labeling standards to reduce interstate compliance fragmentation. Fluid milk processors in the Pacific states are consolidating SKUs to simplify material certification documentation.
Single-serve pouch procurement is concentrating among convenience channel distributors seeking portion-controlled formats for grab-and-go dairy. Traditional gallon jug contracts are compressing as foodservice buyers reduce inventory holding costs. This pattern is most visible in Texas metropolitan corridors where convenience store density exceeds traditional grocery penetration.
North America Dairy Packaging Market Segmentation
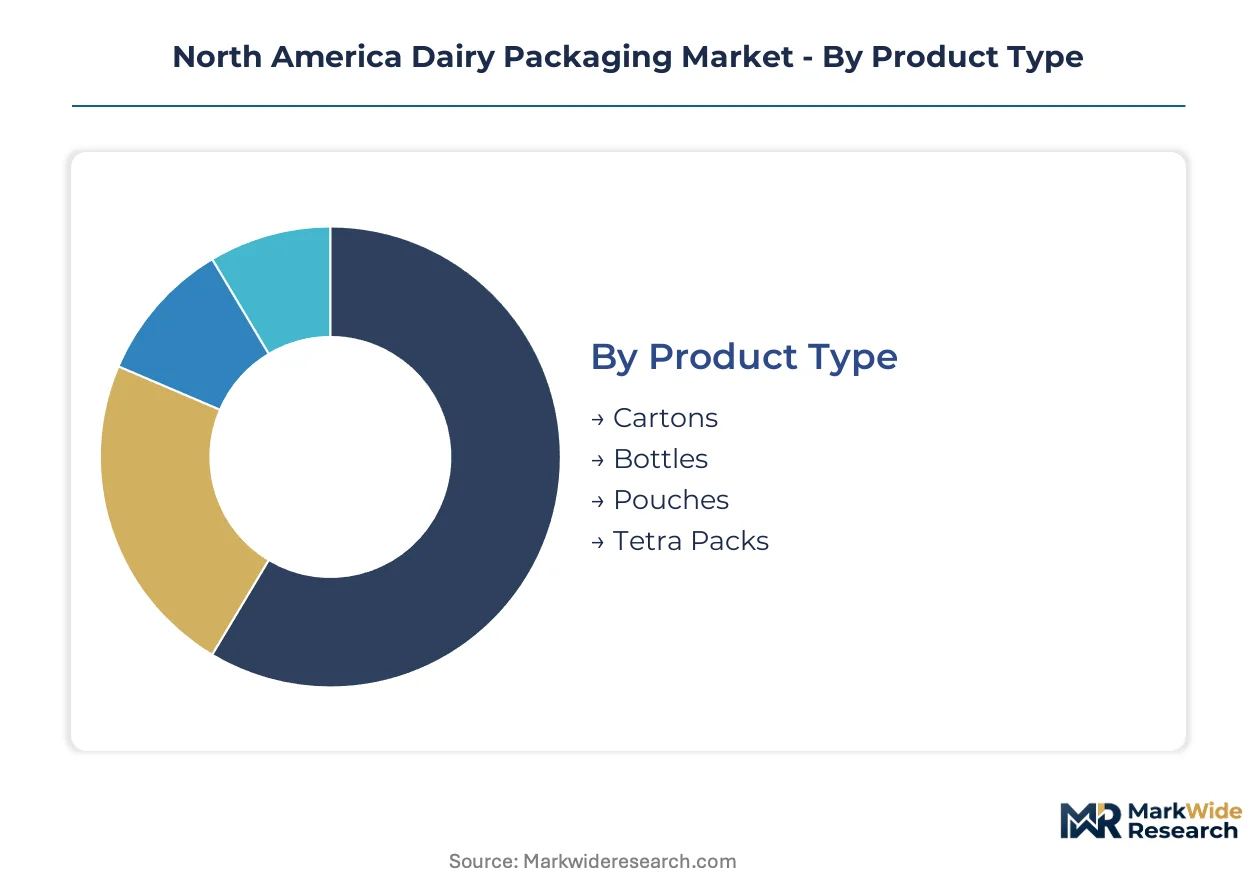
Packaging format decisions in North American dairy directly determine cold-chain requirements, shelf-life economics, and retail channel access. Segmentation reveals how processors align container engineering with specific consumption occasions and regulatory compliance burdens.
Product Type:
After-sales service intensity varies sharply across formats, with aseptic systems demanding technical support contracts that carton suppliers bundle into long-term supply agreements.
- Cartons:Multilayer paperboard constructions incorporate aluminum oxide or ethylene vinyl alcohol barriers measuring 5-12 microns. Wisconsin and Minnesota cooperatives dominate procurement for extended-shelf-life organic milk as USDA seal compliance tightens material substitution windows.
- Bottles:Injection-stretch blow-molded HDPE dominates flavored milk distribution networks, with square-cube shipping efficiency driving adoption among Upper Midwest processors seeking freight optimization.
- Pouches:Single-serve flexible formats target portable consumption in Texas convenience corridors where grab-and-go dairy occasions concentrate.
- Tetra Packs:Aseptic brick formats anchor ambient distribution for fluid milk and plant-based alternatives, with barrier migration into oat and almond protein stabilization.
By volume, cartons lead. By growth pace, pouches are expanding most quickly.
Material:
Cost tier stratification separates premium authentic positioning from mass-market functional containment, with material choice locking processors into specific recycling infrastructure dependencies.
- Plastic:HDPE and PET formats dominate gallon jug and flavored milk segments, though California EPR mandates are forcing redesigns toward mono-material recyclability and post-consumer recycled content thresholds.
- Paper:Barrier-coated paperboard is compressing aluminum-oxide dependency as FDA food-contact notification timelines accelerate material substitution across Upper Midwest processing corridors.
- Glass:Premium authenticity positioning retains direct-to-home delivery networks in legacy Northeast markets, with underpenetrated expansion potential in Texas and Florida metro corridors.
- Metal:Limited dairy application concentrates in specialty cheese and condensed milk formats where oxygen exclusion demands exceed flexible barrier capabilities.
Plastic commands volume leadership. Paper-based barriers are climbing the fastest as organic processors seek seal-compliant alternatives.
End User:
Customer type determines order cadence, with foodservice buyers compressing gallon jug contracts against convenience channel distributors consolidating single-serve pouch procurement.
- Retail:Traditional grocery and mass merchandiser channels favor square-cube carton efficiency and multi-pack configurations, with Pacific state processors consolidating SKUs to simplify material certification documentation.
- Foodservice:Institutional buyers reduce inventory holding costs through smaller, more frequent orders, pressuring traditional gallon jug contract structures most visible in Texas metropolitan corridors.
- E-commerce:Direct-to-consumer fulfillment demands damage-resistant formats with extended ambient stability, pulling aseptic technology into subscription dairy models.
- Direct Sales:Home delivery networks in Wisconsin and Minnesota retain glass bottle loyalty, with route density economics favoring localized processing over national distribution.
Retail dominates volume. E-commerce is gaining share fastest as subscription models proliferate.
Packaging Type:
Supply concentration in flexible film extrusion creates margin pressure distinct from rigid container conversion, with equipment specialization fragmenting vendor capabilities.
- Flexible:High-barrier lidding films for Greek yogurt cups require polymer rheology expertise concentrated among aging technician cohorts in Minnesota, creating capability scarcity.
- Rigid:Injection-molded and thermoformed containers face mechanical incompatibility challenges when square-cube carton formats encounter round-bottle infrastructure at smaller Wisconsin dairies.
- Bulk:Foodservice and ingredient supply chains favor intermediate bulk containers and bag-in-box formats for operational efficiency in high-volume manufacturing settings.
- Single-Serve:Portion-controlled formats concentrate procurement among convenience channel distributors seeking grab-and-go dairy solutions in Texas where convenience store density exceeds traditional grocery penetration.
Rigid formats lead by volume. Single-serve formats show the steepest expansion trajectory as portability demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice buyers and organic processors drive packaging procurement across North America, with regulatory divergence between US states and Canadian federal standards fragmenting compliance requirements. Cold-chain infrastructure density varies sharply, compressing format choices in southern corridors while enabling premium glass bottle networks in legacy northern markets.
United States
Upper Midwest dairy cooperatives in Wisconsin and Minnesota dominate extended-shelf-life organic milk processing, pulling aseptic carton orders as USDA organic seal standards tighten material compliance timelines. FDA food-contact notification requirements govern barrier-layer adhesives under 21 CFR 170-189. California and Oregon extended producer responsibility frameworks are forcing redesigns toward mono-material recyclability ahead of federal mandates.
Canada
Supply-managed dairy quotas concentrate processing in Ontario and Quebec, where bilingual labeling requirements and Health Canada food-contact regulations create distinct packaging specifications. Pacific Northwest cross-border supply chains integrate British Columbia processors with Washington state filling line technology. Toronto and Montreal anchor rigid HDPE bottle procurement for fluid milk distribution.
Mexico
Juarez and Monterrey processing corridors serve US export markets, leveraging maquiladora duty advantages for flexible pouch conversion. Mexican federal standards under COFEPRIS govern food-contact migration limits, with California-bound shipments requiring dual compliance documentation. Guadalajara specialty dairy clusters are adopting aseptic technology for shelf-stable cream formats targeting domestic convenience channels.
North America Dairy Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships, with consolidated material suppliers facing fragmented dairy processor customers. The structure splits between integrated packaging conglomerates owning resin-to-format supply chains and regional converters serving single-state cooperative networks. Three archetypes dominate: multinational barrier technology licensors, North American rigid container specialists, and flexible film extrusion regionalists. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships with organic certifiers to secure material approval pipelines.
Within the multinational technology tier, Tetra Pak International SA and Amcor Limited exemplify integrated barrier solution providers, while Berry Global Group Inc occupies a position among North American rigid format specialists. These anchors represent divergent strategic postures: aseptic system licensors with long-term service contracts versus injection-molded container suppliers optimizing freight economics for Upper Midwest dairy networks.
| Leading Market Players |
|---|
| Berry Global Group Inc |
| Amcor Limited |
| Huhtamaki Group |
| Tetra Pak International SA |
| Ball Corporation |
| Sealed Air Corporation |
| International Paper Company |
| Winpak Ltd |
| Saudi Basic Industries Corporation (SABIC) |
| Others |
Value Network & Pricing Analysis
Ethylene vinyl alcohol resin concentration among three global chemical suppliers in Germany, Japan, and the United States feeds directly into margin compression at Upper Midwest dairy processors seeking barrier-layer feedstock security. Cost-plus contracts indexed to ethylene spot pricing dominate procurement, with Wisconsin and Minnesota cooperatives absorbing volatility through long-term offtake agreements that bundle technical service support.
Pricing Analysis
Cost-plus contracts indexed to ethylene monomer futures govern barrier film procurement across Upper Midwest processing corridors. Pricing stratifies across USDA-certified organic, conventional extended-shelf-life, and commodity fluid milk tiers, with organic certification commanding material substitution premiums. Cost compression in conventional gallon jug segments is intensifying because foodservice buyers consolidate orders and press for volume discounts. Convenience channel distributors show least price sensitivity for single-serve pouch formats where portability commands premium positioning.
Supply Chain Analysis
Export-control regimes on aluminum oxide vapor deposition equipment limit technology transfer to Mexican and Canadian conversion facilities, constraining regional capacity expansion. Barrier-layer feedstock draws from German, Japanese, and US petrochemical complexes, with ethylene vinyl alcohol and adhesive resin supply anchoring in these three manufacturing clusters. Single-source vulnerability concentrates in specialized multilayer extrusion equipment where Minnesota-based technician expertise gates production scale-up. Distribution runs through dairy cooperative networks that consolidate freight loads for square-cube carton efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as aseptic filling line interoperability becomes the decisive infrastructure investment across North American dairy packaging. Tetra Pak's long-term service contract model exemplifies how equipment-financing ecosystems lock in processor loyalty and marginalize standalone format suppliers.
For Market Incumbents: Build certification moats by securing USDA organic material pre-approvals ahead of tightening compliance timelines. Tetra Pak International SA and Amcor Limited should deepen backward integration into bio-based barrier resin compounding to capture margin pools currently held by petrochemical suppliers. Berry Global Group Inc faces margin pressure from California EPR mandates and must invest in mono-material pilot lines to defend position in HDPE bottle segments. For New Entrants and Emerging Players: Pursue underpenetrated direct-to-home glass bottle networks in Texas and Florida metro corridors where route density economics favor localized processing over national distribution. The most penetrable white-space sits in plant-based dairy aseptic applications where oat and almond protein stabilization demands differ from conventional milk thermal processing. A go-to-market angle anchored in Oregon EPR redesign grants offers subsidized entry for cooperative processor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible film extrusion specialists in Minnesota where polymer rheology expertise concentrates among aging technician cohorts. Five-to-ten year viability hinges on successful workforce transition and automation investment. Acquisition targets should display captive relationships with Upper Midwest organic cooperatives. The signal to watch is FDA food-contact notification approval velocity for novel bio-based coatings, which would compress commercialization cycles and revalue material substitution pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Compounding | Captures margin pools from German and Japanese petrochemical suppliers while securing USDA organic compliance pathways. |
| Mono-Material Pilot Line Investment | Addresses California and Oregon EPR mandates ahead of federal standardization, locking in cooperative processor contracts. |
| Direct-to-Home Glass Bottle Network Expansion | Exploits underpenetrated Texas and Florida corridors where authenticity positioning commands price premiums over mass retail. |
| Plant-Based Dairy Aseptic Technology Migration | Extends existing fluid milk barrier expertise into oat and almond protein stabilization formats with distinct thermal demands. |
| Long-Term Service Contract Bundling | Replicates Tetra Pak's equipment-financing ecosystem model to lock in Upper Midwest cooperative loyalty and exclude standalone competitors. |
Research Methodology
A spread of perspectives from dairy cooperative procurement directors, barrier film plant managers, FDA regulatory affairs specialists, and retail category buyers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through USDA organic certification databases, FDA food-contact substance notification filings, and state-level EPR regulatory text. Customs records tracking ethylene vinyl alcohol resin imports and dairy packaging equipment trade flows provided upstream supply chain calibration. Bottom-up volume builds from processor filling line counts and top-down value estimates from cooperative revenue disclosures were triangulated to establish market sizing.
Demand-supply balance framing anchored the projection methodology, with consumption growth modeled against barrier material production capacity across the analysis window. Segmentation dimensions included packaging format, material substrate, end-user channel, and geographic processing cluster. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporated FDA notification timeline assumptions, California EPR implementation pace, and organic milk processing capacity expansion plans.
Macroeconomic conditions sit as an overlay; deviation in ethylene feedstock pricing, freight rate volatility, or dairy commodity price cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance timelines and technology adoption elasticities. Material shifts in FDA bioengineered food disclosure rulemaking or federal EPR preemption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Latin America Dairy Packaging Market
Dairy Packaging
Dairy Containers Market
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Europe Dairy Packaging Market