
 Milk Powder Packaging Machines Market | 2026-2036
Milk Powder Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Powder Packaging Machines Market Foresight
Pharma-grade aseptic specification tiers is unwinding across the milk powder packaging machines sector as infant formula exporters face tightening destination-market hygiene mandates. Syntegon leverages its integrated isolator technology to capture premium dairy OEM contracts in Europe and Asia. Tetra Pak anchors its position through upstream control over carton-aseptic filling system combinations. GEA Group differentiates via specialized powder handling engineering for high-fat and hydrolyzed formula variants.
Milk powder packaging machines constitute electromechanical systems designed to meter, fill, seal, and sometimes gas-flush dried dairy products into primary containers at throughputs ranging from 30 to 600 units per minute, with critical tolerances on fill accuracy and residual oxygen levels to prevent lipid oxidation and caking. Automatic machine configurations command the dominant installed base due to labor cost pressures and lot-traceability requirements, while auger filler architectures lead in fine-powder applications where screw geometry determines flow consistency and dose precision. Flexible bag formats absorb the largest share of new machine orders from dairy manufacturers seeking lightweight, shelf-efficient export packaging.
FDA infant formula facility registration rules and EU MDR-adjacent hygiene standards for food-contact machinery shape equipment validation protocols and limit market access for non-compliant builders. China's NMPA and SAMR enforce GB standard conformity on imported filling lines, adding certification layers for foreign suppliers. Stakeholders must monitor evolving dual carbon goals in major manufacturing geographies, as energy consumption metrics for clean-in-place cycles become embedded in procurement scoring.
Market Dynamics
Pharma-grade aseptic specification tiers are unwinding across the milk powder packaging machines sector as infant formula exporters face tightening destination-market hygiene mandates. Syntegon leverages its integrated isolator technology to capture premium dairy OEM contracts in Europe and Asia. Tetra Pak anchors its position through upstream control over carton-aseptic filling system combinations. GEA Group differentiates via specialized powder handling engineering for high-fat and hydrolyzed formula variants.
Growth Catalysts
- ASEAN Export Standards:Infant formula manufacturers in Vietnam, Indonesia, and Thailand are expanding automated filling capacity to meet stringent EU and China import hygiene requirements. NMPA and SAMR GB standard conformity pressures are accelerating machine replacement cycles.
- Aseptic Filling Technology:Migration from manual to fully automatic systems is concentrating demand for isolator-integrated lines capable of maintaining sub-1 CFU/m³ environmental control during powder transfer operations.
- Dual Carbon Goals:China's MEE and EU Green Deal energy consumption metrics are embedding clean-in-place cycle efficiency into procurement scoring, favoring next-generation machines with heat recovery systems.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L and 304 stainless steel price swings compress margins for European and Asian machine builders already facing extended validation timelines.
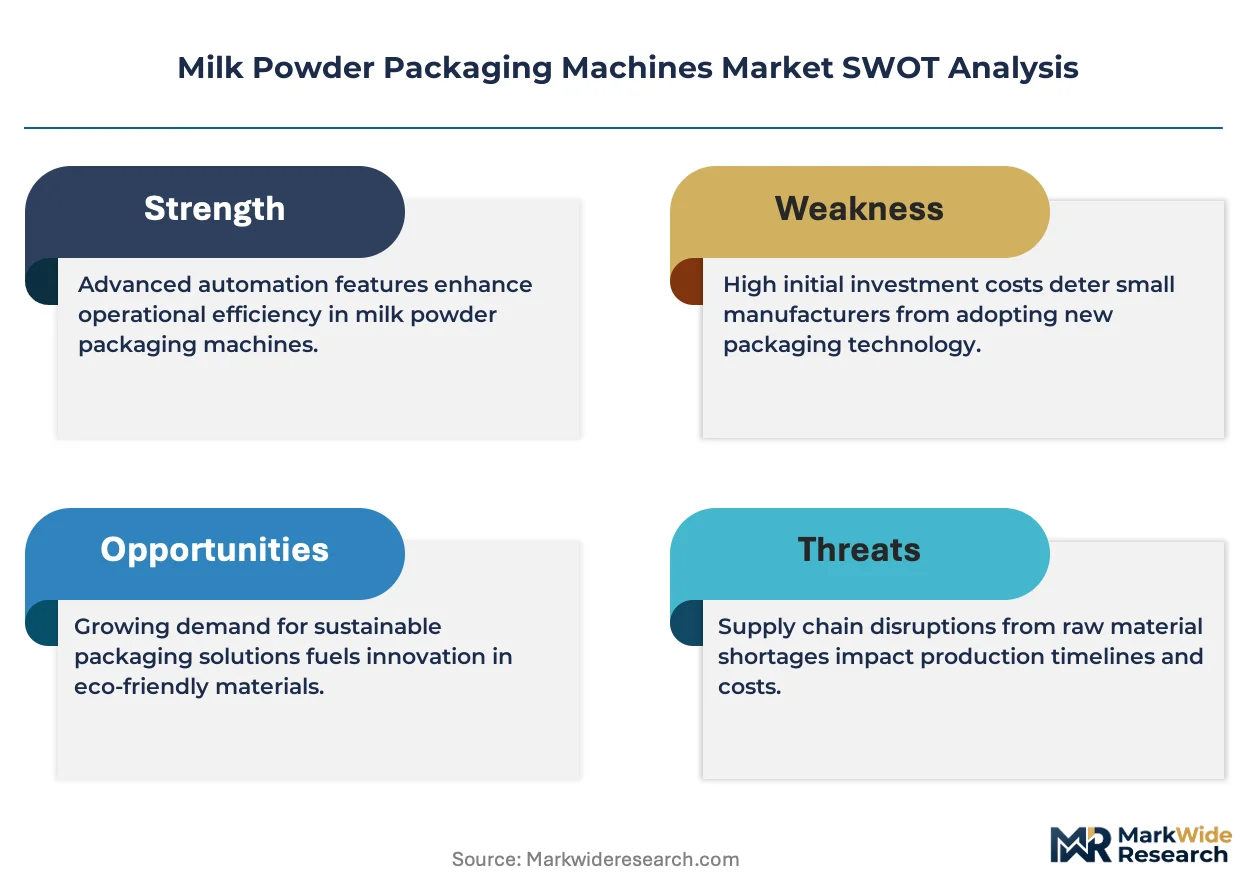
- Validation Protocol Complexity:FDA infant formula facility registration rules and EU MDR-adjacent hygiene standards for food-contact machinery create multi-year certification barriers that limit market access for non-compliant builders.
- Used Equipment Arbitrage:Refurbished European and Japanese machines flood Southeast Asian secondary markets, delaying new-build orders from price-sensitive dairy cooperatives.
Strategic Opportunities
- India PLI Scheme Alignment:Dairy processing infrastructure investments under India's production-linked incentive scheme create first-mover advantages for aseptic filling line suppliers willing to localize assembly.
- Near-Infrared Spectroscopy Integration:Real-time moisture and fat content verification during filling is decomposing traditional offline QC workflows, enabling inline release protocols that reduce warehouse holding costs.
- Flexible Pouch Formats:Stand-up and spouted bag-in-box configurations are capturing share from rigid cans in premium adult nutrition segments, requiring retrofittable forming modules on existing lines.
Industry Challenges
- Mechatronics Talent Scarcity:Servo-driven auger synchronization and isolator robotics programming require specialized engineers that machine builders struggle to recruit in Vietnam and Indonesia expansion markets.
- Legacy MES Integration:Brownfield dairy plants running 1990s-era SCADA architectures face prohibitive retrofit costs when connecting new filling lines to centralized lot-traceability systems mandated by EU and Chinese regulators.
- IP Licensing Friction:Proprietary powder dosing algorithms and gas-flush valve designs trigger cross-border patent disputes that delay equipment shipments to contested markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Powder Packaging Machines Market |
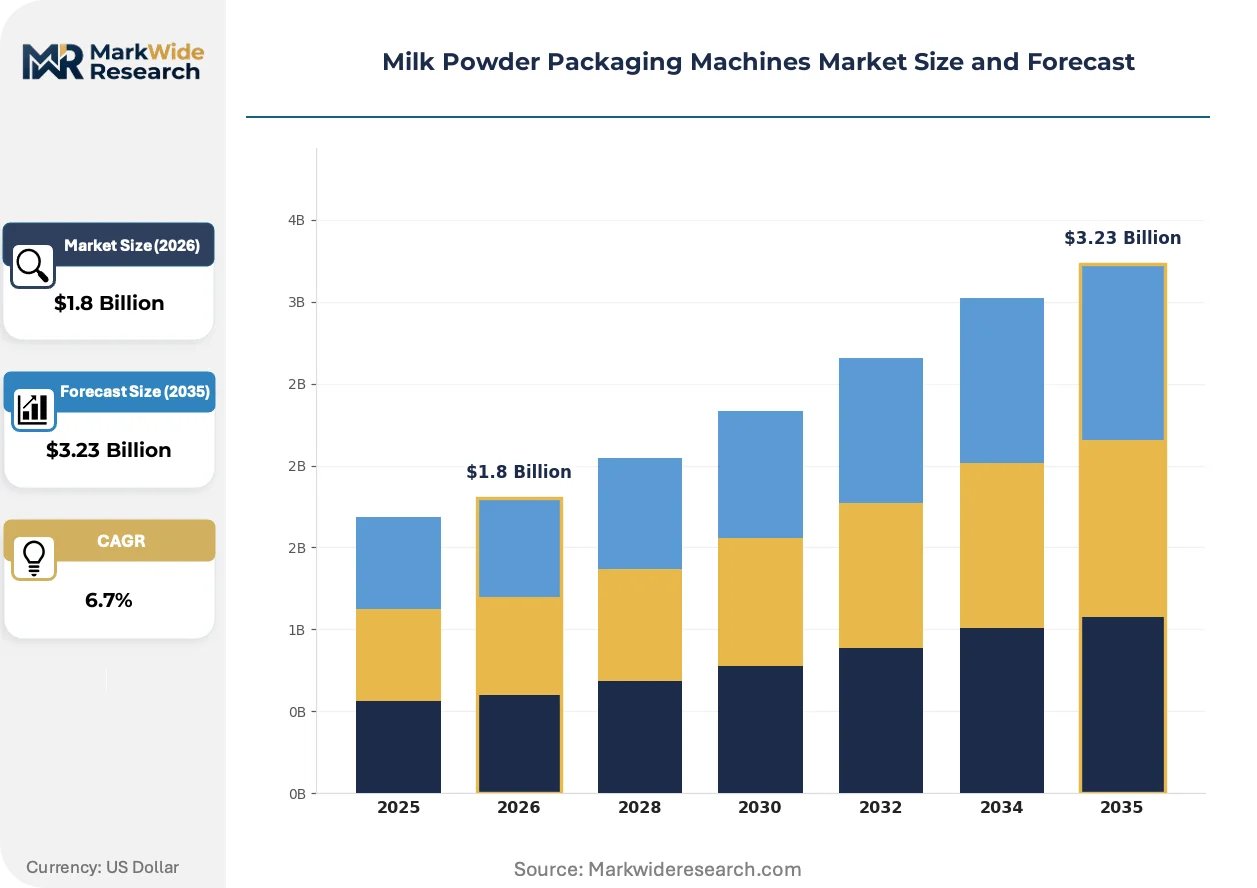
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
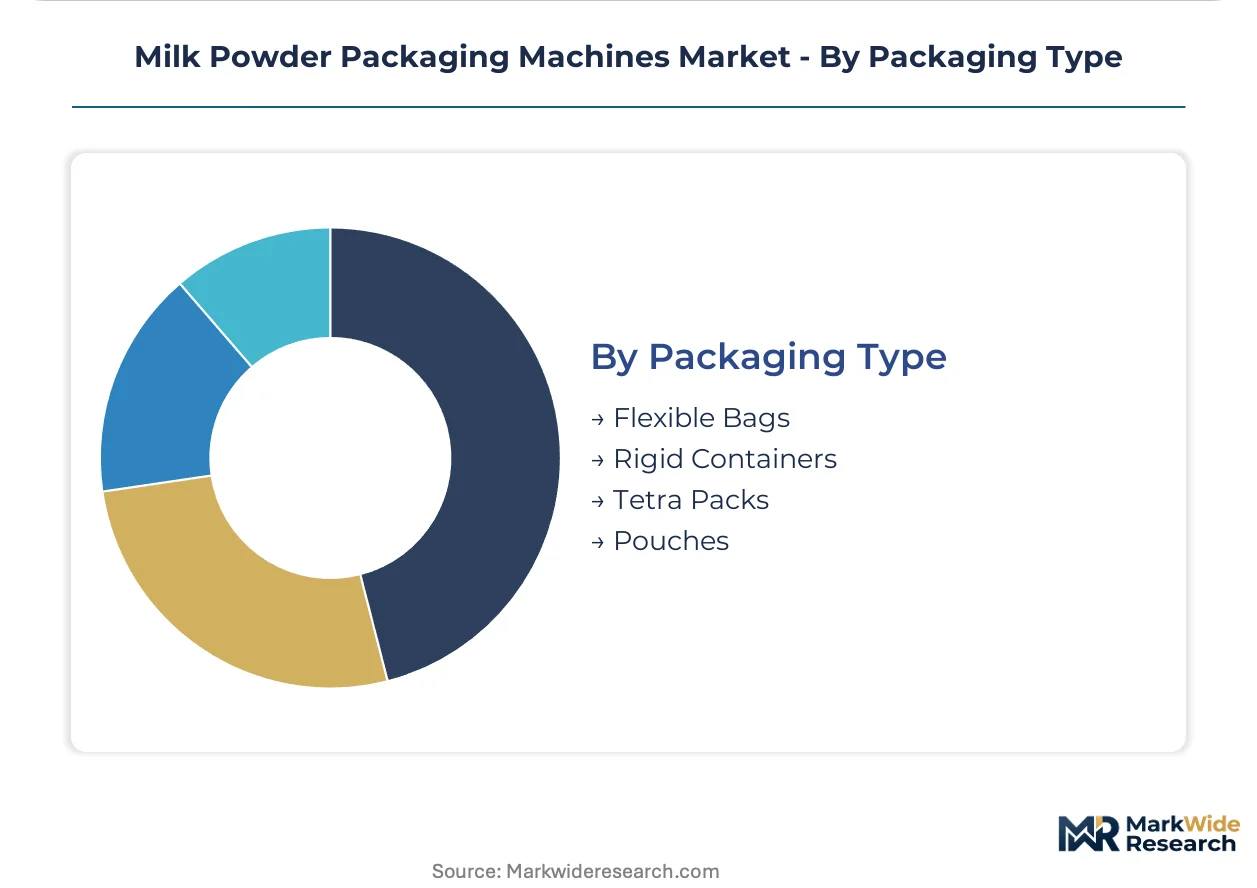
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Fully Automatic Machine Type: Vertical Form Fill Seal, Horizontal Form Fill Seal, Sachet Fill Seal, Auger Filler End User: Dairy Manufacturers, Food Processors, Packaged Food Companies, Co-Packers Packaging Type: Flexible Bags, Rigid Containers, Tetra Packs, Pouches |
| Companies Covered | Syntegon, Tetra Pak, Landpack, HAVER & BOECKER, Shanghai Boevan Packaging Machinery, All-Fill Inc., IMA Group, OPTIMA packaging group, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Powder Packaging Machines Market Shifts & Advancements
Active magnetic bearing technology and AI-driven predictive maintenance modules are reshaping uptime economics for high-speed milk powder filling operations. Equipment buyers now prioritize total cost of ownership metrics over capital expenditure minimization.
Electromagnetic flow meters combined with Coriolis mass flow controllers are decomposing traditional gravimetric filling architectures in high-value infant formula applications. Swiss and Dutch dairy cooperatives have adopted these systems for hydrolyzed protein variants where dose precision below 0.3% CV is mandatory. The technology is decomposing the historical trade-off between throughput and accuracy, enabling 400+ units per minute on 400-gram can formats previously limited to 250 units.
EU MDR-adjacent hygiene standards for food-contact machinery are forcing redesigns of bearing housings and seal geometries to eliminate pathogen harborage points. German and Italian OEMs have re-engineered auger drive assemblies to achieve EHEDG-compliant cleanability without disassembly. The regulatory pressure is compressing design cycles for legacy platforms that cannot achieve the new surface finish and drainage requirements.
Service contract unbundling is fragmenting the traditional full-service lease model that dominated Southeast Asian dairy investments. Vietnamese and Indonesian processors now procure machines and aftermarket support separately, comparing hourly technician rates across regional service networks. The disaggregation is visible most acutely in Ho Chi Minh City and Jakarta, where third-party validation specialists have captured calibration and certification workflows previously captive to OEM service divisions.
Milk Powder Packaging Machines Market Segmentation
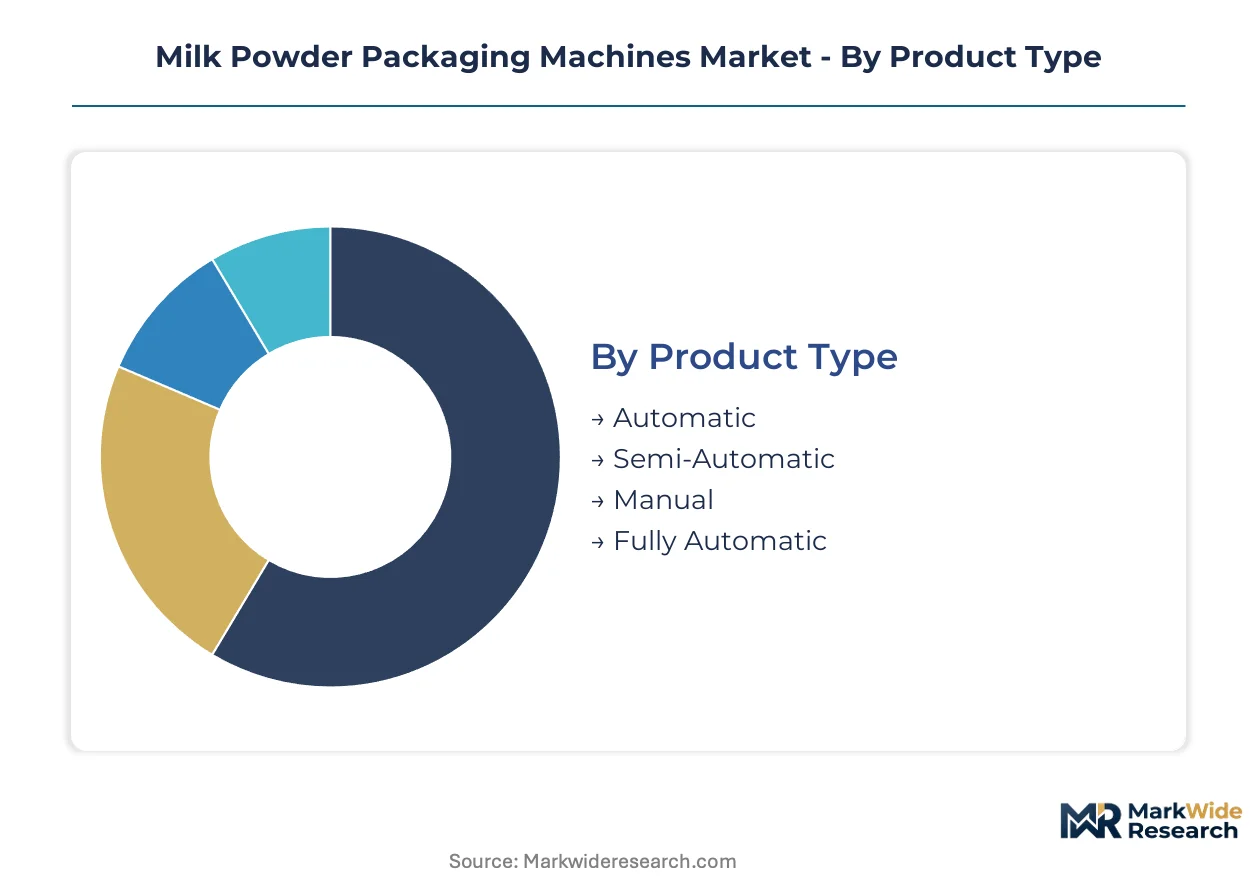
Milk powder packaging machines segment across automation levels, mechanical architectures, customer verticals, and container formats. Each dimension carries distinct technical specifications, validation requirements, and procurement economics that shape vendor positioning and buyer decision criteria.
Product Type:
Substitution pressure from refurbished European equipment and manual labor arbitrage concentrates most intensely in the lowest-automation tiers, while pharma-grade aseptic mandates protect premium automatic configurations from direct replacement.
- Automatic:Servo-driven auger synchronization and isolator-integrated designs dominate infant formula installations in Vietnam and Indonesia. NMPA and SAMR GB standard conformity requirements accelerate replacement of legacy semi-automatic lines with validated automatic systems featuring sub-1 CFU/m³ environmental control.
- Fully Automatic:Complete isolator enclosures with robotic powder transfer and inline NIR spectroscopy command premium positioning for hydrolyzed protein variants. Swiss and Dutch dairy cooperatives specify these configurations where dose precision below 0.3% CV is mandatory for high-value exports.
- Semi-Automatic:Operator-assisted filling with partial mechanization persists in Indian dairy cooperatives under PLI scheme infrastructure investments where capital constraints delay full automation.
- Manual:Hand-filling stations with basic volumetric scoops survive only in artisanal cheese powder operations and micro-scale specialty blenders serving local markets.
Automatic configurations anchor the volume base while fully automatic systems gain share at the steepest rate.
Machine Type:
Cost tier stratification separates high-throughput rotary architectures from compact linear systems, with mid-range vertical platforms capturing the broadest installed base across emerging dairy processing geographies.
- Auger Filler:Screw-based powder dosing with precision servo control achieves fill accuracy within ±0.5% for fine hydrolyzed formulas. GEA Group specializes in high-fat variant handling through proprietary screw geometry that prevents lipid separation during transfer operations.
- Vertical Form Fill Seal:Roll-fed film conversion with integrated gas flushing dominates flexible bag production for ASEAN export markets. Tetra Pak leverages upstream carton supply control to bundle aseptic filling with primary packaging specifications.
- Horizontal Form Fill Seal:Side-seal configurations accommodate rigid tray formats for premium adult nutrition segments requiring shelf-efficient retail presentation.
- Sachet Fill Seal:Compact single-dose units serve travel-size and sample markets with lower capital thresholds but reduced throughput economics.
Auger filler platforms anchor the volume base while vertical form fill seal systems gain share at the steepest rate.
End User:
Application-driven specification divergence separates infant formula manufacturers facing destination-market hygiene mandates from commodity dairy processors optimizing for throughput economics.
- Dairy Manufacturers:Integrated powder processing and packaging operations in Thailand and Vietnam drive demand for isolator-integrated lines with EHEDG-compliant cleanability. FDA infant formula facility registration rules shape validation protocols for export-oriented installations.
- Packaged Food Companies:Multi-product facilities require quick-changeover architectures with recipe-driven servo parameters for switching between whole milk, skim, and specialty protein powders.
- Food Processors:Ingredient supply operations for bakery and confectionery applications prioritize throughput over aseptic specification, accepting standard 316L stainless steel construction without isolator enclosures.
- Co-Packers:Toll manufacturing operations in Ho Chi Minh City and Jakarta favor modular machines with retrofittable forming modules to accommodate shifting customer packaging format requirements.
Dairy manufacturers anchor the volume base while packaged food companies gain share at the steepest rate.
Packaging Type:
Customer type concentration in export-oriented dairy manufacturing elevates lightweight flexible formats over traditional rigid containers for new machine procurement.
- Flexible Bags:Multi-layer laminates with aluminum oxide barriers and integrated reseal features capture the largest share of new orders from ASEAN exporters seeking shelf-efficient shipping cube utilization. Stand-up and spouted bag-in-box configurations are displacing rigid cans in premium adult nutrition segments.
- Pouches:Spouted and fitment-equipped designs for single-serve and on-consumption formats command machinery premiums for specialized forming and sealing stations.
- Rigid Containers:Metal cans with double-seamed closures and composite paperboard drums persist in institutional and bulk ingredient channels where stacking strength and moisture protection outweigh material cost considerations.
- Tetra Packs:Aseptic carton systems remain captive to Tetra Pak's integrated filling-line packaging supply model, limiting independent machine builder participation.
Flexible bags anchor the volume base while pouches gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine builder capacity clusters in Germany, Italy, and Switzerland, with Asian demand concentrated in Vietnam, Indonesia, and Thailand. Export-oriented infant formula processing drives equipment specification divergence across regulatory jurisdictions.
Germany
EHEDG-compliant cleanability mandates from German food-contact machinery regulations reshape auger drive assembly designs. Syntegon leverages integrated isolator technology from its Waiblingen engineering base to capture premium dairy OEM contracts serving EU and Asian export markets. Stuttgart-region fabricators specialize in servo-driven powder dosing systems for high-value hydrolyzed formula variants.
China
NMPA and SAMR GB standard conformity pressures accelerate replacement of legacy filling lines in Yangtze River Delta dairy processing zones. Dual carbon goals from MEE embed clean-in-place cycle efficiency into procurement scoring for new installations. Shanghai and Jiangsu province manufacturers expand automated capacity to meet destination-market hygiene mandates for infant formula exports.
Vietnam
EU and China import requirements drive Ho Chi Minh City processors to adopt isolator-integrated lines with sub-1 CFU/m³ environmental control. Service contract unbundling fragments traditional full-service lease models as third-party validation specialists capture calibration workflows. Dong Nai province dairy cooperatives face delayed new-build orders from refurbished European equipment arbitrage in secondary markets.
Indonesia
Jakarta-based toll manufacturers favor modular machines with retrofittable forming modules to accommodate shifting packaging format requirements. Mechatronics talent scarcity for servo-driven auger synchronization complicates expansion plans for multinational machine builders. Central Java dairy infrastructure investments under national food security programs create demand for semi-automatic configurations where capital constraints delay full automation.
Switzerland
Swissmedic-adjacent hygiene standards for pharmaceutical-grade food processing equipment elevate specification tiers for domestic dairy cooperatives. Swiss and Dutch infant formula exporters specify fully automatic configurations where dose precision below 0.3% CV is mandatory. Zurich-region engineering clusters specialize in Coriolis mass flow controllers that decompose traditional gravimetric filling architectures.
Milk Powder Packaging Machines Market Competitive Landscape
Concentration sits with diversified packaging machinery conglomerates and specialized powder handling engineering firms. German and Swiss OEMs anchor premium tiers through isolator-integrated system integration, while Chinese and Southeast Asian fabricators compete on modular platform economics. Strategic archetypes separate integrated solution providers from component specialists and regional assembly operators. Competitive moves concentrate on technology licensing for aseptic filling modules and backward integration into precision dosing component manufacturing.
Among European diversified machinery groups, GEA Group exemplifies specialized powder handling engineering for high-fat and hydrolyzed formula variants. Syntegon occupies a position representing integrated isolator technology capture in premium dairy OEM contracting. Tetra Pak anchors upstream control over carton-aseptic filling system combinations. Shanghai Boevan Packaging Machinery sits within the Chinese fabricator tier serving domestic and Southeast Asian price-sensitive procurement segments.
| Leading Market Players |
|---|
| Syntegon |
| Tetra Pak |
| Landpack |
| HAVER & BOECKER |
| Shanghai Boevan Packaging Machinery |
| All-Fill Inc. |
| IMA Group |
| OPTIMA packaging group |
| GEA Group |
| Others |
Supply & Pricing Matrix
Refurbished European equipment substitution in Vietnam and Indonesia simultaneously compresses new-machine pricing premiums and shifts procurement geography toward secondary-market hubs in Ho Chi Minh City and Jakarta. This dual displacement forces OEMs to unbundle service contracts and compete on hourly technician rates rather than capital equipment margins.
Pricing Analysis
FDA infant formula facility registration rules and EU MDR-adjacent hygiene standards dictate the pricing tier structure across automatic, semi-automatic, and manual configurations. Three-tier pricing structure across premium isolator-integrated, standard EHEDG-compliant, and economy non-validated levels separates validated export-grade systems from refurbished arbitrage. Cost compression in the semi-automatic tier is intensifying because Indian dairy cooperatives under PLI scheme infrastructure investments prioritize capital outlay minimization over aseptic specification. Price sensitivity concentrates most acutely among Vietnamese and Indonesian toll manufacturers procuring modular platforms with retrofittable forming modules.
Supply Chain Analysis
Port congestion on Hamburg-Singapore and Rotterdam-Jakarta trade lanes elevates inbound logistics costs for German and Italian precision components. Machine builder capacity clusters in Germany, Switzerland, and Italy draw from Grade 316L and 304 stainless steel mills in Germany, Sweden, and China for corrosion-resistant contact surfaces. Single-source vulnerability concentrates in Swiss-engineered Coriolis mass flow controllers and German servo drive assemblies. Distribution runs through regional validation specialists in Ho Chi Minh City and Jakarta who have captured calibration workflows previously captive to OEM service divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as service contract unbundling fragments traditional full-service lease models, creating niches for third-party validation specialists and modular platform suppliers across Southeast Asian dairy processing zones.
For Market Incumbents: Secure isolator-integrated technology leadership through proprietary powder dosing algorithm development and EHEDG-compliant cleanability certification investment. Defensive consolidation requires backward integration into precision servo drive manufacturing to offset stainless steel input volatility and capture margin from Swiss and German component suppliers. Threat of refurbished European equipment arbitrage demands channel control through captive aftermarket service networks in Vietnam and Indonesia. For New Entrants and Emerging Players: Lead with retrofittable forming modules for flexible pouch formats in India's PLI scheme dairy infrastructure investments, where capital constraints delay full automation and create white-space for semi-automatic configurations. Target toll manufacturing operations in Ho Chi Minh City and Jakarta with modular machines accommodating shifting customer packaging format requirements. Go-to-market angle: unbundled validation and calibration services competing on hourly technician rates against OEM captive divisions. For Investors and Strategic Acquirers: The market sits at a technology-upgrade phase that favors specialized powder handling engineering firms with proprietary screw geometry for high-fat variants. Long-term viability across the projection horizon hinges on isolator-integrated system integration capabilities and NIR spectroscopy inline release protocol development. Acquisition target archetype: Swiss or German mid-cap specialists with Coriolis mass flow controller expertise and existing EU MDR-adjacent hygiene standard certifications. Signal to watch: NMPA and SAMR GB standard conformity acceleration in Yangtze River Delta dairy processing zones as inflection indicator for premium tier demand.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Licensing | Syntegon leverages Waiblingen engineering base to capture premium dairy OEM contracts in Europe and Asia. |
| Backward Integration into Servo Drives | German OEMs secure margin protection against stainless steel input volatility through in-house precision motion control production. |
| Flexible Pouch Format Module Development | Stand-up and spouted bag-in-box configurations displace rigid cans in premium adult nutrition segments. |
| NIR Spectroscopy Inline Integration | Real-time moisture verification decomposes offline QC workflows for Swiss and Dutch hydrolyzed formula exporters. |
| Regional Validation Specialist Acquisition | Third-party calibration workflows in Ho Chi Minh City and Jakarta fragment traditional OEM service contract models. |
Research Methodology
A spread of perspectives from dairy processing plant engineers, OEM procurement managers, aftermarket service heads, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA facility registration databases, EU MDR-adjacent machinery hygiene standards, NMPA and SAMR GB standard conformity filings, and customs records for stainless steel component trade flows. Bottom-up unit economics from machine installations triangulated against top-down market sizing from dairy processing capacity expansion announcements.
Segmentation dimensions modeled span automation level, machine architecture, end-user vertical, and packaging format across the projection horizon. CAGRs derived from installed base replacement cycles, export-oriented capacity expansion in Vietnam and Indonesia, and aseptic specification tier migration. Industry-specific forecast inputs include NMPA and SAMR GB standard conformity acceleration timelines and dual carbon goal clean-in-place efficiency procurement scoring from China's MEE.
Forecasts assume regulatory continuity in FDA infant formula facility registration, EU MDR-adjacent hygiene standards, and NMPA and SAMR GB standard conformity regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include stainless steel price volatility, mechatronics talent scarcity in Southeast Asian expansion markets, and IP licensing friction delaying equipment shipments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Latin America Dairy Packaging Market
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Dairy Containers Market
Dairy Packaging
Europe Dairy Packaging Market