
 United States Dairy Packaging Market | 2026-2036
United States Dairy Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dairy Packaging Market Outlook
Texas is reshaping competitive dynamics through new dairy processing capacity near the Panhandle. Amcor Plc leverages its flexible film expertise to supply extended-shelf-life pouches for regional milk processors. Berry Global Group Inc. anchors its position through blow-molded HDPE bottle lines serving yogurt drink brands. Huhtamaki Oyj competes with fiber-based cup and lid systems targeting plant-based dairy alternatives.
United States dairy packaging encompasses primary and secondary containment systems engineered from multilayer polymers, coated paperboard, aluminum laminates, and tempered glass, manufactured through extrusion blow molding, aseptic form-fill-seal, and injection stretch blow processes to preserve microbiological stability and nutritional integrity from processing through retail distribution. Flexible pouches and Tetra Packs capture expanding share in milk and yogurt segments as processors seek lightweight formats with reduced logistics cost and refrigerated footprint. Plastic bottles dominate cheese and butter applications where oxygen barrier precision and resealability command premium positioning.
The FDA enforces food contact substance notifications under 21 CFR while the USDA Agricultural Marketing Service administers grade labeling standards that dictate package information architecture and claim substantiation. California's CalRecycle mandates rigid plastic packaging minimum recycled content thresholds that force converters to qualify post-consumer resin streams for dairy-grade applications. Stakeholders must monitor state-level extended producer responsibility legislation as it proliferates across the Northeast and Pacific Coast.
Market Dynamics
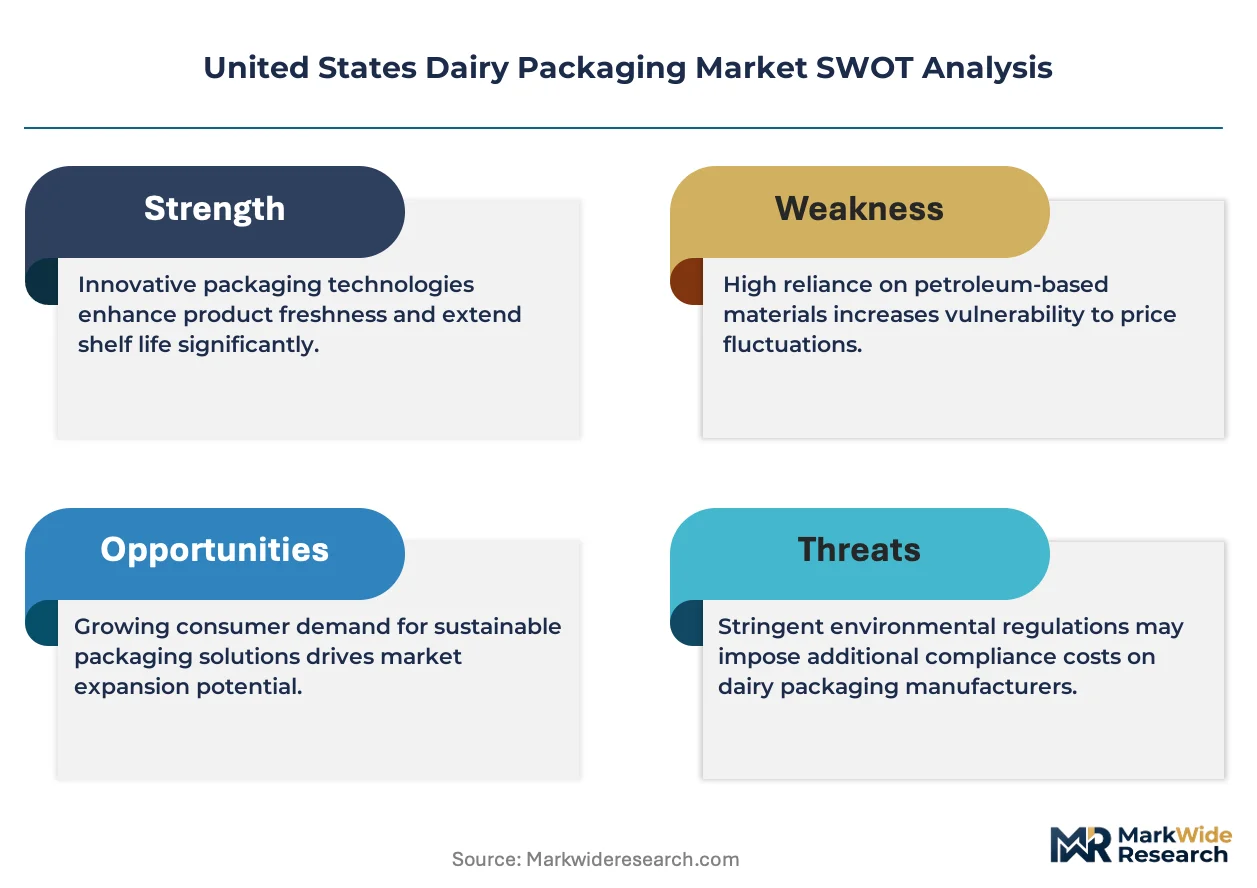
Serialized packaging mandates under the FDA's Food Safety Modernization Act are compressing converter timelines and forcing capital redeployment toward traceability-enabled formats across the dairy value chain.
Growth Catalysts
- Extended-shelf-life milk programs:Kroger and Walmart procurement expansions are pulling pouch and carton volumes upward as retailers consolidate private-label dairy sourcing.
- CalRecycle recycled content thresholds:California's rigid plastic packaging mandates are qualifying post-consumer resin streams for dairy-grade applications, opening compliant converter capacity.
- Plant-based dairy alternatives:Oat and almond milk processors are specifying fiber-based cup systems that displace conventional plastic formats in refrigerated sets.
Market Restraints
- Post-consumer resin qualification costs:Dairy-grade PCR certification requires extensive migration testing that adds twelve to eighteen months to material validation cycles.
- Texas Panhandle processing concentration:New dairy capacity clustering in the Texas Panhandle is stretching regional converter infrastructure and creating logistics bottlenecks for packaging supply.
- Glass substitution in premium segments:Artisan cheese and cultured butter brands are reverting to tempered glass for oxygen barrier precision, constraining polymer growth in high-margin niches.
Strategic Opportunities
- Aseptic form-fill-seal convergence:Combining aseptic processing with digital printing enables mass-customized pouches for regional milk processors without plate changeover downtime.
- Northeast extended producer responsibility legislation:Pending state-level EPR frameworks will create first-mover advantages for converters with established take-back infrastructure.
- Plant-based yogurt drinks:Blow-molded HDPE bottle demand from oat and coconut yogurt brands represents underpenetrated volume outside traditional dairy processor relationships.
Industry Challenges
- Serialized packaging integration:Embedding unique identifiers at line speed requires retrofitting existing form-fill-seal equipment with vision systems and database connectivity.
- Multilayer polymer delamination:Separating incompatible polymer streams for mechanical recycling demands capital-intensive density-based sorting infrastructure that few converters possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dairy Packaging Market |
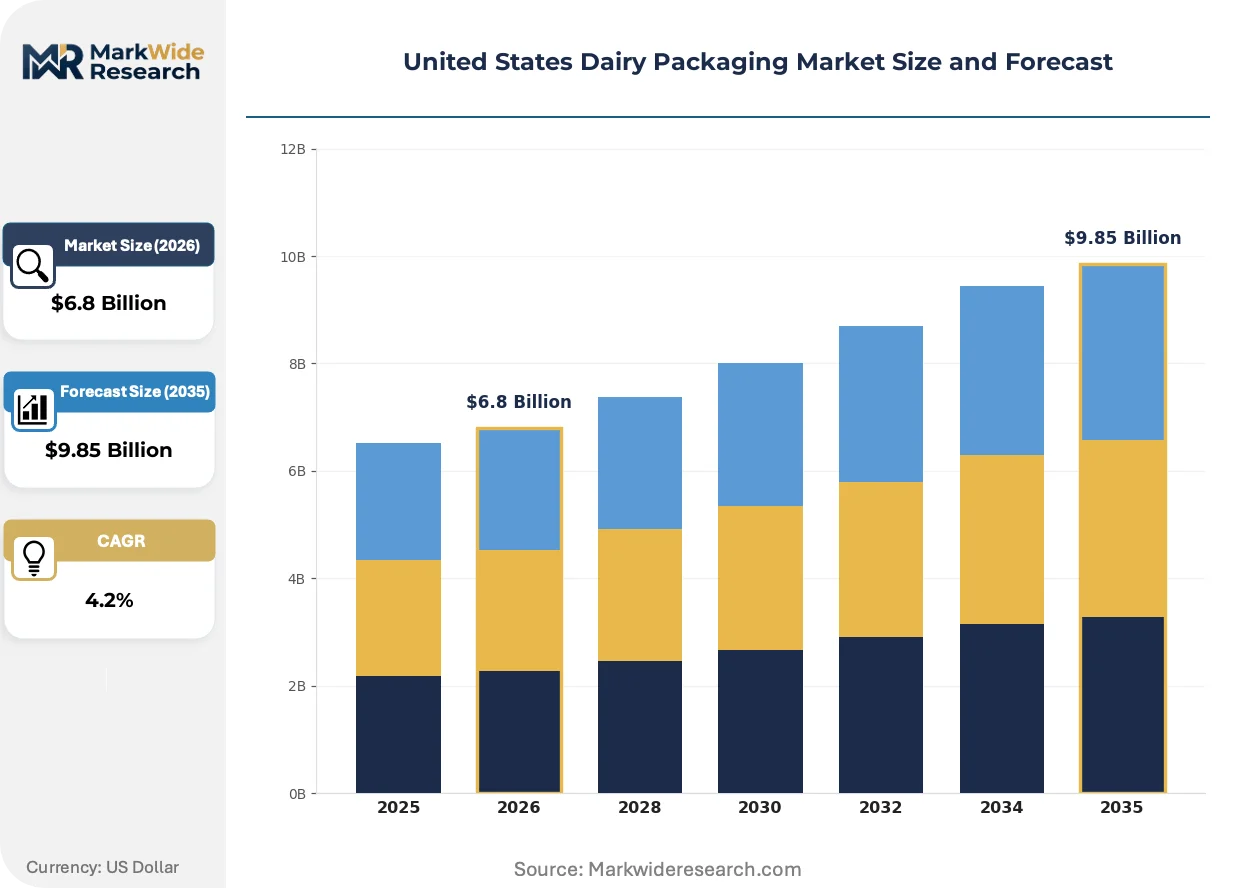
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Pouches, Bottles, Tetra Packs, Cartons Material: Plastic, Paper, Glass, Metals End User: Retail, Food Service, E-commerce, Wholesale Product Type: Milk, Cheese, Yogurt, Butter |
| Companies Covered | Huhtamaki Oyj, Berry Global Group Inc., Amcor Plc, Ball Corporation, Smurfit Kappa Group PLC, Sonoco Products Company, Sealed Air Corporation, International Paper Company, Tetra Pak, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dairy Packaging Market Strategic Shifts
Digital traceability and lightweight format adoption are compressing traditional packaging procurement cycles while expanding the viable substrate set for dairy applications.
Blockchain-enabled supply chain tracking is digitizing lot-level provenance verification from farm to retail shelf. Regional milk cooperatives are piloting serialized QR codes on extended-shelf-life pouches to satisfy Walmart's supplier transparency requirements. This distributed ledger architecture is digitizing audit workflows and compressing recall response timelines from days to hours.
California's CalRecycle mandates are forcing minimum recycled content thresholds into rigid dairy packaging specifications. Converters must now qualify post-consumer HDPE and PP streams for direct food contact, triggering migration testing protocols that extend material validation cycles. The state's Central Valley processing corridor faces the steepest compliance curve given its concentration of blow-molded bottle demand.
Direct-store-delivery networks are fragmenting traditional distributor relationships as fluid milk processors bypass warehousing intermediaries. Kroger's extended-shelf-life pouch programs exemplify this disintermediation, with processors managing refrigerated logistics directly to retail backrooms. This channel compression is visible across California and Texas, where private-label volume concentration enables scale economies for dedicated fleet investments.
United States Dairy Packaging Market Segmentation
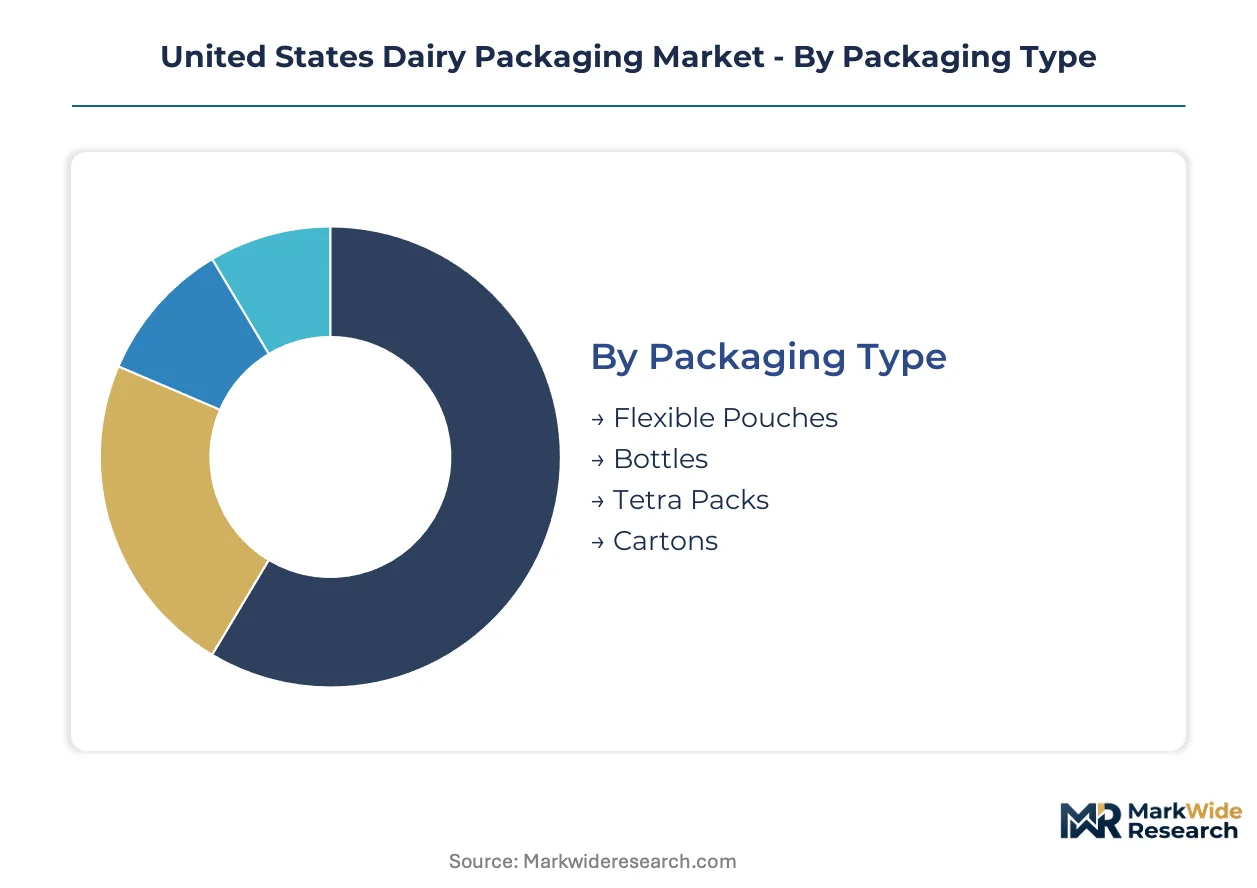
Dairy packaging segmentation reveals how substrate selection, supply chain configuration, and end-use requirements fragment procurement patterns across fluid milk, cultured products, and plant-based alternatives. Understanding these divisions exposes where converter capacity concentrates and where specification gaps create sourcing vulnerability.
Packaging Type:
After-sales service intensity varies sharply across formats, with aseptic pouch systems demanding rapid-response technical support for seal-integrity failures while blow-molded bottles require less frequent field intervention.
- Flexible Pouches:Multilayer polymer laminates with oxygen barrier layers and spouted fitments enable extended-shelf-life milk distribution. Kroger and Walmart private-label programs in California's Central Valley are pulling volume upward as retailers consolidate direct-procurement relationships.
- Bottles:Blow-molded HDPE and PET containers with tamper-evident closures dominate cheese spread and yogurt drink applications. Texas Panhandle processing expansion is stretching regional converter infrastructure and creating logistics bottlenecks for bottle supply.
- Tetra Packs:Aseptic brick cartons with aluminum-laminate barriers serve ambient milk distribution. FDA Food Safety Modernization Act traceability rules are pressuring converters toward serialized formats.
- Cartons:Coated paperboard gable-top containers remain standard for refrigerated fluid milk. CalRecycle recycled content mandates are forcing qualification of post-consumer resin streams for dairy-grade specifications.
Flexible pouches hold the largest share; momentum sits with Tetra Packs as ambient distribution networks expand.
Material:
Cost tier stratification separates premium barrier substrates from commodity-grade alternatives, with multilayer laminates commanding price premiums over monolayer structures.
- Plastic:HDPE, PP, PET, and multilayer flexible films constitute the dominant substrate class. Post-consumer resin qualification for direct food contact requires migration testing protocols that extend validation cycles.
- Paper:Coated paperboard and molded fiber systems target plant-based dairy alternatives. Oat and almond milk processors in California are specifying fiber-based cups that displace conventional plastic formats.
- Glass:Tempered containers serve artisan cheese and cultured butter segments where oxygen barrier precision commands premium positioning. Glass substitution is constraining polymer growth in high-margin niches.
- Metals:Aluminum laminates and foils provide absolute light and oxygen barriers for extended-shelf-life applications. Metal detection systems and compatibility with aseptic processing lines limit deployment flexibility.
Plastic dominates volume; paper is expanding most quickly as plant-based brands prioritize sustainability signaling.
End User:
Customer type determines order-pattern predictability, with retail chains offering volume commitments against food-service accounts that fragment across dispersed operators.
- Retail:Supermarket and mass-merchandiser chains specify private-label packaging with strict traceability requirements. Walmart's supplier transparency mandates are driving serialized QR code pilots on extended-shelf-life pouches.
- Food Service:Institutional and restaurant distributors demand bulk formats with portion-control features. Direct-store-delivery networks are fragmenting traditional distributor relationships as processors bypass warehousing intermediaries.
- E-commerce:Direct-to-consumer dairy subscription services require protective secondary packaging for temperature-controlled last-mile delivery. Cold-chain integrity specifications exceed conventional retail requirements.
- Wholesale:Cash-and-carry and distributor-served accounts prioritize cost-minimization over premium substrate features. Volume concentration enables scale economies for dedicated fleet investments.
Retail commands the largest share; e-commerce is gaining share fastest as refrigerated last-mile infrastructure matures.
Product Type:
Application maturity separates commoditized fluid milk packaging from value-added cultured product formats where barrier precision and resealability justify premium positioning.
- Milk:Fluid milk packaging spans pouches, cartons, and bottles with shelf-life requirements driving substrate selection. Extended-shelf-life programs are consolidating procurement around pouch and carton formats.
- Cheese:Shredded, sliced, and block cheese applications demand oxygen barrier films and resealable structures. Blow-molded HDPE bottles serve processed cheese spreads where oxygen exclusion preserves texture.
- Yogurt:Cup, drinkable, and Greek yogurt formats require moisture barrier and stack-strength optimization. Plant-based yogurt drinks from oat and coconut brands represent underpenetrated volume outside traditional dairy processor relationships.
- Butter:Foil-wrapped and tub formats balance oxygen barrier with printability for brand differentiation. Cultured butter brands are reverting to tempered glass for premium positioning.
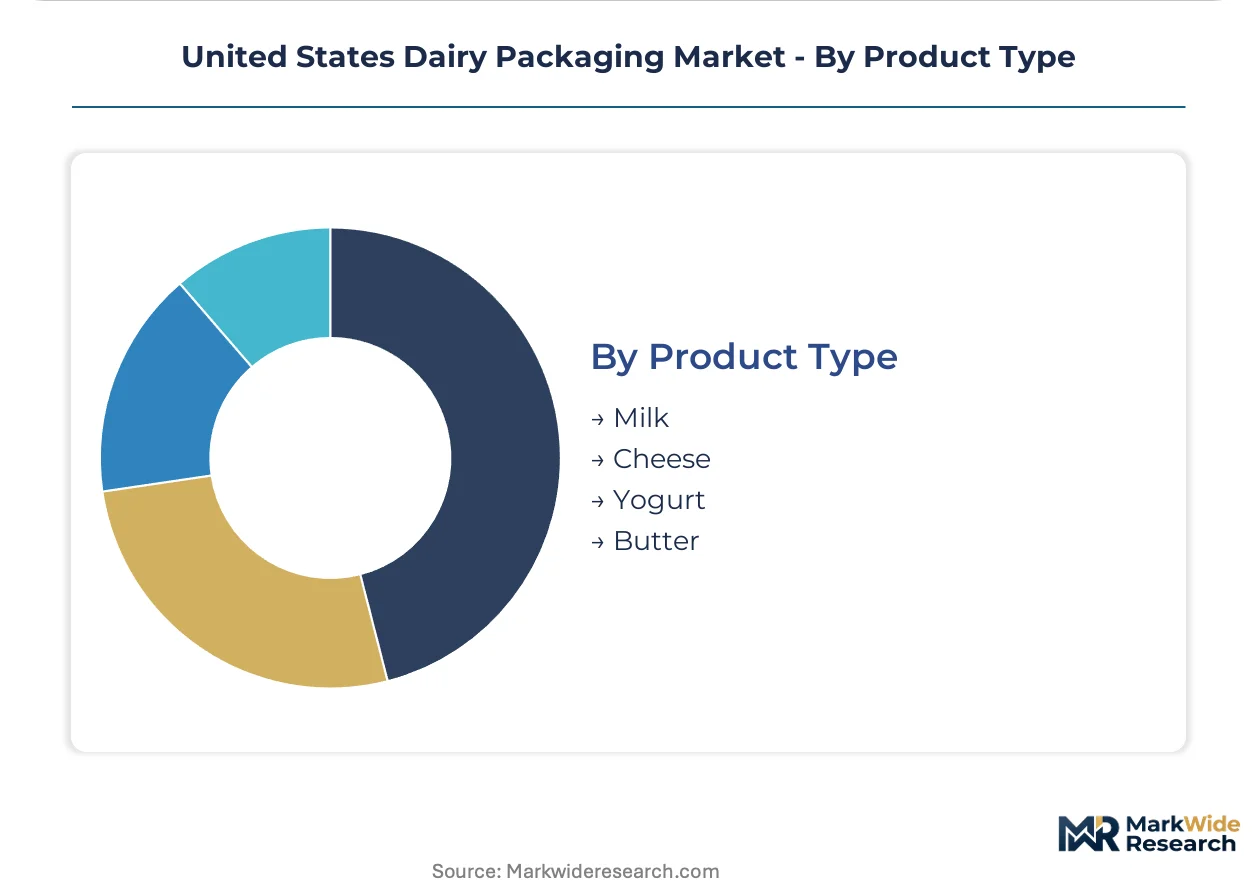
Milk holds the largest share; momentum sits with yogurt as plant-based alternatives fragment the category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA traceability mandates under the Food Safety Modernization Act are reshaping packaging procurement patterns across state-level dairy processing corridors. California's CalRecycle recycled content thresholds and Texas Panhandle capacity expansion are creating divergent compliance and logistics pressures.
California
Central Valley processors face the steepest CalRecycle compliance curve for rigid plastic packaging. The state's minimum recycled content thresholds force converters to qualify post-consumer HDPE and PP streams for direct food contact. Fresno and Tulare counties concentrate blow-molded bottle demand from extended-shelf-life milk programs.
Texas
Panhandle dairy processing expansion is stretching regional converter infrastructure and creating packaging supply bottlenecks. USDA Agricultural Marketing Service grade labeling standards govern package information architecture for fluid milk exports. Amarillo and Lubbock clusters attract pouch and carton procurement from private-label retailers.
Wisconsin
Cheese packaging demand centers on oxygen barrier films and resealable structures for shredded and block formats. State-level dairy processor cooperatives influence specification standardization across the Upper Midwest. Green Bay and Madison metro areas anchor converter relationships with artisan cheese brands.
New York
Pending extended producer responsibility legislation in Albany is pressuring converters to establish take-back infrastructure ahead of mandate implementation. FDA food contact substance notifications under 21 CFR govern multilayer polymer laminates for yogurt applications. Finger Lakes and Hudson Valley processing facilities drive fiber-based cup demand from plant-based dairy alternatives.
Idaho
Milk powder and ingredient packaging concentrates in the Magic Valley processing corridor. Aseptic form-fill-seal equipment investments target export-oriented dairy ingredient producers. Twin Falls and Jerome counties host blow-molded HDPE bottle lines serving yogurt drink brands.
United States Dairy Packaging Market Competitive Environment
Flexible film specialists and rigid container fabricators split the market along substrate lines, with aseptic format providers occupying a distinct middle tier. Consolidation pressures concentrate among converters with integrated resin qualification capabilities. Three strategic archetypes dominate: multilayer laminate specialists, blow-molded bottle scale players, and fiber-based sustainable format innovators. Competitive moves center on post-consumer resin stream certification and aseptic line retrofitting for serialized packaging integration.
Among Nordic-based packaging conglomerates, Huhtamaki Oyj exemplifies the fiber-based sustainable format archetype through its cup and lid system positioning. Amcor Plc and Berry Global Group Inc. occupy central positions within the flexible film and rigid container tiers respectively, with both representing integrated multinational structures capable of spanning substrate categories. These three anchors demonstrate how geographic diversification and substrate breadth serve as defensive positioning against state-level regulatory fragmentation.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Berry Global Group Inc. |
| Amcor Plc |
| Ball Corporation |
| Smurfit Kappa Group PLC |
| Sonoco Products Company |
| Sealed Air Corporation |
| International Paper Company |
| Tetra Pak |
| Others |
Value Chain & Pricing Dynamics
California's Central Valley refrigerated freight corridor anchors cost dynamics for dairy packaging procurement, with lane compression between Fresno processing clusters and Los Angeles distribution centers amplifying price differentiation between national converters and regional specialists. This logistics architecture concentrates supply-side leverage among multilayer laminate producers while forcing smaller blow-molded bottle suppliers into spot-market resin exposure.
Pricing Analysis
Geographic price spreads of 12-18% separate Texas Panhandle procurement from California Central Valley contracts for equivalent HDPE bottle specifications. Three-tier pricing structure across premium barrier laminates, standard monolayer films, and economy-grade recycled-content formats dominates substrate categories. Pricing pressure stems from Kroger and Walmart private-label consolidation demanding year-over-year cost reductions. Food-service distributors exhibit highest price sensitivity due to fragmented volume aggregation, while extended-shelf-life milk processors prioritize seal-integrity performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Amcor Plc, Berry Global Group Inc., and Huhtamaki Oyj holding approximately 60% of qualified aseptic and blow-molded capacity. Raw material dependencies draw from Texas Gulf Coast petrochemical feedstocks, post-consumer resin streams from California collection infrastructure, and aluminum laminate supply from domestic rolling mills. Single-source vulnerability concentrates in FDA-compliant multilayer adhesive formulations where qualified alternatives require 18-month migration protocols. Distribution runs through direct-store-delivery networks bypassing traditional warehousing intermediaries in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail procurement desks as Kroger and Walmart extended-shelf-life program expansions compress supplier margins and force specification standardization across regional converter bases.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into post-consumer resin qualification capabilities before CalRecycle mandates tighten further. Anchor capacity expansion in Texas Panhandle clusters to capture logistics proximity premiums as dairy processing concentrates there. Defend against fiber-based cup displacement in plant-based segments through barrier coating R&D partnerships with oat milk processors. For New Entrants and Emerging Players: Pursue white-space opportunities in serialized packaging retrofit services for mid-tier converters lacking FDA Food Safety Modernization Act compliance infrastructure. Target Northeast extended producer responsibility legislation preparation as a service offering to converters without established take-back programs. Lead with digital printing integration for mass-customized pouch runs as the go-to-market wedge against plate-based incumbents. For Investors and Strategic Acquirers: Fiber-based sustainable format specialists with California manufacturing footprints represent the most defensible acquisition archetype given plant-based dairy alternative momentum and state-level recycled content mandates. Long-term viability hinges on substrate diversification beyond petroleum-dependent polymers as regulatory pressure intensifies. Monitor FDA traceability rule enforcement velocity as the critical inflection signal for serialized packaging demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Qualification Investment | CalRecycle compliance thresholds force dairy-grade PCR certification ahead of mandate expansion. |
| Aseptic Line Serialization Retrofit | FDA Food Safety Modernization Act rules compress timelines for traceability-enabled format deployment. |
| Fiber-Based Cup System Expansion | Oat and almond milk processors in California displace conventional plastic with molded fiber specifications. |
| Direct-Store-Delivery Fleet Integration | Kroger and Walmart private-label consolidation rewards packaging suppliers with logistics coordination capabilities. |
| Extended Producer Responsibility Infrastructure | Pending Northeast state legislation creates first-mover advantage for converters with established take-back programs. |
Study Parameters
Desk research of FDA food contact substance notifications, USDA Agricultural Marketing Service grade labeling standards, and CalRecycle regulatory filings preceded structured interviews with dairy packaging procurement directors, converter operations managers, retail category buyers, and resin qualification laboratory directors. Secondary validation drew from SEC 10-K filings of publicly traded packaging conglomerates, trade association production surveys, and customs import records for aluminum laminate substrates. Bottom-up volume modeling across substrate categories triangulated against top-down market sizing from processor capacity announcements.
Assumptions held fixed include FDA enforcement velocity on Food Safety Modernization Act traceability rules, CalRecycle recycled content threshold implementation timelines, and extended-shelf-life milk program expansion rates at major retailers. Variables included resin price volatility, state-level extended producer responsibility legislation adoption pace, and plant-based dairy alternative market penetration. Segmentation dimensions modeled encompass packaging type, material substrate, end-user channel, and product application. CAGRs were derived from regression analysis of historical procurement volumes against processing capacity expansion announcements. Industry-specific inputs included aseptic form-fill-seal equipment installation rates and post-consumer resin qualification pipeline status.
Macroeconomic conditions sit as an overlay; deviation in diesel freight costs, interest rate environments affecting converter capital expenditure cycles, or resin feedstock price shocks would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Quarterly review of FDA guidance document releases, state legislative tracking databases, and retail private-label program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Latin America Dairy Packaging Market
Dairy Packaging
Dairy Containers Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
Europe Dairy Packaging Market