
 Dairy Packaging Market | 2026-2036
Dairy Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Packaging Market Intelligence
EU Green Deal packaging rules are realigning the cost-of-entry calculus for dairy packaging suppliers entering European markets. Tetra Pak International SA leverages its aseptic carton R&D infrastructure to sustain technology leadership in extended-shelf-life formats. Amcor plc anchors its position through backward integration into recycled resin streams for dairy bottles and pouches. SIG Combibloc Group AG competes on filling-machine compatibility, locking in dairy processor loyalty through capital equipment tie-ins.
Dairy packaging encompasses primary and secondary containment systems engineered from plastic resins, paperboard laminates, glass, or aluminum, manufactured through blow-molding, thermoforming, or aseptic forming processes to preserve microbiological stability and nutritional integrity of fluid milk, fermented products, and fat-based derivatives. Cartons and pouches are capturing share from rigid formats as dairy processors prioritize lightweighting and logistics efficiency in chilled distribution networks. Plastic retains volume dominance across milk and yogurt applications, though paper-based alternatives are penetrating premium organic segments where consumer willingness to pay for fiber-based barriers exceeds material cost premiums.
FDA food-contact substance notifications govern polymer safety for US dairy packaging, while EFSA and EU REACH restrict certain additives and mandate recyclability disclosures, collectively elevating compliance investment for multi-material laminates. India's FSSAI packaging regulations and BIS standards for food-grade plastics are tightening at the state level, forcing domestic dairy cooperatives to upgrade from unprinted LDPE pouches to certified multilayer structures. Stakeholders must monitor how extended producer responsibility frameworks in Europe and evolving FDA recycling-content guidance reshape material specification decisions before committing to long-term capital contracts.
Market Dynamics
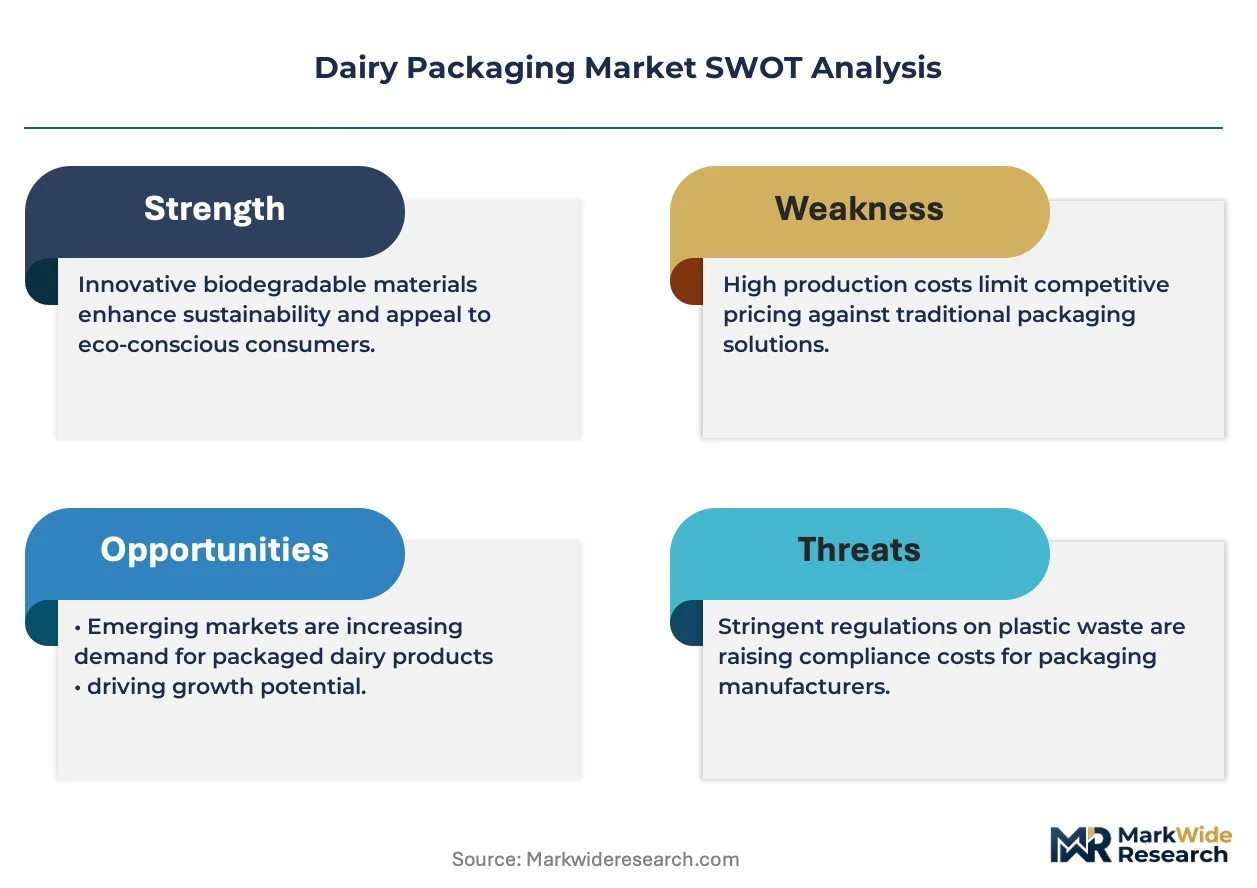
The EU Green Deal packaging waste directives are compressing the viable material set for dairy containment systems, forcing processors to absorb compliance costs or exit European supply chains entirely.
Growth Catalysts
- Aseptic carton technology:Extended-shelf-life formats are capturing volume from chilled distribution networks as processors eliminate refrigeration capital expenditure.
- India's cold-chain investments:Organized dairy retail expansion in Maharashtra and Gujarat is accelerating branded pouch and carton uptake among urban households.
- FSSAI state-level enforcement:Tightened BIS standards for food-grade plastics are displacing unprinted LDPE pouches in favor of certified multilayer structures.
Market Restraints
- Recycled resin input volatility:Post-consumer rPET and rHDPE pricing swings compress margin predictability for bottle converters.
- Multi-material laminate technical limitation:Current fiber-based barriers fail to match plastic oxygen transmission rates for ultra-high-temperature milk.
- EU REACH additive restrictions:Phthalate and heavy-metal compliance testing extends new product qualification timelines by 8-14 months.
Strategic Opportunities
- Extended producer responsibility tailwind:European EPR frameworks reward mono-material designs with lower compliance fees.
- India's dairy cooperative modernization:State federations in Karnataka and Rajasthan are upgrading from loose milk to pre-printed pouches.
- Digital printing convergence:Inkjet and flexo technologies enable SKU proliferation without plate-change downtime.
Industry Challenges
- Barrier polymer formulation expertise:Shortage of chemists skilled in EVOH and nylon coextrusion limits domestic converter capability in emerging markets.
- Legacy filling-line incompatibility:Aseptic carton format switches require capital-intensive machine replacement or retrofits.
- Recyclability certification complexity:Multiple competing standards (How2Recycle, OPRL, Green Dot) create labeling fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Packaging Market |
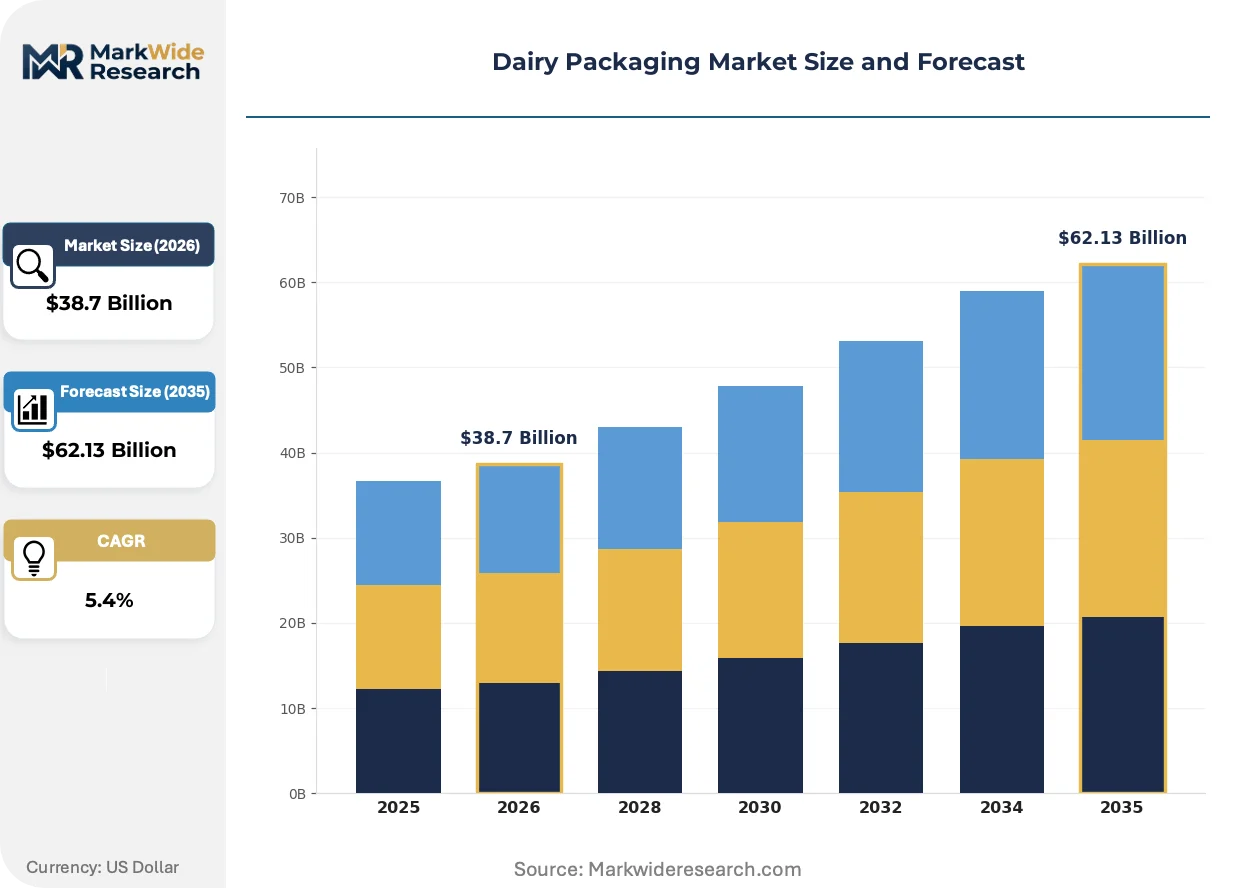
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
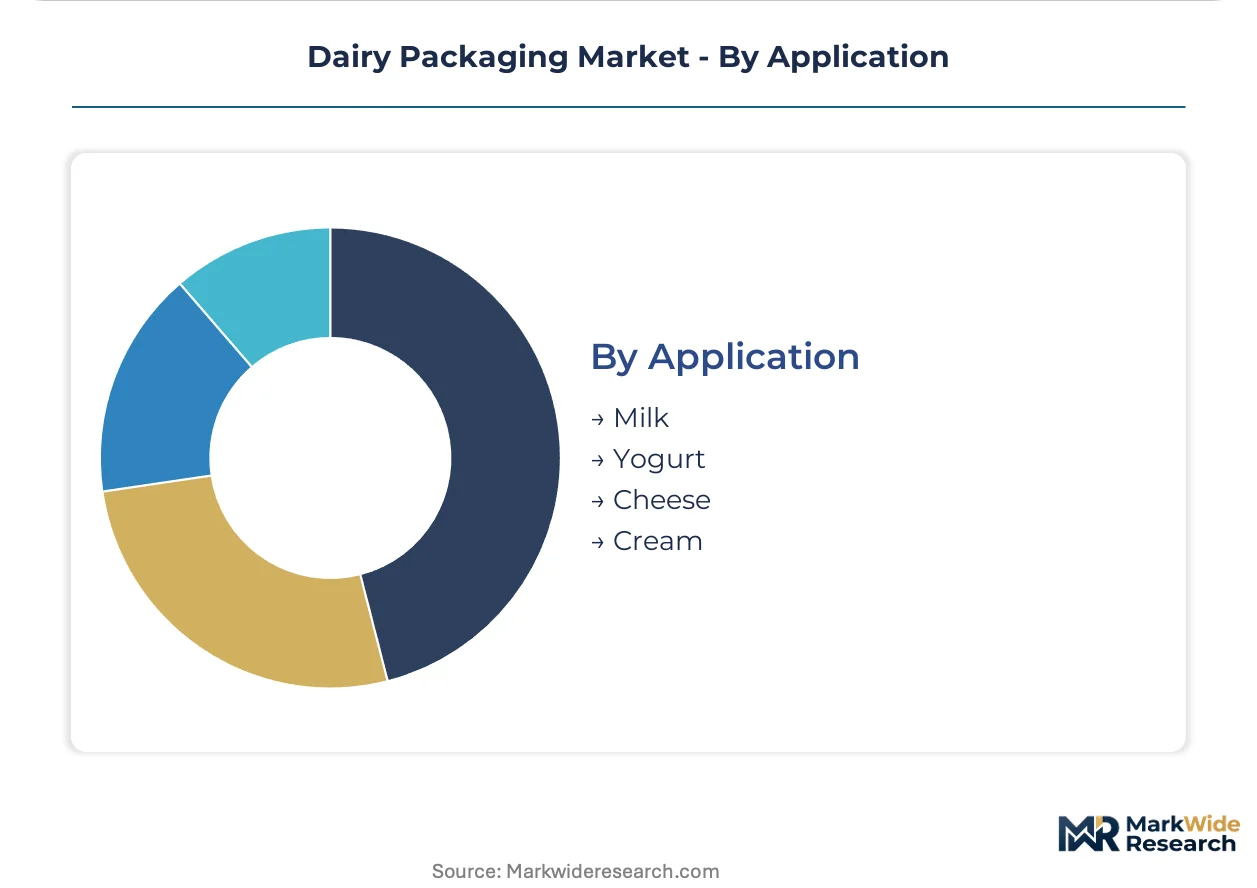
| Segmentation | Packaging Type: Bottles, Cartons, Pouches, Tetra Packs Material: Plastic, Paper, Glass, Aluminum End User: Retailers, Wholesalers, Food Service, Household Application: Milk, Yogurt, Cheese, Cream |
| Companies Covered | Tetra Pak International SA, Amcor plc, Berry Global Inc., Huhtamaki Oyj, Sealed Air Corporation, SIG Combibloc Group AG, Elopak AS, Mondi Group, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Packaging Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory stringency are converging to restructure the dairy packaging value chain, with lightweighting and circularity mandates dictating specification decisions.
Paperboard barrier laminates are expanding into ultra-high-temperature milk applications previously reserved for multi-layer plastic bottles. European organic dairy processors in Denmark and the Netherlands are adopting these formats despite 15-20% material cost premiums. The technology is expanding into premium private-label segments where shelf differentiation justifies unit economics compression.
EU Green Deal packaging waste directives are mandating recyclability-by-design for all dairy containment placed on European markets. The regulation forces elimination of non-separable material combinations and triggers redesign cycles for legacy gable-top cartons. Processors in Germany and France are responding with mono-material pilot programs ahead of 2030 enforcement milestones.
Direct-to-consumer subscription models are fragmenting traditional wholesale procurement for specialty dairy. Small-batch yogurt and kefir brands in the US and UK are bypassing retail distribution through insulated shipper formats. This channel rotation concentrates demand in California, New York, and London metro corridors where cold-chain logistics density supports weekly delivery cadences.
Dairy Packaging Market Segmentation
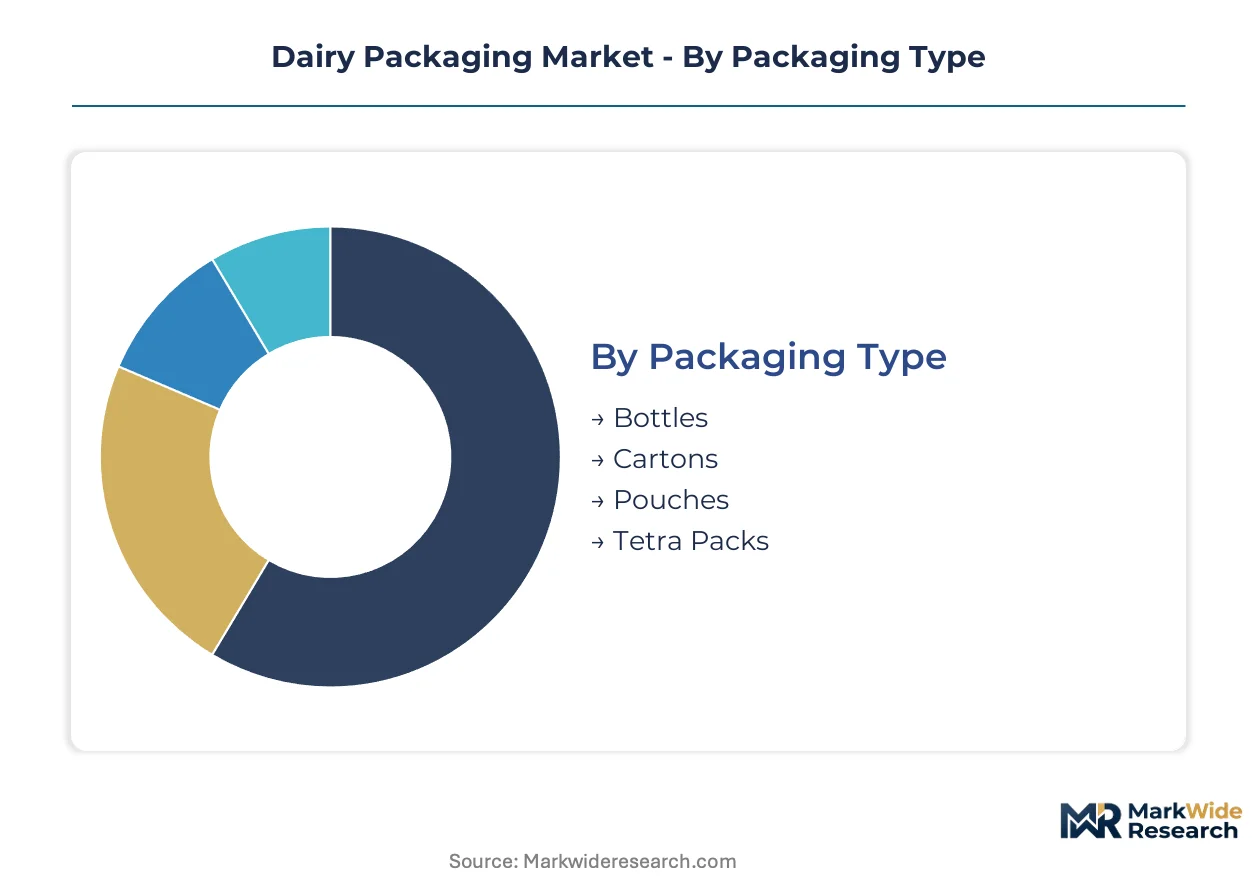
Dairy packaging specifications diverge sharply across temperature regimes, shelf-life targets, and distribution economics. Material selection and format geometry determine cold-chain capital requirements, logistics cube efficiency, and compliance pathways under tightening EPR frameworks.
Packaging Type:
Structural format dictates filling-line compatibility, barrier performance, and end-of-life recovery economics across dairy supply chains.
- Cartons:Paperboard barrier laminates with aluminum or polymer layers provide extended shelf-life protection for ambient distribution. European organic processors in Denmark and the Netherlands absorb material cost premiums to meet EU Green Deal recyclability mandates.
- Bottles:Blow-molded HDPE and PET containers dominate chilled milk distribution in North American and European retail. Recycled resin integration is accelerating as FDA food-contact notifications and EFSA compliance testing expand acceptable rHDPE and rPET input ratios.
- Pouches:Flexible multilayer structures reduce material weight and logistics cost for emerging market dairy cooperatives. FSSAI state-level enforcement in India is displacing unprinted LDPE formats with certified food-grade alternatives.
- Tetra Packs:Aseptic brick and gable-top configurations eliminate refrigeration capital expenditure for processors in markets with sparse cold-chain infrastructure. Format switches require machine replacement or retrofits, locking in processor loyalty through capital equipment tie-ins.
Mature deployment sits with bottles. Newer deployment is concentrated in cartons.
Material:
Substrate selection balances oxygen transmission rates, mechanical integrity, and circularity compliance under divergent regulatory regimes.
- Plastic:HDPE, PET, and multilayer coextrusions retain volume dominance across milk and yogurt applications. Post-consumer recycled resin pricing volatility compresses margin predictability for converters navigating FDA and EFSA notification timelines.
- Paper:Fiber-based barriers penetrate premium organic segments where consumer willingness to pay exceeds material cost premiums. Current technical limitations in oxygen transmission rates restrict penetration of ultra-high-temperature milk applications.
- Glass:Inert containment preserves flavor integrity for high-value cultured dairy and specialty cream products. Weight and fragility constraints limit adoption beyond premium retail channels in Germany, France, and Italy.
- Aluminum:Foil layers within laminate structures provide zero oxygen transmission for long-life dairy derivatives. Mono-material recovery challenges intensify under EU Green Deal recyclability-by-design mandates.
Plastic commands installed base. Paper is climbing the fastest under sustainability-driven specification shifts.
End User:
Procurement scale and format standardization vary across channel types, dictating converter salesforce deployment and inventory strategies.
- Retailers:Supermarket and hypermarket chains specify standardized formats with high-visibility printing for shelf differentiation. Digital printing convergence enables SKU proliferation without plate-change downtime for private-label programs.
- Wholesalers:Bulk procurement of standardized bottles and pouches serves institutional redistribution networks. Price sensitivity concentrates demand in high-volume, low-specification formats.
- Food Service:Hotels, restaurants, and catering operations prioritize portion control and dispensing efficiency over shelf aesthetics. Bag-in-box and single-serve formats dominate this channel.
- Household:Direct-to-consumer subscription models fragment traditional wholesale procurement for specialty dairy in California, New York, and London metro corridors.
Retailer procurement is the most consolidated. Household channels are expanding most quickly through subscription logistics innovation.
Application:
Product rheology and microbiological stability requirements drive barrier specification and sterilization protocol selection.
- Milk:Fluid milk packaging spans ambient UHT and chilled pasteurized formats with divergent shelf-life targets. Aseptic carton technology captures volume from chilled distribution as processors eliminate refrigeration capital expenditure.
- Yogurt:Viscous cultured products demand container rigidity and controlled headspace for texture preservation. Cup and pot formats dominate, with paperboard alternatives penetrating organic segments.
- Cheese:Modified atmosphere packaging and vacuum barriers control moisture loss and mold inhibition across hard and soft cheese categories. Waxed paper and multilayer films serve distinct aging and retail requirements.
- Cream:High-fat derivatives require oxygen and light barriers to prevent oxidative rancidity. Small-format cartons and bottles serve food service and retail channels respectively.
Milk commands the largest format diversity. Cheese packaging is gaining share fastest through premium specialty expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate India's organized dairy packaging demand, while EU Green Deal compliance zones reshape European material specifications. Cold-chain infrastructure investments and regulatory enforcement timelines determine regional competitive positioning across the analysis window.
India
State-level FSSAI enforcement in Maharashtra and Karnataka accelerates displacement of unprinted LDPE pouches. The BIS certification mandate for food-grade plastics forces dairy cooperatives toward multilayer certified structures. Ahmedabad and Surat industrial corridors anchor pouch and aseptic carton manufacturing clusters serving Gujarat Cooperative Milk Marketing Federation procurement.
Germany
Organic dairy processors in Bavaria and Baden-Württemberg absorb 15-20% material cost premiums for paperboard barrier laminates. EU Green Deal recyclability-by-design mandates trigger redesign cycles for legacy gable-top formats ahead of 2030 milestones. The Munich-Stuttgart corridor concentrates mono-material pilot programs among major dairy processors.
United States
Direct-to-consumer subscription models fragment wholesale procurement in California and New York metro corridors. FDA food-contact substance notifications govern polymer safety for extended-shelf-life formats. Wisconsin and California dairy belts anchor blow-molded HDPE bottle demand from major fluid milk processors.
Netherlands
Premium organic segments in Randstad cities demonstrate consumer willingness to pay for fiber-based barrier alternatives. EFSA compliance testing for recycled resin integration extends qualification timelines for domestic converters. Eindhoven-Tilburg logistics hubs facilitate aseptic carton distribution across Benelux chilled networks.
China
Dual carbon goals and SAMR packaging standards tighten material compliance for dairy containment systems. Yangtze River Delta dairy processors prioritize lightweighting to reduce logistics costs in dense urban distribution. Shanghai and Suzhou manufacturing bases supply aseptic carton formats to domestic and export markets.
Dairy Packaging Market Key Industry Players
European producers anchor the premium compliance tier; Asia-Pacific specialists hold cost-optimized segments through regional manufacturing density. The vendor base concentrates around integrated material-format combinations rather than commodity supply. Three archetypes dominate: aseptic technology licensors, recycled resin integrators, and filling-machine system bundlers. Competitive moves center on backward integration into resin streams and capital equipment tie-ins that lock processor loyalty.
Among the integrated technology tier, Tetra Pak International SA and SIG Combibloc Group AG exemplify aseptic carton system providers whose equipment-format bundling creates switching costs for dairy processors. Amcor plc represents the resin-integration archetype through captive supply chains for recycled polymer streams. These three entities occupy distinct competitive positions defined by their core capability anchors rather than overlapping segment competition.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| Amcor plc |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| SIG Combibloc Group AG |
| Elopak AS |
| Mondi Group |
| Ball Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap converters across Germany and Italy anchor regional supply clusters, their conservative balance sheets limiting capacity expansion and sustaining pricing discipline for certified multilayer structures. This ownership pattern concentrates supply-side bargaining power among established players while forcing processors to absorb compliance premiums or accept longer lead times.
Pricing Analysis
Short lead-time premiums of 12-18% apply to aseptic carton orders below contractual minimums, while spot inventory of recycled HDPE resin trades at discounts when post-consumer bale availability peaks. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA compliance tier, volume scale, and after-sales technical support bundling. Pricing pressure stems from rPET and rHDPE input volatility compressing converter margins. Institutional wholesalers exhibit highest price sensitivity, while organic dairy processors in Denmark and the Netherlands absorb material cost premiums for fiber-based barriers.
Supply Chain Analysis
EFSA and FDA food-contact certification gates supply eligibility, extending qualification timelines for new market entrants. Manufacturing concentrates in Germany, China, and India, with blow-molded HDPE bottle production anchored in Wisconsin and California dairy belts. Raw material dependencies include aluminum foil for barrier laminates, food-grade LLDPE for pouch coextrusion, and post-consumer resin streams for circular content targets. Single-source vulnerability sits with EVOH barrier polymer supply from limited specialty chemical producers. Distribution runs through dairy processor filling-line integration, locking in format choices through capital equipment tie-ins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging waste directives are compressing the viable supplier set, forcing sub-scale converters to exit or sell as compliance costs outstrip revenue. Consolidation favors players with backward integration into certified resin streams and established EFSA notification pathways.
For Market Incumbents: Cement technology leadership through captive aseptic filling-machine installation bases that lock processor loyalty. Deepen upstream control over post-consumer rHDPE and rPET sorting infrastructure to buffer resin pricing volatility. Defend against paper-based barrier substitution by accelerating oxygen transmission rate improvements in multilayer plastic formats.
For New Entrants and Emerging Players: Digital printing convergence offers a technology-first wedge, enabling SKU proliferation without plate-change downtime for small-batch dairy brands. Target direct-to-consumer subscription channels in California and London metro corridors where insulated shipper format demand fragments traditional wholesale procurement. Pursue white-label manufacturing partnerships with specialty kefir and yogurt startups bypassing retail distribution.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mono-material pilot program operators in Germany and France ahead of EU Green Deal enforcement milestones. Five-to-ten-year viability hinges on recyclability-by-design certification rather than legacy multi-material laminate expertise. Watch FSSAI state-level enforcement acceleration in Maharashtra and Karnataka as inflection signal for Indian dairy cooperative modernization demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Streams | Captive rHDPE supply from post-consumer bale sourcing insulates Amcor plc from pricing volatility. |
| Aseptic Filling-Machine System Bundling | Tetra Pak International SA locks processor loyalty through capital equipment tie-ins and format exclusivity. |
| Mono-Material Pilot Program Expansion | German dairy processors in Bavaria redesign legacy gable-top cartons to meet EU Green Deal recyclability mandates. |
| Digital Printing Technology Deployment | Inkjet and flexo capabilities enable private-label SKU proliferation without plate-change downtime for retailer programs. |
| State-Level FSSAI Certification Investment | Multilayer pouch converters in Gujarat secure BIS food-grade certification to serve Gujarat Cooperative Milk Marketing Federation procurement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across dairy processor procurement directors, converter plant managers, filling-machine OEM technical sales leads, and EFSA regulatory affairs consultants. Bottom-up volume builds from segment-level production data triangulated against top-down macroeconomic drivers. Secondary sources included FDA food-contact substance notifications, EU REACH additive restriction updates, FSSAI state enforcement circulars, and BIS certification registries.
Data-stream reconciliation across shipment volumes, resin pricing indices, and capital expenditure disclosures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include packaging type, material substrate, end-user channel, and application temperature regime. CAGRs were derived from trend-line extrapolation of historical volume shifts adjusted for regulatory enforcement timelines and cold-chain infrastructure investment curves. Forecast inputs incorporated aseptic carton technology adoption rates and recycled resin integration ratios.
Several conditions sit outside the modeled scope, including abrupt tariff restructuring on aluminum foil imports, unanticipated EVOH supply disruptions, and rapid shifts in consumer willingness to pay for fiber-based barriers. Forecasts reflect assumptions about regulatory enforcement consistency and resin pricing mean-reversion. A model refresh is warranted upon material change in EU Green Deal implementation timelines or FSSAI state-level certification mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Europe Dairy Packaging Market
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Latin America Dairy Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
Dairy Containers Market