
 Yogurt Packaging Market | 2026-2036
Yogurt Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Yogurt Packaging Market Analytics
India is tilting toward expanded thermoforming capacity for single-serve yogurt cups to serve its organized dairy retail expansion. Tetra Pak leverages aseptic carton expertise to anchor ambient yogurt distribution across Southeast Asian markets. Huhtamaki Group sustains flexible packaging leadership through high-barrier pouch formats for drinkable yogurt segments. Mondi Group competes with molded fiber innovations that target European private-label sustainability mandates.
Yogurt packaging encompasses the engineered containment systems—ranging from thermoformed polystyrene cups to multilayer aseptic cartons—designed to preserve dairy freshness, enable portion control, and support cold-chain logistics from dairy processor to retail shelf. These structures typically incorporate ethylene vinyl alcohol copolymer barriers or aluminum oxide coatings to block oxygen ingress and extend refrigerated shelf life. Cups dominate volume deployment across retail channels, though pouches are gaining structural share in on-the-go consumption scenarios where lightweighting and dispensing convenience override rigidity requirements. Glass jars retain premium positioning in organic and artisanal segments where material authenticity commands shelf price separation from mass-market tubs.
The EU F-Gas Regulation and REACH chemical restrictions are reshaping material selection for sealant layers and printing inks across European yogurt packaging supply chains. FDA food-contact substance notifications govern polymer migration limits for US-bound dairy packaging, while India's BIS certification requirements for food-grade plastics create compliance thresholds for imported substrate formats. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling infrastructure investments before committing capital to regional capacity.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for polystyrene cups across European dairy supply chains, forcing processors to validate alternative substrates before filling line retrofits complete.
Growth Catalysts
- REACH chemical restrictions:European converters accelerate compliant barrier coating development, opening procurement windows for EVOH and aluminum oxide suppliers.
- ASEAN ambient distribution:Tropical climate logistics drive aseptic carton demand for shelf-stable yogurt formats across Indonesia, Vietnam, and Thailand.
- German dairy retrofit wave:Filling line upgrades in Bavaria and North Rhine-Westphalia create equipment demand for handling paperboard and recyclable polymer substrates.
Market Restraints
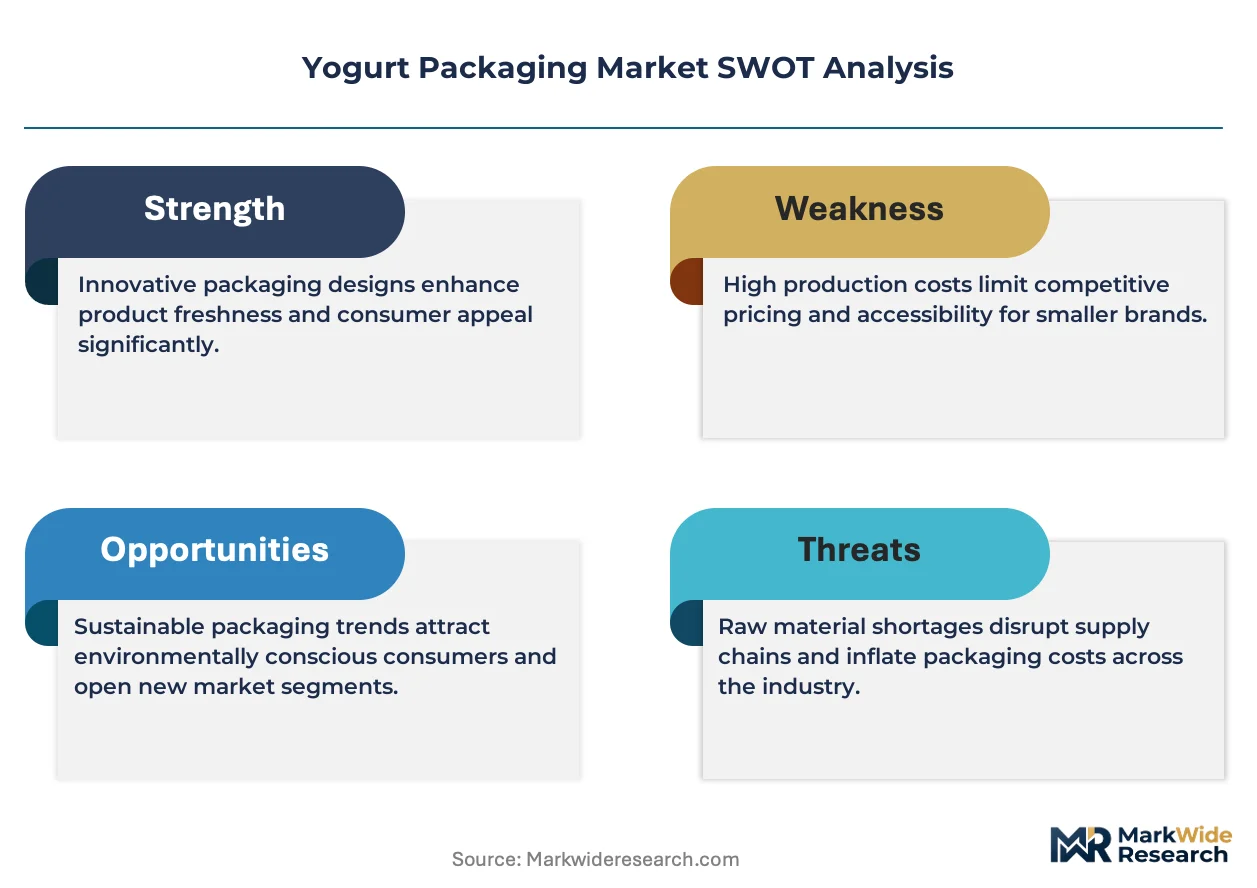
- Ethylene vinyl alcohol resin concentration:Asian petrochemical suppliers dominate EVOH copolymer supply, exposing European converters to feedstock volatility and currency risk.
- Multi-layer laminate incompatibility:Existing European mechanical recycling infrastructure cannot process aluminum-plastic yogurt pouch laminates, creating disposal cost penalties.
- Glass jar weight penalty:Cold-chain logistics operators impose surcharges on artisanal yogurt glass packaging, compressing margin for organic segment producers.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and D-Mart shelf space growth drives thermoforming capacity investment for single-serve cup formats in Maharashtra and Karnataka.
- Digital printing convergence:HP Indigo and Xeikon inkjet systems enable short-run SKU proliferation for private-label yogurt brands seeking seasonal packaging differentiation.
- Extended Producer Responsibility frameworks:French and Italian EPR fee structures reward mono-material packaging designs, incentivizing rPET cup development.
Industry Challenges
- Barrier chemist talent scarcity:European packaging converters face recruitment gaps for polymer scientists capable of formulating oxygen-blocking coatings without perfluorinated compounds.
- Legacy filling line integration:Dairy processors in the US Midwest struggle to adapt 1990s-era HFFS equipment for paperboard cup formats without complete line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yogurt Packaging Market |
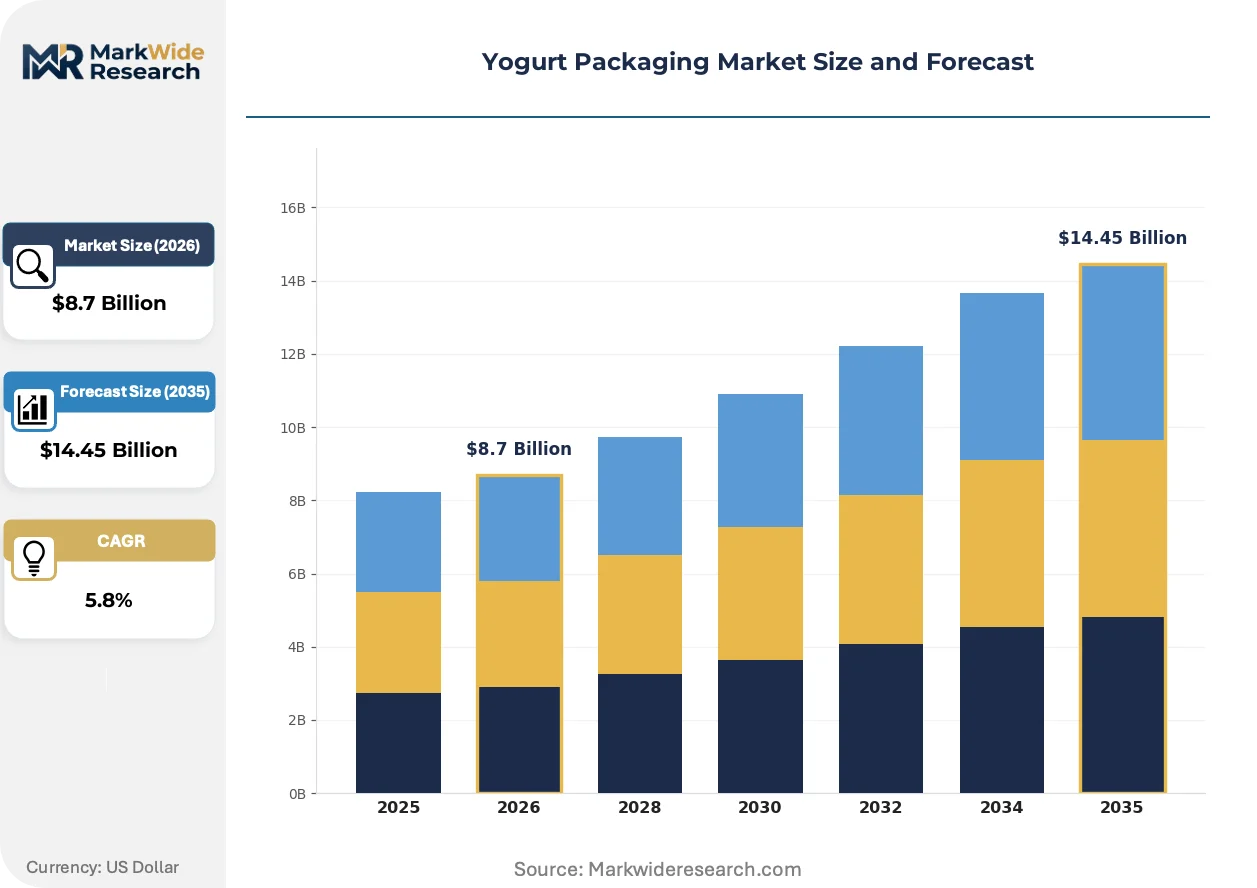
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cups, Jars, Pouches, Tubs Material: Plastic, Glass, Paperboard, Metal Closure Type: Screw Cap, Lid, Snap-On Cap, Twist-Off Cap End User: Retail, Food Service, B2B, Direct-to-Consumer |
| Companies Covered | WestRock Company, ELOPAK, Tetra Pak, Bemis Company Inc., Nampak Ltd., Mondi Group, Huhtamaki Group, Ahlstrom, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yogurt Packaging Market Evolving Landscape
Active and intelligent packaging technologies are rewriting shelf-life economics for ambient and chilled yogurt segments, while regulatory chemistry restrictions force material scientists toward bio-based barrier alternatives.
Mono-material polypropylene cups with vacuum-deposited silicon oxide barriers are collapsing the technical justification for multi-layer EVOH laminates in refrigerated yogurt applications. German private-label dairies including Aldi Süd and Lidl suppliers have validated 12-month shelf-life performance, triggering specification reviews across Northern European retail chains. The shift is collapsing barrier material supplier margins as silicon oxide deposition equipment manufacturers capture value previously held by resin compounders.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in polystyrene cup expansion, compelling thermoformers to adopt CO2 or hydrocarbon alternatives. Italian and Spanish converters face capital equipment decisions by 2027 to maintain compliance. The restriction hits expanded polystyrene yogurt cup producers hardest, accelerating migration toward solid-phase polypropylene and PET formats that bypass blowing agent chemistry entirely.
Direct-to-retailer procurement contracts are displacing traditional distributor intermediaries in North American yogurt packaging supply. Kroger, Walmart, and Costco now negotiate directly with Huhtamaki and Berry Global for store-brand cup and lid supply, compressing regional packaging distributor margins. The pattern is most visible in the US Southeast, where Publix Super Markets has consolidated yogurt packaging procurement through centralized category management teams.
Yogurt Packaging Market Segmentation
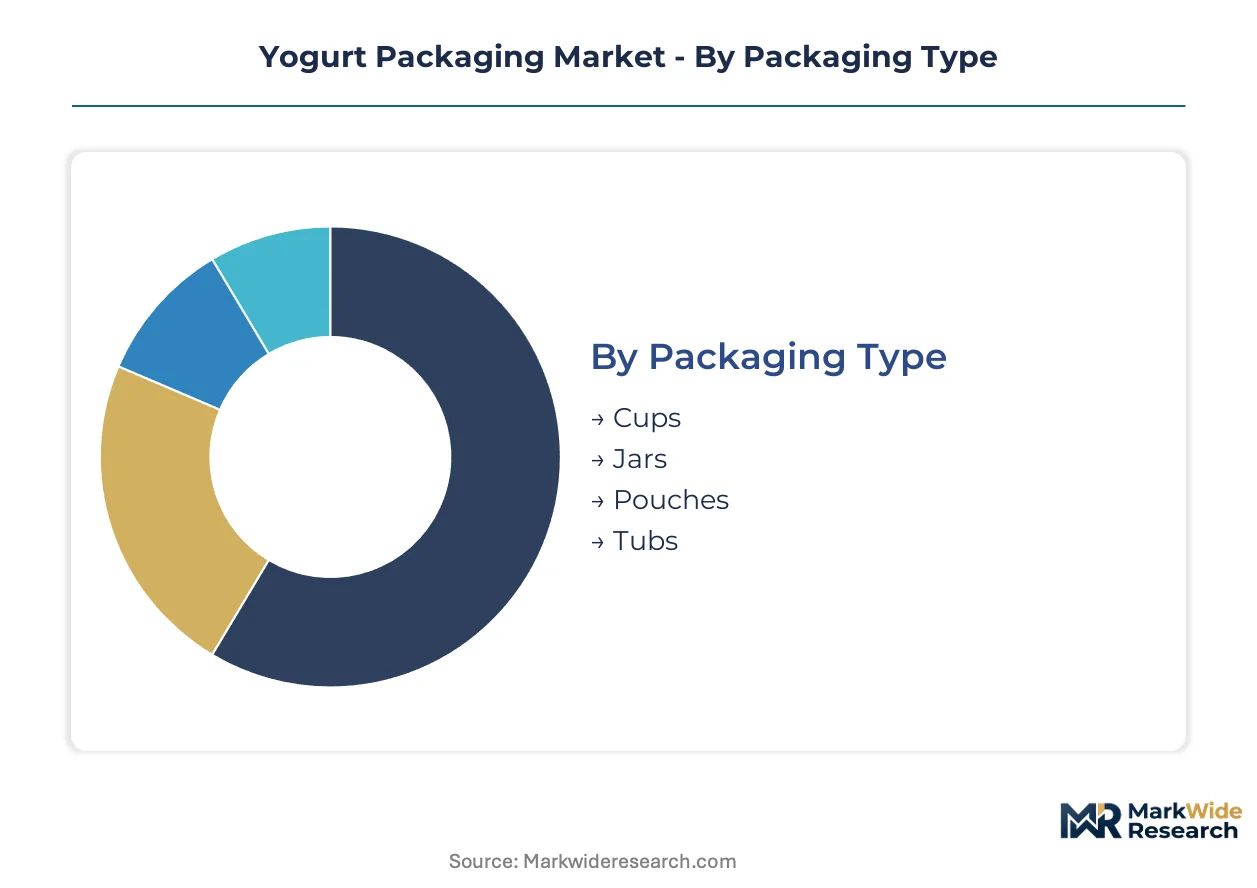
Yogurt packaging segmentation reflects divergent cold-chain requirements, consumption occasions, and sustainability mandates across retail and foodservice channels. Material and format selection directly determines shelf-life performance, logistics economics, and compliance with evolving extended producer responsibility frameworks.
Packaging Type:
Use-case spectrum spans single-serve convenience to bulk household formats, with rigidity and barrier requirements varying by distribution temperature and consumption setting.
- Cups:Thermoformed polystyrene or polypropylene structures dominate refrigerated retail shelves through portion-controlled 100-150g formats. German dairy processors at Aldi Süd and Lidl suppliers are retrofitting filling lines to accommodate mono-material polypropylene cups with silicon oxide barriers, responding to EU Single-Use Plastics Directive pressures.
- Pouches:Flexible multilayer laminates with spout fitments address on-the-go consumption where lightweighting overrides rigidity requirements. Drinkable yogurt adoption across Southeast Asian ambient distribution channels drives specification demand for high-barrier aluminum-plastic laminates that withstand tropical logistics without refrigeration.
- Jars:Molded glass containers retain premium positioning in organic and artisanal segments where material authenticity commands shelf price separation.
- Tubs:Injection-molded polypropylene containers serve family-size and bulk yogurt formats through club retail channels.
The dominant share belongs to cups, while pouches are closing the gap fastest.
Material:
Cost tier stratification separates mass-market polymer deployment from premium substrate alternatives that carry sustainability certifications or aesthetic differentiation.
- Plastic:Polypropylene, polystyrene, and polyethylene terephthalate constitute the volume base through thermoformed cups, injection-molded tubs, and flexible pouches. REACH chemical restrictions and EU F-Gas Regulation are accelerating migration from expanded polystyrene toward solid-phase polypropylene and recycled PET formats.
- Paperboard:Liquid packaging board with aluminum oxide or ethylene vinyl alcohol copolymer barriers enables aseptic carton formats for ambient yogurt distribution. Tetra Pak leverages this substrate expertise across Indonesian, Vietnamese, and Thai markets where cold-chain infrastructure remains underdeveloped.
- Glass:Soda-lime containers serve organic segment producers despite cold-chain logistics surcharges that compress margins.
- Metal:Tinplate and aluminum formats retain niche deployment for specialty yogurt products requiring extended ambient stability.
Plastic retains volume leadership, though paperboard is expanding most quickly in European retail conversion programs.
Closure Type:
Application context determines resealability requirements, with consumption occasion and pack size driving specification divergence between single-serve and multi-serve formats.
- Lid:Die-cut aluminum foil or polymer membranes heat-sealed to cup rims provide tamper evidence and oxygen barrier for single-serve refrigerated formats. Indian organized retail expansion through Reliance Retail and D-Mart is concentrating procurement of lidded thermoformed cups in Maharashtra and Karnataka.
- Screw Cap:Injection-molded polypropylene or polyethylene closures with continuous threads enable resealability for drinkable yogurt pouches and larger tubs. Huhtamaki Group specifications dominate this segment through high-barrier pouch formats with integrated spout-cap assemblies.
- Snap-On Cap:Press-fit polyethylene closures serve portion-controlled cups where resealability is secondary to opening convenience.
- Twist-Off Cap:Metal lug closures retain deployment in glass jar formats for premium organic positioning.
Lid formats command the installed base, while screw cap integration is gaining share fastest in drinkable yogurt proliferation.
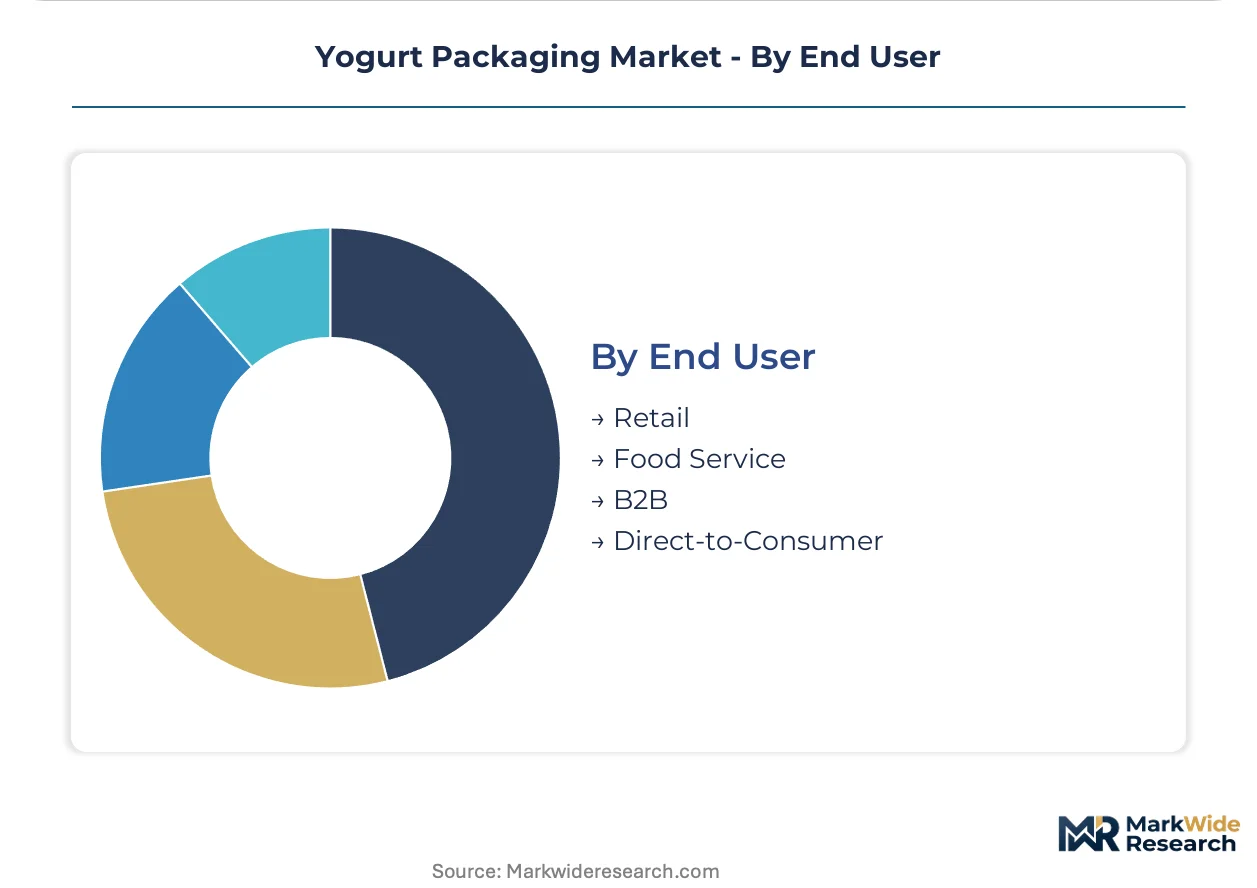
End User:
Customer type segmentation separates procurement patterns, with centralized category management displacing traditional distributor intermediaries in scale retail channels.
- Retail:Supermarkets, hypermarkets, and convenience stores constitute the primary demand channel through private-label and branded yogurt procurement. Kroger, Walmart, and Costco negotiate directly with converters for store-brand cup and lid supply, compressing regional packaging distributor margins in the US Southeast.
- Food Service:Hotels, restaurants, and institutional catering drive bulk tub and portion-controlled cup specifications with simplified graphics requirements.
- B2B:Ingredient and co-manufacturing supply to downstream dairy processors concentrates in industrial-scale pouch and bulk container formats.
- Direct-to-Consumer:Subscription and e-commerce channels are emerging with customized portion sizes and sustainable substrate mandates.
Retail holds the dominant position, while direct-to-consumer is climbing the fastest on digital-native brand proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, the United States, India, China, and Indonesia, with each geography responding to distinct regulatory pressures and consumption patterns that reshape substrate selection and filling line investments.
Germany
Aldi Süd and Lidl suppliers drive mono-material polypropylene cup adoption as private-label dairies retrofit Bavarian and North Rhine-Westphalia filling lines. The EU F-Gas Regulation accelerates polystyrene phase-out, compelling thermoformers in Baden-Württemberg to adopt CO2 blowing agents or abandon expanded foam entirely.
United States
Kroger, Walmart, and Costco consolidate yogurt packaging procurement through centralized category management, bypassing regional distributors in the Southeast. FDA food-contact substance notifications govern polymer migration limits, while Midwest dairy processors struggle to adapt legacy HFFS equipment for paperboard formats.
India
Reliance Retail and D-Mart shelf space expansion concentrates thermoforming demand in Maharashtra and Karnataka for single-serve lidded cups. BIS certification requirements for food-grade plastics create compliance thresholds for imported substrate formats, favoring domestic converter capacity additions.
China
Asian petrochemical suppliers dominate EVOH copolymer feedstock supply, exposing European converters to currency volatility. Domestic dairy brands in the Yangtze River Delta and Pearl River Delta drive high-barrier pouch specifications for ambient yogurt distribution through e-commerce channels.
Indonesia
Tetra Pak leverages aseptic carton expertise to anchor ambient yogurt distribution across Jakarta and Surabaya retail networks where cold-chain infrastructure remains underdeveloped. Tropical climate logistics sustain demand for aluminum-plastic laminates that withstand unrefrigerated distribution.
Yogurt Packaging Market Competitive Landscape
Integrated packaging conglomerates and specialized dairy substrate converters split the market between scale-driven aseptic carton supply and flexible format innovation. Consolidation pressures intensify as direct-to-retailer procurement contracts displace traditional distributor intermediaries. Three archetypes dominate: multinational material science conglomerates with captive resin supply, regional flexible packaging specialists with beverage dairy expertise, and molded fiber innovators targeting sustainability mandates. Competitive moves concentrate on filling line retrofit partnerships and mono-material barrier coating development.
Within the multinational conglomerate tier, Tetra Pak and Huhtamaki Group exemplify divergent strategic positions. Tetra Pak represents the aseptic carton archetype with established ambient distribution infrastructure across Southeast Asian markets. Huhtamaki Group occupies the flexible packaging specialist position, anchoring high-barrier pouch supply for drinkable yogurt segments. Mondi Group sits within the sustainable substrate innovation cluster, competing through molded fiber formats that address European private-label sustainability mandates.
| Leading Market Players |
|---|
| WestRock Company |
| ELOPAK |
| Tetra Pak |
| Bemis Company Inc. |
| Nampak Ltd. |
| Mondi Group |
| Huhtamaki Group |
| Ahlstrom |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp polymer corridor shapes cost dynamics across European yogurt packaging supply chains, concentrating EVOH resin pricing power among Asian petrochemical suppliers while downstream German dairies absorb freight premiums through private-label price differentiation.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across European yogurt packaging substrates, separating premium mono-material polypropylene cups with silicon oxide barriers from standard multi-layer laminates and economy-grade expanded polystyrene formats. Price differentiation hinges on compliance certification grade and cold-chain logistics integration, with organic segment glass jars commanding shelf premiums despite distribution surcharges. Pricing pressure intensifies downward as direct-to-retailer procurement contracts compress regional distributor margins, particularly in the US Southeast where Kroger and Walmart consolidate category management. Private-label buyers exhibit highest price sensitivity, while artisanal organic producers absorb premium substrate costs with least elasticity.
Supply Chain Analysis
Extended payment terms from German dairy processors to Baden-Württemberg thermoformers are tightening converter working capital, accelerating supply-chain finance facility adoption among mid-tier substrate suppliers. Raw material flows concentrate through China, South Korea, and Germany for EVOH copolymer, silicon oxide deposition equipment, and liquid packaging board respectively. The supply chain rests on Asian petrochemical feedstock for oxygen-barrier resins, exposing European converters to currency volatility and single-source vulnerability. Distribution runs through direct-retailer contracts displacing traditional distributor intermediaries in North American and Northern European channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier chemist talent scarcity constrains European converter capacity expansion, with polymer scientists capable of formulating perfluorinated-compound-free coatings commanding premium compensation packages that reshape competitive economics.
For Market Incumbents: Harden technical moats by acquiring silicon oxide deposition equipment manufacturers to capture value migrating from resin compounders, while retrofitting legacy filling line partnerships in Bavaria and North Rhine-Westphalia to lock in Aldi Süd and Lidl supplier relationships against molded fiber substitutes from Mondi Group. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian thermoforming capacity for single-serve lidded cups serving Reliance Retail and D-Mart expansion in Maharashtra and Karnataka, where BIS certification requirements create compliance barriers for imported substrates and favor domestic production partnerships with organized dairy retail. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core dairy substrate divisions, particularly European converters with stranded polystyrene assets facing EU F-Gas Regulation compliance deadlines. Long-term viability favors mono-material barrier coating specialists with validated retailer specifications. The inflection signal to monitor is silicon oxide deposition equipment order backlogs from German private-label dairies.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Development | Silicon oxide deposition expertise captures value previously held by EVOH resin suppliers. |
| Filling Line Retrofit Partnership | German dairy processor upgrades in Bavaria validate paperboard and recyclable polymer substrates. |
| Direct-to-Retailer Procurement Contract | Kroger and Walmart consolidation in the US Southeast compresses regional distributor margins permanently. |
| Sustainable Substrate Certification | French and Italian EPR fee structures reward mono-material rPET cup designs with cost advantages. |
| Tropical Climate Distribution Infrastructure | Tetra Pak anchors ambient yogurt supply across Indonesian and Vietnamese retail networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, customs trade data, and dairy processor capital expenditure disclosures, combining interviews with packaging converter plant managers, German dairy procurement leads, and retail category buyers with validation from ECHA restriction proposals and BIS certification records. Bottom-up substrate demand modeling triangulates against top-down cold-chain logistics capacity assessments.
Forecast inputs incorporate packaging format substitution rates, regulatory compliance deadlines, and filling line retrofit timelines across the projection horizon. Segmentation dimensions span material substrate, pack format, closure type, and end-user channel, with CAGRs derived from installed base turnover analysis and retailer procurement contract velocity. Industry-specific inputs include EU Single-Use Plastics Directive implementation pacing and EVOH resin supply concentration metrics.
Macroeconomic conditions sit as an overlay; deviation in freight rates, polymer feedstock pricing, or dairy commodity costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and recycling infrastructure deployment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Europe Dairy Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Latin America Dairy Packaging Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Dairy Containers Market