
 Latin America Dairy Packaging Market | 2026-2036
Latin America Dairy Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Dairy Packaging Market Foresight
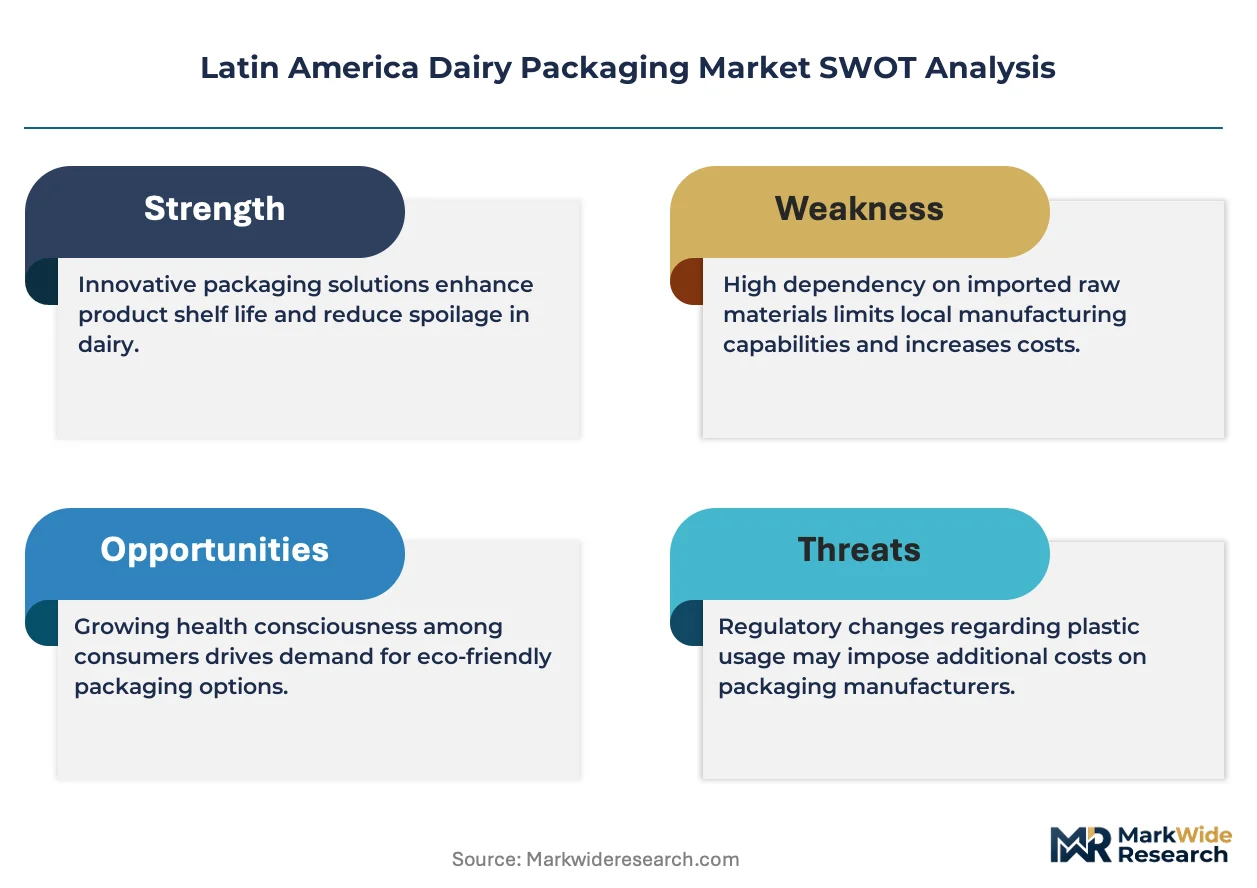
Subscription-based packaging maintenance and IoT-enabled shelf-life monitoring is hardening into a standard revenue layer for dairy packaging suppliers in Latin America. Tetra Laval Group leverages its aseptic technology leadership to anchor long-term service contracts across Brazilian cooperatives. Amcor PLC sustains competitive positioning through backward integration into recycled resin production for dairy bottles. Mondi PLC differentiates via lightweight paperboard innovations targeting Mexico's growing UHT milk segment.
Latin America dairy packaging encompasses the engineered containment, preservation, and distribution systems for fluid milk, fermented products, and shelf-stable dairy derivatives, typically employing multilayer barrier films with oxygen transmission rates below 0.5 cc/m²/day to prevent lipid oxidation and microbial spoilage during tropical supply chains. The primary commercial purpose centers on extending product viability from production through informal retail channels where cold chain continuity remains intermittent. Tetra Packs dominate volume in Brazil and Mexico due to ambient distribution economics, while pouches capture fastest growth in value-oriented Colombian and Peruvian markets where flexible formats reduce unit costs. Plastic bottles concentrate margin pools among premium organic and probiotic segments in Argentina and Chile, where transparent PET with UV barriers commands price premiums from health-conscious consumers.
Brazil's INMETRO enforces biodegradability certification for food-contact materials, while Mexico's PROFECO monitors labeling accuracy and net content compliance across dairy SKUs, collectively elevating technical barriers for imported packaging substrates. ANVISA in Brazil and COFEPRIS in Mexico coordinate sanitary registrations that dictate permissible additives in plastic dairy contact layers, directly influencing resin formulation decisions by converters. Stakeholders must monitor evolving extended producer responsibility frameworks across Mercosur and Pacific Alliance jurisdictions to preempt compliance-driven cost restructuring.
Market Dynamics
Extended shelf-life milk adoption across Brazilian retail chains is compressing cold-chain dependency and rewiring distribution economics for packaging converters throughout the region.
Growth Catalysts
- INMETRO biodegradability mandates:Brazil's certification requirements for food-contact materials are pulling converters toward certified substrates and creating technical differentiation among compliant suppliers.
- UHT ambient distribution:Tetra Pack formats bypass refrigeration infrastructure gaps across informal retail channels, unlocking volume in secondary cities and rural catchments.
- Southeastern dairy belt concentration:São Paulo and Minas Gerais states generate packaging procurement clusters that reward localized converter capacity and just-in-time logistics.
Market Restraints
- Recycled resin input volatility:Post-consumer rPET and rHDPE availability fluctuates with informal collection infrastructure, squeezing margin predictability for bottle converters.
- Multilayer film technical barriers:Oxygen transmission rates below 0.5 cc/m²/day require specialized coextrusion equipment that concentrates supply among a limited equipment vendor base.
- PROFECO labeling enforcement:Mexico's net content verification protocols add compliance overhead that extends SKU approval timelines for imported packaging substrates.
Strategic Opportunities
- Peruvian and Colombian pouch penetration:Value-oriented flexible formats remain underdeveloped relative to Brazil and Mexico, offering first-mover positioning for lightweight barrier solutions.
- IoT-enabled shelf-life monitoring:Connected packaging integrating temperature-logging sensors creates subscription revenue streams and locks in long-term service relationships with cooperatives.
- Extended producer responsibility frameworks:Emerging Mercosur and Pacific Alliance waste policies will mandate design-for-recyclability, rewarding early compliance investments with preferential supplier status.
Industry Challenges
- Coextrusion technician scarcity:Multilayer barrier film production requires specialized operators that training pipelines across Brazil and Mexico fail to replenish at sufficient velocity.
- ANVISA-COFEPRIS registration synchronization:Divergent sanitary approval timelines for plastic additives across Brazil and Mexico force dual-track formulation development that fragments R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Dairy Packaging Market |
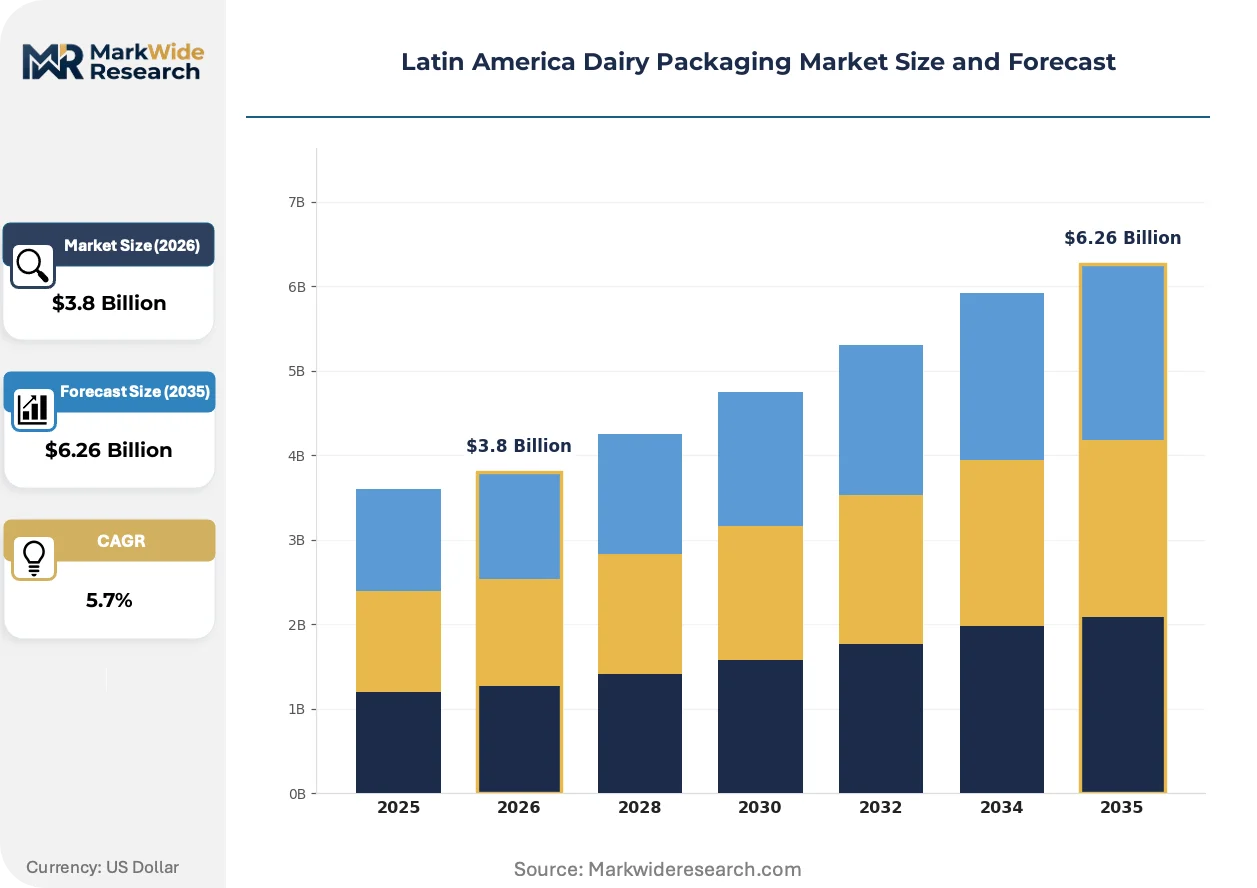
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Pouches, Tetra Packs, Containers Material: Plastic, Glass, Metal, Paper Board End User: Retail, Food Service, Households, Manufacturers Closure Type: Screw Caps, Snap-On, Heat Seal, Others |
| Companies Covered | Amcor PLC, Mondi PLC, Berry Global Inc, Smurfit Kappa, Tetra Laval Group, Sonoco Products Company, AptarGroup Inc, Winpak Ltd, CAN-PACK SA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Dairy Packaging Market Shifts & Advancements
Active and intelligent packaging systems are migrating from pilot programs to commercial deployment, embedding sensing and communication capabilities directly into dairy containment formats.
Smart labels incorporating time-temperature indicators are absorbing monitoring functions previously handled by external logistics systems. Brazilian cooperatives are piloting these formats for extended shelf-life milk routes where cold-chain gaps persist. The technology is absorbing liability exposure from spoilage claims while generating data assets that converters monetize through subscription analytics.
PROFECO and ANVISA are tightening additive disclosure requirements for plastic food-contact layers, forcing resin formulators to document migration testing across tropical storage conditions. This regulatory compression is elevating technical documentation burdens but simultaneously advantaging converters with in-house polymer laboratories. Mid-tier suppliers without captive testing capacity face outsourcing costs that erode competitiveness in price-sensitive segments.
Retail chains in São Paulo are consolidating packaging procurement through centralized technical specifications rather than brand-level sourcing. This buyer concentration is compressing supplier rosters and rewarding converters with pan-SKU service capabilities. The shift is most visible among supermarket cooperatives that now mandate uniform barrier performance standards across private-label dairy lines.
Latin America Dairy Packaging Market Segmentation
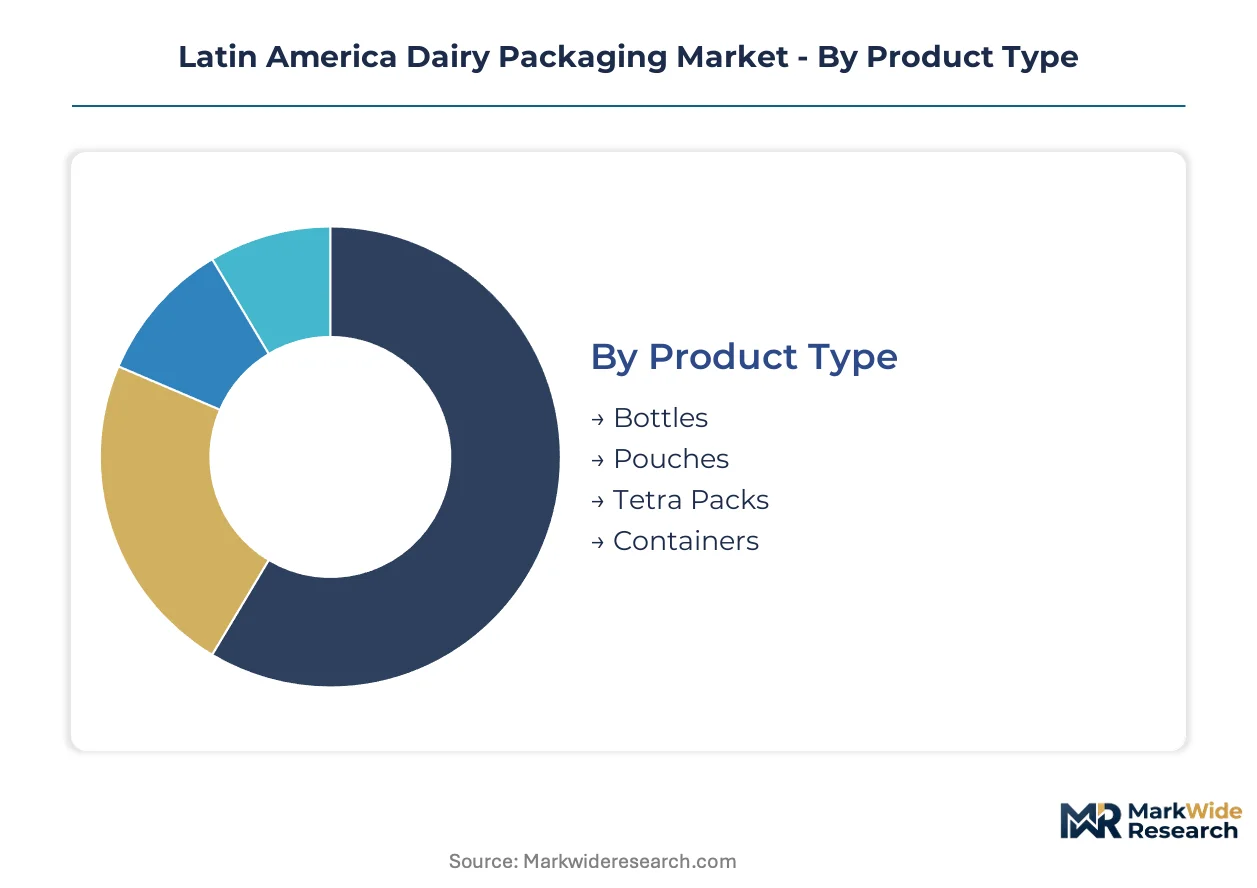
Packaging format selection in Latin American dairy markets hinges on cold-chain reliability, ambient distribution economics, and retail channel structure. Each segment category carries distinct technical requirements and regulatory compliance burdens that shape converter specialization and procurement patterns.
Product Type:
Upgrade cycles in dairy packaging track refrigeration infrastructure maturity and retail format evolution across the region's heterogeneous distribution landscape.
- Bottles:PET and HDPE formats dominate premium organic and probiotic segments in Argentina and Chile. Transparent structures with UV barriers command price premiums from health-conscious consumers in supermarket channels.
- Pouches:Multilayer barrier films with oxygen transmission rates below 0.5 cc/m²/day enable ambient distribution of UHT milk in Colombia and Peru. Value-oriented flexible formats reduce unit costs for informal retail penetration.
- Tetra Packs:Aseptic carton systems anchor volume in Brazil and Mexico, bypassing refrigeration gaps through ambient-stable multilayer paperboard laminates.
- Containers:Rigid plastic and paperboard tubs concentrate in fermented dairy applications across São Paulo's dairy belt, serving yogurt and fresh cheese segments.
Tetra Packs sit at the top of the volume ranking, with Pouches climbing the fastest.
Material:
Material compliance costs diverge sharply across Mercosur and Pacific Alliance jurisdictions, forcing converters to maintain parallel certification portfolios.
- Plastic:rPET and rHDPE availability fluctuates with informal collection infrastructure, squeezing margin predictability for bottle converters serving Brazilian retail chains.
- Glass:Premium positioning in Argentine organic dairy segments leverages perceived purity and reusability credentials, though weight penalties limit distribution radius.
- Metal:Tinplate and aluminum concentrate in evaporated milk and condensed dairy applications, with Costa Rican and Guatemalan processors maintaining regional canning capacity.
- Paper Board:Liquid packaging board with polyethylene barrier layers dominates Tetra Pack structures, with FSC certification increasingly mandatory for European retail chain suppliers.
Plastic commands the largest installed base, though Paper Board is gaining share fastest through aseptic carton expansion.
End User:
Procurement concentration among buyer types is restructuring supplier relationships, with retail cooperative technical specifications displacing brand-level sourcing decisions.
- Retail:Supermarket cooperatives in São Paulo now mandate uniform barrier performance standards across private-label dairy lines, compressing supplier rosters.
- Food Service:Institutional buyers in Mexico City and Lima prioritize portion-control formats and extended ambient stability for HORECA channel distribution.
- Households:Direct-to-consumer subscription models in Buenos Aires and Santiago are piloting refillable glass and returnable PET systems.
- Manufacturers:Dairy processors in Minas Gerais and Jalisco states source packaging through centralized procurement functions that reward pan-SKU service capabilities.
Retail anchors procurement volume, while Food Service is expanding most quickly through institutional channel growth.
Closure Type:
Closure selection interfaces directly with shelf-life extension targets and resealability requirements across ambient and chilled distribution pathways.
- Screw Caps:HDPE and PP threaded closures dominate refillable and family-size formats in Brazilian and Mexican retail channels, enabling multiple-use convenience.
- Snap-On:Lightweight polypropylene designs concentrate in single-serve pouch and portion-cup applications for Colombian and Peruvian value segments.
- Heat Seal:Induction and conduction sealing systems anchor aseptic carton and multilayer film structures, providing tamper-evidence for extended shelf-life milk routes.
- Others:Pour spouts, dispensing fitments, and tethered caps serve specialized fermented dairy and cream applications with viscosity-specific flow requirements.
Heat Seal leads in unit volume through Tetra Pack integration, with Screw Caps showing the steepest expansion trajectory through premium bottle growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands packaging procurement volume across Latin America, while Mexico's regulatory complexity creates higher compliance barriers for substrate suppliers entering that market.
Brazil
Extended shelf-life milk adoption across São Paulo and Minas Gerais retail chains is compressing cold-chain dependency and rewiring distribution economics. INMETRO enforces biodegradability certification for food-contact materials, pulling converters toward certified substrates. The southeastern dairy belt spanning São Paulo and Minas Gerais generates procurement clusters that reward localized converter capacity.
Mexico
UHT ambient distribution through informal retail channels unlocks volume in secondary cities and rural catchments where refrigeration infrastructure remains intermittent. PROFECO monitors labeling accuracy and net content compliance across dairy SKUs, elevating technical barriers for imported packaging substrates. Dairy processors in Jalisco state source packaging through centralized procurement functions.
Argentina
Premium organic and probiotic segments concentrate procurement among transparent PET bottles with UV barriers that command price premiums from health-conscious consumers. The national pharmaceutical regulator coordinates sanitary registrations dictating permissible additives in plastic dairy contact layers. Buenos Aires anchors direct-to-consumer subscription models piloting refillable glass systems.
Colombia
Value-oriented flexible pouch formats reduce unit costs for informal retail penetration, capturing fastest growth in barrier film demand. The national standards body oversees material compliance requirements that reshape converter specialization. Bogotá-based cooperatives drive procurement concentration for multilayer films with oxygen transmission rates below 0.5 cc/m²/day.
Chile
Health-conscious supermarket channels sustain transparent PET bottle demand for premium dairy positioning. Environmental regulators enforce extended producer responsibility frameworks that mandate design-for-recyclability. Santiago anchors subscription-based packaging maintenance pilots integrating IoT-enabled shelf-life monitoring.
Latin America Dairy Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aseptic technology leaders anchoring long-term service contracts while resin-integrated converters compete on material compliance. The vendor base concentrates among three strategic archetypes: multinational packaging conglomerates with pan-regional service networks, regional converters with localized biodegradability certification, and specialized barrier film technicians with captive coextrusion equipment. M&A activity targets additive formulation capabilities, while capacity expansion concentrates in São Paulo's logistics corridor.
Within the multinational tier, Tetra Laval Group and Amcor PLC exemplify divergent strategic positioning—one leveraging aseptic technology leadership for service contract anchoring, the other sustaining competitive positioning through backward integration into recycled resin production. Mondi PLC occupies a position among paperboard specialists targeting Mexico's UHT milk expansion.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi PLC |
| Berry Global Inc |
| Smurfit Kappa |
| Tetra Laval Group |
| Sonoco Products Company |
| AptarGroup Inc |
| Winpak Ltd |
| CAN-PACK SA |
| Others |
Supply & Pricing Matrix
INMETRO biodegradability mandates in Brazil gate qualified supply access and premium-tier pricing for dairy packaging converters, compressing margins for uncertified competitors while rewarding early compliance investments with preferential procurement status from São Paulo supermarket cooperatives.
Pricing Analysis
Capacity additions in São Paulo's logistics corridor are reshaping price floors for multilayer barrier films, intensifying competition among certified converters. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified liquid packaging board from conventional substrates and uncertified alternatives. Pricing pressure stems from recycled resin input volatility squeezing bottle converter margins. Value-oriented Colombian and Peruvian buyers exhibit highest price sensitivity, while Argentine organic dairy segments absorb transparent PET premiums.
Supply Chain Analysis
Coextrusion technician scarcity across Brazil and Mexico constrains multilayer barrier film output, forcing reliance on limited equipment vendor networks. Supply concentrates in Brazil, Mexico, and Argentina, with resin formulation anchored in polymer laboratories near São Paulo and Jalisco. Raw material dependencies draw from post-consumer rPET streams, imported barrier additives, and liquid packaging board. Single-source vulnerability pervades specialized coextrusion equipment procurement. Distribution runs through centralized dairy processor procurement functions and retail cooperative specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America dairy packaging functions as a geographic-arbitrage play, with INMETRO certification costs in Brazil running substantially below Pacific Alliance compliance burdens in Mexico, creating margin expansion opportunities for cross-border substrate suppliers.
For Market Incumbents: To counter emerging regional converters with localized biodegradability certification, Tetra Laval Group and Amcor PLC should deepen backward integration into recycled resin production and anchor long-term service contracts through IoT-enabled shelf-life monitoring subscriptions. Certification investment in parallel ANVISA-COFEPRIS registration capabilities defends against dual-track formulation fragmentation. For New Entrants and Emerging Players: PROFECO labeling enforcement in Mexico opens a window for compliance-specialist converters to capture share among imported substrate suppliers facing extended SKU approval timelines. Peruvian and Colombian pouch penetration offers the most penetrable white-space, with value-oriented flexible formats underdeveloped relative to Brazil. Go-to-market positioning should target Bogotá-based cooperatives with lightweight barrier solutions and oxygen transmission guarantees below 0.5 cc/m²/day. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier suppliers without captive polymer laboratories, as regulatory documentation burdens erode competitiveness against integrated competitors. Long-term viability across the five-to-ten year window hinges on extended producer responsibility framework positioning. Acquisition targets should display early design-for-recyclability investments and Mercosur certification portfolios. The signal to watch is consolidation velocity among São Paulo supermarket cooperatives mandating uniform barrier standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin | Amcor PLC's captive rPET production insulates margin predictability from informal collection infrastructure volatility. |
| IoT-Enabled Shelf-Life Monitoring Deployment | Tetra Laval Group locks in Brazilian cooperative relationships through subscription-based temperature-logging sensor analytics. |
| Dual ANVISA-COFEPRIS Registration Investment | Converters with parallel sanitary approval capabilities avoid fragmented R&D resource allocation across Brazil and Mexico. |
| Lightweight Paperboard Innovation | Mondi PLC targets Mexico's UHT milk expansion with ambient-stable multilayer carton structures. |
| Extended Producer Responsibility Compliance | Early design-for-recyclability investments secure preferential supplier status under emerging Mercosur waste policies. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Colombia, and Chile, with primary inputs from each market combining interviews with dairy processor procurement directors, packaging converter plant managers, retail cooperative category buyers, and regulatory affairs specialists at ANVISA and COFEPRIS. Secondary validation draws from customs trade data, INMETRO certification registries, SEC filings of listed packaging conglomerates, and dairy industry association reports. Bottom-up volume estimates from SKU-level procurement patterns triangulate against top-down market sizing from national dairy production statistics.
Rate-of-change decomposition separates volume growth from value expansion across packaging format, material compliance tier, and end-user concentration dimensions. The analytical framework models CAGRs through regression of historical procurement data against refrigeration infrastructure buildout rates and extended shelf-life milk adoption curves. Forecast inputs include informal retail channel penetration metrics and biodegradable substrate cost parity timelines.
Revisions become necessary when INMETRO mandates accelerate biodegradability certification deadlines or when PROFECO enforcement intensifies net content verification protocols. Forecasts reflect assumptions about cold-chain infrastructure continuity and recycled resin collection system maturation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Europe Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Dairy Containers Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Machines Market