
 Dairy Containers Market | 2026-2036
Dairy Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Containers Market Outlook
Food-grade aseptic specification upgrades is redrawing competitive boundaries across the dairy containers landscape. Tetra Pak leverages its laminated carton technology leadership to dominate extended-shelf-life applications in emerging markets. Amcor plc anchors global supply security through its multi-material platform spanning HDPE and PET dairy bottles. Berry Global Inc. specializes in thin-wall injection-molded plastic jugs for high-volume fluid milk operations in North America.
Dairy containers are rigid or semi-rigid vessels engineered from food-contact-compliant polymers, coated paperboard, or glass, designed to preserve organoleptic properties through barrier control against oxygen, light, and moisture ingress. Their primary commercial function centers on extending shelf life while enabling efficient filling, distribution, and retail display of fluid milk, yogurt, cream, and cheese products. Carton formats lead in ambient distribution economics due to their rectangular stacking efficiency and fiber-based sustainability profile, while PET containers represent the fastest-growing material segment as brand owners convert from glass to reduce breakage and freight cost. HDPE plastic jugs remain the mature volume backbone in North American retail milk, though margin pools are compressing as resin volatility and lightweighting targets intensify.
The FDA's food-contact substance notification process governs polymer safety for US dairy packaging, while the EU Green Deal and Packaging and Packaging Waste Regulation mandate recyclability thresholds and recycled content minimums across European supply chains. India's FSSAI enforces contaminant limits and labeling standards that shape import eligibility and domestic converter qualification. Stakeholders must monitor how diverging extended producer responsibility schemes and deposit-return system expansions alter material economics and regional sourcing priorities.
Market Dynamics
Mono-material and fiber-based container designs are accelerating as the EU Packaging and Packaging Waste Regulation mandates recyclability thresholds, forcing converters to abandon multi-layer laminates and triggering capital reallocation across European and Asian supply chains.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content minimums and extended producer responsibility schemes are pulling investment into circular-ready container technologies across France, Germany, and Italy.
- Cold-chain infrastructure maturation:Organized retail expansion in India is creating pull for tamper-evident and aseptic dairy formats as urban distribution networks deepen.
- Lightweighting process advances:Thin-wall injection molding improvements are cutting resin consumption per unit while maintaining top-load strength for fluid milk logistics.
Market Restraints
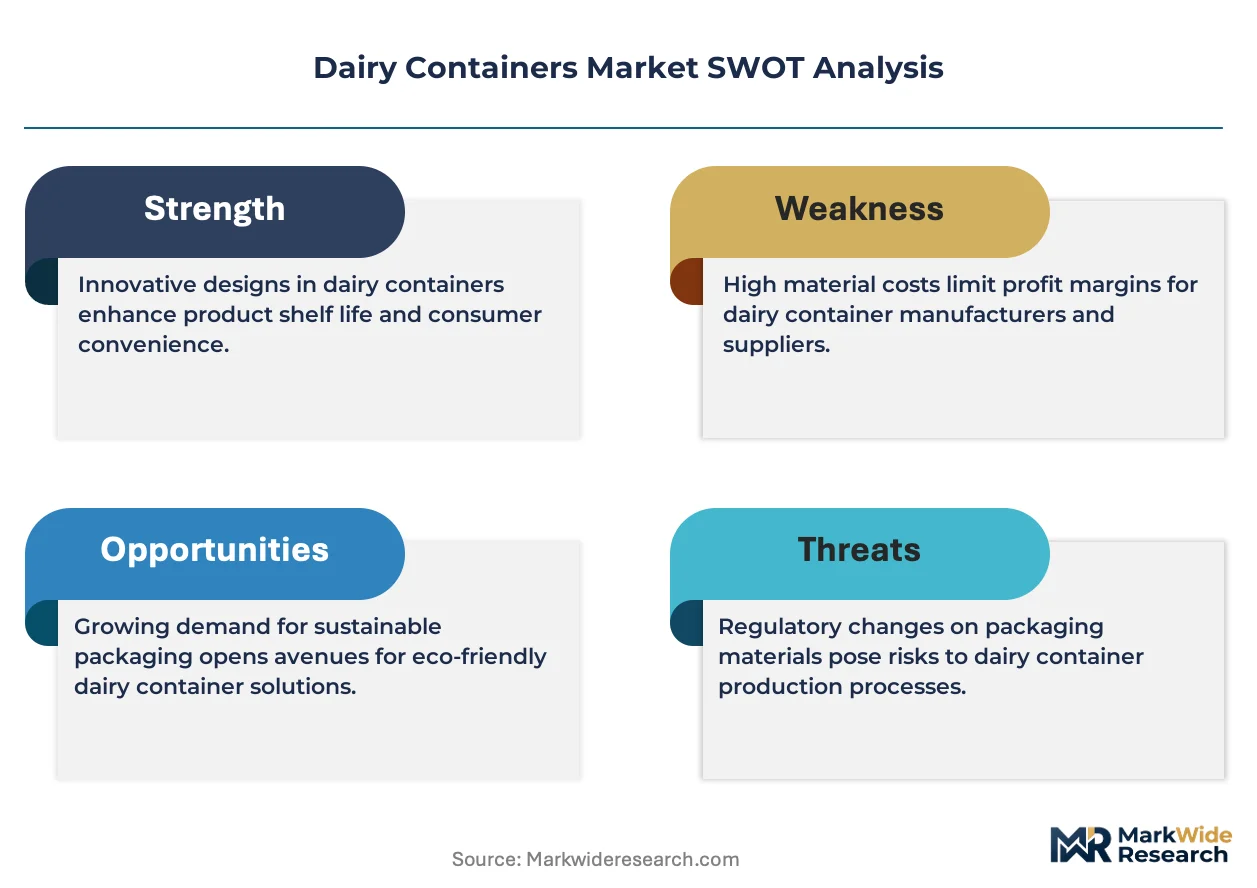
- Resin cost volatility:HDPE and PET feedstock price swings compress converter margins and destabilize annual contract negotiations with dairy processors.
- Multi-layer technical lock-in:Aseptic carton barrier performance depends on aluminum-polymer laminates that lack viable mono-material substitutes at commercial scale.
- Deposit-return system fragmentation:Incompatible state-level container recovery schemes in the US create compliance complexity and limit packaging standardization.
Strategic Opportunities
- India organized retail penetration:Tier-2 and Tier-3 city cold-chain buildout is opening addressable demand for extended-shelf-life carton and pouch formats.
- Paperboard-barrier convergence:Bio-based coatings and fiber-molded innovations are creating functional alternatives to plastic aseptic containers for ambient yogurt.
- Reusable container pooling:Returnable glass and stainless-steel systems are gaining regulatory support in France and Germany for fresh milk home delivery channels.
Industry Challenges
- Food-contact notification timelines:FDA clearance for novel barrier polymers stretches 18-24 months, delaying product launches and freezing R&D pipelines.
- Legacy filling line incompatibility:Retrofitting aseptic carton equipment for fiber-based alternatives requires seven-figure capital commitments and extended downtime.
- Recyclability certification complexity:Diverging How2Recycle, OPRL, and Green Dot standards force parallel testing regimes for multi-market product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Containers Market |
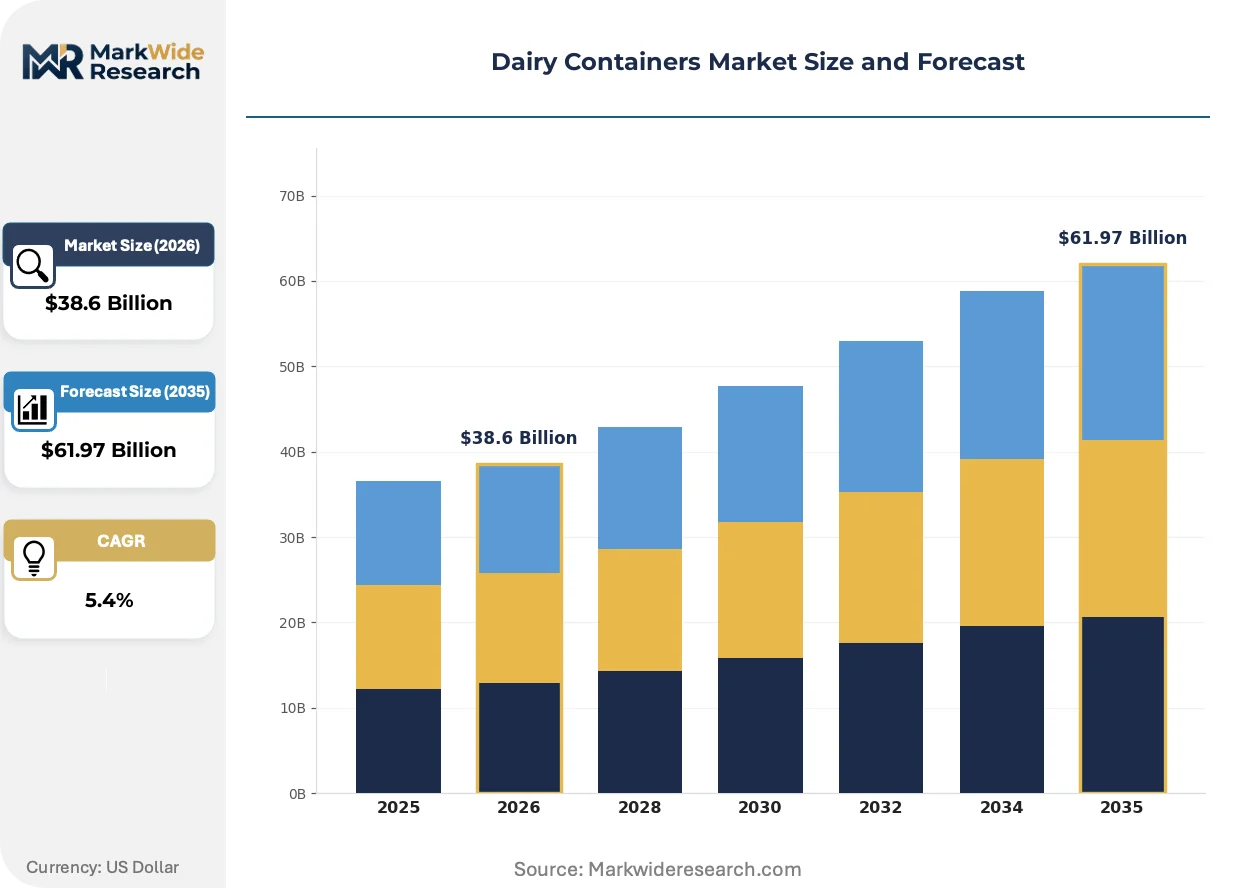
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Plastic Jugs, Glass Bottles, Cartons, Tetra Paks Material: HDPE, PET, Glass, Aluminum Volume Capacity: 200ml, 500ml, 1L, 2L End User: Retailers, Wholesalers, Restaurants, Direct Consumers |
| Companies Covered | Berry Global Inc., Amcor plc, Tetra Pak, Greiner Packaging, Sonoco Products Company, Smurfit Kappa, Sealed Air, Winpak Ltd, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Containers Market Strategic Shifts
Material science breakthroughs and regulatory compression are converging to redraw technical specifications and procurement criteria across dairy container categories.
PET container technology with enhanced oxygen-scavenging additives is displacing glass bottles in premium yogurt and flavored milk segments. European and Latin American brand owners are accelerating conversion programs to cut freight breakage and enable shelf-ready clarity. This displacement is compressing glass converter capacity while expanding blow-molding equipment orders.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from dairy lidstock and folding carton applications. European converters are qualifying silicone and bio-wax barrier alternatives ahead of enforcement deadlines. Fresh cheese and butter packaging categories face the steepest reformulation timelines and technical risk.
Direct-store-delivery networks are consolidating procurement authority into fewer dairy processor technical teams, compressing supplier rosters and lengthening qualification cycles. Regional cooperatives in the US Midwest and Nordic markets are centralizing packaging specification decisions. This concentration favors multi-material platform suppliers with integrated design and testing capabilities.
Dairy Containers Market Segmentation
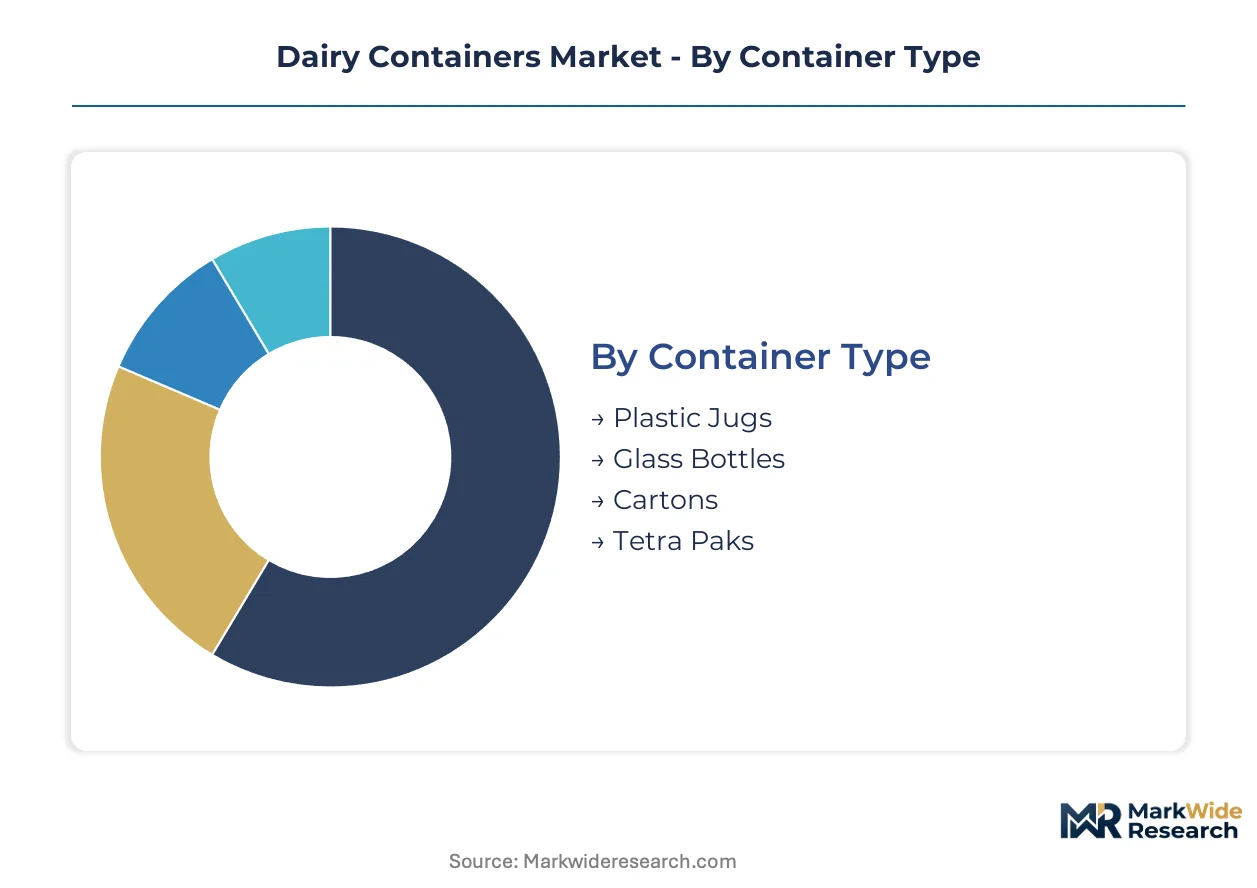
Container specifications in dairy packaging diverge sharply across regulatory jurisdictions, with FDA food-contact notifications governing polymer selection in the US while EU Green Deal mandates drive material transitions in European supply chains. Understanding how these regulatory fault lines map to container categories reveals procurement priorities and investment allocation patterns.
Container Type:
FDA clearance timelines and EU recyclability thresholds create divergent competitive dynamics across container formats, with converters optimizing for either speed-to-market or circular-economy compliance.
- Plastic Jugs:HDPE blow-molded vessels dominate North American fluid milk retail through lightweighting advances and established dairy-processor filling infrastructure. Demand concentrates in US Midwest cooperative networks where thin-wall injection molding cuts resin consumption per unit.
- Glass Bottles:Premium positioning and deposit-return system compatibility sustain glass in German and French fresh-milk home delivery channels despite freight cost penalties. Reusable pooling systems in Nordic markets are expanding returnable glass deployment.
- Cartons:Fiber-based rectangular formats optimize ambient distribution economics through pallet-stacking efficiency.
- Tetra Paks:Laminated aseptic cartons anchor extended-shelf-life applications in Indian organized retail expansion.
Plastic jugs handle the majority of throughput; Tetra Paks are gaining share fastest on emerging-market cold-chain maturation.
Material:
Cost tier differentiation separates commodity resins from performance polymers and alternative substrates, with resin volatility compressing margins at the commodity end while barrier innovation commands premium positioning.
- HDPE:High-density polyethylene remains the volume backbone for fluid milk jugs in North America, though lightweighting targets and resin price swings intensify margin pressure across converter operations.
- PET:Enhanced oxygen-scavenging additives enable PET displacement of glass in premium yogurt and flavored milk segments, with European brand owners accelerating conversion programs to cut freight breakage.
- Glass:Inert surface properties and regulatory acceptance for reusable systems sustain demand in deposit-return markets.
- Aluminum:Thin-gauge foil layers provide barrier performance in aseptic carton laminates pending mono-material substitution feasibility.
HDPE carries the volume base; PET climbs the fastest on premium segment conversion from glass.
Volume Capacity:
Customer type and consumption occasion drive capacity selection, with retail format scale and household size patterns shaping regional preference distributions.
- 200ml:Single-serve portions target on-the-go consumption and institutional channels, with Indian Tier-2 city retail expansion pulling demand for portion-controlled formats.
- 500ml:Mid-size capacity captures small-household and premium positioning segments in European markets.
- 1L:Standard household reference size dominates North American and European retail shelf sets.
- 2L:Family-size formats concentrate in US club-store and value-oriented retail channels where per-unit economics favor bulk purchasing.
1L formats anchor mainstream retail throughput; 200ml portions expand most quickly on emerging-market urbanization.
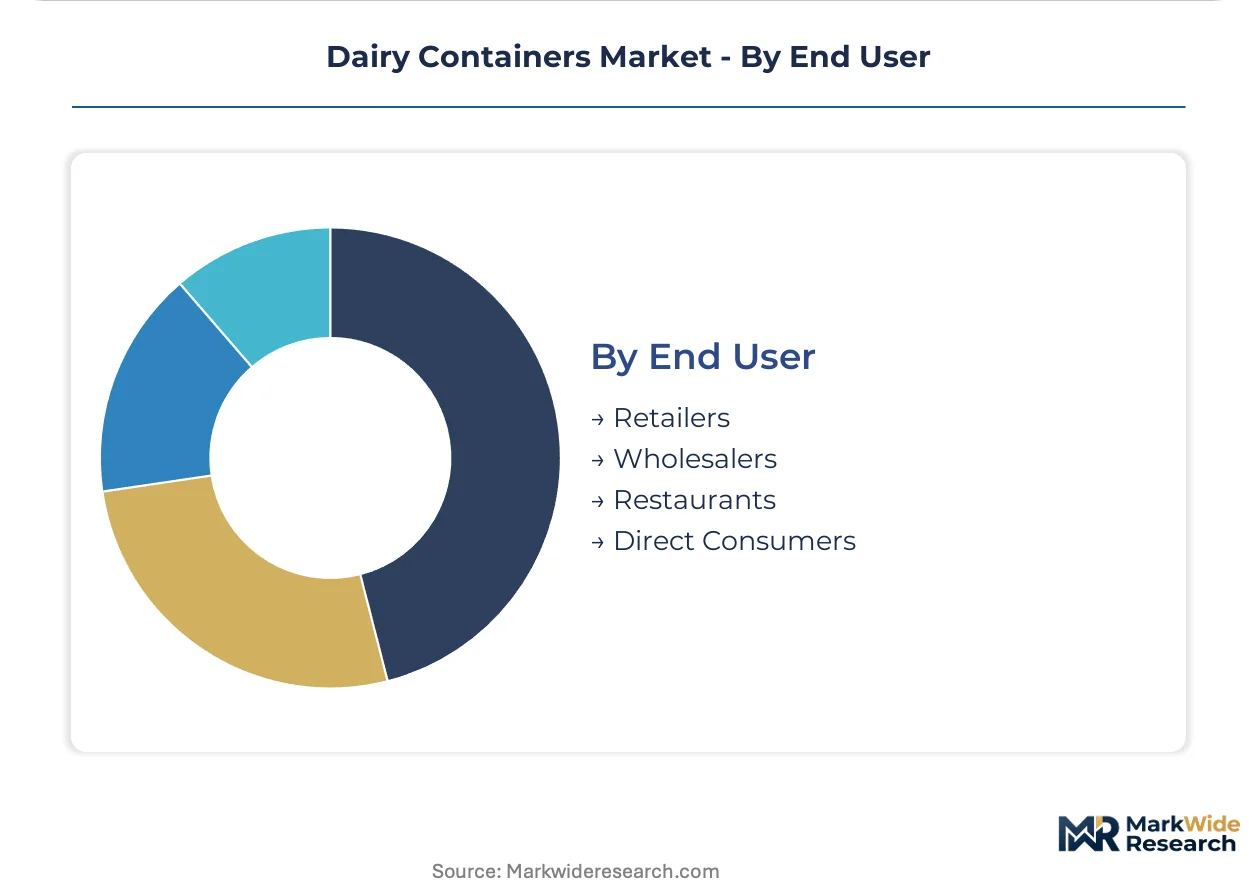
End User:
Procurement authority concentration into fewer dairy processor technical teams is reshaping supplier relationships across end-user categories, with direct-store-delivery network consolidation favoring integrated platform suppliers.
- Retailers:Supermarket and hypermarket chains command specification authority for shelf-ready packaging, with French and German central buying offices driving harmonized recyclability requirements across supplier bases.
- Wholesalers:Distribution intermediaries in Indian cold-chain networks are consolidating procurement for Tier-2 and Tier-3 city coverage, creating pull for aseptic carton and pouch formats.
- Restaurants:Foodservice operators prioritize portion control and storage efficiency in back-of-house configurations.
- Direct Consumers:Subscription milk delivery and farm-gate sales sustain reusable glass and stainless-steel systems in Nordic and German markets.
Retailers control the dominant procurement volume; wholesalers show the steepest expansion trajectory on Indian organized retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in dairy containers tilt toward deficit positions in emerging economies with expanding cold-chain networks, while established manufacturing clusters in Europe and North America anchor export capacity for aseptic and barrier technologies.
United States
Midwest dairy cooperatives drive demand for thin-wall HDPE jugs as fluid milk volumes concentrate in Illinois, Wisconsin, and Minnesota processing corridors. FDA food-contact substance notifications govern polymer approvals, extending qualification timelines for novel barrier materials. Chicago and Minneapolis-St. Paul host the dominant converter clusters serving retail and foodservice channels.
Germany
Deposit-return system expansion sustains reusable glass bottle networks for fresh milk home delivery across Bavaria and North Rhine-Westphalia. EU Green Deal packaging mandates and extended producer responsibility schemes accelerate mono-material transitions. The Baden-Württemberg region anchors fiber-based carton engineering capabilities for export markets.
India
Tier-2 and Tier-3 city retail penetration generates pull for aseptic carton and pouch formats as organized dairy distribution deepens. FSSAI contaminant limits and labeling standards shape import eligibility and domestic converter qualification. Maharashtra and Gujarat concentrate cold-chain infrastructure buildout and dairy processing capacity.
France
Premium yogurt and fresh cheese segments sustain demand for enhanced-barrier PET conversion from traditional glass. REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy grease-resistant coatings from dairy lidstock applications. The Île-de-France and Auvergne-Rhône-Alpes regions host specification authority for pan-European retail chains.
Brazil
Extended-shelf-life carton demand expands with supermarket penetration in São Paulo and Minas Gerais dairy belts. ANVISA food-contact regulations align with Mercosur technical standards for regional trade integration. The São Paulo state corridor concentrates blow-molding and liquid packaging board conversion capacity.
Dairy Containers Market Competitive Environment
Concentration sits with diversified packaging conglomerates and specialized dairy container engineers. The vendor base spans three tiers: integrated multi-material platforms with global supply security, regional specialists in thin-wall injection molding, and niche players in aseptic barrier laminates. Strategic moves center on portfolio diversification into fiber-based alternatives and geographic expansion into Indian organized retail corridors.
Among the integrated packaging conglomerates, Tetra Pak and Amcor plc occupy positions spanning aseptic carton and multi-material bottle platforms respectively. Berry Global Inc. sits within the North American specialist tier. These three entities exemplify the competitive archetypes reshaping procurement relationships as dairy processor technical teams consolidate specification authority.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| Tetra Pak |
| Greiner Packaging |
| Sonoco Products Company |
| Smurfit Kappa |
| Sealed Air |
| Winpak Ltd |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day resin inventory cycles in North American dairy container operations tether converter margins to spot HDPE and PET volatility, amplifying pricing power asymmetry between integrated multi-material platforms and regional thin-wall specialists serving Midwest dairy cooperatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the dairy container landscape. Three-tier pricing structure across premium, standard, and economy levels separates aseptic barrier laminates from commodity HDPE jugs and fiber-based cartons. Cost compression in standard-grade HDPE is intensifying because lightweighting targets and resin price swings compress converter margins. Dairy processor technical teams exhibit lowest price sensitivity for aseptic carton formats with extended-shelf-life barrier performance, while regional cooperatives drive hardest bargaining on high-volume fluid milk jug contracts.
Supply Chain Analysis
Sixty-to-ninety-day resin inventory cycles expose converters to feedstock volatility that shapes working capital requirements and margin stability. Manufacturing gravity centers on the United States, Germany, and India, with Baden-Württemberg anchoring fiber-based carton engineering and Maharashtra concentrating cold-chain infrastructure buildout. Converter operations draw from HDPE and PET resin feedstocks, aluminum foil barrier layers, and liquid packaging board substrates. Single-source vulnerability in aluminum-polymer laminate supply for aseptic cartons creates qualification risk as EU recyclability mandates force material transitions. Distribution runs through direct-store-delivery networks consolidating procurement authority into fewer dairy processor technical teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as direct-store-delivery networks consolidate procurement authority into fewer dairy processor technical teams, lengthening supplier qualification cycles and compressing vendor rosters across North American and Nordic markets.
For Market Incumbents: Compound barrier technology leadership in aseptic laminates with backward integration into bio-based coating R&D to outpace REACH-driven PFAS elimination timelines. Add fiber-molded capacity in Baden-Württemberg or Maharashtra to capture EU Green Deal and Indian organized retail expansion simultaneously. The priority lever sits with qualifying mono-material substitutes before multi-layer technical lock-in hardens. For New Entrants and Emerging Players: Lead with paperboard-barrier convergence for ambient yogurt applications in French and German premium segments where REACH restrictions eliminate legacy grease-resistant coatings. Target Indian Tier-2 and Tier-3 city wholesale channels for aseptic pouch formats as cold-chain infrastructure matures. A certification-first go-to-market angle accelerates FSSAI qualification and domestic converter partnership. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fiber-based aseptic container engineering as EU recyclability thresholds force equipment retrofits and seven-figure filling line downtime. Long-term viability favors platform suppliers with integrated multi-material capabilities spanning HDPE, PET, and coated paperboard rather than single-technology specialists. The signal to watch is FDA food-contact notification clearance velocity for novel barrier polymers as a proxy for R&D pipeline health.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Expansion | EU Packaging and Packaging Waste Regulation recyclability thresholds force abandonment of multi-layer laminates. |
| India Cold-Chain Infrastructure Partnership | Tier-2 and Tier-3 city retail penetration creates pull for tamper-evident aseptic carton formats. |
| Bio-Based Barrier Coating R&D Investment | REACH PFAS restrictions eliminate legacy grease-resistant coatings from dairy lidstock applications. |
| Direct-Store-Delivery Network Consolidation | Procurement authority concentration favors integrated platform suppliers with multi-material capabilities. |
| Reusable Container Pooling System Launch | Deposit-return system expansion in Germany and France sustains returnable glass networks for fresh milk delivery. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with dairy processor technical directors, converter plant managers, retail category buyers, cold-chain logistics specialists, and regulatory affairs leads. Secondary validation drew from FDA food-contact substance notification filings, EU Packaging and Packaging Waste Regulation impact assessments, FSSAI contaminant limit circulars, and customs trade data for resin and liquid packaging board flows. Bottom-up volume modeling triangulated against top-down market sizing across container type, material, and capacity dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by container type, material substrate, volume capacity tier, end-user channel, and geographic regulatory cluster. CAGRs were derived from trend extrapolation anchored in disclosed capital expenditure patterns and capacity expansion timelines. Key inputs included cold-chain infrastructure buildout velocity in Indian Tier-2 cities, EU extended producer responsibility scheme implementation pace, and lightweighting process advance adoption rates in North American fluid milk operations.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain investment in emerging markets or accelerated mono-material substitution feasibility would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and resin price regime stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Packaging
Dairy Products Packaging Market
Dairy Packaging
Europe Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Machines Market
Dairy Packaging
Yogurt Packaging Market
Dairy Packaging
United States Dairy Packaging Market
Dairy Packaging
North America Dairy Packaging Market
Dairy Packaging
Milk Powder Packaging Market
Dairy Packaging
Milk Packaging Market
Dairy Packaging
Dairy Packaging Market
Dairy Packaging
Latin America Dairy Packaging Market