
 Content Creation Market | 2026-2036
Content Creation Market Size, Share, and Industry Trends Forecast 2026-2036
Content Creation Market Analysis
The EU AI Act is recalibrating compliance burdens for generative content platforms, forcing new transparency layers and human-in-the-loop requirements that raise fixed costs for entrants. Runway AI leverages its native video-generation stack to anchor technical leadership in multimodal output. Siege Media sustains dominance in long-form SEO content through specialized editorial workflows and direct publisher relationships. Omniscient Digital differentiates by controlling end-to-end B2B content strategy rather than competing on per-article pricing alone.
Content creation encompasses the ideation, production, editing, and distribution of material across digital channels, typically rendered through text-based editors, nonlinear video systems, or generative neural networks operating on latent diffusion and transformer architectures. Its primary commercial purpose is to capture audience attention, convey brand narratives, and convert engagement into measurable business outcomes across paid, owned, and earned media. Video as a content type now commands the largest share of production budgets as platforms prioritize motion-based feeds and shoppable formats. Interactive delivery formats represent the fastest-expanding structural category, driven by embedded personalization engines and real-time audience response tools. The business target audience segment carries the deepest margin pools, given longer contract cycles and integrated strategy mandates that consumer-facing creators rarely secure.
The Federal Trade Commission in the United States enforces disclosure standards for sponsored and AI-generated material, while the European Union's Digital Services Act imposes systemic transparency obligations on large content distribution platforms. These frameworks shape product roadmaps by mandating provenance labeling, altering monetization eligibility, and restricting certain automated amplification techniques. Stakeholders must monitor emerging jurisdictional fragmentation in content authenticity rules to determine where to centralize compliance infrastructure and where to localize operations.
Market Dynamics
Generative neural architectures operating on transformer and diffusion models are compressing production timelines from weeks to hours, forcing legacy editorial workflows and agency retainers into structural obsolescence.
Growth Catalysts
- EU AI Act transparency mandates:Provenance labeling requirements create first-mover advantages for platforms that architect compliance-native systems from inception rather than retrofitting legacy stacks.
- Enterprise marketing team procurement:Direct platform adoption displaces traditional agency intermediaries as buyers demand integrated strategy-to-distribution control.
- Shoppable video formats:Platform algorithmic prioritization of motion-based feeds concentrates advertising spend toward native video production tooling.
Market Restraints
- Compute infrastructure concentration:GPU cluster access bottlenecks through hyperscaler cloud providers create input cost volatility for training and inference workloads.
- Training data licensing friction:Copyright ambiguity around scraped corpora generates legal exposure that reinsurance markets now explicitly exclude from coverage.
- Human-in-the-loop compliance costs:The EU AI Act's oversight requirements impose fixed operational overhead that scales disproportionately for smaller platform entrants.
Strategic Opportunities
- Interactive personalization engines:Real-time audience response tooling remains underdeployed in B2B content verticals outside technology and financial services.
- India's creator-economy infrastructure:Dense mobile-first consumption patterns and venture-backed tooling ecosystems offer expansion white space for localized platform entrants.
- Convergence of latent diffusion and retrieval-augmented generation:Hybrid architectures enable factual grounding in long-form editorial workflows previously resistant to pure generative output.
Industry Challenges
- Multimodal prompt engineering expertise:Cross-functional talent capable of orchestrating text, image, and video generation pipelines commands scarcity premiums that compress margin structures.
- Legacy CMS integration complexity:Enterprise content management systems built on decade-old architectures resist API-native connectivity with generative platforms.
- Provenance authentication standardization:Competing technical specifications from Coalition for Content Provenance and Authenticity and proprietary platform schemes fragment interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Creation Market |
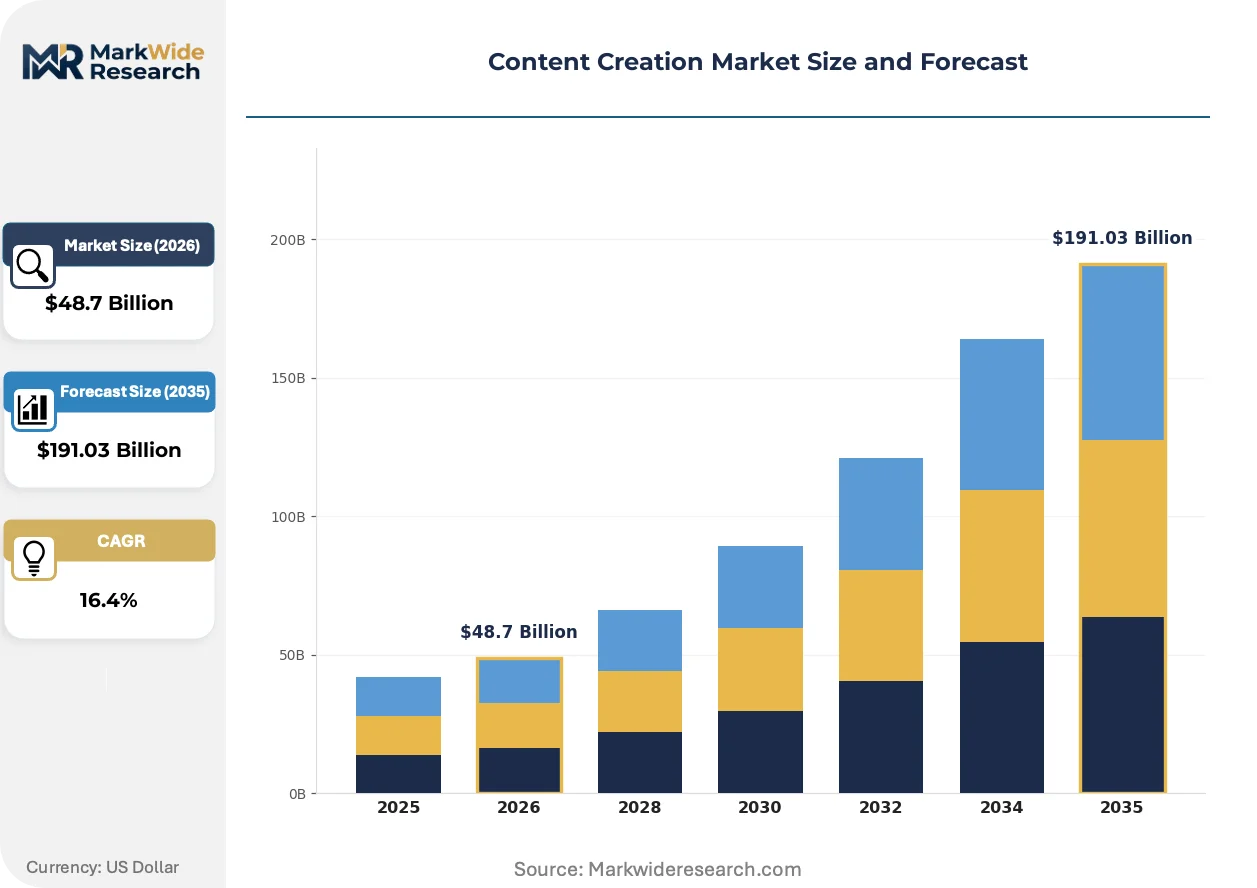
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video, Blog, Social Media Post, Podcast Delivery Format: Written, Visual, Audio, Interactive Target Audience: Consumers, Businesses, Educators, Influencers Industry Vertical: Technology, Entertainment, Education, Healthcare |
| Companies Covered | Siege Media, Runway AI, Omniscient Digital, Contentoo, The Goat Agency, Brafton, Column Five, Ten Speed, Foundation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Creation Market Emerging Trajectories
Multimodal generation stacks are collapsing the traditional boundaries between creative disciplines, enabling single-operator production workflows that previously required specialized agency silos.
Latent diffusion architectures combined with transformer-based language models are unifying text, image, and video generation within unified inference pipelines. Enterprise marketing teams are adopting these integrated systems fastest, displacing discrete toolchains that previously required export-import cycles between specialized applications. This compression is eliminating the handoff friction that historically justified agency markup structures.
The EU AI Act's systemic transparency obligations are mandating provenance labeling and algorithmic disclosure for large content distribution platforms. Industrial consequence includes mandatory human oversight documentation and audit trail retention that alters product roadmaps toward compliance-by-design. European enterprise buyers are responding by centralizing vendor selection criteria around regulatory certification rather than feature velocity alone.
Subscription-based procurement of generative tooling is displacing per-project agency contracts as the dominant commercial model. Enterprise procurement functions are consolidating vendor relationships with end-to-end strategy platforms rather than atomizing spend across specialized creative shops. This concentration is most visible in United States technology and financial services verticals where procurement cycles have compressed from annual to quarterly review intervals.
Content Creation Market Segmentation
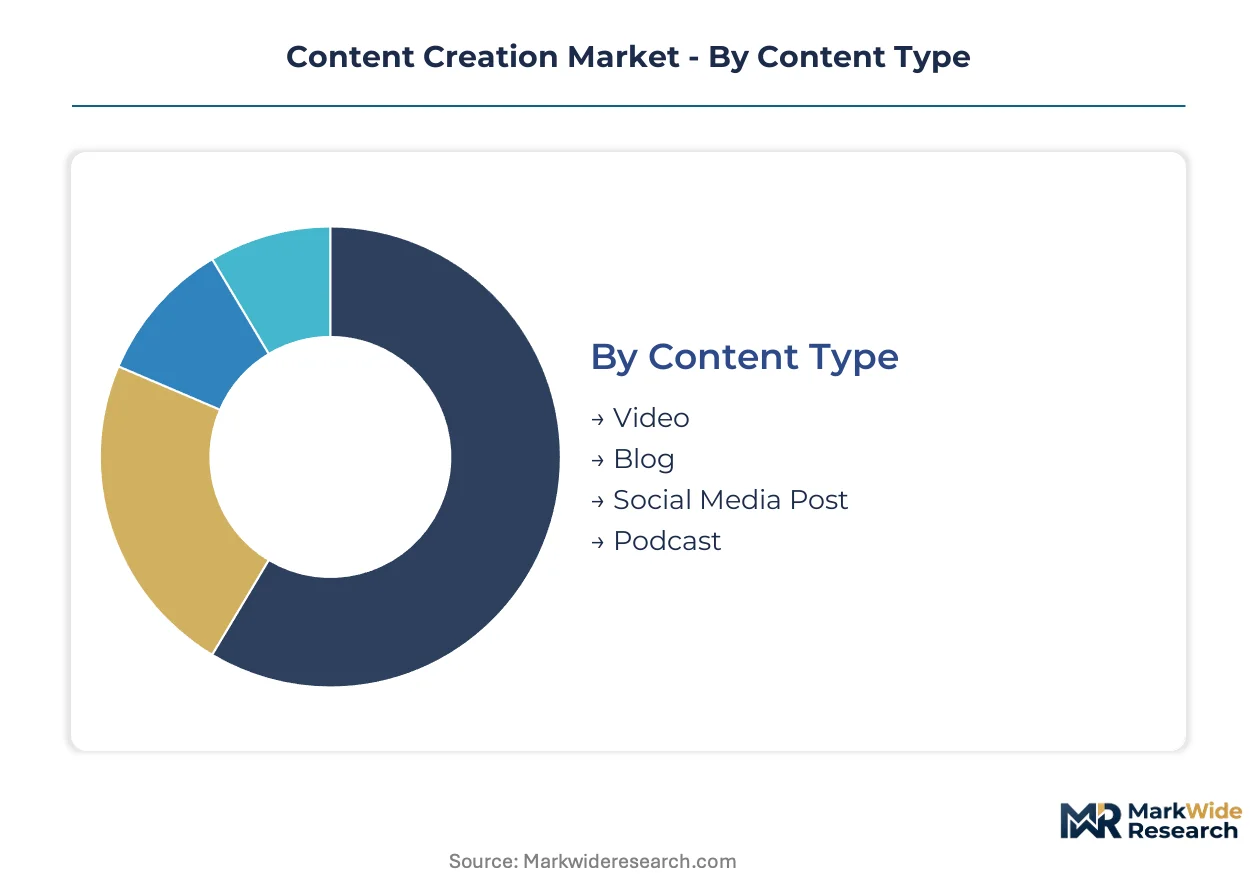
Content creation tooling exhibits divergent technical requirements across output modalities. Procurement patterns fragment sharply between high-velocity social formats and long-form editorial workflows.
Content Type:
Specification differences in production pipelines determine which segments absorb the majority of enterprise tooling investment.
- Video:Latent diffusion and transformer architectures now enable single-operator production workflows that previously required specialized agency silos. Demand concentrates in United States technology and financial services verticals where shoppable formats command algorithmic prioritization from platform distributors.
- Blog:Retrieval-augmented generation combined with latent diffusion enables factual grounding in long-form editorial workflows previously resistant to pure generative output. Technology sector buyers in the United States are adopting these hybrid architectures fastest, displacing discrete toolchains that required export-import cycles between applications.
- Social Media Post:Real-time personalization engines serve micro-content at platform-native velocity.
- Podcast:Audio production workflows leverage neural voice synthesis for scalable host augmentation.
Mature deployment sits with Blog formats. Newer deployment is concentrated in Video.
Delivery Format:
Cost tier stratification separates infrastructure-heavy interactive systems from lightweight static distribution.
- Interactive:Embedded personalization engines and real-time audience response tools represent the fastest-expanding structural category. B2B technology and financial services verticals outside consumer entertainment show particular underdeployment, creating expansion white space for platform entrants.
- Visual:Motion-based feeds concentrate advertising spend toward native video production tooling as platforms algorithmically prioritize shoppable formats.
- Written:Text-based editors retain dominance in SEO-centric editorial workflows with established publisher relationships.
- Audio:Neural synthesis pipelines compress voice production timelines from studio sessions to automated generation.
Interactive formats are climbing the fastest. Written formats maintain the deepest installed base.
Target Audience:
Customer type determines contract structure and margin retention across the value chain.
- Businesses:Enterprise marketing teams carry the deepest margin pools given longer contract cycles and integrated strategy mandates. Direct platform adoption displaces traditional agency intermediaries as procurement functions consolidate vendor relationships with end-to-end strategy platforms.
- Influencers:Creator-economy infrastructure density in the United States supports venture-backed tooling ecosystems with compressed procurement cycles.
- Consumers:Individual creators drive volume adoption through freemium conversion funnels.
- Educators:Institutional procurement follows distinct compliance and accessibility requirements.
Businesses anchor revenue concentration. Influencers are gaining share fastest in tooling adoption.
Industry Vertical:
Application context shapes regulatory exposure and integration complexity for platform vendors.
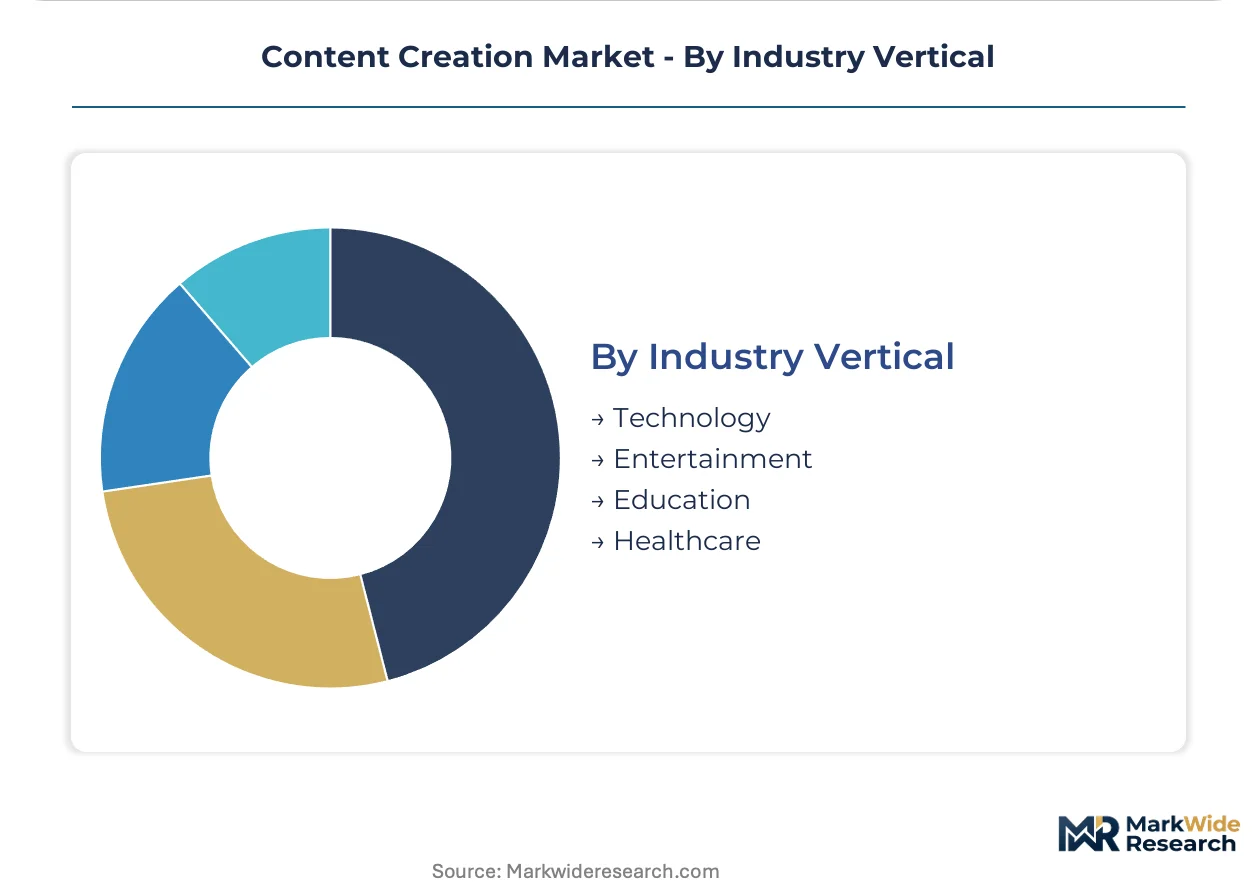
- Technology:Enterprise buyers in this vertical have compressed procurement cycles from annual to quarterly review intervals. Subscription-based procurement of generative tooling displaces per-project agency contracts as the dominant commercial model.
- Healthcare:HIPAA compliance requirements and FDA disclosure standards for AI-generated material impose documentation burdens that alter product roadmaps.
- Entertainment:Copyright ambiguity around training corpora generates legal exposure that reinsurance markets now explicitly exclude from coverage.
- Education:Accessibility mandates and institutional procurement protocols create distinct vendor selection criteria.
Technology verticals show the steepest expansion trajectory. Healthcare maintains the most rigorous compliance infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the United States concentrate venture-backed tooling ecosystems, while India's Software Technology Parks of India scheme accelerates creator-economy infrastructure deployment. Germany's media hubs and China's coastal manufacturing clusters round out production gravity.
United States
Enterprise marketing teams in technology and financial services verticals compress procurement cycles from annual to quarterly review intervals. The Federal Trade Commission enforces disclosure standards for sponsored and AI-generated material through updated endorsement guidelines. Silicon Valley and New York City anchor dense clusters of generative platform development, with Los Angeles sustaining specialized video production tooling ecosystems.
Germany
Industrial B2B content mandates drive adoption of compliance-native systems architected for EU AI Act transparency requirements. The EU AI Act imposes systemic transparency obligations and human-in-the-loop documentation burdens on large content distribution platforms. Berlin and Munich host concentrated development of editorial workflow platforms serving enterprise procurement functions across the DACH region.
India
Dense mobile-first consumption patterns and Software Technology Parks of India tax incentives attract localized platform entrants targeting creator-economy infrastructure gaps. The Reserve Bank of India and Ministry of Electronics and Information Technology shape digital content monetization frameworks through payment aggregator regulations. Bangalore and Hyderabad sustain venture-backed tooling ecosystems with compressed procurement cycles for influencer-facing applications.
China
Platform algorithmic prioritization of shoppable video formats concentrates advertising spend toward native video production tooling in coastal manufacturing zones. The Ministry of Industry and Information Technology and State Administration for Market Regulation govern generative content through algorithmic recommendation and deep synthesis provisions. The Yangtze River Delta and Pearl River Delta clusters integrate latent diffusion architectures into unified inference pipelines for export-oriented content production.
United Kingdom
Subscription-based procurement of generative tooling displaces per-project agency contracts as enterprise buyers consolidate vendor relationships with end-to-end strategy platforms. The UK Information Commissioner's Office enforces GDPR-aligned transparency obligations for automated content systems. London anchors specialized editorial workflow providers serving European enterprise marketing teams navigating post-Brexit regulatory fragmentation.
Content Creation Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base organizes around three strategic archetypes: native AI generation platforms, specialized SEO editorial agencies, and integrated B2B strategy consultancies. Competitive moves concentrate on M&A-driven capability expansion and strategic partnerships bridging generative infrastructure with legacy CMS integration.
Within the native AI generation tier, Runway AI exemplifies technical leadership in multimodal output through its video-generation stack. Siege Media occupies a position representing specialized editorial workflows with direct publisher relationships in long-form SEO content. Omniscient Digital sits within the integrated strategy archetype, anchoring end-to-end B2B content control rather than per-article pricing competition.
| Leading Market Players |
|---|
| Siege Media |
| Runway AI |
| Omniscient Digital |
| Contentoo |
| The Goat Agency |
| Brafton |
| Column Five |
| Ten Speed |
| Foundation |
| Others |
Supply Flow & Price Mechanics
GPU cloud spot pricing indices cascade through generative content production tiers, compressing margins for inference-heavy workloads while rewarding platforms with captive compute capacity. Input cost volatility from hyperscaler concentration feeds directly into subscription pricing stratification across enterprise and creator segments.
Pricing Analysis
Lead-time-driven pricing separates urgent production workflows from scheduled batch operations, with enterprise buyers paying premiums for sub-hour turnaround on multimodal generation. Pricing stratifies across premium, standard, and economy tiers based on API call volume commitments and human-in-the-loop oversight levels. Cost compression in the mid-market intensifies as open-source diffusion models erode proprietary API margins. Influencer-facing tooling shows highest price sensitivity, while integrated B2B strategy platforms retain pricing power through end-to-end workflow control.
Supply Chain Analysis
Freight costs for specialized AI training hardware concentrate supply chain leverage in United States, Taiwan, and South Korea fabrication hubs. Compute infrastructure draws from NVIDIA GPU allocations, custom ASIC foundry capacity, and hyperscaler cloud reservation blocks. Single-source vulnerability sits with TSMC advanced node dependence for training accelerators. Distribution runs through direct API provisioning and enterprise licensing agreements rather than physical channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative neural architectures are displacing legacy editorial agency retainers, compressing production timelines from weeks to hours and forcing structural repricing of creative services.
For Market Incumbents: Deepen vertical integration into proprietary training data pipelines to defend against copyright litigation exposure that reinsurance markets now exclude. Consolidate API-native connectivity with legacy CMS architectures to lock in enterprise procurement functions before retrofit costs escalate. Siege Media's direct publisher relationships and Omniscient Digital's end-to-end strategy control represent defensible moats against pure-play generation platforms.
For New Entrants and Emerging Players: Enter via India's Software Technology Parks of India incentive zones where mobile-first consumption patterns and venture-backed tooling ecosystems offer expansion white space. Target interactive personalization engines in B2B verticals outside technology and financial services, where real-time audience response tooling remains underdeployed. Position around EU AI Act compliance-native architecture as European enterprise buyers centralize vendor selection around regulatory certification.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid architecture specialists in Germany and United Kingdom markets navigating post-Brexit regulatory fragmentation. Long-term viability hinges on platforms controlling end-to-end strategy workflows rather than competing on per-article generation pricing alone. Monitor EU AI Act enforcement actions as inflection indicator for compliance-native system valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-Native Architecture Development | EU AI Act mandates reshape procurement criteria toward audit-trail-retention capabilities. |
| Hybrid RAG-Diffusion Integration | Retrieval-augmented generation enables factual grounding in long-form editorial workflows. |
| Enterprise CMS API Partnership | Legacy content management system connectivity determines platform adoption velocity. |
| Provenance Labeling Infrastructure | C2PA standard adoption differentiates platforms on transparency compliance. |
| India Creator-Economy Expansion | Software Technology Parks of India tax incentives attract localized platform entrants. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this content creation market analysis. Primary interviews with platform engineering leads, enterprise marketing procurement officers, creator-economy monetization specialists, and regulatory compliance directors combined with FTC disclosure guidelines, EU AI Act implementation documents, and hyperscaler capex disclosures. Bottom-up triangulation across content type, delivery format, and target audience segments validated against top-down spend estimates from enterprise technology and financial services verticals.
Granularity-level modeling operated at content modality, deployment scale, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs derived from segment-level adoption curves weighted by procurement cycle compression patterns in United States enterprise marketing teams. Industry-specific forecast inputs included GPU infrastructure expansion timelines, training data licensing friction indices, and human-in-the-loop compliance cost trajectories.
Revisions become necessary when EU AI Act enforcement actions, FTC disclosure rule expansions, or hyperscaler compute allocation shocks materialize beyond modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Global Influencer Market