
 Social Publishing Application Market | 2026-2036
Social Publishing Application Market Size, Share, and Industry Trends Forecast 2026-2036
Social Publishing Application Market Analytics
Open-source container orchestration is realigning infrastructure economics for social publishing platforms as Kubernetes displaces proprietary hosting stacks. Meta Platforms leverages its captive social graph to sustain content distribution dominance. Alphabet Inc. competes through deep API integration across its productivity suite, while ByteDance anchors short-form video publishing workflows with algorithmic distribution engines.
A social publishing application is a software platform that enables users to create, schedule, distribute, and analyze content across digital channels, typically incorporating content calendars, multi-account authentication protocols, and engagement analytics dashboards. Its primary commercial purpose is to consolidate fragmented social media operations into unified workflows for brand consistency and audience reach. The freemium monetization model captures the widest user base, though subscription-based tiers concentrate the majority of margin pools among enterprise accounts. Social media tools within the application type dimension lead current adoption, while e-commerce integrations represent the fastest-expanding segment as shoppable content bridges discovery and transaction.
The EU AI Act and GDPR impose algorithmic transparency and data processing constraints on platforms operating across European jurisdictions, directly shaping product architecture for automated content recommendation engines. In the United States, the FTC scrutinizes influencer disclosure practices and native advertising transparency, elevating compliance tooling from optional feature to procurement requirement. Stakeholders must weigh regulatory fragmentation against the cost of region-specific product variants when evaluating platform investments.
Market Dynamics
Container orchestration via Kubernetes is compressing infrastructure costs for social publishing platforms, forcing legacy hosting architectures into rapid obsolescence while enterprise buyers consolidate vendor relationships around API-native stacks.
Growth Catalysts
- EU AI Act compliance tooling:Automated transparency engines for algorithmic content recommendation are becoming mandatory procurement criteria for European enterprise accounts, creating pull for audit-ready platforms.
- Creator economy clusters:Los Angeles and New York influencer agencies are driving demand for multi-account authentication protocols that streamline omnichannel campaign orchestration.
- Shoppable content integration:E-commerce bridging tools that connect discovery to transaction represent the fastest-expanding application segment as retail brands consolidate social operations.
Market Restraints
- GDPR data localization:European data processing constraints force costly region-specific product variants, fragmenting development resources and delaying feature parity.
- Cloud infrastructure concentration:Three hyperscalers control the majority of container hosting capacity, exposing publishers to pricing power asymmetry and egress cost volatility.
- Algorithmic opacity limits:Platform black-box distribution engines prevent publishers from optimizing content performance, capping return on creative investment.
Strategic Opportunities
- FTC disclosure automation:Native advertising transparency mandates in the United States elevate compliance tooling from optional feature to procurement requirement, opening white space for integrated disclosure engines.
- Short-form video workflows:Algorithmic distribution engines optimized for sub-60-second content formats enable publishers to capture attention-share from traditional long-form channels.
- API convergence:Deep integration between productivity suites and publishing stacks is unifying creative production with distribution scheduling, compressing campaign cycle times.
Industry Challenges
- Cross-platform authentication complexity:Multi-account credential management across fragmented social networks requires specialized security engineering talent that commands premium compensation.
- Legacy CMS integration friction:Enterprise content management systems built for web-first publishing resist API-native social workflows, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Publishing Application Market |
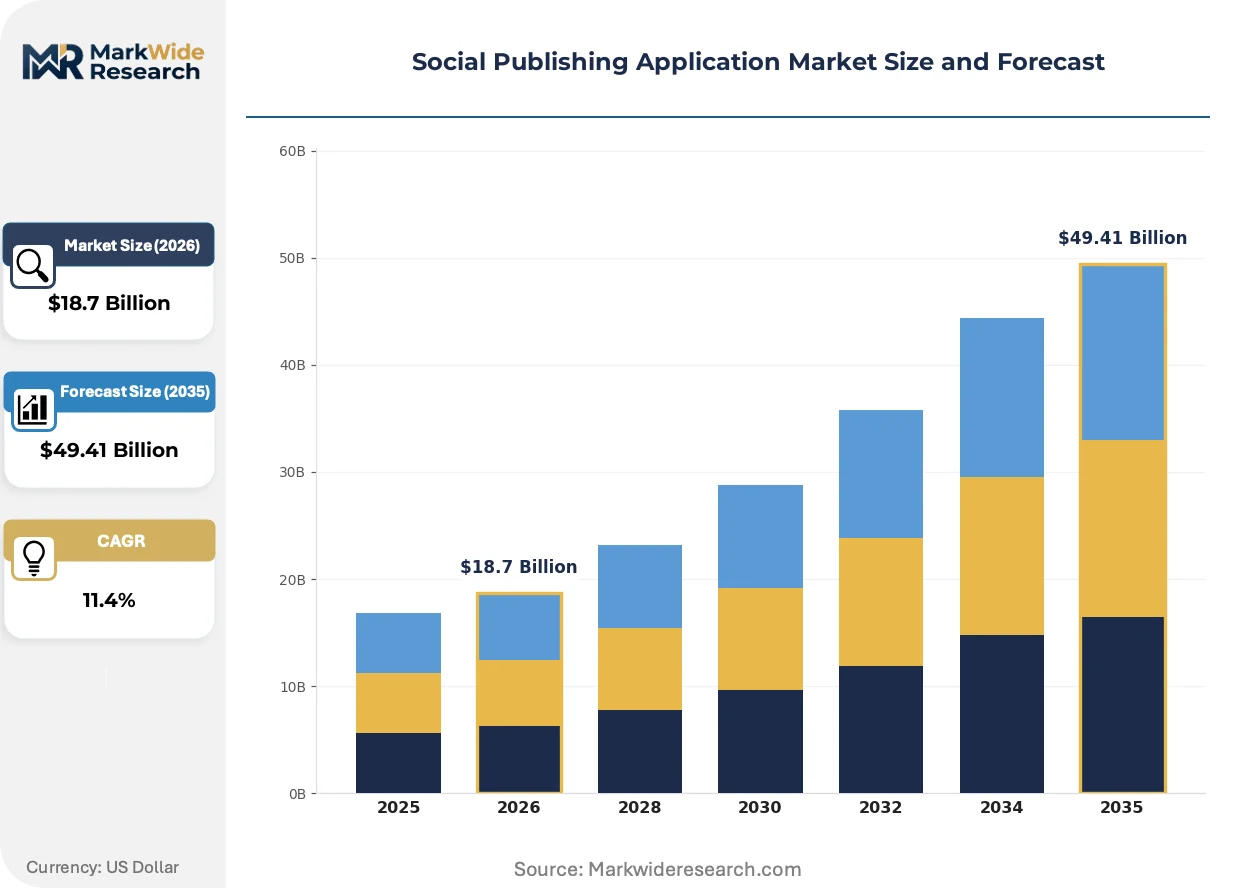
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Blogging Platforms, Content Management Systems, Social Media Tools, E-commerce Integrations User Type: Individuals, Small Businesses, Enterprises, Influencers Monetization Model: Subscription-Based, Freemium, Ad-Supported, Transaction-Based Integration Level: API Integrations, Plug-in Options, Standalone Solutions, Cross-Platform Functionality |
| Companies Covered | IBM Corporation, Adobe, Oracle, Sprout Social, SAS Institute, Meta Platforms, Alphabet Inc., ByteDance, Tencent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Publishing Application Market Evolving Landscape
Federated content architectures and real-time engagement analytics are compressing the gap between creation and distribution, while regulatory transparency mandates reshape product roadmaps across jurisdictions.
Generative content orchestration layers are unifying creative production, scheduling, and performance analytics into single-pane workflows. Mid-market marketing agencies are adopting these stacks fastest, replacing point solutions that required manual data stitching. This unification is collapsing the traditional separation between creative and media operations, forcing agency restructuring.
GDPR algorithmic transparency requirements and the EU AI Act are mandating explainable recommendation engines for automated content distribution. Publishers operating across European jurisdictions must now document decision logic for content ranking and audience targeting. Enterprise platforms are responding by building audit trails and consent management modules directly into core architecture rather than bolting on compliance features.
Enterprise procurement of social publishing tools is consolidating around outcome-based engagement metrics rather than seat-based licensing. Marketing departments are replacing perpetual subscriptions with contracts tied to verified audience reach and conversion attribution. This shift is most visible in United States retail and consumer packaged goods verticals, where CFO scrutiny of martech spend has intensified.
Social Publishing Application Market Segmentation
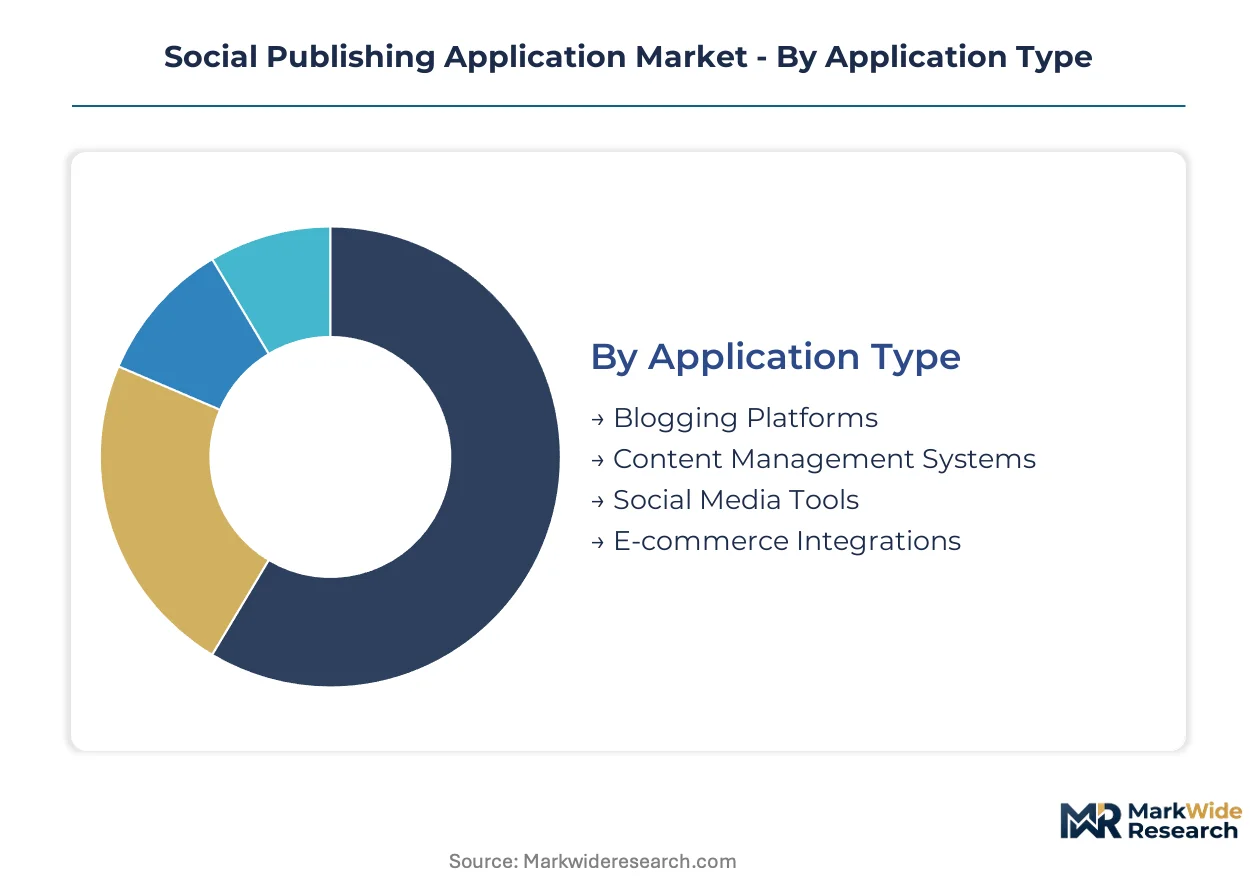
Segmentation in social publishing applications reveals how buyer priorities diverge across workflow complexity, budget tiers, and regulatory exposure. Procurement patterns cluster around integration depth and monetization flexibility rather than surface-level feature comparisons.
Application Type:
Enterprise buyers prioritize workflow consolidation over point-solution specialization, driving procurement toward platforms that compress creative-to-distribution cycle times.
- Social Media Tools:These platforms consolidate multi-account authentication, content calendars, and engagement analytics into unified dashboards. Demand concentrates among Los Angeles and New York creator economy clusters where omnichannel campaign orchestration is mandatory. Enterprise marketing teams favor these for brand consistency across fragmented networks.
- E-commerce Integrations:Shoppable content bridges connect discovery to transaction, embedding checkout flows within social feeds. Retail brands in the United States are consolidating social operations around these bridges as CFO scrutiny of martech spend intensifies. These integrations are gaining share fastest as shoppable content adoption accelerates.
- Content Management Systems:Web-first publishing architectures resist API-native social workflows, forcing expensive middleware development for enterprise deployments.
- Blogging Platforms:Long-form content creation tools retain niche adoption among independent publishers and SEO-focused content marketers.
Volume sits with Social Media Tools; growth tilts toward E-commerce Integrations.
User Type:
Revenue concentration follows account size, with enterprise contracts delivering disproportionate margin pools despite smaller user counts.
- Enterprises:Large marketing departments procure outcome-based contracts tied to verified audience reach and conversion attribution. These buyers demand audit-ready compliance architectures for EU AI Act and GDPR mandates, elevating procurement criteria beyond feature checklists.
- Influencers:Multi-account authentication protocols streamline omnichannel campaign orchestration for Los Angeles and New York agency-represented creators. FTC disclosure automation has shifted from optional feature to mandatory procurement requirement for this segment.
- Small Businesses:Mid-market marketing agencies adopt generative content orchestration layers fastest, replacing point solutions that required manual data stitching.
- Individuals:Freemium tiers capture the widest user base, though individual accounts contribute minimally to aggregate margin pools.
Margin concentrates with Enterprises; expansion tilts toward Influencers.
Monetization Model:
Pricing architecture determines addressable market breadth and revenue predictability, with hybrid models capturing both volume and value.
- Freemium:Tiered entry points capture individual users and small businesses, converting a subset to paid tiers through feature gates. This model dominates user acquisition but requires careful unit economics management to prevent support cost inflation.
- Subscription-Based:Recurring revenue contracts concentrate among enterprise accounts seeking procurement predictability. These tiers deliver the majority of margin pools through annual commitments and seat-based or outcome-based pricing.
- Ad-Supported:Publisher-funded models sustain free tiers for high-volume content creators, though data localization requirements under GDPR fragment implementation.
- Transaction-Based:Revenue shares on shoppable content transactions align platform incentives with merchant success, gaining traction among e-commerce integrations.
User volume sits with Freemium; revenue predictability tilts toward Subscription-Based.
Integration Level:
Technical architecture choices determine implementation friction and long-term vendor lock-in exposure for enterprise procurement teams.
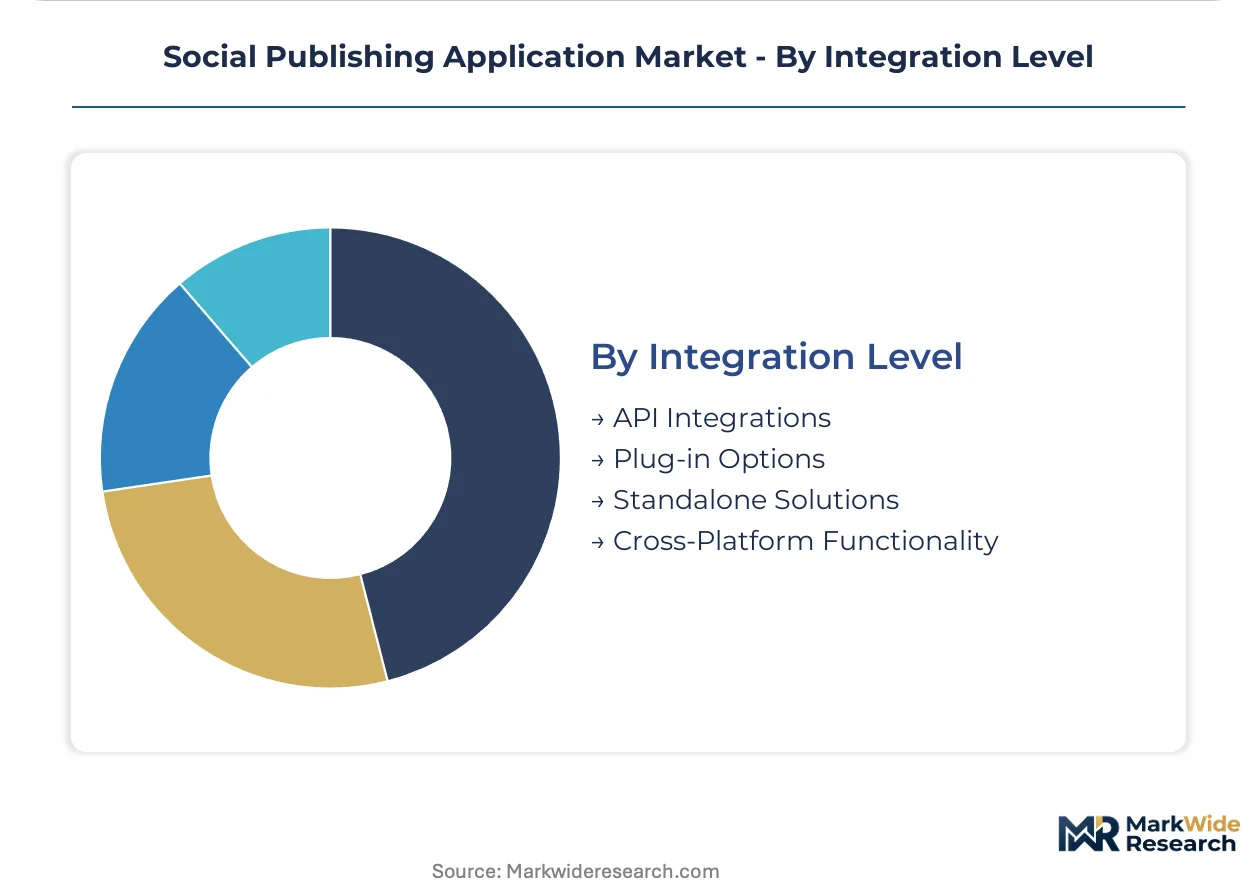
- API Integrations:Deep connectivity between productivity suites and publishing stacks unifies creative production with distribution scheduling. Enterprise buyers consolidate vendor relationships around these API-native stacks as Kubernetes compresses infrastructure costs.
- Cross-Platform Functionality:Unified workflows across fragmented social networks reduce credential management complexity. Demand concentrates where multi-account authentication protocols are mandatory for compliance and operational efficiency.
- Plug-in Options:Modular extensions allow legacy CMS augmentation without full platform replacement, addressing integration friction for web-first enterprises.
- Standalone Solutions:Self-contained platforms retain adoption among security-conscious buyers seeking minimal external dependency surfaces.
Procurement momentum sits with API Integrations; flexibility demand tilts toward Cross-Platform Functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creator economy clusters in Los Angeles and New York concentrate demand for multi-account authentication protocols and omnichannel campaign orchestration tools. Enterprise marketing teams across Germany, Japan, and the United Kingdom are expanding procurement of audit-ready platforms to satisfy tightening algorithmic transparency mandates. Regulatory fragmentation between the EU AI Act and national disclosure requirements is forcing region-specific product variants.
United States
FTC scrutiny of influencer disclosure practices and native advertising transparency elevates compliance tooling from optional feature to procurement requirement. Marketing departments in retail and consumer packaged goods verticals are replacing perpetual subscriptions with contracts tied to verified audience reach. Los Angeles and New York influencer agencies drive concentrated demand for streamlined credential management across fragmented social networks.
Germany
GDPR data localization constraints force costly region-specific product architectures that fragment development resources and delay feature parity. Enterprise buyers demand audit-ready compliance architectures for algorithmic transparency mandates under the EU AI Act. Frankfurt and Munich marketing technology clusters are consolidating vendor relationships around API-native stacks as Kubernetes compresses infrastructure economics.
United Kingdom
Mid-market marketing agencies in London are adopting generative content orchestration layers fastest, replacing point solutions that required manual data stitching. The UK Information Commissioner's Office enforces GDPR-aligned data processing constraints that shape product roadmaps for automated content recommendation engines. Manchester and Birmingham creator economy hubs are expanding procurement of outcome-based engagement metrics rather than seat-based licensing.
Japan
METI guidelines on platform transparency and consumer protection influence enterprise procurement criteria for social publishing stacks. Marketing departments prioritize deep API integration between productivity suites and publishing platforms to compress campaign cycle times. Tokyo and Osaka advertising technology clusters are consolidating around vendors offering native compliance modules for cross-border data governance.
India
Digitally native brands in Mumbai and Bangalore are driving adoption of shoppable content bridges that connect discovery to transaction within social feeds. The country's data protection authority is developing localization requirements that will shape future product architecture for international platforms. Hyderabad and Delhi-NCR influencer marketing agencies are expanding demand for multi-account authentication protocols as creator economy professionalization accelerates.
Social Publishing Application Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise procurement consolidating around outcome-based engagement metrics rather than seat-based licensing. The vendor base fragments across API-native stacks, algorithmic distribution engines, and compliance-focused audit platforms. Three strategic archetypes dominate: captive social graph operators, productivity suite integrators, and short-form video workflow specialists. Competitive moves center on M&A to acquire authentication protocol expertise and strategic partnerships to embed compliance tooling directly into core architecture.
Within the productivity suite integrator tier, Adobe and Oracle occupy positions anchoring enterprise workflow consolidation through deep API connectivity. Meta Platforms exemplifies the captive social graph archetype, leveraging proprietary distribution infrastructure to sustain content reach dominance. ByteDance sits within the algorithmic distribution specialist tier, anchoring short-form video publishing workflows through recommendation engine optimization.
| Leading Market Players |
|---|
| IBM Corporation |
| Adobe |
| Oracle |
| Sprout Social |
| SAS Institute |
| Meta Platforms |
| Alphabet Inc. |
| ByteDance |
| Tencent |
| Others |
Value Network & Pricing Analysis
Enterprise marketing teams in retail and consumer packaged goods verticals anchor pricing power through outcome-based contracts tied to verified audience reach, compressing seat-based licensing premiums while elevating compliance-module bundling as the dominant pricing architecture.
Pricing Analysis
Freemium tiers capture user volume while subscription-based contracts concentrate margin pools among enterprise accounts. Pricing stratifies across premium compliance bundles, standard workflow tiers, and economy self-serve levels, with EU AI Act audit-readiness and FTC disclosure automation driving premium differentiation. Cost compression in mid-market segments is intensifying as generative content orchestration layers displace point solutions. Small businesses exhibit highest price sensitivity, while enterprise procurement teams prioritize outcome-based engagement metrics over per-seat costs.
Supply Chain Analysis
Specialized security engineering talent for multi-account authentication protocols concentrates in San Francisco, London, and Bangalore, with premium compensation demands compressing platform margins. Infrastructure provisioning draws from hyperscaler data centers in the United States, Germany, and Japan, while API-native development resources cluster in Tel Aviv and Toronto. Single-source vulnerability in cloud infrastructure concentration exposes publishers to egress cost volatility. Distribution runs through direct enterprise sales teams, self-serve digital channels, and agency partnership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance engineering talent scarcity props pricing for audit-ready platforms, creating durable margin pools for vendors with embedded transparency architectures.
For Market Incumbents: Lock in enterprise relationships through deep API integration with productivity suites, defending against Alphabet Inc. and Adobe's workflow consolidation plays. Acquire specialized authentication protocol expertise to neutralize cross-platform credential management friction. Expand compliance module development capacity in Frankfurt and London to capture EU AI Act and GDPR audit-ready demand. For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for algorithmic transparency engines targeting mid-market marketing agencies replacing manual compliance workflows. Target shoppable content bridge development for United States retail brands consolidating social operations around transaction-linked discovery. Pursue channel partnerships with Los Angeles and New York influencer agencies seeking streamlined FTC disclosure automation. For Investors and Strategic Acquirers: The window for entry favors API-native workflow consolidation specialists with embedded compliance architectures. Long-term viability hinges on outcome-based contract structures that align platform economics with verified conversion attribution. Watch for hyperscaler pricing power asymmetry triggering enterprise procurement consolidation around multi-cloud deployment options as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Integration | EU AI Act mandates elevate audit-ready platforms to mandatory procurement criteria for Frankfurt enterprise buyers. |
| API-Native Workflow Consolidation | Deep connectivity between productivity suites and publishing stacks compresses campaign cycle times for Oracle and Adobe anchored deployments. |
| Short-Form Video Workflow Optimization | Algorithmic distribution engines for sub-60-second content capture attention-share from traditional channels for ByteDance-competitive positioning. |
| Shoppable Content Bridge Development | E-commerce transaction integration within social feeds aligns platform incentives with United States retail brand success metrics. |
| Authentication Protocol Acquisition | Multi-account credential management expertise commands premium compensation, creating defensive moats through specialized security engineering talent. |
Research Methodology
SEC filings, hyperscaler infrastructure capex disclosures, and EU regulatory transparency databases formed the secondary backbone, supplemented by customs records tracking software services trade flows. Primary interviews with CTOs at mid-market marketing agencies, enterprise IT procurement officers, platform integration specialists, and compliance engineering directors grounded segmentation assumptions. Bottom-up and top-down triangulation validated addressable market sizing across deployment models and organization tiers.
Bottom-up modeling anchored volume estimates in active user counts and average revenue per account, while top-down analysis cross-checked against aggregate enterprise martech spend patterns. Segmentation dimensions included application type, user tier, monetization model, and integration complexity across the analysis window. CAGRs were derived from trend extrapolation of compliance tooling adoption curves and shoppable content integration velocity, with Kubernetes infrastructure cost compression and algorithmic transparency mandate timelines as key forecast inputs.
Caveats apply where regulatory enforcement intensity, hyperscaler pricing actions, or generative AI capability leaps could materially shift the outlook. Forecasts reflect assumptions about enterprise procurement consolidation velocity and creator economy professionalization trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
User Generated Content Platform Market