
 Tagetes Oil Market | 2026-2036
Tagetes Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Tagetes Oil Market Analysis
Contract farming arrangements with built-in offtake guarantees are reconfiguring capital requirements for new entrants in tagetes oil production. Berje Inc leverages backward integration into South American cultivation zones to secure raw material consistency. Robertet S.A. anchors its competitive stance through proprietary extraction technologies that preserve terpenoid profiles. Synthite Industries Ltd dominates bulk supply contracts to flavor houses across Asian markets.
Tagetes oil is a steam-distilled essential oil derived primarily from Tagetes minuta, containing tagetone, dihydrotagetone, and ocimene as signature constituents, with applications spanning fragrance compounding, food flavoring, and therapeutic formulations. The essential oil product type captures the dominant value share due to its versatility across industrial buyers, while pharmaceutical ingredient grades command premium positioning driven by stringent purity certifications. Glass bottle packaging leads among high-value therapeutic and aromatherapy channels, whereas bulk packaging sustains margin efficiency for fragrance manufacturing customers.
REACH registration requirements in Europe, EPA FIFRA compliance in the United States, and India's BIS essential oil standards collectively elevate barrier costs for unqualified suppliers. FDA oversight of flavoring substance approvals further constrains market access for non-compliant producers. Stakeholders must monitor regulatory divergence between organic certification regimes and conventional chemical standards to anticipate sourcing cost shifts.
Market Dynamics
REACH registration deadlines and EPA FIFRA re-registration cycles are compressing supplier qualification timelines, forcing distillation facilities to front-load compliance investments before offtake contracts can be secured.
Growth Catalysts
- Clean-label fragrance mandates:EU Cosmetic Regulation Annex III restrictions on synthetic allergens redirect formulators toward botanically derived alternatives, elevating tagetes oil substitution rates in fine fragrance compounding.
- India BIS essential oil standards:Harmonized quality benchmarks for export-grade tagetes oil reduce buyer testing burdens, accelerating contract finalization between Indian distillers and European fragrance houses.
- Steam distillation optimization:Continuous-flow extraction systems cut batch cycle times by half, enabling processors to capture volatile terpenoid fractions that degrade under conventional pot-still methods.
Market Restraints
- Raw material geographic concentration:Tagetes minuta cultivation clusters in Madhya Pradesh and KwaZulu-Natal expose supply chains to monsoon variability and port congestion at Durban and Mumbai.
- Tagetone photochemical instability:The signature ketone constituent degrades under UV exposure, limiting shelf-life for therapeutic-grade oils and forcing cold-chain logistics that inflate landed costs.
- Synthetic ocimene substitution:Petrochemical-derived ocimene from Asian olefin crackers undercuts natural tagetes oil on price in mass-market fragrance applications, compressing volume at the commodity tier.
Strategic Opportunities
- Pharmaceutical API-grade certification:USP monograph compliance for tagetes oil opens prescription dermatology formulations previously blocked by purity variance, with CDSCO alignment enabling parallel India registration.
- Carbon-negative distillation:Biomass-fired stills paired with carbon credit verification create premium positioning for EU Green Deal-aligned procurement tenders from cosmetics multinationals.
- Direct-to-compounder e-commerce:B2B platforms connecting small-batch distillers with independent perfumers bypass traditional broker markups, capturing margin from the artisan fragrance segment.
Industry Challenges
- Gas chromatography-mass spectrometry analytical capacity:Batch-to-batch terpenoid profiling requires capital-intensive GC-MS infrastructure that rural Indian distillers struggle to finance, creating quality documentation gaps.
- Organic certification audit timelines:ECOCERT and USDA Organic conversion periods stretch 24-36 months, locking transitional acreage out of premium pricing tiers during the gap period.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tagetes Oil Market |
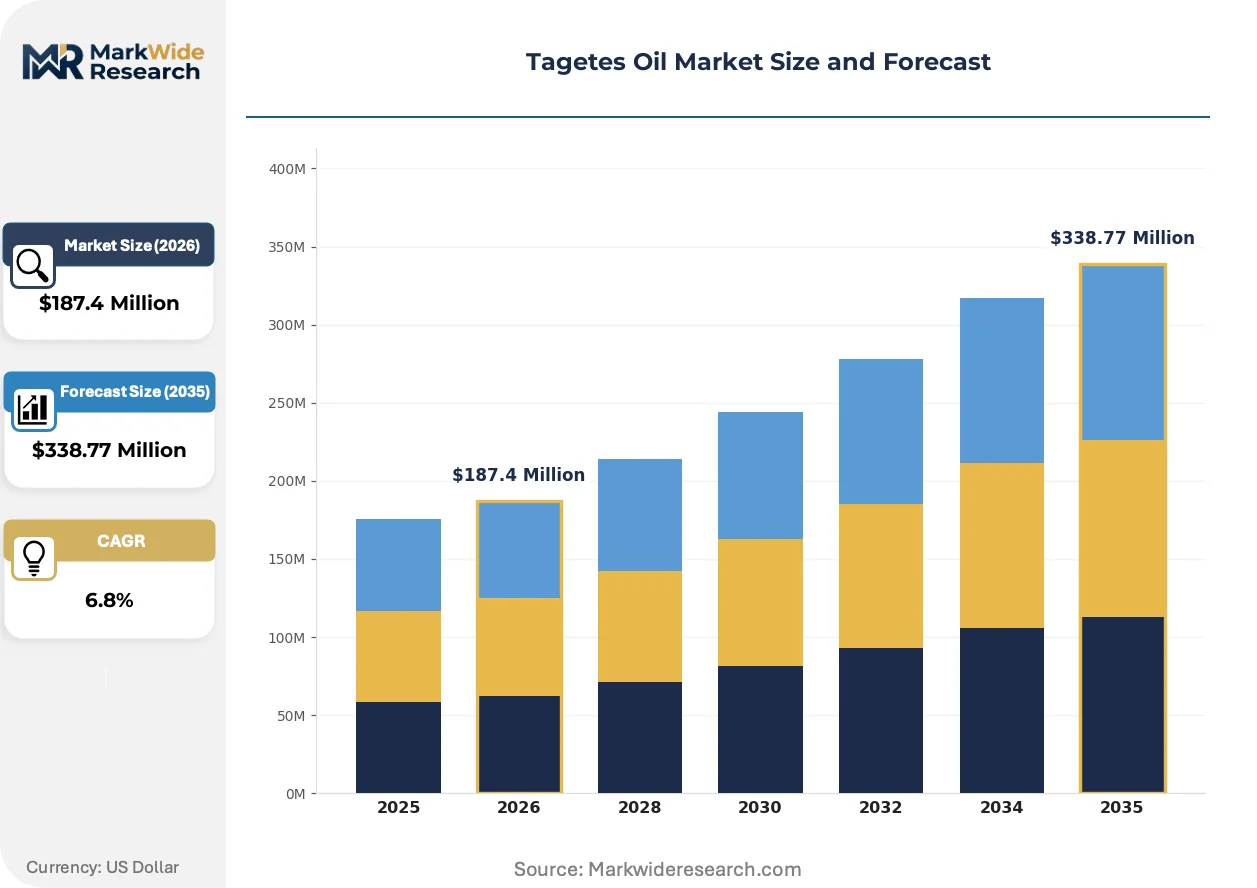
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Food Flavoring, Aromatherapy Blend, Pharmaceutical Ingredient End User: Cosmetics Industry, Food & Beverage Sector, Healthcare Professionals, Aromatherapy Practitioners Packaging Type: Glass Bottles, Plastic Containers, Bulk Packaging, Sachets Application: Fragrance Manufacturing, Culinary Uses, Therapeutic Products, Natural Remedies |
| Companies Covered | Berje Inc, Albert Vieille SAS, Fleurchem Inc, Ernesto Ventós S.A., Vigon International Inc, R K Essential Oils Company, Synthite Industries Ltd, Robertet S.A., Givaudan S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tagetes Oil Market Emerging Trajectories
Supercritical CO2 extraction and molecular distillation are fragmenting the technology base for tagetes oil production, creating tiered supply quality that reshapes buyer-supplier matching algorithms across fragrance and pharmaceutical channels.
Supercritical CO2 extraction operates at low temperatures to preserve heat-labile tagetone isomers, yielding pharmaceutical-grade oils that command threefold premiums over steam-distilled equivalents. European flavor houses with dedicated naturals divisions are retrofitting facilities to dual-mode capability. Steam distillation is rendering obsolete for high-value therapeutic applications where terpenoid fidelity determines clinical efficacy claims.
REACH Annex XIV authorization requirements for residual solvent limits now extend to extraction aids used in tagetes oil processing, compelling distillers to validate hexane-free claims through third-party testing. The industrial consequence is a bifurcation between EU-exporting facilities with in-house chromatography labs and commodity suppliers reliant on external certification. Pharmaceutical ingredient grades face the steepest compliance cost escalation, with some Indian processors withdrawing from the European therapeutic market entirely.
Fragrance compounders are consolidating supplier rosters from twenty-plus vendors to three-to-four strategic partnerships, prioritizing distillers with backward integration into contract farming. This concentration disrupts spot-market brokers who historically intermediated between small African growers and European buyers. The shift is most visible in South Africa, where vertically integrated processors with captive cultivation in Limpopo province are capturing volume previously dispersed across informal cooperatives.
Tagetes Oil Market Segmentation
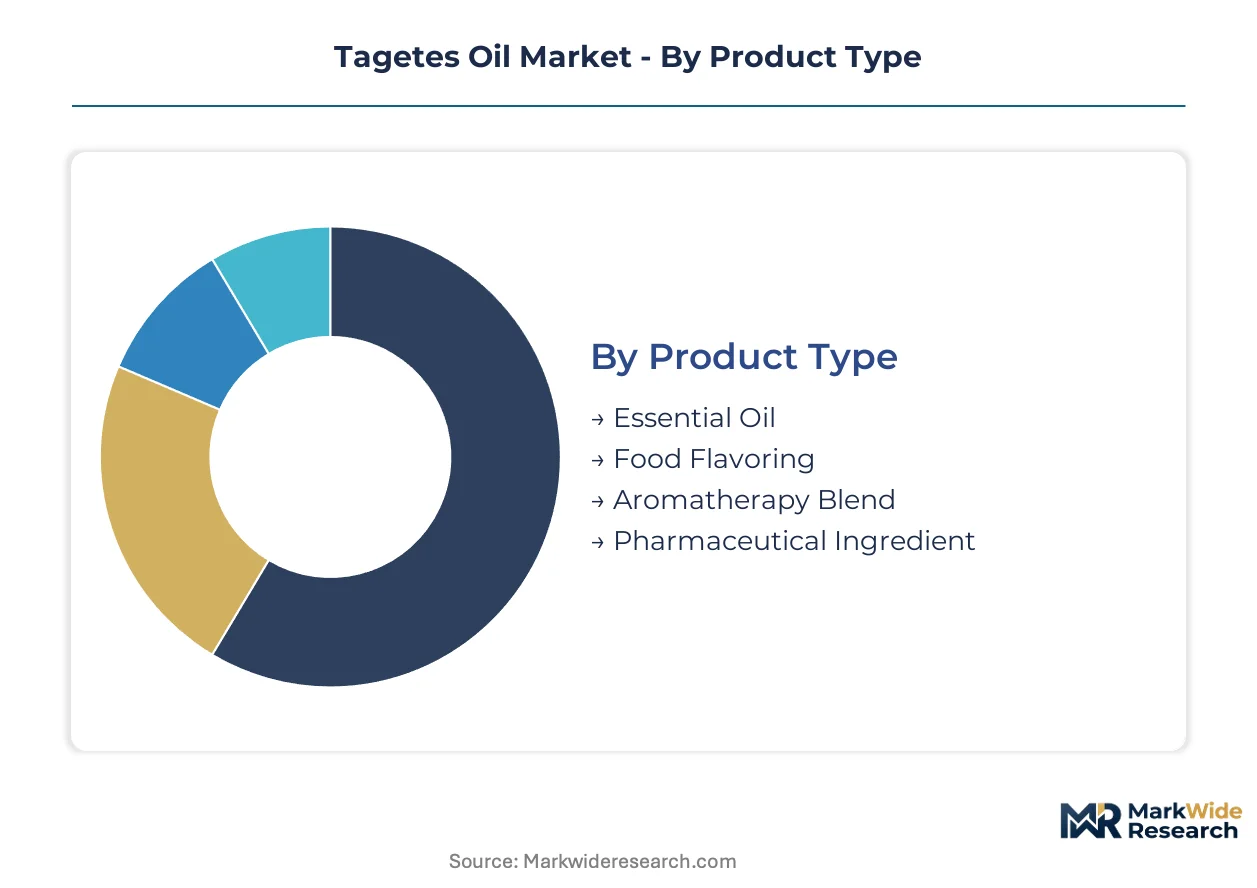
Tagetes oil segmentation reveals distinct service and support requirements across buyer categories. Pharmaceutical ingredient purchasers demand batch-specific chromatography documentation, while fragrance compounders prioritize supply continuity over technical handholding.
Product Type:
After-sales intensity varies sharply across product grades, with pharmaceutical and therapeutic segments requiring certificate-of-analysis replenishment and regulatory filing support that essential oil commodity buyers rarely request.
- Essential Oil:Steam-distilled concentrate containing tagetone, dihydrotagetone, and ocimene as marker compounds. Demand concentrates in European fragrance houses responding to EU Cosmetic Regulation Annex III synthetic allergen restrictions, with buyers prioritizing terpenoid consistency over origin certification.
- Pharmaceutical Ingredient:USP monograph-compliant grade with validated tagetone isomer ratios and sub-ppm residual solvent thresholds. German and Swiss dermatology formulators drive specification tightening, as REACH Annex XIV authorization requirements extend to extraction aid residuals.
- Food Flavoring:FEMA GRAS-listed grade with FDA-approved usage levels for baked goods and beverages.
- Aromatherapy Blend:Pre-diluted formulations for therapeutic massage and inhalation applications.
Essential Oil holds the largest share; momentum sits with Pharmaceutical Ingredient.
End User:
Cost tier differentiation separates institutional buyers with dedicated quality assurance staff from artisan formulators purchasing through distributor channels.
- Cosmetics Industry:Fine fragrance and personal care manufacturers specifying tagetes oil for its herbaceous-fruity top notes. French and Italian luxury houses anchor volume, with clean-label mandates accelerating substitution away from synthetic ocimene.
- Healthcare Professionals:Dermatology clinics and hospital pharmacies prescribing tagetes oil for antifungal and wound-healing protocols. South African public health procurement channels represent expanding volume as traditional medicine integration advances.
- Food & Beverage Sector:Flavor houses and natural food manufacturers leveraging tagetes for citrus-type flavor modulation.
- Aromatherapy Practitioners:Independent therapists and wellness centers sourcing small-batch therapeutic grades.
Cosmetics Industry commands premium pricing tiers; Healthcare Professionals represent the steepest expansion trajectory.
Packaging Type:
Volume scale determines packaging economics, with fragrance manufacturing customers absorbing tanker-load deliveries that therapeutic channels cannot warehouse.
- Bulk Packaging:Stainless steel drums and intermediate bulk containers for fragrance compounders and flavor houses. Mumbai and Rotterdam port consolidation points serve Indian and European distillation clusters respectively.
- Glass Bottles:Amber and cobalt pharmaceutical-grade containers with tamper-evident closures. German and Swiss aromatherapy distributors specify DIN-standard neck finishes for compatibility with dispensing equipment.
- Plastic Containers:HDPE bottles for food service and institutional catering applications.
- Sachets:Single-use foil pouches for sample distribution and travel retail.
Bulk Packaging dominates volume throughput; Glass Bottles capture value concentration.
Application:
Supply concentration aligns with application maturity, with fragrance manufacturing anchored by long-term contracts while natural remedies remain fragmented across informal channels.
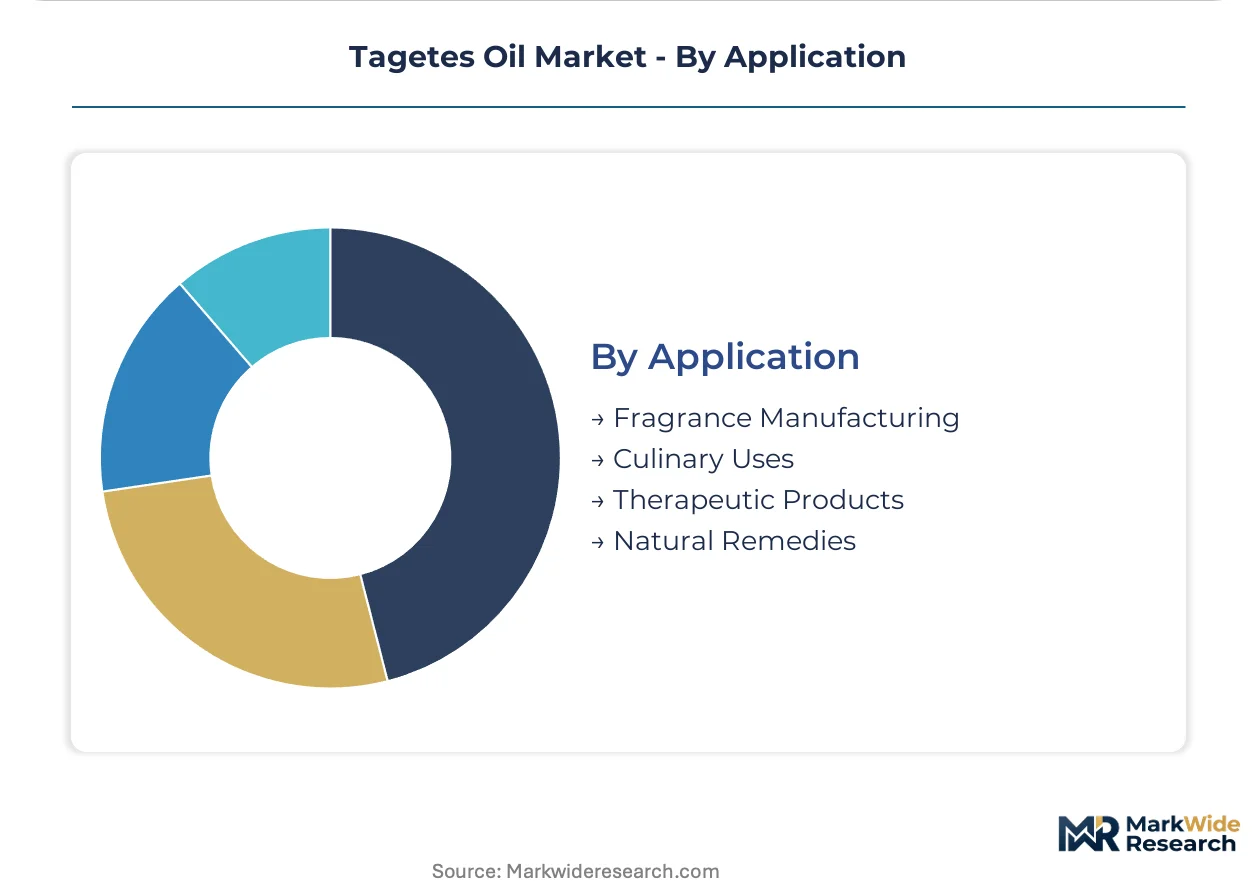
- Fragrance Manufacturing:Fine fragrance, functional perfumery, and home care applications requiring standardized tagetone content for reproducible odor profiles. Givaudan and Firmenich procurement specifications drive Indian distiller investment in continuous-flow extraction systems.
- Therapeutic Products:Prescription and over-the-counter dermatology formulations with clinical efficacy claims. USP-grade certification requirements exclude most African and small-scale Indian suppliers from this segment.
- Culinary Uses:Commercial bakery and beverage flavoring with FEMA GRAS regulatory clearance.
- Natural Remedies:Traditional medicine and folk healing applications with minimal regulatory oversight.
Fragrance Manufacturing holds the largest share; Therapeutic Products are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fragrance compounders in France and Italy anchor premium-grade procurement, while pharmaceutical formulators in Germany and Switzerland drive USP-grade specification tightening. Indian bulk distillers and South African integrated processors compete for mid-market volume.
France
Fine fragrance houses in Grasse and Paris specify tagetes oil for herbaceous-fruity top notes in clean-label formulations. EU Cosmetic Regulation Annex III restrictions on synthetic allergens redirect formulators toward botanically derived alternatives. The Provence-Alpes-Côte d'Azur cluster hosts distillation facilities retrofitting for dual-mode extraction capability.
India
Bulk supply contracts to Asian flavor houses concentrate demand in Madhya Pradesh cultivation zones. BIS essential oil standards harmonize quality benchmarks for export-grade material, reducing European buyer testing burdens. Indore and Mumbai serve as consolidation points where continuous-flow extraction systems capture volatile terpenoid fractions.
Germany
Dermatology formulators in Frankfurt and Munich drive USP monograph compliance requirements for prescription therapeutic applications. REACH Annex XIV authorization requirements extend to extraction aid residuals, elevating documentation burdens. The Baden-Württemberg region hosts fragrance compounders consolidating supplier rosters to strategic partnerships.
South Africa
Public health procurement channels in KwaZulu-Natal and Limpopo expand volume as traditional medicine integration advances. Port congestion at Durban exposes supply chains to logistics variability. Vertically integrated processors with captive cultivation capture volume previously dispersed across informal cooperatives.
Switzerland
Swissmedic oversight shapes pharmaceutical-grade certification requirements for dermatology applications. Geneva and Basel anchor demand for validated tagetone isomer ratios with sub-ppm residual solvent thresholds. Swiss fragrance houses with dedicated naturals divisions prioritize distillers with backward integration into contract farming arrangements.
Tagetes Oil Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base spans multinational flavor houses with captive extraction facilities, mid-scale Indian distillers serving bulk contracts, and boutique South African processors targeting therapeutic grades. Three archetypes dominate: vertically integrated agritech operators, technology-licensing extraction specialists, and broker-dependent spot-market suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with processors retrofitting facilities for supercritical CO2 capability and fragrance houses consolidating supplier rosters.
Among established extraction specialists, Robertet S.A. and Berje Inc exemplify technology-forward positioning, while Synthite Industries Ltd anchors the bulk-supply tier. These three occupy positions that span the quality-documentation spectrum from commodity-grade spot supply to USP-certified pharmaceutical channels. Their geographic footprints reflect sourcing corridor concentration in South American cultivation zones and Indian distillation clusters.
| Leading Market Players |
|---|
| Berje Inc |
| Albert Vieille SAS |
| Fleurchem Inc |
| Ernesto Ventós S.A. |
| Vigon International Inc |
| R K Essential Oils Company |
| Synthite Industries Ltd |
| Robertet S.A. |
| Givaudan S.A. |
| Others |
Supply Flow & Price Mechanics
Madhya Pradesh distillation clusters anchor global capacity for steam-distilled tagetes oil, with Indore-based processors leveraging BIS certification to command premium positioning in European fragrance procurement. Their dominance in continuous-flow extraction systems translates directly into pricing power over spot-market suppliers lacking validated terpenoid documentation.
Pricing Analysis
Certification level creates the primary spread across tagetes oil tiers, with USP monograph-compliant pharmaceutical grades commanding substantial premiums over FEMA GRAS-listed flavoring grades. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by terpenoid fidelity, residual solvent thresholds, and chromatography documentation depth. Pricing pressure stems from synthetic ocimene substitution in mass-market fragrance applications, compressing margins at the commodity tier. Fragrance compounders with dedicated naturals divisions exhibit lowest price sensitivity, while artisan perfumers purchasing through distributor channels absorb the highest per-unit costs.
Supply Chain Analysis
Extended payment terms from European fragrance houses strain working capital for Indian distillers, forcing supply-chain finance facilities to bridge harvest-to-contract gaps. Raw material sourcing draws from Madhya Pradesh cultivation zones, KwaZulu-Natal contract farming arrangements, and Limpopo province captive acreage. Tagetes minuta biomass, hexane-free extraction validation, and cold-chain logistics infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in Durban and Mumbai port congestion exposure. Distribution runs through Rotterdam and Mumbai consolidation points serving fragrance manufacturing customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the tagetes oil market creates acquisition targets for specialists capable of bridging quality-documentation gaps, as EU Cosmetic Regulation Annex III clean-label mandates splinter demand into certifiable and non-certifiable tiers.
For Market Incumbents: Pre-empt synthetic ocimene displacement by retrofitting facilities for supercritical CO2 extraction capability, preserving terpenoid fidelity that commodity steam distillation cannot match. Consolidate supplier rosters from fragmented spot-market brokers to three-to-four strategic partnerships with backward integration into contract farming, locking in raw material consistency before REACH Annex XIV authorization deadlines compress qualification timelines.
For New Entrants and Emerging Players: Build out direct-to-compounder e-commerce platforms connecting small-batch distillers with independent perfumers, capturing margin from the artisan fragrance segment that traditional broker networks underserve. Target pharmaceutical API-grade certification as the most penetrable premium tier, where USP monograph compliance excludes most African and small-scale Indian suppliers and CDSCO alignment enables parallel India registration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated processors with captive cultivation and long-term offtake guarantees from Givaudan and Firmenich procurement divisions. Five-to-ten year viability favors distillation facilities with in-house GC-MS chromatography infrastructure and dual-mode extraction capability. The signal to watch is consolidation of supplier rosters by European fragrance houses, which will determine which mid-scale processors achieve strategic-partnership status versus spot-market commoditization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Captive cultivation in Limpopo and Madhya Pradesh secures raw material consistency for REACH-compliant export volumes. |
| Supercritical CO2 Extraction Retrofit | Low-temperature processing preserves heat-labile tagetone isomers for pharmaceutical-grade certification. |
| Long-term Supply Agreement | Strategic partnerships with French and Italian fine fragrance houses reduce spot-market price volatility exposure. |
| USP Monograph Certification | Validated tagetone isomer ratios open prescription dermatology formulations blocked by purity variance. |
| Carbon-Negative Distillation Program | Biomass-fired stills with carbon credit verification capture EU Green Deal-aligned procurement tenders. |
Methodological Framework
The analysis maps essential oil, pharmaceutical ingredient, food flavoring, and aromatherapy blend sub-sectors, each validated through distillation facility operators, fragrance house procurement directors, and pharmaceutical formulator quality assurance leads. Primary interview data triangulates against BIS essential oil standards documentation, REACH Annex XIV authorization filings, FDA FEMA GRAS listings, and customs trade records for Indian and South African export flows. Bottom-up capacity assessments across Madhya Pradesh and KwaZulu-Natal cultivation zones reconcile with top-down demand modeling from European fragrance compounding and German dermatology formulation channels.
Assumption sets held regulatory compliance timelines and synthetic substitution elasticities fixed while varying clean-label mandate penetration rates and pharmaceutical API-grade certification adoption curves across the projection horizon. Segmentation dimensions span product grade tier, end-use application, packaging format, and regional production hub. CAGRs derive from weighted-average growth contributions across these segments. Industry-specific forecast inputs include continuous-flow extraction system adoption rates and ECOCERT organic certification audit completion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian bulk distillers or sudden REACH Annex XIV authorization accelerations would shift outcomes. Macroeconomic commodity price volatility, regulatory divergence between organic certification regimes, or breakthrough synthetic biology production of tagetone isomers would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Europe Mineral Turpentine Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Pennyroyal Oil Market
Extracts
Hibiscus Flower Powder Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Botanicals Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Pullulan Market
Extracts
Belladonna Market
Extracts
Saffron Extract Market
Extracts
Cajeput Oil Market
Extracts
Essential Oil Isolates Market
Extracts
Antioxidants Reagent Market
Extracts
Aloe Vera Derivatives Market
Extracts
Extracts and Distillates Market
Extracts
Black Fungus Extract Market