
 Europe Organic Pet Food for Cats and Dogs Market | 2026-2036
Europe Organic Pet Food for Cats and Dogs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic Pet Food for Cats and Dogs Market Foresight
REACH compliance is broadening the cost-of-entry calculus for new entrants into European organic pet food manufacturing. Mars Petcare leverages its pan-European distribution infrastructure to sustain organic SKU proliferation across multiple member states. Nestlé Purina anchors its competitive stance through specialized veterinary-grade organic lines that command shelf space in premium channels. Hill's Pet Nutrition differentiates via science-backed organic formulations that navigate the gap between clinical nutrition and clean-label consumer expectations.
Europe organic pet food for cats and dogs comprises nutritionally complete and complementary feeding products formulated from ingredients certified under EU organic farming standards, with mandatory restrictions on synthetic pesticides, GMOs, and artificial additives alongside specified minimum organic content thresholds. These products serve the commercial purpose of delivering species-appropriate nutrition while satisfying pet owner preferences for transparency, environmental accountability, and reduced chemical exposure in companion animal diets. Dry food occupies the largest volume position due to logistical efficiency and extended shelf stability, yet wet food captures disproportionate margin pools as consumers trade up toward moisture-rich, minimally processed formats. The ingredient dimension shows meat-derived proteins leading value contribution, though vegetable-sourced formulations are gaining traction among flexitarian pet owners seeking reduced planetary footprint diets for their animals.
The European Food Safety Authority (EFSA) and national regulators such as BfR in Germany and ANSES in France enforce contaminant limits and labeling standards that directly shape product formulation decisions and market access conditions for organic pet food brands. CE marking requirements under the EU Feed Hygiene Regulation establish baseline manufacturing standards that all market participants must satisfy, while national organic certification bodies administer the EU organic logo that commands consumer trust and price premiums. Stakeholders must monitor evolving proposals under the EU Green Deal's Farm to Fork strategy, as anticipated tightening of agricultural input standards will cascade into feed ingredient costs and reformulation requirements across the organic pet food value chain.
Market Dynamics
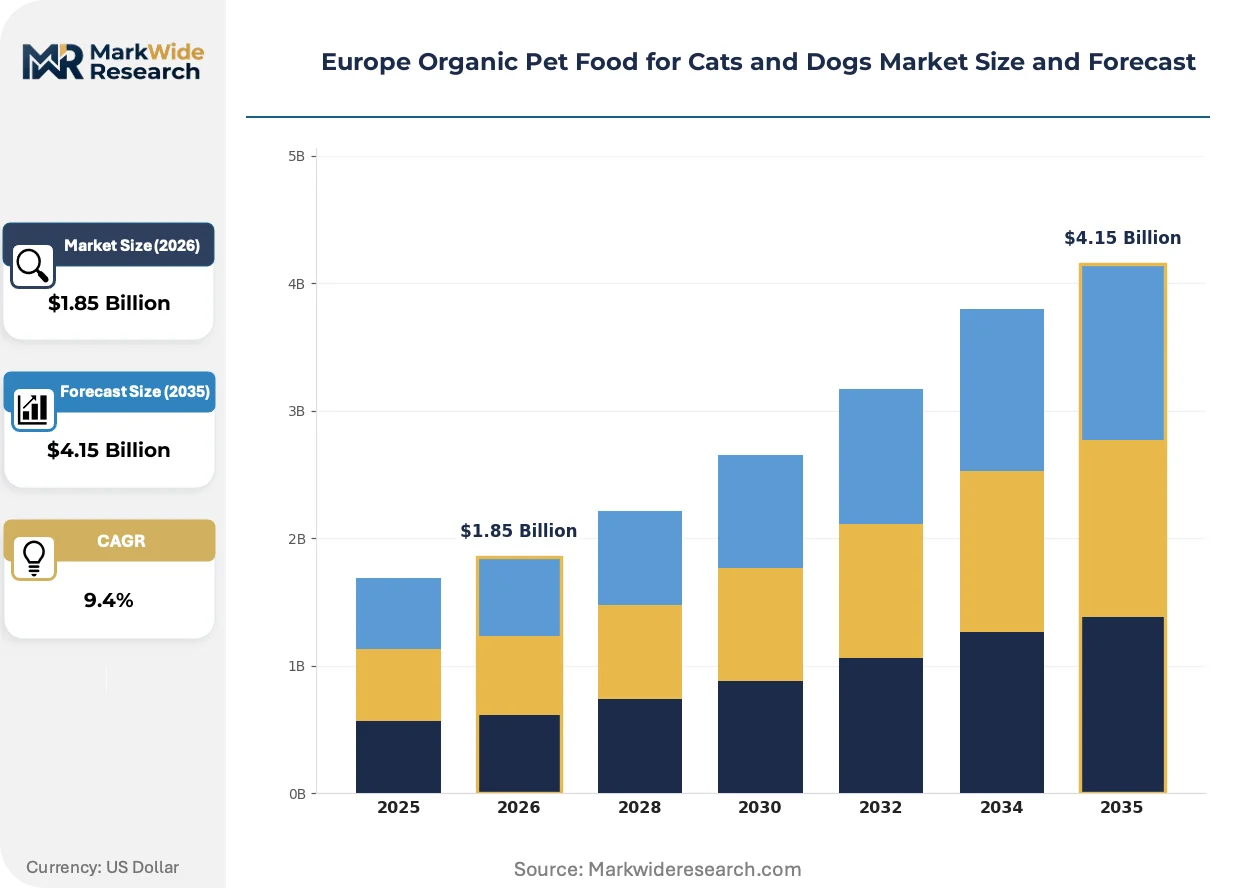
The EU Green Deal is compressing reformulation timelines across European organic pet food supply chains as Farm to Fork mandates cascade from agricultural inputs through finished feed products. This regulatory pressure is restructuring ingredient sourcing relationships and accelerating capital deployment toward certified organic supply networks.
Growth Catalysts
- REACH compliance thresholds:Chemical safety standards under ECHA are filtering out non-compliant ingredient suppliers, consolidating procurement toward certified organic channels that preempt regulatory scrutiny.
- Urban premiumization:Dense metropolitan pet owner populations in Germany, France, and the United Kingdom are concentrating demand for veterinary-recommended organic formulations with transparent provenance claims.
- F-Gas Regulation phase-down:Cold chain refrigeration constraints are favoring dry organic formats with extended ambient stability, reshaping manufacturing investment toward extrusion and dehydration capacity.
Market Restraints
- Organic protein input scarcity:Certified meat and fish meal supplies concentrate among limited EU-registered abattoirs and aquaculture operations, exposing formulators to price volatility and allocation risk.
- CE marking complexity:Feed Hygiene Regulation compliance requires dedicated manufacturing infrastructure that smaller entrants cannot economically justify, elevating cost-of-entry barriers.
- Conventional pet food substitution:Mass-market brands with clean-label positioning capture price-sensitive consumers who prioritize ingredient transparency over full organic certification.
Strategic Opportunities
- Eastern European market development:Poland, Czech Republic, and Romania exhibit rising pet ownership rates with nascent organic certification infrastructure, creating first-mover positioning potential.
- Veterinary channel expansion:Clinic-dispensed organic therapeutic diets command prescription-level margins while building professional endorsement networks that sustain consumer loyalty.
- CSRD-aligned sustainability reporting:Corporate sustainability disclosure requirements are creating procurement preference for organic suppliers with verified Scope 3 emission reductions and regenerative agriculture partnerships.
Industry Challenges
- Organic certification timeline compression:EU organic logo approval processes extend 12-18 months, delaying product launches and trapping working capital in inventory awaiting market authorization.
- Formulation science talent scarcity:Veterinary nutritionists with dual expertise in clinical requirements and organic ingredient constraints command premium compensation, constraining R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic Pet Food for Cats and Dogs Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Type: Meat, Fish, Vegetables, Grains Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pet Shops Customer Type: Pet Owners, Veterinarians, Pet Retailers, Trainers |
| Companies Covered | Mars Petcare, Nestlé Purina, Hill's Pet Nutrition, Royal Canin, Blue Buffalo, Affinity Petcare, WellPet, Natura Plus Ultra Pet Food, Tiernahrung Deuerer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic Pet Food for Cats and Dogs Market Shifts & Advancements
European organic pet food markets are experiencing simultaneous pressure from regulatory tightening and consumer expectation elevation, forcing convergence between sustainability verification and nutritional performance claims.
Novel protein sources including insect meal and cultivated meat precursors are electrifying formulation pipelines as conventional organic meat supplies face agricultural land constraints. Flexitarian pet owners in Scandinavian markets are accelerating trials of vegetable-forward complete diets. This protein diversification is compressing traditional livestock-dependent supply relationships and opening procurement channels to biotechnology suppliers.
EFSA contaminant limit revisions are mandating expanded mycotoxin and heavy metal testing protocols across organic ingredient streams. Manufacturers must now deploy advanced spectroscopy and chromatography systems to maintain batch release authorization. Wet food specialists with integrated testing laboratories are capturing disproportionate shelf space as retailers demand documented safety assurance beyond baseline certification.
Subscription-based direct-to-consumer models are displacing conventional retail stocking arrangements among digitally native pet owners. German and French markets exhibit highest penetration of auto-replenishment platforms that combine veterinary consultation with personalized organic diet curation. This channel shift is fragmenting volume concentration previously held by mass-market supermarkets and hypermarkets.
Europe Organic Pet Food for Cats and Dogs Market Segmentation
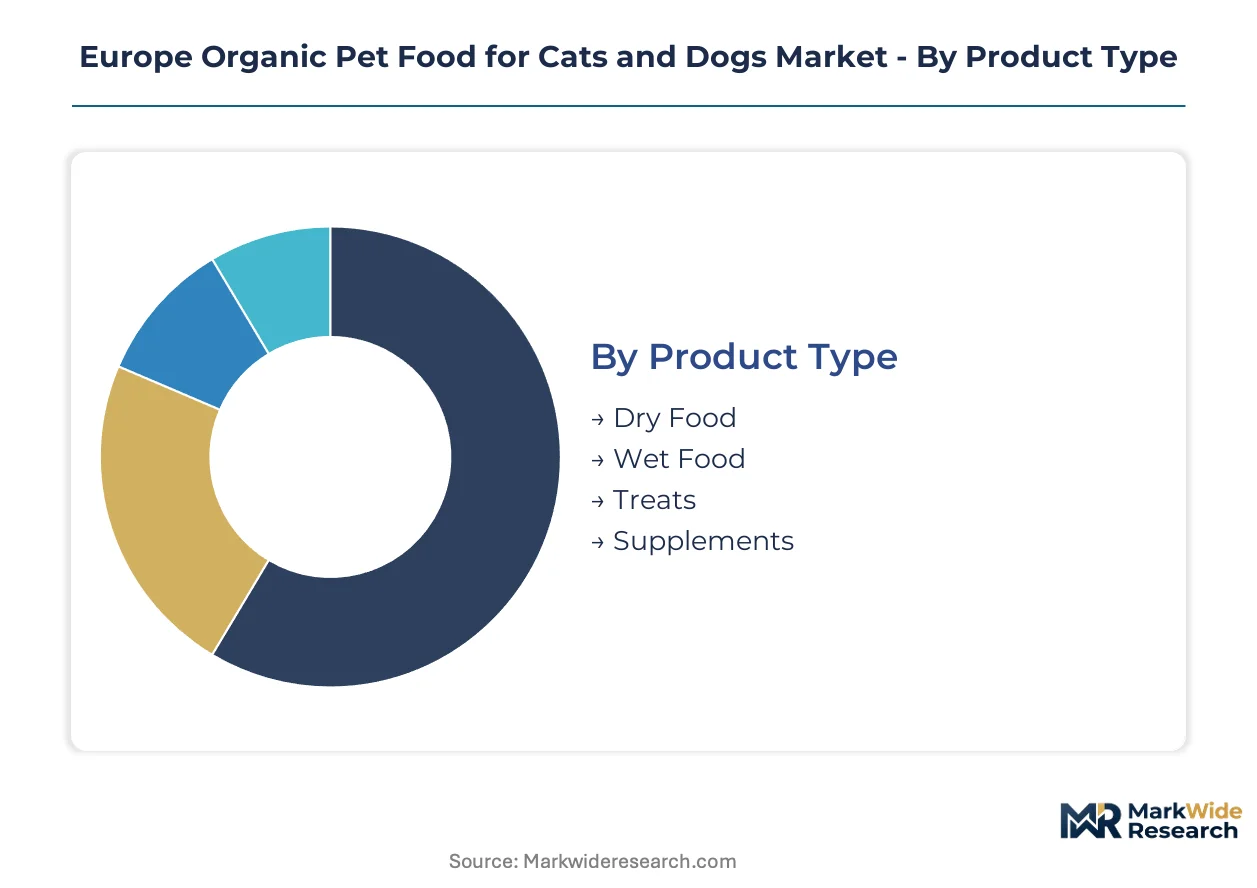
Segmentation in European organic pet food reveals how certification requirements, moisture formats, and channel economics partition demand. Each dimension exposes distinct margin structures and regulatory exposure profiles that shape manufacturer investment priorities.
Product Type:
The customization-standardization spectrum runs from mass-produced extruded kibble to small-batch wet formulations with veterinary customization.
- Dry Food:Extruded and baked formulations with 6-12% moisture content deliver logistical efficiency through ambient distribution. German and French mass-market retailers concentrate procurement here, though EFSA mycotoxin surveillance is tightening batch release protocols.
- Wet Food:Canned and pouch formats with 75-85% moisture content command veterinary channel placement through palatability advantages. Premium urban pet owners in the United Kingdom drive disproportionate margin capture despite cold chain cost penalties.
- Treats:Functional and reward-based formats with targeted health claims. Limited organic certification infrastructure constrains SKU proliferation relative to conventional alternatives.
- Supplements:Nutraceutical add-ons targeting joint, coat, and digestive health. Veterinary endorsement requirements limit direct-to-consumer penetration.
Leading the category by volume: Dry Food. Growing fastest: Wet Food.
Ingredient Type:
Cost tier stratification separates livestock-derived proteins from plant-forward alternatives, with fish occupying a premium midpoint.
- Meat:Beef, poultry, and pork from EU-registered organic abattoirs supply amino acid-complete formulations. German pet owners show strongest preference, though certified slaughterhouse capacity constraints create allocation bottlenecks.
- Fish:Wild-caught and aquaculture-derived marine proteins deliver omega-3 fatty acid profiles. Scandinavian markets exhibit highest per-capita consumption, with MSC-organic dual certification commanding shelf space premiums.
- Vegetables:Legume and root-based formulations targeting flexitarian pet owner values. French and Benelux markets show accelerating trial rates for reduced planetary footprint positioning.
- Grains:Rice, oats, and ancient grain carbohydrate bases. Grain-free trend compression has shifted volume toward vegetable-sourced alternatives in premium channels.
Leading the category by value contribution: Meat. Expanding most quickly: Vegetables.
Distribution Channel:
Margin concentration flows toward channels with professional endorsement capacity, while volume aggregates in high-frequency retail.
- Online Retail:Subscription platforms and veterinary-integrated e-commerce. German auto-replenishment penetration leads Europe, with personalized diet curation building switching costs.
- Specialty Stores:Independent pet boutiques with certified organic focus. United Kingdom and France sustain highest store density, though rent inflation is compressing independent viability.
- Supermarkets:Mass-market grocers with private-label organic expansion. Price transparency pressures limit branded premium capture.
- Pet Shops:Chain and franchise networks with veterinary consultation integration. Eastern European markets show fastest network expansion as pet ownership rates climb.
Leading the category by transaction volume: Supermarkets. Gaining share fastest: Online Retail.
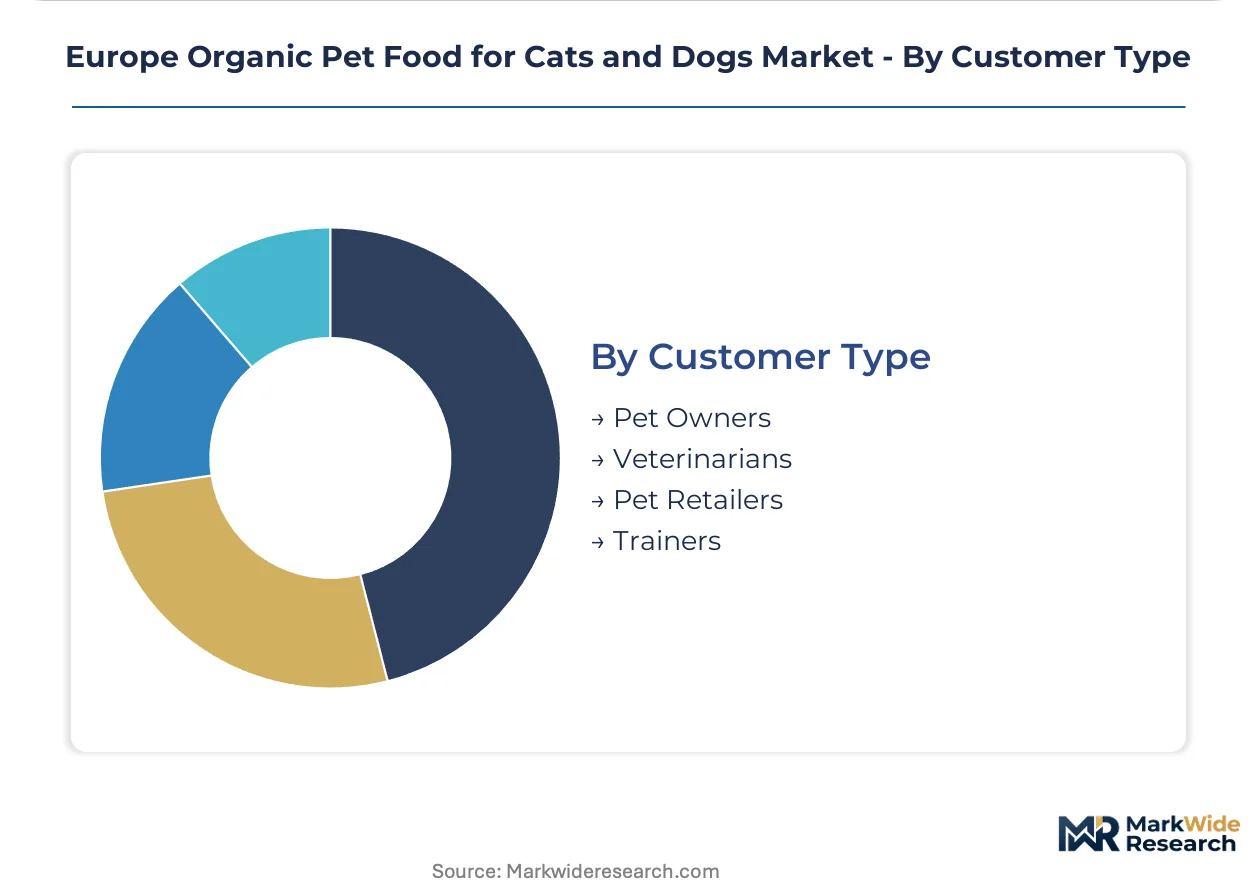
Customer Type:
Application maturity separates established pet owner mass demand from emerging professional channel prescription economics.
- Pet Owners:End consumers making discretionary purchase decisions. Urban density in Germany, France, and the United Kingdom concentrates premiumization willingness.
- Veterinarians:Clinical prescribers of therapeutic organic diets. Prescription-level margins and professional endorsement networks sustain loyalty.
- Pet Retailers:B2B procurement for resale through physical and digital storefronts. Category management sophistication varies across national markets.
- Trainers:Professional behavior specialists integrating nutrition into conditioning protocols. Niche volume with high treat-format concentration.
Leading the category by absolute spend: Pet Owners. Steepest expansion trajectory: Veterinarians.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU organic certification zones in Germany and France concentrate manufacturing investment through feed-grade tax incentives and streamlined Farm to Fork compliance pathways. These regulatory advantages draw ingredient suppliers and extrusion capacity toward the Rhine-Ruhr and Île-de-France corridors.
Germany
Urban pet owner density in Berlin, Munich, and Hamburg concentrates demand for veterinary-recommended organic formulations. BfR enforces contaminant limits that exceed baseline EFSA thresholds, filtering out non-compliant suppliers. The Rhine-Ruhr industrial cluster hosts extrusion and dehydration capacity serving pan-European distribution networks.
France
Flexitarian pet owner values in Paris and Lyon accelerate trials of vegetable-forward complete diets. ANSES mandates expanded mycotoxin testing protocols that reshape batch release economics. The Île-de-France corridor anchors wet food specialists with integrated spectroscopy laboratories for retailer safety assurance.
United Kingdom
Premium urban pet owners in London and Manchester drive disproportionate wet food margin capture despite cold chain penalties. F-Gas Regulation phase-down constraints favor dry format investment in Midlands manufacturing zones. Subscription auto-replenishment platforms penetrate highest here, fragmenting supermarket volume concentration.
Italy
Specialty store density in Milan and Rome sustains independent pet boutique networks with certified organic focus. CE marking requirements under EU Feed Hygiene Regulation elevate cost-of-entry for smaller domestic formulators. The Emilia-Romagna cluster develops private-label organic capacity for mass-market grocer expansion.
Poland
Rising pet ownership rates in Warsaw and Kraków coincide with nascent organic certification infrastructure creating first-mover positioning potential. National organic logo approval timelines extend procurement relationships toward established EU-registered suppliers. Poznań manufacturing zones attract German and French capital for extrusion capacity serving Eastern European demand.
Europe Organic Pet Food for Cats and Dogs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification and channel positioning. Mars Petcare and Nestlé Purina anchor consolidated share through pan-European distribution infrastructure and veterinary endorsement networks. Hill's Pet Nutrition and Royal Canin occupy science-backed therapeutic positioning. Competitive moves concentrate on SKU proliferation into wet formats and subscription platform integration.
Among diversified multinational holdings, Mars Petcare and Nestlé Purina exemplify scale-driven archetypes leveraging cross-border logistics and retail category management. Hill's Pet Nutrition represents the clinical-nutrition specialist tier bridging veterinary prescription economics with clean-label consumer expectations. These three anchors sit within distinct competitive vectors: mass-market penetration, premium channel capture, and professional endorsement networks.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina |
| Hill's Pet Nutrition |
| Royal Canin |
| Blue Buffalo |
| Affinity Petcare |
| WellPet |
| Natura Plus Ultra Pet Food |
| Tiernahrung Deuerer |
| Others |
Supply & Pricing Matrix
Certified organic meat and fish meal from EU-registered abattoirs and aquaculture operations flows through tiered pricing structures that reward long-term procurement contracts with price stability, while spot purchases of scarce protein inputs command substantial premiums from formulators facing Farm to Fork compliance deadlines.
Pricing Analysis
Lead-time compression drives pricing stratification across the European organic pet food value chain, with veterinary-channel wet formulations carrying 30-40% premiums over mass-market dry equivalents due to cold chain requirements and batch-level safety documentation. Price differentiation hinges on EU organic logo certification tier and volume scale, with private-label supermarket contracts experiencing margin compression from retailer price transparency demands while subscription-based direct-to-consumer platforms sustain pricing power through personalized diet curation. Pricing pressure stems from certified protein input scarcity concentrated among limited German and French slaughterhouse suppliers. Mass-market pet owners exhibit highest price sensitivity, trading down to clean-label conventional alternatives, whereas urban flexitarian consumers in Scandinavian markets show lowest elasticity for vegetable-forward complete diets.
Supply Chain Analysis
Direct-to-veterinary channels handle prescription-grade organic therapeutic demand, while mass-market distribution runs through German and French supermarket networks with private-label expansion compressing branded shelf space. Geographic supply concentration centers on Germany, France, and the Netherlands for extrusion and dehydration capacity, with Denmark and Norway anchoring marine protein sourcing for omega-3 formulations. Raw material dependencies include certified organic meat meals, fish oils, and legume proteins from regenerative agriculture partnerships. Single-source vulnerability in EU-registered abattoir capacity creates allocation risk during seasonal livestock cycles. Distribution downstream fragments between subscription auto-replenishment platforms gaining share in United Kingdom urban corridors and traditional pet shop networks expanding across Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
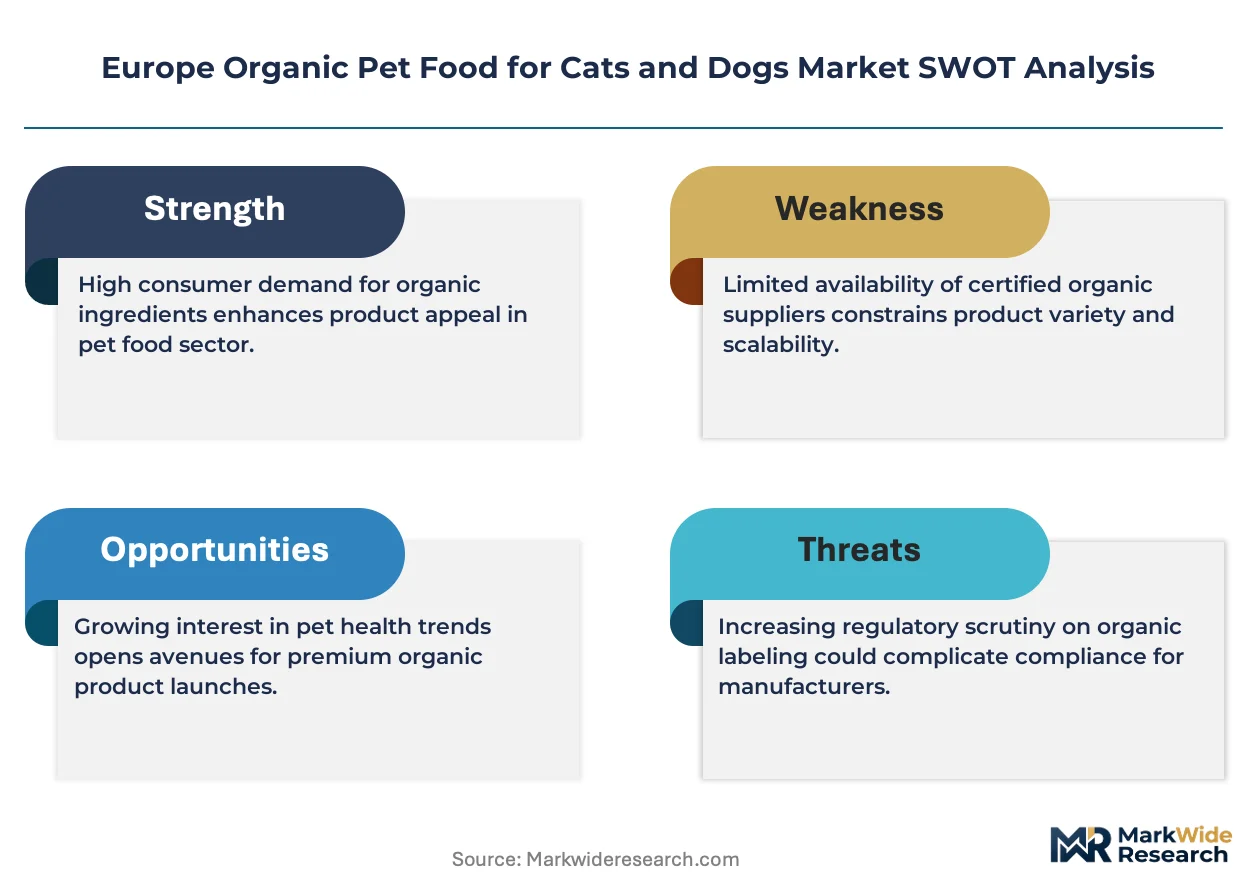
European organic pet food markets operate under structural supply constraint, with limited EU-registered abattoir and aquaculture certification capacity propping input pricing and consolidating procurement power among incumbent formulators with established supplier relationships.
For Market Incumbents: Hedge against protein input volatility through backward integration into regenerative agriculture partnerships and captive supply agreements with Scandinavian aquaculture operators. Expand wet format manufacturing capacity in Île-de-France and Rhine-Ruhr corridors to capture veterinary-channel prescription margins. Defensive positioning requires preemptive investment in spectroscopy and chromatography testing infrastructure ahead of anticipated EFSA contaminant limit revisions. For New Entrants and Emerging Players: Enter via subscription-based direct-to-consumer platforms in United Kingdom and German urban corridors, where auto-replenishment penetration fragments incumbent supermarket dominance. Target Poland, Czech Republic, and Romania as white-space geographies with rising pet ownership rates and nascent organic certification infrastructure. Prioritize vegetable-forward complete diet formulations to bypass conventional livestock protein scarcity and align with flexitarian consumer values in Benelux and Scandinavian markets. For Investors and Strategic Acquirers: Accelerated M&A activity among wet food specialists with integrated testing laboratories is the leading indicator that veterinary-channel margin pools are consolidating ahead of retailer safety assurance demands. Long-term viability favors acquisition targets with dual certification infrastructure spanning EU organic logo and MSC marine sustainability standards. Watch for inflection signals in national organic logo approval timeline compression, which will trap working capital and strain subscale formulators into distressed exit scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Expansion | Clinic-dispensed organic therapeutic diets command prescription-level margins through BfR and ANSES endorsement networks. |
| Regenerative Agriculture Partnership | CSRD-aligned Scope 3 emission reductions create procurement preference for suppliers with verified carbon-negative feedstock programs. |
| Wet Format Manufacturing Scale-Up | Integrated spectroscopy laboratories capture disproportionate shelf space as EFSA mycotoxin surveillance tightens batch release protocols. |
| Eastern European Distribution Buildout | Pet shop network expansion in Poland and Romania concentrates first-mover positioning before organic certification infrastructure matures. |
| Novel Protein Sourcing Diversification | Insect meal and cultivated meat precursors decompress traditional livestock-dependent supply relationships facing agricultural land constraints. |
Research Methodology
Multi-period observation of EU organic certification approval timelines, REACH compliance cost trajectories, and veterinary-channel margin evolution anchored the trend analysis, supplemented by interviews with pet food formulators, regulatory affairs specialists at national certification bodies, procurement leads at mass-market retailers, and veterinary nutritionists with dual expertise in clinical requirements and organic ingredient constraints. Secondary validation drew from EFSA contaminant surveillance reports, EU Feed Hygiene Regulation implementation guidance, national organic farming statistics, and trade data on certified meat and fish meal flows. Bottom-up SKU-level volume modeling triangulated against top-down category expenditure estimates from retail audit databases.
Segment-weighting approaches applied differential growth assumptions across dry, wet, treat, and supplement formats, with ingredient-type stratification modeling meat, fish, vegetable, and grain protein sourcing economics. Distribution channel segmentation captured online subscription penetration trajectories, specialty store rent inflation effects, and supermarket private-label expansion dynamics. CAGRs derived from regression analysis of historical certification capacity expansion, projected against Farm to Fork agricultural input standard tightening. Forecast inputs included anticipated F-Gas Regulation phase-down impacts on cold chain cost structures and CSRD disclosure requirements shaping procurement preference evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal implementation or prolonged organic protein input scarcity extending approval timelines beyond standard 12-18 month windows. Periodic stress-testing of base assumptions is recommended, particularly regarding national regulatory divergence from EFSA baseline thresholds and biotechnology supplier readiness for novel protein scale-up.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Japan Dog Food Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Pet Care Market
Pet Care Products
Pet Relaxants Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Pet Beds Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Dog Raincoats Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
UK Pet Training Services Market