
 Independent Software Vendors (Isvs) Market | 2026-2036
Independent Software Vendors (Isvs) Market Size, Share, and Industry Trends Forecast 2026-2036
Independent Software Vendors (Isvs) Market Analysis
North American cloud infrastructure capacity is rebalancing as hyperscaler investments shift toward sovereign data residency requirements. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise workloads across regulated verticals. Oracle Corporation sustains database-to-cloud migration momentum through aggressive R&D intensity in autonomous systems. SAP SE dominates ERP modernization cycles in European manufacturing accounts.
Independent Software Vendors design, develop, and distribute proprietary software applications operating on third-party hardware or cloud infrastructure, typically delivered through licensing, subscription, or usage-based monetization models with API interoperability and multi-tenant architecture as core technical parameters. Their primary commercial purpose centers on solving specialized business problems—from financial reconciliation to patient record management—without owning the underlying computing platform. Cloud-based deployment now leads revenue contribution as enterprises exit capital-intensive on-premises estates, while vertical solutions command premium pricing through industry-specific compliance certifications and pre-configured workflows. Horizontal solutions compete on scale economics across mid-market segments where standardization outweighs customization needs.
FDA 21 CFR Part 11 and HIPAA constrain healthcare software validation requirements in the United States, while the EU AI Act imposes risk-tiered conformity obligations on vendors deploying algorithmic decision tools in European jurisdictions. EMA and national competent authorities are tightening pharmacovigilance software standards, forcing ISVs to embed audit trails and explainability modules. Stakeholders must monitor divergence between United States sectoral privacy frameworks and European horizontal AI governance as this regulatory fragmentation threatens interoperability roadmaps and compliance cost structures.
Market Dynamics
Cloud-native architectures are displacing monolithic legacy stacks as enterprises prioritize API interoperability and sovereign data residency over capital-intensive on-premises estates.
Growth Catalysts
- EU AI Act conformity mandates:Risk-tiered algorithmic governance requirements in European jurisdictions are accelerating procurement of certified clinical decision-support tools by healthcare providers seeking preemptive compliance.
- API-first interoperability standards:Healthcare systems in the United States demand seamless electronic health record integration, pulling ISV investment toward Fast Healthcare Interoperability Resources (FHIR) compliance.
- Hyperscaler infrastructure expansion:Microsoft Azure and AWS sovereign cloud regions in Germany, India, and the United States are reducing data localization barriers for regulated verticals.
Market Restraints
- Specialized compliance engineering talent scarcity:FDA 21 CFR Part 11 validation expertise commands premium compensation, inflating R&D cost structures for clinical software vendors.
- Concentrated hyperscaler dependency:Three cloud infrastructure providers control essential compute and storage capacity, exposing ISVs to egress pricing volatility and service continuity risk.
- Legacy technical debt drag:Enterprises running COBOL and early-generation ERP cores face prohibitive migration costs, delaying subscription revenue conversion for modernization vendors.
Strategic Opportunities
- Indian pharmaceutical manufacturing digitization:CDSCO pharmacovigilance mandates and PLI scheme incentives are creating first-mover advantage for clinical trial management software providers.
- Edge-to-cloud orchestration convergence:Manufacturing ISVs embedding AI inference at plant level while synchronizing with central ERP systems can capture premium pricing in German automotive supply chains.
- Outcome-based contracting channels:Hospital systems in the United States are piloting utilization-linked pricing for surgical planning software, displacing perpetual license models.
Industry Challenges
- FHIR certification timeline compression:ONC interoperability rule deadlines are forcing engineering teams to accelerate validation cycles without compromising HIPAA security controls.
- Cross-border data governance fragmentation:Divergent United States sectoral privacy frameworks and European horizontal AI governance are complicating unified product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Independent Software Vendors (Isvs) Market |
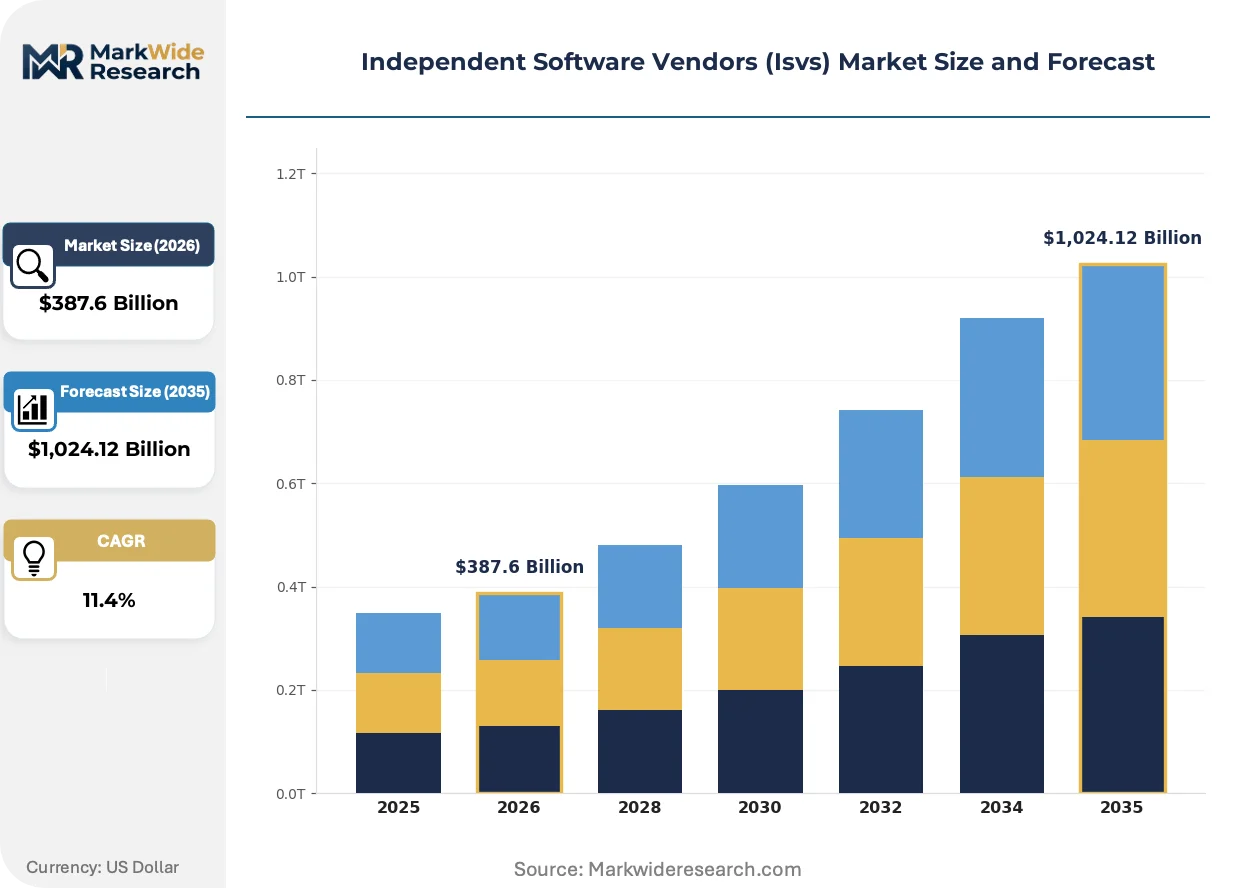
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Solution Type: Vertical Solutions, Horizontal Solutions, Custom Solutions, Middleware End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Industry Vertical: Healthcare, Finance, Retail, Education |
| Companies Covered | Microsoft Corporation, Oracle Corporation, Salesforce Inc., SAP SE, IBM Corporation, Cisco Systems, Inc., Adobe Inc., ServiceNow, Inc., Intuit Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Independent Software Vendors (Isvs) Market Emerging Trajectories
Generative AI coding assistants and autonomous testing platforms are compressing software release cycles while elevating quality assurance standards across regulated verticals.
Containerized microservices architecture is decentralizing enterprise software deployment from centralized data centers toward distributed edge nodes. Manufacturing ISVs in Germany are adopting Kubernetes-orchestrated workloads to enable real-time quality control at production lines. This topology is decentralizing latency-sensitive applications from hyperscaler core regions toward plant-level infrastructure, reducing bandwidth costs while complicating centralized security governance.
The EU AI Act's risk-based conformity assessment framework is mandating algorithmic explainability modules for high-risk decision-support systems. ISVs deploying diagnostic imaging tools must embed technical documentation and human oversight protocols before European market entry. Clinical software vendors are responding by restructuring product teams to include ethicists and regulatory engineers alongside traditional developers.
Hospital procurement committees are consolidating vendor relationships around integrated platform ecosystems rather than point solutions. United States health systems are favoring ISVs offering unified clinical, financial, and operational modules over specialized single-function tools. This concentration is displacing standalone revenue cycle management vendors in favor of comprehensive electronic health record platforms with embedded billing capabilities.
Independent Software Vendors (Isvs) Market Segmentation
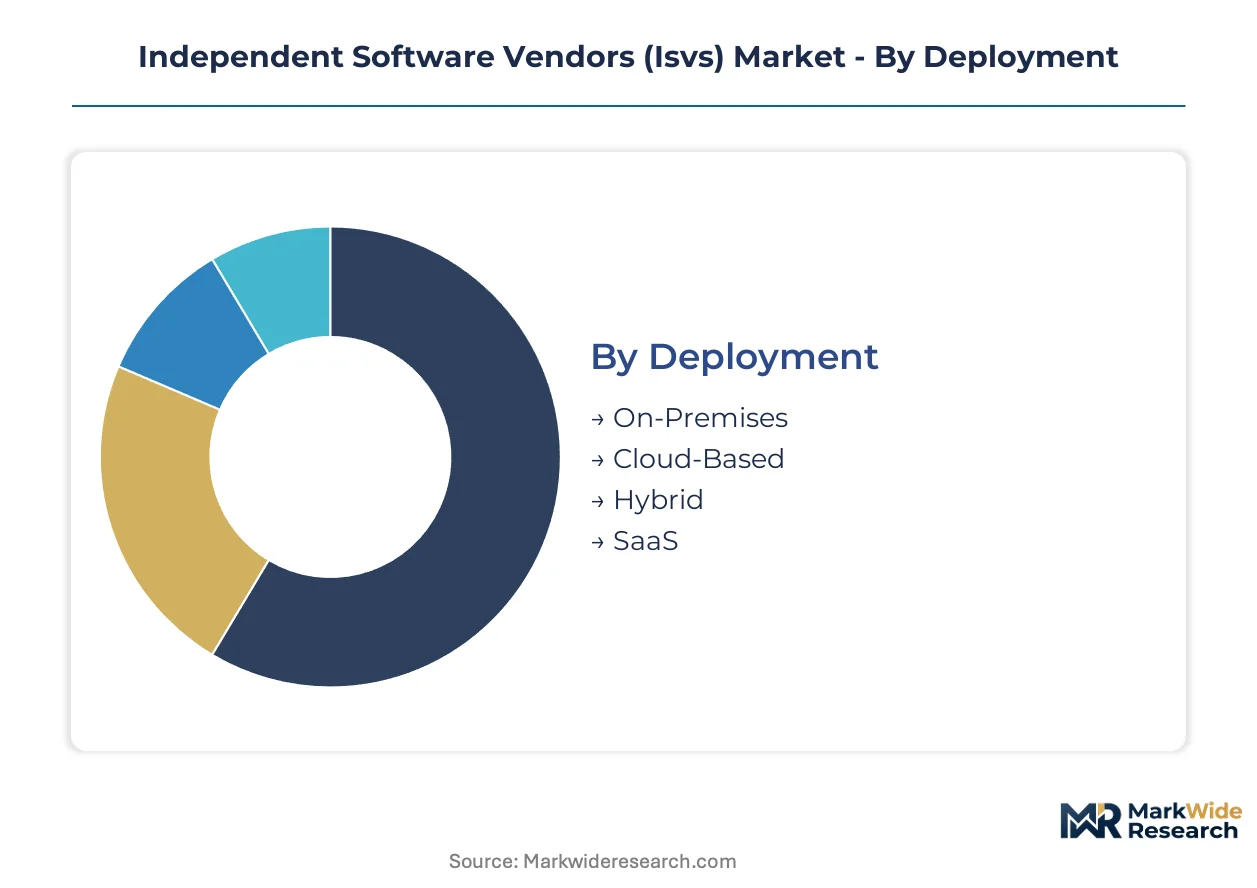
ISV revenue flows diverge sharply across deployment architectures and buyer scale, with compliance certification requirements fragmenting addressable markets. Procurement committees in regulated verticals now prioritize sovereign data residency over cost optimization, compressing vendor qualification timelines.
Deployment:
Supply concentration among hyperscalers is reshaping how ISVs architect delivery models and margin structures.
- Cloud-Based:Multi-tenant architectures running on Azure, AWS, or GCP infrastructure dominate new procurement in healthcare and finance. German automotive manufacturers and United States hospital systems are mandating EU or domestic data residency, pulling ISVs toward sovereign cloud regions.
- SaaS:Subscription monetization with API-first interoperability standards commands premium pricing in mid-market segments. Indian pharmaceutical manufacturers under CDSCO pharmacovigilance mandates are accelerating SaaS adoption for clinical trial management.
- On-Premises:Legacy estates in government and defense sectors where air-gapped security is non-negotiable.
- Hybrid:Edge-to-core orchestration for manufacturing quality control with central ERP synchronization.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
Solution Type:
Cost tier stratification separates standardized horizontal tools from compliance-intensive vertical offerings.
- Vertical Solutions:Pre-configured workflows with embedded FDA 21 CFR Part 11 or EU AI Act certification modules. United States health systems pay substantial premiums for clinical decision-support tools with embedded HIPAA audit trails.
- Horizontal Solutions:ERP, CRM, and HCM platforms competing on scale economics across standardized mid-market processes. German manufacturing accounts favor SAP-integrated modules over point solutions.
- Custom Solutions:Bespoke development for specialized government or defense requirements with proprietary security protocols.
- Middleware:FHIR-compliant integration layers enabling electronic health record interoperability in United States hospital networks.
Vertical Solutions command the highest margin per seat; Horizontal Solutions scale fastest across enterprise segments.
End User:
Customer type determines sales cycle length and contract structure more than any other segmentation dimension.
- Large Enterprises:Procurement committees consolidate around integrated platform ecosystems with outcome-based contracting pilots. United States health systems favor unified clinical, financial, and operational modules.
- Medium Enterprises:Standardized cloud migration with API interoperability as the primary selection criterion.
- Small Enterprises:Price-sensitive adoption of off-the-shelf SaaS with minimal customization.
- Government:Sovereign data residency and FedRAMP or equivalent certification requirements.
Large Enterprises absorb the bulk of contract value; Medium Enterprises are climbing the fastest as digitization spreads.
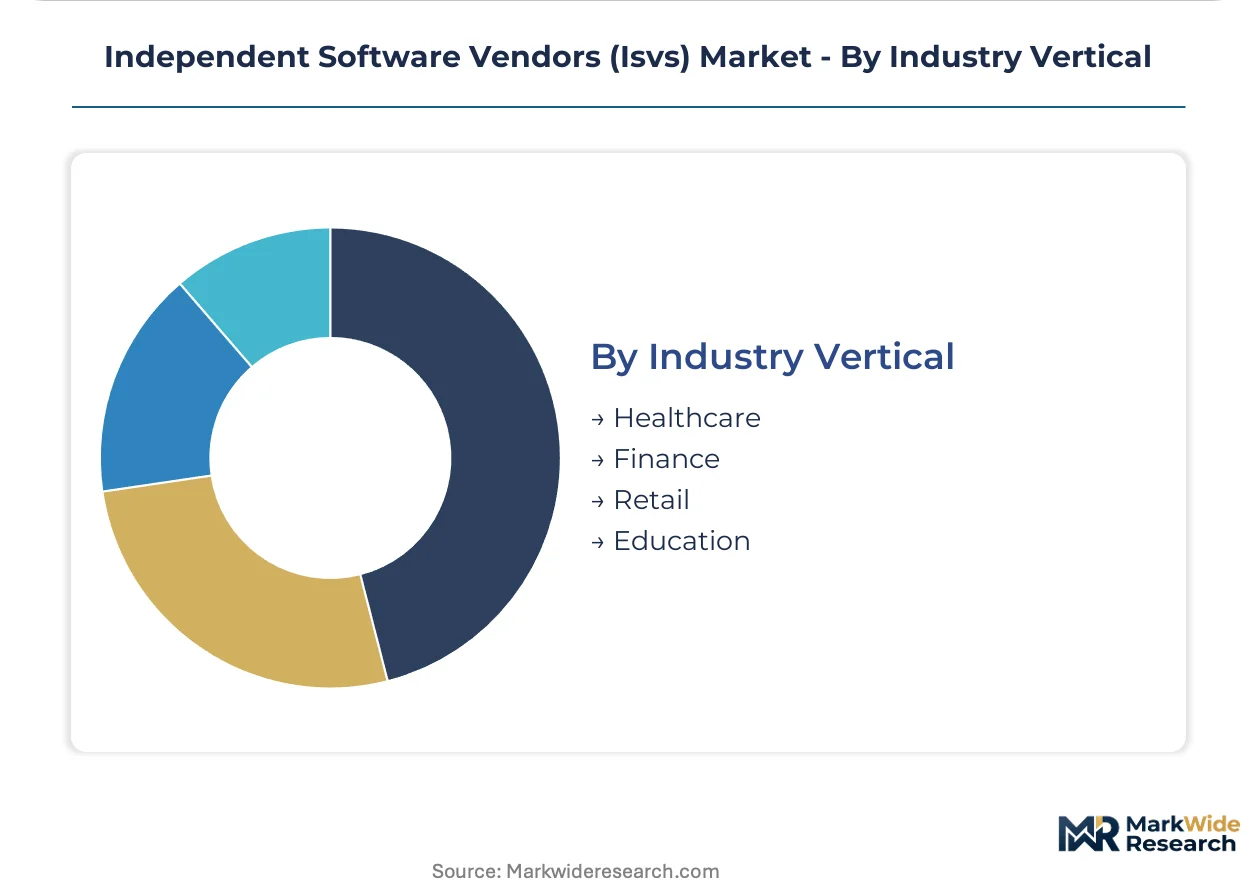
Industry Vertical:
Application-specific compliance burdens create divergent R&D intensity requirements across verticals.
- Healthcare:Algorithmic explainability modules and human oversight protocols mandated by EU AI Act for diagnostic imaging tools. EMA pharmacovigilance standards force embedded audit trails.
- Finance:Real-time reconciliation and fraud detection with SEC reporting integration.
- Retail:Inventory optimization and customer analytics with lower compliance overhead.
- Education:Learning management systems with FERPA-aligned data governance.
Healthcare absorbs the bulk of compliance-engineering investment; Finance is gaining share fastest as regulatory scrutiny intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments from hyperscalers anchor regional demand patterns across sovereign data residency requirements. Enterprise digitization concentrates procurement in jurisdictions with mature regulatory frameworks and established industrial clusters.
United States
Federal cloud migration mandates and hospital system consolidation drive procurement of clinical decision-support platforms. FDA 21 CFR Part 11 validation requirements constrain vendor qualification timelines for electronic health record integrations. The Boston-Cambridge corridor hosts specialized compliance engineering talent pools serving pharmaceutical software developers.
Germany
Automotive supply chain digitization and EU AI Act conformity deadlines accelerate edge-to-cloud orchestration investments. The KBA and national competent authorities enforce algorithmic explainability standards for manufacturing quality systems. Baden-Württemberg's industrial belt concentrates Kubernetes-orchestrated deployments for real-time production control.
India
CDSCO pharmacovigilance mandates and PLI scheme incentives pull clinical trial management software adoption among pharmaceutical manufacturers. RBI and SEBI data localization rules reshape financial services software architecture. Hyderabad and Bengaluru clusters host captive development centers serving global healthcare ISVs.
United Kingdom
NHS procurement centralization favors integrated platform ecosystems over point solutions for hospital networks. MHRA alignment with EMA pharmacovigilance standards forces embedded audit trail capabilities. London's fintech corridor sustains demand for real-time reconciliation and fraud detection modules.
Japan
METI digital transformation subsidies and aging demographics drive healthcare software modernization among regional hospital networks. PMDA software as medical device regulations constrain algorithmic diagnostic tool deployment. The Osaka-Kobe manufacturing belt sustains ERP modernization cycles among precision machinery suppliers.
Independent Software Vendors (Isvs) Market Vendor Landscape
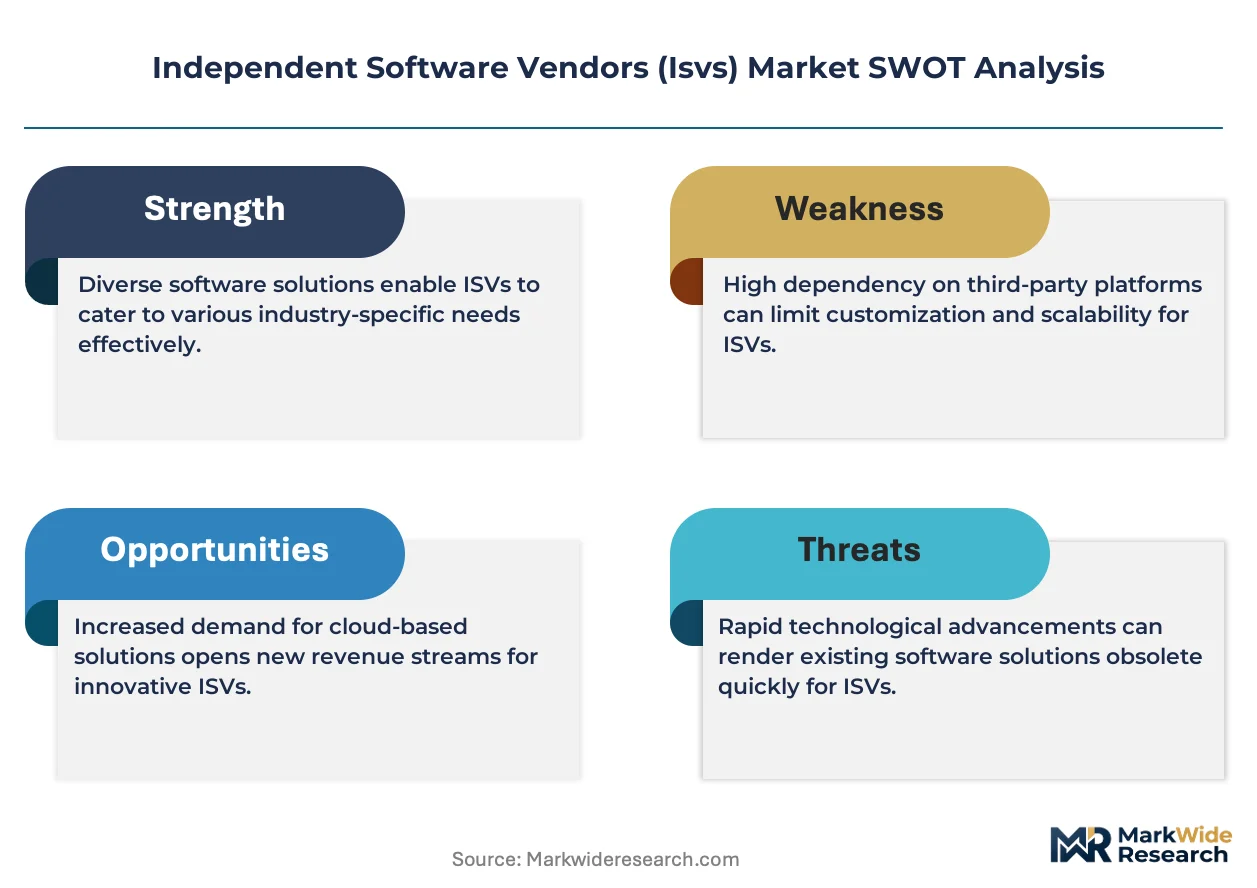
Global majors compete with regional champions across sovereign cloud certification and vertical-specific compliance engineering. The vendor base organizes around hyperscaler-aligned platform ecosystems, specialized vertical solution providers, and legacy modernization specialists. Three archetypes dominate: cloud-native disruptors with API-first architectures, incumbent ERP vendors defending installed bases through modular cloud extensions, and compliance-focused specialists embedding regulatory protocols as core differentiators. M&A activity concentrates on clinical workflow automation and edge computing capabilities, while strategic partnerships with sovereign cloud providers accelerate market access in regulated jurisdictions.
Within the hyperscaler-aligned tier, Microsoft Corporation and Oracle Corporation exemplify platform ecosystem strategies anchoring enterprise workloads across regulated verticals. SAP SE occupies a position representing ERP modernization specialists defending European manufacturing accounts through autonomous database-to-cloud migration tools. These three entities sit within the consolidated core where R&D intensity and compliance certification capabilities create defensive moats against specialized challengers.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| Salesforce Inc. |
| SAP SE |
| IBM Corporation |
| Cisco Systems, Inc. |
| Adobe Inc. |
| ServiceNow, Inc. |
| Intuit Inc. |
| Others |
Supply Flow & Price Mechanics
Hyperscaler compute pricing indices cascade through ISV cost structures, compressing margins for cloud-native entrants while enabling premium tiering for compliance-certified vertical solutions. Sovereign data residency requirements in Germany and India reshape procurement cost calculations as buyers absorb localization premiums.
Pricing Analysis
Service bundling separates compliance-validated packages from stripped-down API-only tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR Part 11 certification depth and embedded audit trail capabilities. Cost compression in mid-market SaaS intensifies as hyperscaler egress fees inflate operational overhead. Small enterprises exhibit highest price sensitivity, while United States hospital systems accept substantial premiums for unified platform ecosystems with outcome-based contracting pilots.
Supply Chain Analysis
Freight costs for edge hardware shipments to manufacturing plants in Germany and automotive corridors in Mexico strain working capital cycles for ISVs deploying Kubernetes-orchestrated quality control systems. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore, drawing from specialized semiconductor components and sovereign-certified server hardware. Single-source vulnerability around NVIDIA GPU allocations threatens AI inference deployment timelines. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with embedded solution architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISV competitive positioning hinges on vertical-integration races into compliance engineering capabilities and captive cloud infrastructure. Players are pursuing backward integration into regulatory certification workflows as the decisive upstream lever.
For Market Incumbents: Anticipate API-first disruptors attacking mid-market horizontal segments with FHIR-compliant interoperability tools. Incumbents must consolidate channel control through exclusive hyperscaler marketplace partnerships and deepen investment in autonomous validation pipelines for FDA 21 CFR Part 11 submissions. Certification investment in EU AI Act conformity modules defends margin position against European regulatory fragmentation. For New Entrants and Emerging Players: Medium-sized pharmaceutical manufacturers in India under CDSCO pharmacovigilance mandates represent the most penetrable buyer archetype. White-space targets include clinical trial management SaaS with embedded PLI scheme compliance tracking and edge-to-cloud orchestration for German automotive Tier 2 suppliers. Go-to-market execution should anchor on channel partnerships with system integrators possessing existing manufacturing vertical relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-focused specialists with embedded FDA and EMA certification libraries in the United States and United Kingdom. Long-term viability across the analysis window rests on algorithmic explainability IP and sovereign cloud deployment capabilities. The signal to watch is consolidation velocity among hospital procurement committees favoring integrated platforms over point solutions.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | EMA-aligned algorithmic explainability modules unlock European healthcare procurement channels. |
| Hyperscaler Sovereign Cloud Partnership | Azure and AWS dedicated regions in Germany and India satisfy data residency mandates for regulated verticals. |
| Acquisition of Compliance Engineering Specialist | FDA 21 CFR Part 11 validation expertise compresses product launch timelines for clinical software vendors. |
| Edge-to-Cloud Orchestration Platform Launch | Kubernetes-based manufacturing quality systems capture premium pricing in German automotive supply chains. |
| FHIR-First Interoperability Expansion | Fast Healthcare Interoperability Resources compliance secures United States hospital system procurement contracts. |
Methodological Framework
SEC 10-K filings, hyperscaler capex disclosures, and FDA 510(k) clearance databases formed the secondary backbone of data collection. Primary interviews with CTOs, hospital procurement officers, platform engineers, and regulatory affairs specialists at healthcare ISVs validated bottom-up estimates against top-down market sizing. Triangulation across deployment model, organization size, vertical specialization, and regional adoption patterns anchored segmentation integrity.
Bottom-up modeling aggregated individual vendor revenue streams across cloud-based, SaaS, on-premises, and hybrid deployment architectures. Top-down validation cross-referenced aggregate spending patterns from enterprise IT budget surveys and GPO contract databases. CAGRs were derived from regression analysis against digitization maturity indices and regulatory compliance deadline schedules. Forecast inputs incorporated EU AI Act implementation timelines and CDSCO pharmacovigilance mandate enforcement intensity.
Revisions become necessary when sovereign data residency requirements expand to additional jurisdictions or hyperscaler pricing structures undergo structural recalibration. Forecasts reflect assumptions about regulatory harmonization velocity and cloud infrastructure capacity expansion trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Spa and Salon Software Market
Software & Services
Session Support Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Middleware Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Cricket Analysis Software Market
Software & Services
HSM-As-A-Service Market
Software & Services
Device Tracking Software Market
Software & Services
Test Management Software Market
Software & Services
Product Optimization Software Market
Software & Services
Global Intelligent Apps Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
RFP Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Global Journal App Market
Software & Services
Cloud-Based ERP Software Market