
 Phytochemicals Market | 2026-2036
Phytochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Phytochemicals Market Outlook
Specialized ingredient distribution is narrowing as consolidated nutraceutical formulators demand certified supply chains with full traceability documentation. Naturex leverages backward integration into Mediterranean botanical sourcing to secure raw material consistency. Euromed sustains competitive positioning through advanced supercritical CO2 extraction capabilities for thermolabile compounds. Indena SPA dominates the pharmaceutical-grade segment with patented phytosome delivery technologies.
Phytochemicals constitute bioactive secondary metabolites synthesized by plants, including flavonoids, alkaloids, terpenes, and polyphenols, typically extracted via solvent extraction, supercritical fluid methods, or chromatographic purification to achieve standardized potency for industrial applications. These compounds serve primarily as functional ingredients conferring antioxidant, anti-inflammatory, or antimicrobial properties in formulated consumer and therapeutic products. Flavonoids and polyphenols anchor the value pool due to their extensive validation in cardiovascular and metabolic health applications, while terpenes represent the fastest-expanding category driven by aroma-therapeutic and cannabis-adjacent product pipelines. Alkaloids occupy a mature, high-margin niche where synthetic biology competitors threaten long-term volume growth.
EFSA health claims regulation and FDA NDI notifications impose substantial substantiation burdens on novel phytochemical introductions, effectively filtering market access to well-capitalized players with clinical trial capabilities. REACH compliance for botanical imports into Europe adds toxicological documentation requirements that smaller extract houses struggle to meet. Stakeholders must monitor evolving pharmacovigilance frameworks and synthetic biology cost curves to determine whether to deepen natural extraction investments or pivot toward fermentation-derived equivalents.
Market Dynamics
Consolidation among nutraceutical formulators is compressing supplier margins while demanding certified supply chains with full traceability documentation from botanical extract houses.
Growth Catalysts
- EFSA Health Claims Pathway:Validated polyphenol extracts gain preferred positioning in European functional food formulations, accelerating procurement from standardized suppliers.
- Supercritical CO2 Extraction:Advanced solvent-free methods preserve thermolabile terpene profiles for pharmaceutical-grade applications, expanding addressable product categories.
- Germany:Botanical extract clusters around Hamburg and Frankfurt supply corridors concentrate formulation expertise and logistics infrastructure for continental distribution.
Market Restraints
- Raw Material Volatility:Mediterranean botanical harvests face climate-driven yield fluctuations, compressing margin predictability for standardized extract producers.
- REACH Compliance Burden:Toxicological documentation requirements for botanical imports into Europe filter market access to well-capitalized players with dedicated regulatory affairs functions.
- Synthetic Biology Substitution:Fermentation-derived alkaloid equivalents threaten long-term volume growth in mature pharmaceutical applications where purity specifications allow synthetic sourcing.
Strategic Opportunities
- Phytosome Delivery Systems:Enhanced bioavailability technologies open pharmaceutical partnerships beyond traditional nutraceutical channels, commanding premium positioning.
- India:Underpenetrated Ayurvedic extract standardization presents white space for FSSAI-compliant suppliers establishing domestic manufacturing presence.
- US FDA NDI Notification:First-mover substantiation investments create defensive moats against late entrants lacking clinical trial capabilities for novel botanical actives.
Industry Challenges
- Analytical Chemist Shortage:Specialized phytochemical quantification and marker compound identification skills command scarcity premiums, constraining quality control scaling.
- Chromatographic Purification Capex:Preparative HPLC and simulated moving bed systems require seven-figure capital commitments for pharmaceutical-grade purity specifications.
- Pharmacovigilance Integration:Evolving adverse event reporting frameworks demand cross-functional coordination between regulatory, quality, and medical affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytochemicals Market |
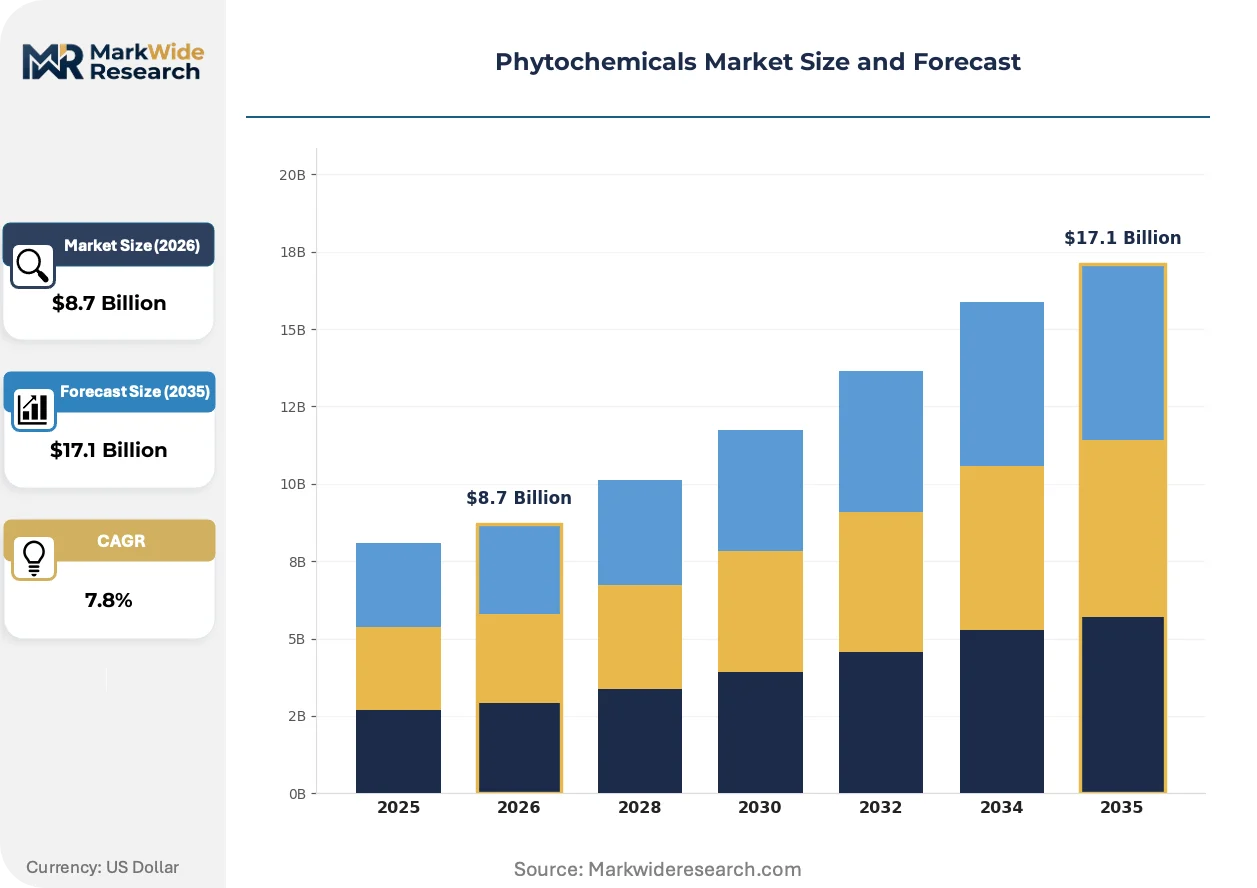
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavonoids, Alkaloids, Terpenes, Polyphenols Application: Nutraceuticals, Personal Care, Food & Beverages, Pharmaceuticals Source: Fruits, Vegetables, Herbs, Spices End User: Manufacturers, Distributors, Retailers, Researchers |
| Companies Covered | Naturex, Euromed, Indena SPA, Martin Bauer, BGG, Natural Remedies, Active Ingredients Group, Aovca, Tsumura and Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytochemicals Market Strategic Shifts
Digital traceability platforms and advanced extraction technologies are compressing traditional quality assurance timelines while regulatory substantiation requirements deepen competitive differentiation.
Supercritical fluid extraction coupled with in-line spectroscopic monitoring is virtualizing batch release decisions, eliminating traditional wet chemistry hold times. Pharmaceutical manufacturers in Switzerland and Germany are adopting these integrated systems for real-time potency verification. The technology is virtualizing quality control workflows from weeks to hours, compressing working capital cycles and enabling just-in-time botanical sourcing.
EFSA's evolving health claims assessment framework now requires systematic review-level evidence for polyphenol cardiovascular benefits, raising substantiation thresholds. This regulatory tightening favors extract houses with dedicated clinical trial infrastructure over commodity suppliers. German and French formulators are responding by consolidating supplier panels toward EFSA-preferred dossier holders with established safety databases.
Certification-driven procurement now dominates contract negotiations, with buyers demanding organic, non-GMO, and carbon footprint documentation alongside standard potency certificates. Direct sourcing from Mediterranean growing cooperatives is displacing traditional distributor intermediaries in premium segments. This pattern concentrates in German botanical extract procurement, where sustainability scoring influences supplier selection beyond price-performance metrics.
Phytochemicals Market Segmentation
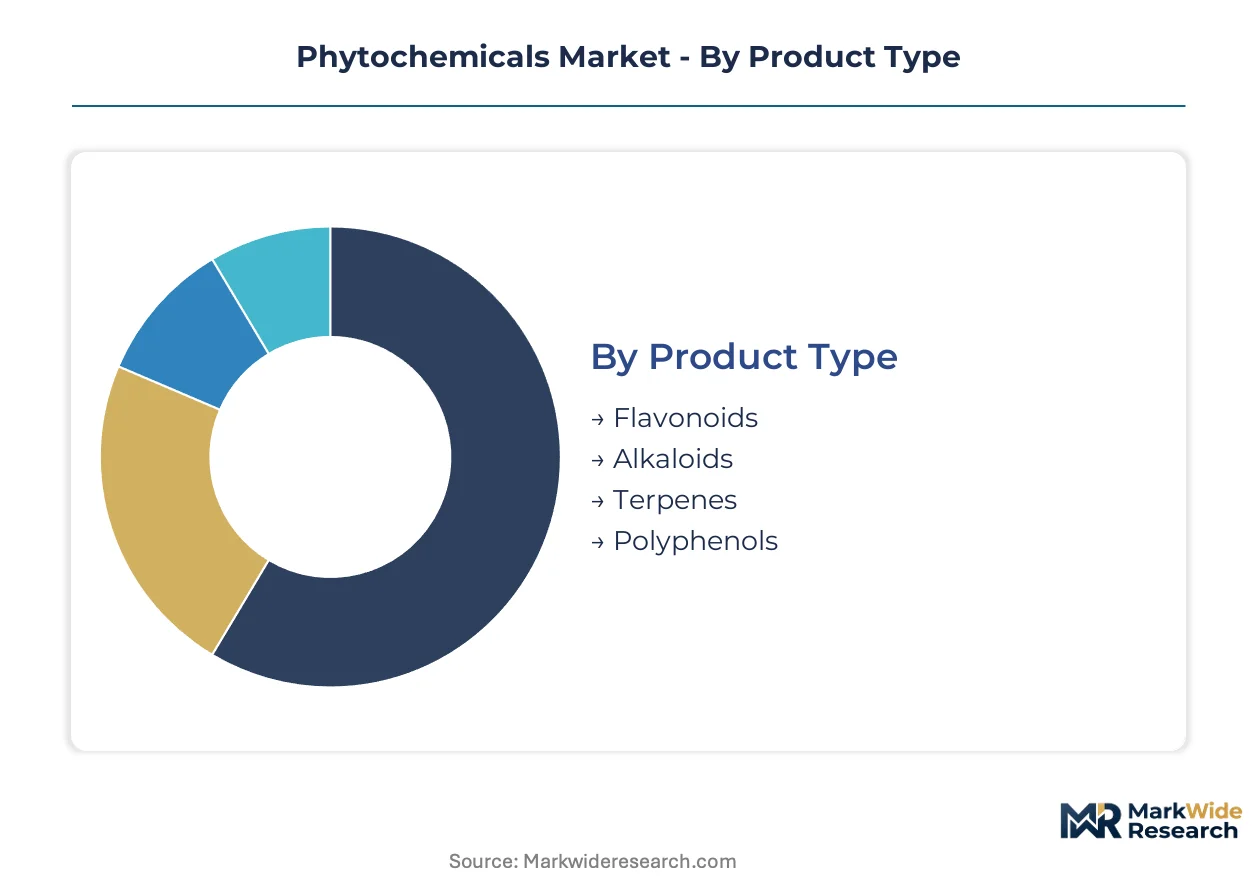
Phytochemical segmentation determines extraction technology selection, regulatory pathway complexity, and margin architecture for suppliers. Distinct purity specifications across product categories create tiered pricing structures that separate pharmaceutical-grade from nutraceutical-grade procurement channels.
Product Type:
Use-case spectrum spans antioxidant fortification through targeted therapeutic delivery, with each compound class demanding specialized stabilization and bioavailability enhancement.
- Flavonoids:These polyphenolic compounds including quercetin and catechin demonstrate established cardiovascular and metabolic health applications. German nutraceutical formulators in Hamburg and Frankfurt corridors concentrate procurement of standardized flavonoid extracts for EFSA-compliant functional food positioning.
- Polyphenols:Broad-spectrum antioxidant compounds encompassing resveratrol and ellagic acid require chromatographic purification for pharmaceutical-grade specifications. Demand clusters in Swiss and German pharmaceutical manufacturing where supercritical CO2 extraction preserves thermolabile activity profiles for anti-inflammatory formulations.
- Terpenes:Aromatic hydrocarbons including limonene and pinene extracted for aroma-therapeutic and cannabis-adjacent applications.
- Alkaloids:Nitrogen-containing compounds such as caffeine and berberine facing synthetic biology substitution pressure in mature pharmaceutical segments.
The dominant share belongs to Flavonoids, while Terpenes is closing the gap fastest.
Application:
Customer procurement patterns separate commodity-grade from certified-grade purchasing, with regulatory substantiation requirements filtering supplier access by segment.
- Nutraceuticals:Dietary supplement and functional food formulations requiring standardized potency certificates and full traceability documentation. Consolidated formulators in Germany demand backward integration proof from Mediterranean botanical suppliers for contract eligibility.
- Pharmaceuticals:Clinical-grade applications mandating pharmacopoeial compliance and adverse event reporting infrastructure. Indena SPA and Euromed compete through patented phytosome delivery systems and supercritical extraction capabilities for partnership access with Swiss and German drug manufacturers.
- Personal Care:Topical antioxidant and anti-aging formulations with organic certification premiums driving Mediterranean cooperative sourcing.
- Food & Beverages:Natural preservative and colorant applications subject to FDA GRAS and EFSA food additive assessments.
Nutraceuticals commands the largest procurement volume, though Pharmaceuticals generates the steepest margin expansion.
Source:
Raw material geography dictates harvest timing, climate risk exposure, and extraction yield consistency for processor operations.
- Herbs:Medicinal botanicals including St. John's wort and echinacea cultivated in Mediterranean and Eastern European growing regions for standardized marker compound content.
- Fruits:Berry-derived anthocyanins and citrus bioflavonoids processed through solvent extraction for nutraceutical applications.
- Vegetables:Cruciferous-derived glucosinolates and carotenoids requiring post-harvest stabilization to preserve bioactive integrity.
- Spices:Turmeric curcuminoids and gingerols commanding organic certification premiums in German and French procurement panels.
Herbs anchors supply concentration, while Fruits demonstrates the most rapid demand acceleration.
End User:
Supply chain position determines technical specification depth, with downstream proximity correlating to traceability documentation requirements.
- Manufacturers:Formulators and finished product producers requiring batch-specific certificates of analysis and stability data packages for regulatory dossier compilation.
- Distributors:Specialized ingredient intermediaries consolidating procurement from multiple extract houses for nutraceutical customer portfolios.
- Retailers:Direct-to-consumer channels and private label operators with sustainability scoring influencing supplier selection.
- Researchers:Academic and clinical trial investigators sourcing reference-grade materials for mechanism-of-action and bioavailability studies.
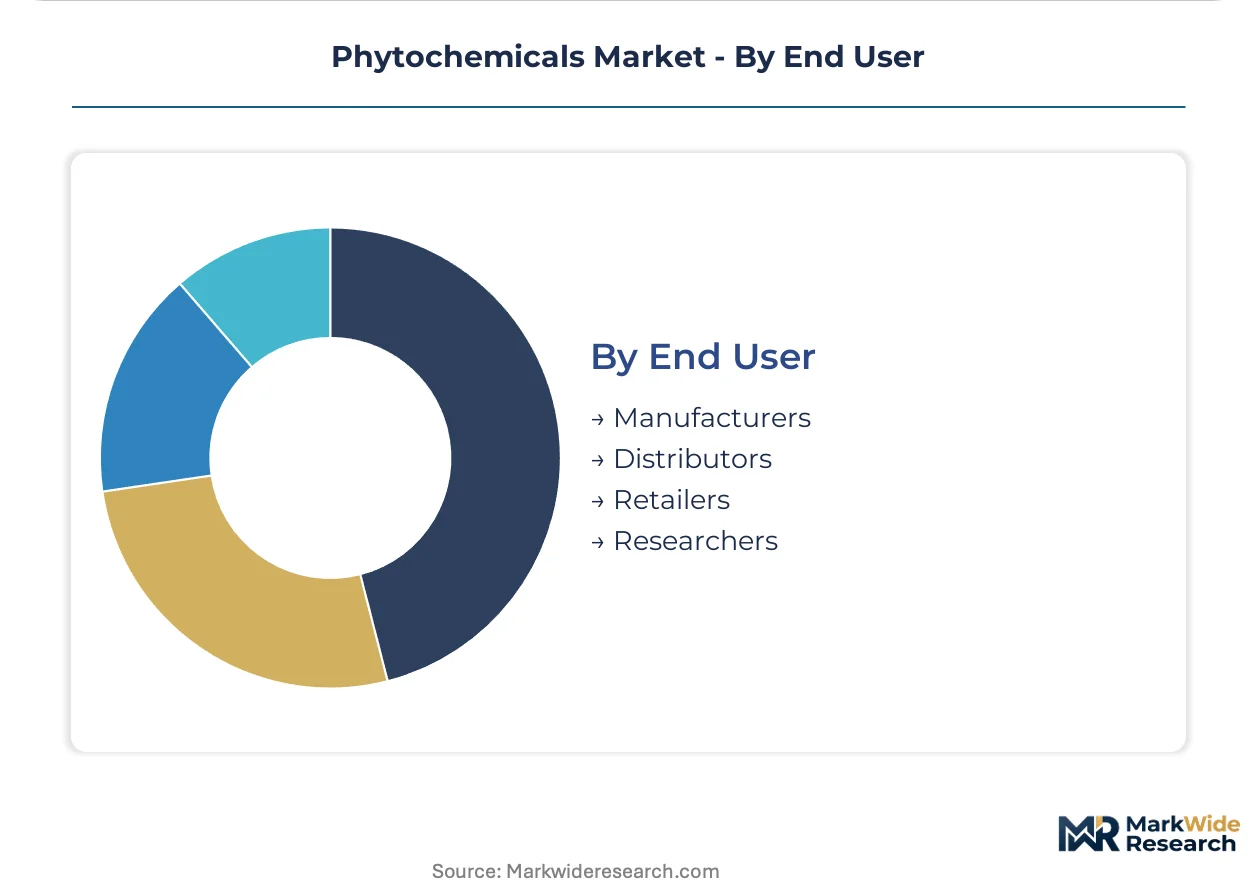
Manufacturers represents the dominant procurement node, with Researchers expanding fastest as clinical substantiation investments deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's health claims assessment framework anchors European demand concentration, while FDA's New Dietary Ingredient notification pathway shapes North American procurement patterns. German botanical extract houses cluster around Hamburg and Frankfurt supply corridors, establishing continental distribution dominance. India and China represent underpenetrated standardization opportunities where domestic regulatory compliance creates defensive positioning for early entrants.
Germany
Nutraceutical formulators in Hamburg and Frankfurt corridors drive standardized extract procurement for EFSA-compliant functional food positioning. REACH compliance for botanical imports imposes toxicological documentation requirements that filter market access to well-capitalized players with dedicated regulatory affairs functions. Martin Bauer and Euromed sustain operations through advanced extraction capabilities serving Swiss and German pharmaceutical manufacturers.
United States
FDA's NDI notification pathway creates defensive moats for first-movers with clinical trial capabilities for novel botanical actives. Consolidated supplement manufacturers demand certified supply chains with full traceability documentation from Mediterranean botanical suppliers. Naturex leverages backward integration into Mediterranean sourcing to secure raw material consistency for US formulation partnerships.
Switzerland
Swissmedic pharmaceutical-grade specifications drive demand for patented phytosome delivery technologies and supercritical CO2 extraction capabilities. Indena SPA competes through enhanced bioavailability systems for partnership access with Basel and Zurich drug manufacturers. Geneva-based formulators concentrate procurement of chromatographically purified polyphenols for anti-inflammatory therapeutic applications.
India
FSSAI-compliant Ayurvedic extract standardization presents white space for suppliers establishing domestic manufacturing presence. Underpenetrated functional food and dietary supplement channels await validated polyphenol and flavonoid introductions with full traceability documentation. Natural Remedies and Active Ingredients Group occupy positions within the domestic botanical processing infrastructure.
China
SAMR botanical import standards and domestic pharmacopoeial compliance requirements reshape procurement patterns for standardized plant extracts. Yangtze River Delta formulation clusters demand certified supply chains with carbon footprint and organic certification documentation. BGG and Aovca represent Chinese-originated suppliers navigating domestic regulatory substantiation requirements.
Phytochemicals Market Competitive Environment
Backward-integrated botanical specialists and technology-differentiated extract houses split the market between supply security and formulation innovation. Supplier margins compress as consolidated nutraceutical formulators demand certified supply chains with full traceability documentation. Three archetypes dominate: Mediterranean-sourced backward integrators, supercritical extraction technology leaders, and pharmaceutical-grade delivery system patent holders. Competitive moves concentrate on geographic sourcing expansion and regulatory dossier accumulation.
Within the technology-differentiated tier, Euromed and Indena SPA exemplify extraction and delivery system specialization. Naturex anchors the backward-integrated archetype through Mediterranean botanical sourcing control. Tsumura and Co represents Japanese-originated traditional medicine standardization expertise. These three companies occupy distinct competitive positions without overlapping strategic territory, permitting sustained margin architecture across the value pool.
| Leading Market Players |
|---|
| Naturex |
| Euromed |
| Indena SPA |
| Martin Bauer |
| BGG |
| Natural Remedies |
| Active Ingredients Group |
| Aovca |
| Tsumura and Co |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Mediterranean botanical processing during the 2023-2024 harvest cycle compressed utilization rates below 65%, forcing extract houses to absorb fixed costs while competing for limited formulation contracts from consolidated German nutraceutical buyers. This utilization squeeze simultaneously eroded spot-market pricing and accelerated backward integration investments as suppliers sought captive demand to stabilize throughput.
Pricing Analysis
Geographic price spreads between Hamburg corridor procurement and spot Mediterranean sourcing have widened to reflect certification premiums rather than raw material differentials alone. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and commodity-grade extracts separates suppliers by EFSA dossier depth and REACH compliance infrastructure. Cost compression in standard-grade flavonoid extracts is intensifying because synthetic biology competitors are achieving purity parity at lower unit economics. Commodity traders exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers accept substantial premiums for pharmacopoeial-compliant chromatographic purification.
Supply Chain Analysis
Extended payment terms now stretch 90-120 days for Mediterranean cooperative suppliers, with supply-chain finance facilities emerging as a competitive tool for extract houses seeking raw material security. Botanical sourcing concentrates in Italy, Spain, and Morocco for Mediterranean polyphenol crops, with Indian Ayurvedic herbs gaining share in specialty alkaloid segments. Raw material dependencies rest on climate-vulnerable harvests of St. John's wort, turmeric rhizomes, and citrus bioflavonoid feedstocks. Single-source vulnerability runs through Hamburg-Frankfurt logistics corridors where customs delays cascade through just-in-time formulation schedules. Distribution runs through specialized ingredient distributors consolidating multi-origin portfolios for nutraceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phytochemicals market operates as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. EFSA health claims dossiers and FDA NDI notifications impose substantiation burdens that filter market access to well-capitalized incumbents with clinical trial infrastructure.
For Market Incumbents: Build regulatory dossier moats by deepening EFSA cardiovascular health claim submissions for standardized polyphenol extracts. Secure backward integration into carbon-certified Mediterranean growing cooperatives to defend margin position against climate-driven raw material volatility. Synthetic biology substitution in alkaloid segments demands accelerated phytosome delivery system patenting to preserve pharmaceutical partnership access.
For New Entrants and Emerging Players: Build out FSSAI-compliant Ayurvedic extract standardization capabilities in India, where domestic manufacturing presence creates defensive positioning before multinational incumbents establish local facilities. Target underpenetrated functional food channels with validated flavonoid introductions carrying full organic traceability documentation. Partner with German distributor networks seeking secondary sourcing alternatives to consolidated supplier panels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure as pharmaceutical-grade purity specifications demand seven-figure preparative HPLC commitments. Long-term viability favors technology-differentiated extract houses with patented delivery systems over commodity-standardized suppliers facing margin compression. Monitor synthetic biology cost curves as the critical inflection signal determining whether natural extraction investments retain competitive returns. Regulatory dossier accumulation velocity separates acquisition targets with defendable market position from commodity-exposed operators.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claims Dossier Investment | Validated polyphenol extracts gain preferred positioning in German functional food formulations. |
| Supercritical CO2 Capacity Expansion | Advanced solvent-free methods preserve thermolabile terpene profiles for Swiss pharmaceutical partnerships. |
| Mediterranean Cooperative Backward Integration | Direct sourcing from Italian and Spanish growing regions secures climate-resilient raw material consistency. |
| Phytosome Delivery System Patenting | Enhanced bioavailability technologies command premium positioning in Basel and Zurich drug manufacturing channels. |
| FSSAI-Compliant India Manufacturing Buildout | Domestic Ayurvedic extract standardization captures white space before multinational incumbent entry. |
Study Parameters
Desk research of EFSA health claims registers, FDA NDI notification databases, and REACH compliance filings preceded structured interviews with extraction technology directors, regulatory affairs managers at botanical suppliers, procurement leads at German nutraceutical formulators, and quality control heads at Swiss pharmaceutical manufacturers. Secondary validation drew from customs trade data, pharmacopoeial monograph revisions, and SEC filings of publicly traded ingredient suppliers. Bottom-up segment sizing triangulated against top-down market value estimates from trade association publications.
Assumptions held fixed include EFSA's systematic review-level evidence requirements for polyphenol cardiovascular claims and FDA's current NDI notification pathway structure, while synthetic biology cost curves and climate volatility patterns were varied across sensitivity scenarios. Segmentation modeling spanned compound class, application grade, extraction technology, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical procurement volume trajectories and projected formulation demand from pharmaceutical and nutraceutical end-use channels.
Practitioners should monitor regulatory revision triggers including EFSA health claims framework updates and FDA NDI guidance modifications for early signals of substantiation burden shifts. Forecasts reflect these documented assumptions; synthetic biology purity breakthroughs, REACH scope expansions, or Mediterranean climate disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Lemon Balm Extract Market
Extracts
Nootkatone Market
Extracts
Global Marigold Flower Extract Market
Extracts
Agmatine Market
Extracts
Global Aphrodisiac Powder Market
Extracts
Valerian Root Powder Market
Extracts
Fig Glycolic Extract Market
Extracts
Tagetes Oil Market
Extracts
Belladonna Market
Extracts
Global Pine-Derived Chemicals Market
Extracts
Patchouli Oil Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Cassia Extract Market
Extracts
Irish Moss Extract Market
Extracts
Nicotinic Acid Market