
 Asia-Pacific Tourism Market | 2026-2036
Asia-Pacific Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tourism Market Outlook
Aftermarket service revenue from loyalty programs and destination experience packaging is tilting toward higher-margin curated offerings. TUI AG leverages its integrated tour operating platform to control end-to-end itinerary design across Southeast Asian routes. China Duty Free Group anchors its position through captive retail footprints at Hainan and major Chinese gateway airports. Abercrombie & Kent specializes in ultra-luxury expedition programming that commands premium pricing per passenger.
Asia-Pacific tourism encompasses cross-border travel services, accommodation provisioning, destination activities, and transportation coordination across diverse cultural and ecological zones, typically operating through seasonal yield-management algorithms and dynamic capacity allocation to optimize occupancy rates and route density. The sector's primary commercial purpose is to monetize geographic and cultural distinctiveness through staged visitor experiences that generate foreign exchange and local employment. Adventure tours and eco-tourism represent the fastest-expanding service categories as younger demographics prioritize activity-based immersion over passive sightseeing. Wellness retreats command superior margin pools due to extended length-of-stay patterns and ancillary spa and nutrition service attach rates. Leisure travelers constitute the dominant customer type by volume, though business traveler recovery in Singapore and Seoul corporate corridors is reshaping midweek accommodation demand patterns.
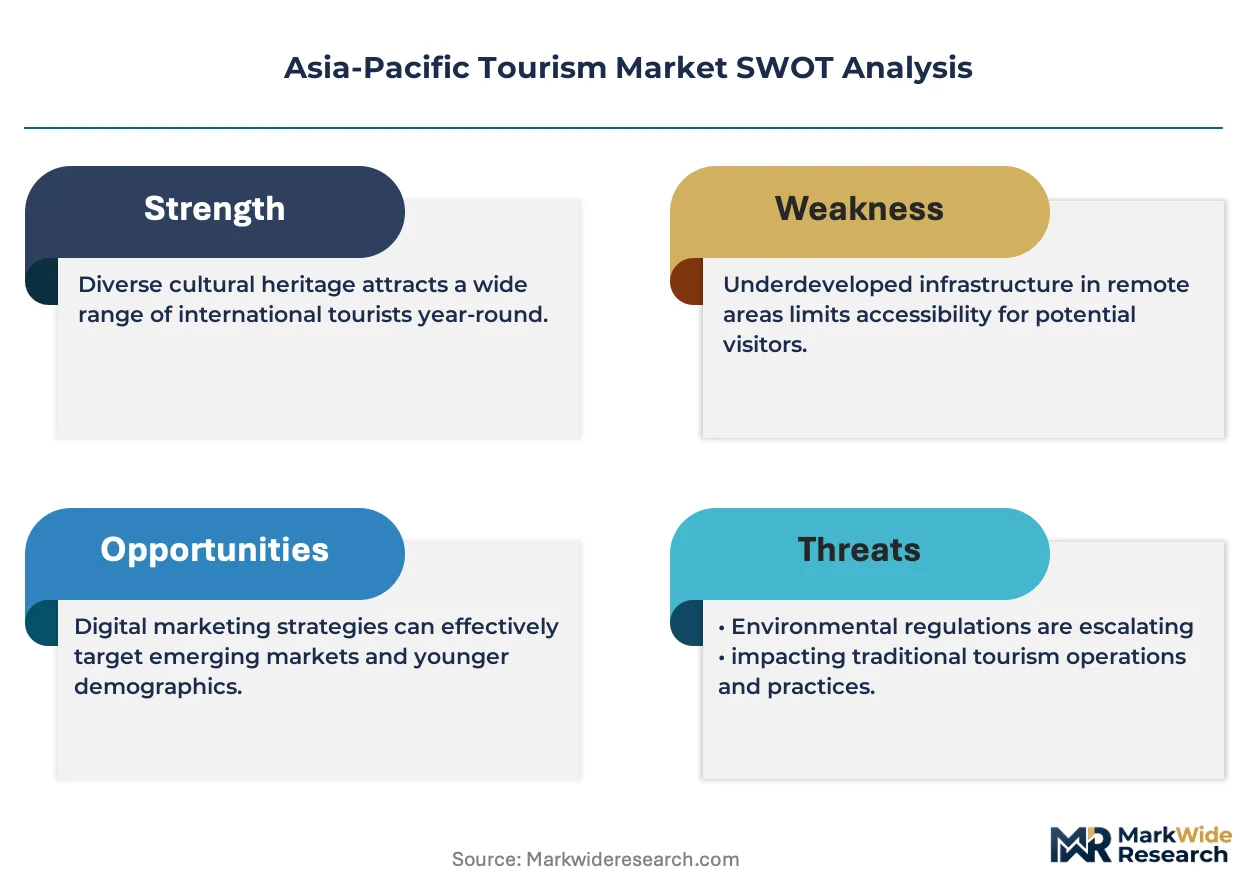
Thailand's Ministry of Tourism and Sports enforces environmental carrying-capacity limits at marine national parks, directly constraining daily visitor volumes at Phi Phi Islands and Similan archipelago sites. Japan's Tourism Agency coordinates with METI on inbound visitor infrastructure standards, while Australia's Great Barrier Reef Marine Park Authority imposes operator licensing conditions that filter market access for reef-activity providers. Stakeholders must monitor how cumulative regulatory load from carbon-offset mandates, visitor caps, and cultural heritage protection protocols reshapes operational cost structures and permissible expansion zones across the region.
Market Dynamics
Japan's digital nomad visa liberalization and Thailand's marine park carrying-capacity enforcement are compressing visitor distribution patterns while rerouting demand toward secondary corridors. These dual regulatory currents are forcing operators to rebuild yield algorithms around constrained access zones and extended-stay visa cohorts.
Growth Catalysts
- Visa Regime Modernization:Japan's Tourism Agency digital nomad scheme and Indonesia's second-home visa program are unlocking month-long stays that multiply per-visitor spend across accommodation and experience layers.
- Wellness Infrastructure:Thailand's Ministry of Public Health certification protocols for traditional medicine retreats are standardizing service quality that commands premium pricing from European and North American source markets.
- Aviation Connectivity:Vietnam's coastal resort corridor benefits from new direct routes into Da Nang and Phu Quoc that bypass legacy gateway congestion in Bangkok and Singapore.
Market Restraints
- Environmental Carrying-Capacity Mandates:Thailand's Ministry of Tourism and Sports daily visitor caps at Phi Phi Islands and Similan archipelago sites permanently constrain peak-season inventory.
- Reef-Activity Licensing:Australia's Great Barrier Reef Marine Park Authority operator certification requirements filter market access and extend compliance timelines for new entrants.
- Labor Input Volatility:Seasonal hospitality worker availability across Indonesia's resort islands fluctuates with agricultural harvest cycles, compressing service consistency during high-demand windows.
Strategic Opportunities
- Underpenetrated Secondary Corridors:Vietnam's emerging central coast destination cluster between Hoi An and Quy Nhon offers undeveloped beachfront inventory with lower land-cost bases than established Thai or Balinese equivalents.
- Regulatory Tailwind:Australia's Nature Repair Market framework creates verified biodiversity credit mechanisms that eco-tourism operators can monetize alongside guest experiences.
- Channel Innovation:Direct-to-consumer booking platforms are displacing traditional wholesale tour operator intermediaries, capturing margin previously allocated to third-party distribution.
Industry Challenges
- Specialized Talent Scarcity:Marine biology interpretation and wilderness guiding credentials required by Australia's Great Barrier Reef Marine Park Authority licensing exceed regional training pipeline output.
- Legacy Reservation System Integration:Small-to-midscale accommodation providers across Indonesia's archipelago struggle to connect property management systems with global distribution networks.
- Carbon Accounting Compliance:Emerging offset disclosure mandates in multiple source markets demand data infrastructure that fragmented supplier bases lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tourism Market |
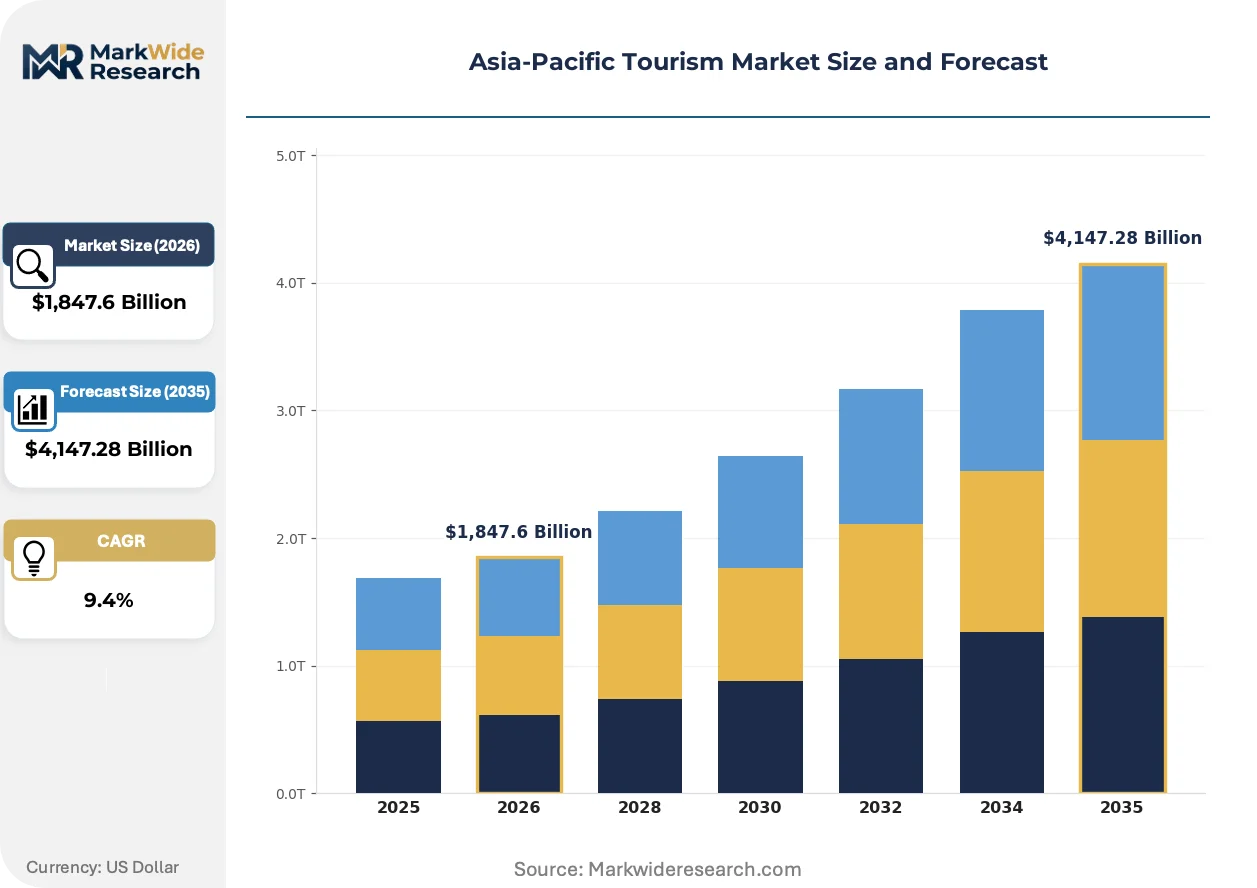
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $4,147.28 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Adventure Tours, Cultural Tours, Eco-Tourism, Wellness Retreats Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Solo Travelers Transportation Mode: Air Travel, Train Travel, Cruise Ships, Car Rentals Accommodation Type: Hotels, Resorts, Hostels, Vacation Rentals |
| Companies Covered | DFS Group, TUI AG, China Duty Free Group, Hilton Hotels of Malaysia, Abercrombie & Kent, Dufry AG, Shilla Duty Free, Conrad Singapore Orchard, Lotte Duty Free, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tourism Market Strategic Shifts
Immersive digital technologies are compressing the pre-booking research phase while regulatory carbon-accounting requirements are reshaping operator reporting obligations. These forces are converging to redefine how experiences are marketed, verified, and consumed across the region.
Extended reality platforms are virtualizing destination preview experiences before physical travel commitment. Younger leisure demographics in South Korea and Japan now expect three-dimensional property walkthroughs and activity simulations as standard pre-purchase due diligence. This technology is virtualizing traditional brochure-and-review research patterns, compressing booking lead times and elevating visual fidelity expectations.
Thailand's Ministry of Tourism and Sports coordinates with the Department of National Parks on mandatory environmental impact assessments for new concession approvals. These protocols extend development timelines but filter out speculative operators lacking capital for compliance infrastructure. Coastal resort projects in Phuket and Krabi face the most stringent scrutiny, driving investment toward renovation of existing inventory rather than greenfield expansion.
Aftermarket service unbundling is fragmenting the packaged tour model across Australian experiential nature circuits. Independent travelers now assemble component bookings directly with local guides, transport providers, and accommodation operators, bypassing traditional tour operator margins. This pattern concentrates in Tasmania and Queensland's reef-adjacent communities where digital connectivity enables direct supplier discovery.
Asia-Pacific Tourism Market Segmentation
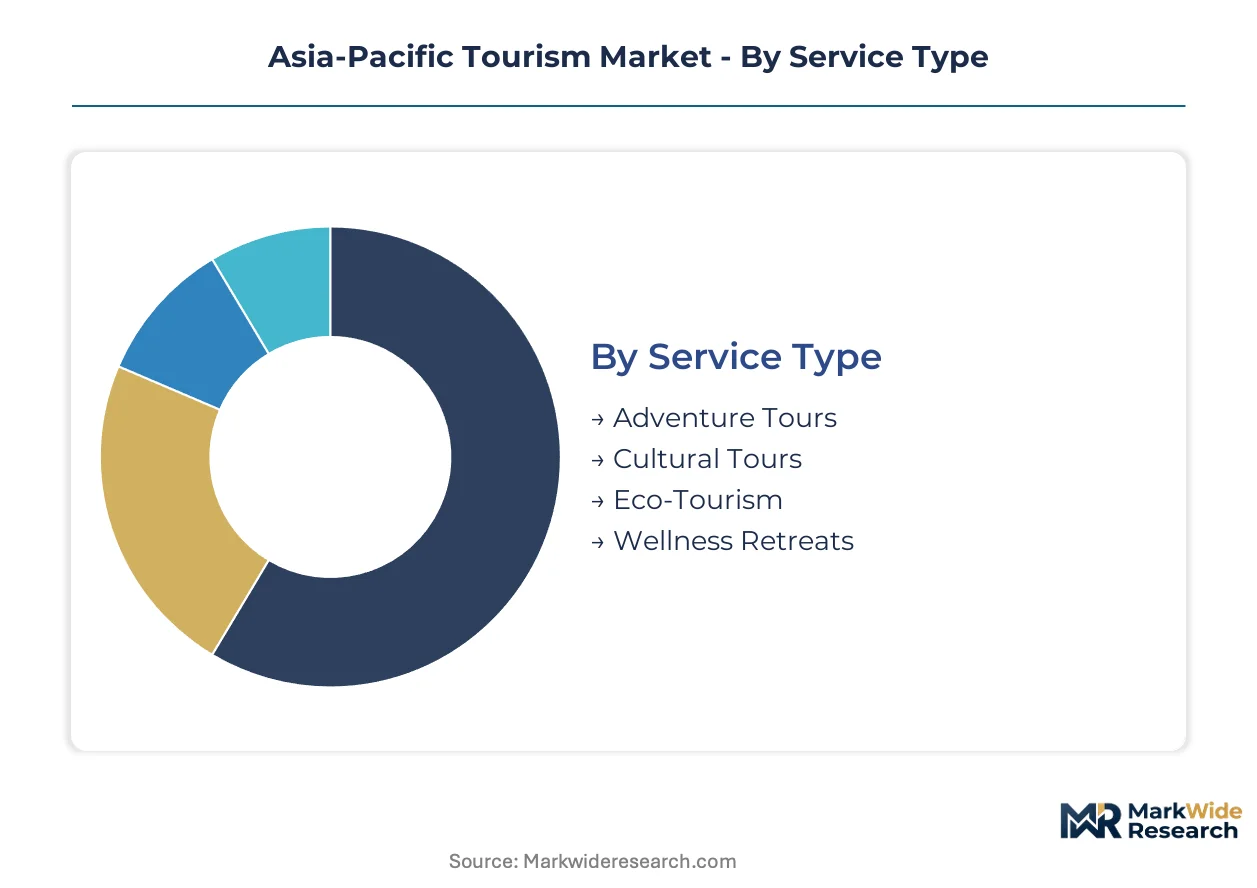
Segmentation in Asia-Pacific tourism reveals distinct demand clusters shaped by visa duration, environmental carrying-capacity limits, and digital booking infrastructure. Operators configure yield algorithms and inventory allocation differently across each slice, with wellness and eco-tourism commanding premium positioning.
Service Type:
Demand concentrates in experience formats that extend length-of-stay and justify higher per-day spend across Thailand's certified traditional medicine corridors and Australia's reef-adjacent circuits.
- Adventure Tours:Activity-based itineraries span trekking, diving, and wildlife encounters across Indonesia's Komodo National Park and New Zealand's Southern Alps. Vietnam's emerging central coast cluster between Hoi An and Quy Nhon is capturing diverted demand from capacity-constrained Thai marine parks.
- Wellness Retreats:Extended-stay programming integrates spa services, nutrition consulting, and traditional medicine certification under Thailand's Ministry of Public Health protocols. European and North American source markets pay premium rates for standardized service quality in Phuket and Bali.
- Eco-Tourism:Australia's Nature Repair Market framework enables biodiversity credit monetization alongside guest experiences. Operators in Queensland and Tasmania bundle reef interpretation with verified conservation outcomes.
- Cultural Tours:Heritage-focused itineraries leverage Japan's inbound tourism infrastructure and Vietnam's UNESCO corridor density. Group sizing adapts to Japan's Tourism Agency visitor management protocols at sensitive sites.
The dominant share belongs to Wellness Retreats, while Eco-Tourism is closing the gap fastest through Australia's regulatory credit mechanisms and carbon-conscious traveler preferences.
Customer Type:
Booking patterns diverge sharply between extended-stay visa cohorts and traditional short-haul segments, reshaping midweek occupancy algorithms.
- Leisure Travelers:Volume-dominant segment assembling component bookings directly with local suppliers across Australian nature circuits, bypassing traditional tour operator margins. Tasmania and Queensland reef communities show highest unbundling penetration.
- Business Travelers:Midweek demand concentration in Singapore and Seoul corporate corridors is recovering post-pandemic, compressing yield management windows for properties with mixed-use positioning.
- Solo Travelers:Digital nomad visa schemes in Japan and Indonesia's second-home program unlock month-long stays with multiplied per-visitor spend across accommodation layers.
- Group Travelers:Packaged tour demand persists in China's outbound corridor and India's emerging middle-class segment, though direct-to-consumer platforms erode wholesale intermediary share.
Leisure Travelers anchor volume, yet Solo Travelers are expanding most quickly through visa liberalization and remote-work normalization.
Transportation Mode:
Connectivity investments are rerouting flows around legacy gateway congestion toward secondary destination clusters.
- Air Travel:Direct route expansion into Da Nang and Phu Quoc bypasses Bangkok and Singapore hub dependency. Vietnam's coastal resort corridor benefits most from this aviation infrastructure shift.
- Cruise Ships:Reef-activity licensing from Australia's Great Barrier Reef Marine Park Authority constrains operator certification and extends compliance timelines for new entrants in this segment.
- Train Travel:Japan's shinkansen network and Vietnam's north-south reunification line serve domestic and regional corridor demand with lower carbon intensity than short-haul aviation.
- Car Rentals:Independent mobility supports Australia's experiential nature tourism circuits where digital connectivity enables direct supplier discovery outside packaged tour structures.
Air Travel retains the largest share, though Train Travel is gaining ground fastest on sustainability positioning and regional connectivity improvements.
Accommodation Type:
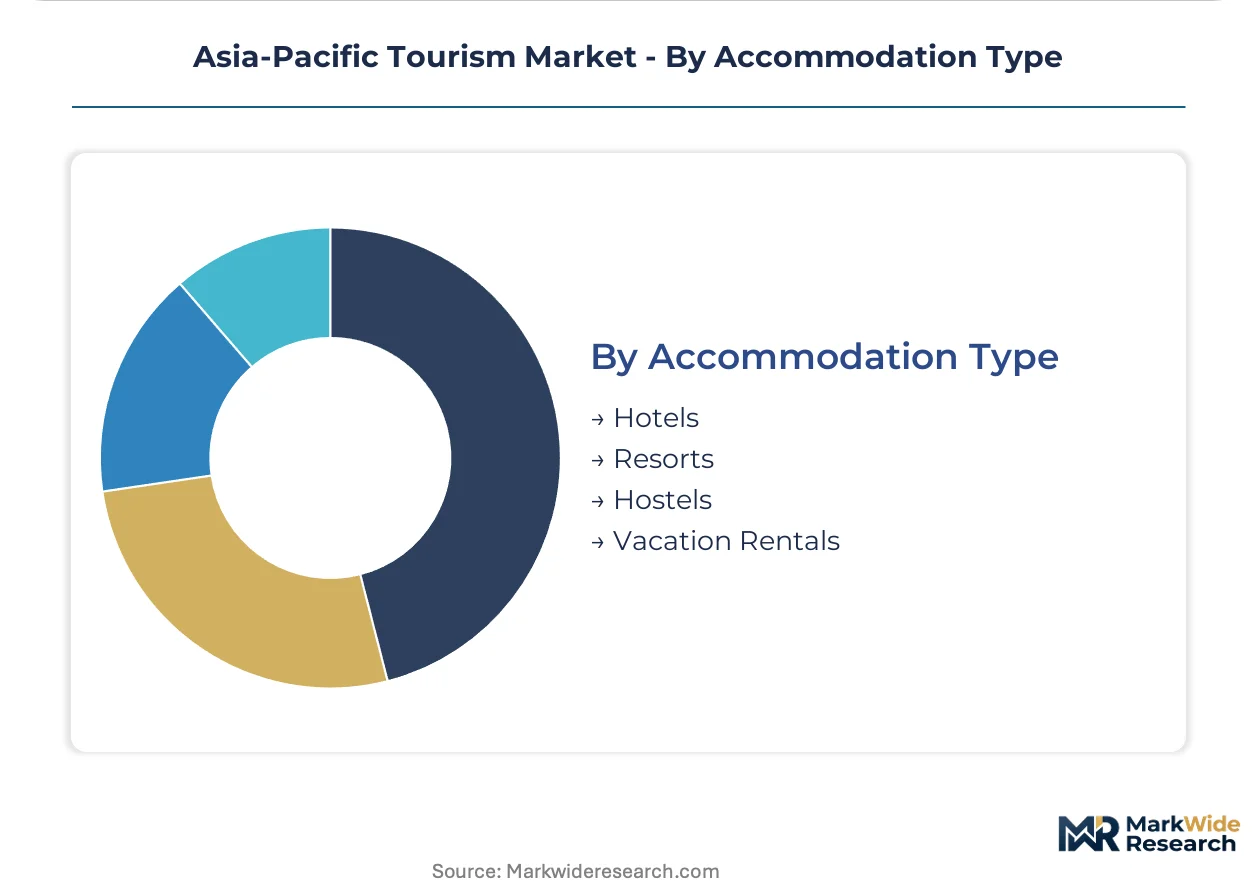
Inventory constraints from environmental carrying-capacity mandates favor renovation over greenfield development across Thailand's most scrutinized coastal zones.
- Resorts:Wellness and eco-tourism positioning commands superior margin pools through extended length-of-stay and ancillary service attach rates. Thailand's Ministry of Tourism and Sports environmental impact assessments filter speculative greenfield projects in Phuket and Krabi.
- Vacation Rentals:Direct-to-consumer platforms displace traditional distribution, capturing margin previously allocated to third-party intermediaries. Indonesia's archipelago properties struggle with legacy reservation system integration.
- Hotels:Mixed-use properties in Singapore and Seoul balance corporate midweek demand with leisure weekend compression, requiring dynamic yield algorithms.
- Hostels:Budget positioning serves younger demographics in South Korea and Japan where immersive digital preview technologies compress booking lead times.
Resorts hold the dominant position, while Vacation Rentals are climbing the fastest through platform disintermediation and extended-stay visa cohort preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across the region: Vietnam's coastal resorts attract cost-conscious European leisure travelers while Japan's certified wellness corridors command premium rates from North American visitors with minimal price sensitivity.
Japan
Digital nomad visa cohorts from Europe and North America multiply per-visitor spend through month-long accommodation bookings. METI coordinates with the Tourism Agency on inbound infrastructure standards that streamline extended-stay visitor processing. Tokyo and Osaka anchor corporate corridor recovery, while Kyoto's cultural heritage sites adapt to visitor management protocols.
Thailand
Wellness retreat demand from European source markets concentrates in Phuket and Bali-certified traditional medicine corridors. The Ministry of Tourism and Sports enforces environmental carrying-capacity limits at Phi Phi Islands and Similan archipelago sites. Krabi faces stringent coastal resort scrutiny, diverting investment toward renovation of existing inventory.
Vietnam
Direct aviation routes into Da Nang and Phu Quoc bypass legacy gateway congestion in Bangkok and Singapore. The coastal resort corridor between Hoi An and Quy Nhon captures diverted demand from capacity-constrained Thai marine parks with lower land-cost bases.
Australia
Experiential nature tourism circuits in Queensland and Tasmania show highest unbundling penetration as independent travelers assemble component bookings directly. The Great Barrier Reef Marine Park Authority imposes operator licensing conditions that filter market access. The Nature Repair Market framework enables biodiversity credit monetization alongside guest experiences.
Indonesia
Second-home visa programs unlock extended stays from remote-work professionals across Bali and Lombok resort islands. The Ministry of Public Health certification protocols standardize wellness service quality. Seasonal hospitality worker availability fluctuates with agricultural harvest cycles, compressing service consistency during high-demand windows.
Asia-Pacific Tourism Market Competitive Environment
Capability concentration sits with integrated tour operators controlling end-to-end itinerary design; scale advantage sits with duty-free retail networks anchored at gateway airports. The market structures around three tiers: vertically integrated hospitality conglomerates, specialized expedition programmers, and airport-captive retail operators. Competitive moves center on direct-to-consumer platform development and regulatory credit mechanism participation.
Among integrated tour operators, TUI AG represents the vertically integrated archetype spanning Southeast Asian route control, while Abercrombie & Kent exemplifies ultra-luxury expedition programming commanding premium per-passenger pricing. Within duty-free retail, China Duty Free Group anchors the airport-captive tier through Hainan and major Chinese gateway footprints.
| Leading Market Players |
|---|
| DFS Group |
| TUI AG |
| China Duty Free Group |
| Hilton Hotels of Malaysia |
| Abercrombie & Kent |
| Dufry AG |
| Shilla Duty Free |
| Conrad Singapore Orchard |
| Lotte Duty Free |
| Others |
Value Chain & Pricing Dynamics
Environmental carrying-capacity enforcement at Thailand's marine national parks determines both margin compression at capacity-constrained sites and inventory allocation toward secondary corridors. This regulatory chokepoint forces operators to rebuild yield algorithms around permitted expansion zones while redirecting investment toward renovation rather than greenfield development.
Pricing Analysis
Aftermarket service revenue from loyalty programs and curated experience packaging drives lifetime value across integrated tour operating platforms. Three-tier pricing structure across premium, standard, and economy levels separates ultra-luxury expedition programming from mass-market packaged tours. Cost compression in midscale accommodation stems from direct-to-consumer platform disintermediation capturing margin previously allocated to wholesale intermediaries. European leisure travelers show highest price sensitivity, while North American wellness retreat demand exhibits minimal elasticity.
Supply Chain Analysis
Export-control restrictions on immersive digital preview technologies limit platform provider flows into Japanese and South Korean source markets. Supply concentrates in Thailand's certified traditional medicine corridors, Australia's reef-adjacent operator networks, and Vietnam's emerging central coast destination cluster. Raw material dependencies include seasonal hospitality labor pools, aviation seat inventory, and conservation-compliant marine activity permits. Single-source vulnerability sits with agricultural harvest cycles compressing Indonesian resort island staffing. Distribution runs through direct-to-consumer booking platforms displacing legacy wholesale tour operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual destination preview technologies threaten traditional brochure-and-review research patterns, forcing incumbents to defend physical experience value against digital substitution.
For Market Incumbents: Entrench position through captive control of end-to-end itinerary design across Southeast Asian routes. Deepen backward integration into wellness certification infrastructure under Thailand's Ministry of Public Health protocols. Defend against direct-to-consumer platform erosion by embedding loyalty program lock-in with extended-stay visa cohorts. For New Entrants and Emerging Players: Vietnam's central coast corridor between Hoi An and Quy Nhon offers undeveloped beachfront inventory with lower land-cost bases than established Thai equivalents. Target Australia's Nature Repair Market framework participation for biodiversity credit monetization alongside guest experiences. Pursue regulatory credit mechanism positioning as the primary go-to-market angle. For Investors and Strategic Acquirers: Japan's digital nomad visa liberalization reshapes the acquisition landscape toward extended-stay accommodation platforms. Long-term viability centers on operators controlling month-long visitor spend multiplication across accommodation and experience layers. Target integrated hospitality conglomerates with captive retail footprints at gateway airports. Watch for carbon-offset disclosure mandate enforcement as the inflection signal requiring data infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Development | Captures margin from wholesale tour operator intermediaries across Australian nature circuits. |
| Wellness Certification Investment | Commands premium pricing from European source markets through Thailand's Ministry of Public Health protocols. |
| Secondary Corridor Expansion | Accesses undeveloped inventory in Vietnam's central coast with lower land-cost bases than Thai equivalents. |
| Regulatory Credit Mechanism Participation | Monetizes biodiversity outcomes alongside guest experiences under Australia's Nature Repair Market framework. |
| Aviation Route Development | Bypasses legacy gateway congestion through direct routes into Da Nang and Phu Quoc. |
Study Parameters
Desk research of customs aviation data, national tourism board statistics, and reef-marine park licensing records preceded structured interviews with tour operating executives, resort yield management directors, conservation authority licensing officers, and digital platform product heads. Primary fieldwork with accommodation operators across Thailand's marine park zones and Australia's reef-adjacent communities validated secondary findings. Bottom-up inventory analysis triangulated against top-down aviation capacity and visa issuance data.
Assumptions held fixed include environmental carrying-capacity enforcement levels, visa regime durations, and aviation route network configurations across the projection horizon. The analytical framework modeled service type, customer type, transportation mode, and accommodation type dimensions alongside source market regulatory cluster patterns. CAGRs derived from yield-per-visitor spend trajectories and length-of-stay elasticity curves. Forecast inputs incorporated digital nomad visa uptake rates and carbon-offset disclosure mandate adoption timelines.
Macroeconomic conditions sit as an overlay; deviation in source market currency volatility, aviation fuel cost spikes, or regional labor migration patterns would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement continuity and visa policy stability. Material shifts in marine park visitor cap levels or digital nomad visa eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
Tourism Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
Global Home Exchange Service Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
South Korea Travel Retail Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
China Outbound Travel Market