
 Jalapeno Extract Market | 2026-2036
Jalapeno Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Jalapeno Extract Market Analytics
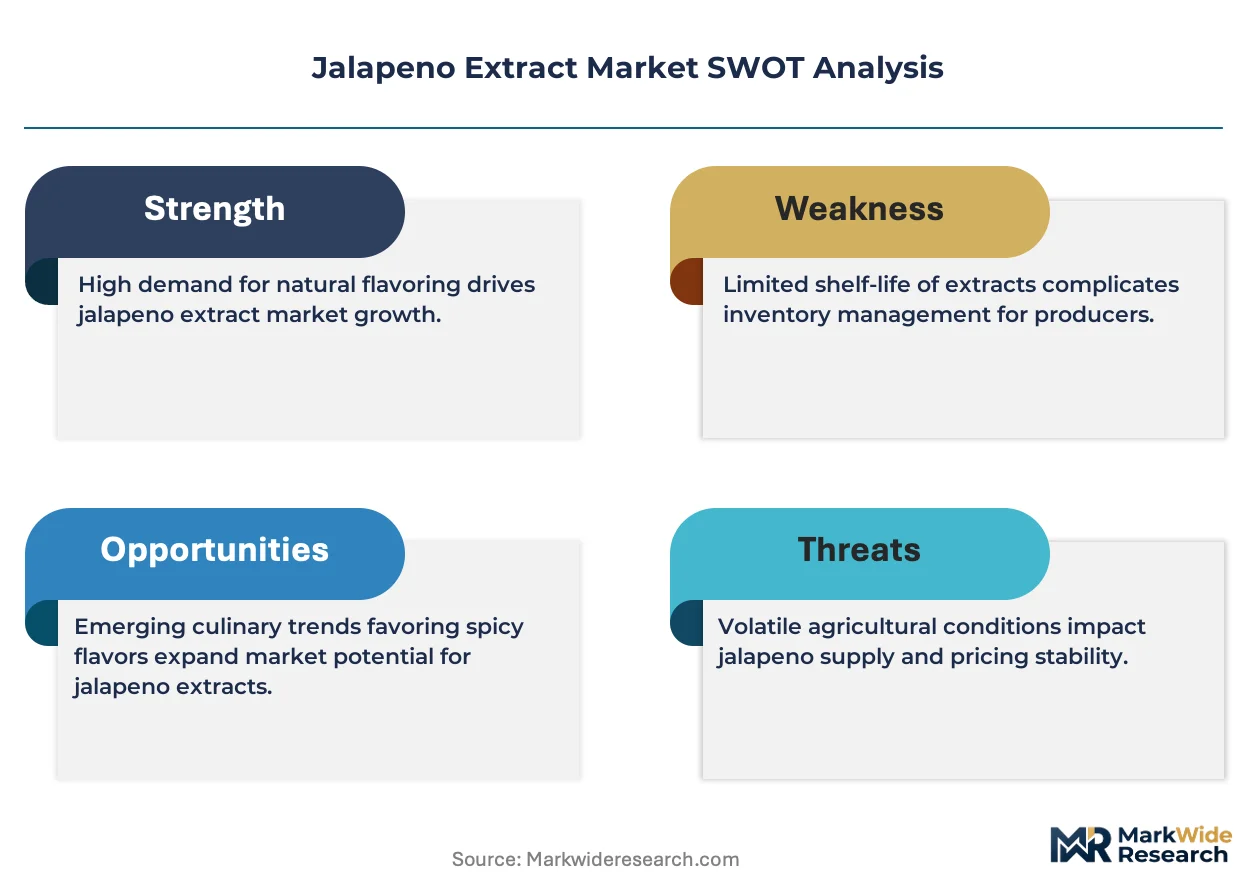
Organic certification under USDA NOP and EU 2018/848 is bifurcating the supplier base into qualified and excluded tiers. McCormick & Company leverages its backward integration into Mexican growing regions to sustain raw material traceability. Kalsec Inc. specializes in supercritical CO2 extraction technology for capsaicinoid standardization. Synthite Industries Ltd anchors its position through oleoresin concentration capabilities at its Kerala processing complex.
Jalapeno extract comprises capsaicinoids, primarily capsaicin and dihydrocapsaicin, extracted from Capsicum annuum fruit through solvent or supercritical fluid methods, yielding standardized heat units measured in Scoville Heat Units for industrial flavoring and pharmaceutical applications. Liquid extract dominates food manufacturing applications where pumpable dosing and batch consistency matter most, while oleoresin commands premium positioning in nutraceuticals for its concentrated capsaicinoid content and extended shelf stability. Powder extract competes on logistics efficiency for spice blending operations, though margin pools favor solvent-free extraction claims in the organic form segment.
FDA's Food Safety Modernization Act preventive controls and EPA pesticide tolerance limits for chili peppers govern import and processing standards, while USDA Organic and Non-GMO Project verification gate retail channel access in North American markets. EU REACH and EFSA novel food assessments shape European market entry timelines for new extract formats. Stakeholders must monitor capsaicinoid patent filings and climate volatility in Mexican source regions to secure supply continuity and extraction yield advantages.
Market Dynamics
Clean-label reformulation pressure from ready-meal and snack manufacturers is consolidating demand around standardized capsaicinoid extracts with full supply chain traceability.
Growth Catalysts
- FSMA enforcement:FDA's updated preventive controls on imported spices are disqualifying non-compliant suppliers, redirecting volume toward certified Mexican processors with validated HACCP systems.
- Supercritical CO2 extraction:This solvent-free technology enables precise capsaicinoid standardization that meets organic certification thresholds under USDA NOP and EU 2018/848.
- Chihuahua-Sinaloa cluster:Irrigation infrastructure investments and capsaicinoid breeding programs in these Mexican states are securing raw material consistency for industrial buyers.
Market Restraints
- Input cost volatility:Fresh jalapeno prices fluctuate with Mexican rainfall patterns and labor availability during harvest windows.
- Supply concentration risk:Overreliance on Chihuahua and Sinaloa growing regions creates vulnerability to climate shocks and water allocation disputes.
- Regulatory friction:EU REACH registration requirements and EFSA novel food assessments delay market entry for new extract formats by months.
Strategic Opportunities
- Pharmaceutical applications:Topical analgesic and metabolic health formulations represent underdeveloped demand channels for standardized capsaicinoid extracts.
- Direct-to-manufacturer platforms:Digital procurement channels are bypassing traditional spice traders, enabling price transparency and lot-level traceability.
- Non-GMO Project verification:This certification gate is commanding retail premiums in North American markets as clean-label requirements tighten.
Industry Challenges
- Extraction technician shortage:Supercritical CO2 operation requires specialized training that outpaces current vocational program output.
- Organic certification timelines:USDA NOP and EU 2018/848 conversion periods extend supplier qualification cycles, constraining rapid scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jalapeno Extract Market |
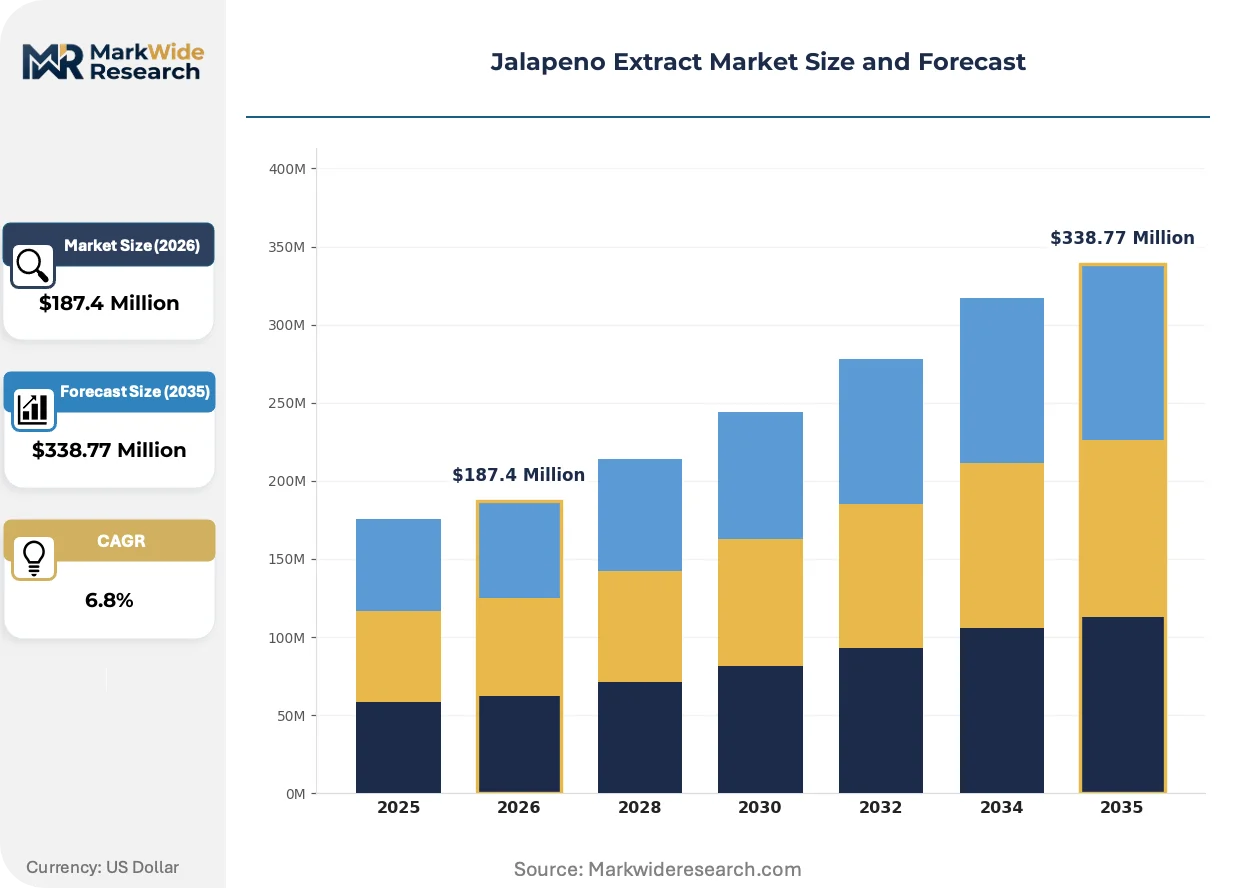
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Spray Dry, Oleoresin Application: Food Industry, Beverage Industry, Nutraceuticals, Spices End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Form: Organic, Conventional, Natural, Synthetic |
| Companies Covered | McCormick & Company, Olam Spices, Silva International, Kalsec Inc., Kerry Group, Sensient Technologies, Synthite Industries Ltd, Ingredion Incorporated, Roland Foods LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jalapeno Extract Market Evolving Landscape
Extraction technology maturation and regulatory harmonization pressures are compressing the supplier base while opening premium positioning for traceable, certified product lines.
Supercritical CO2 extraction systems are supplanting traditional solvent-based methods in capsaicinoid recovery operations. Nutraceutical manufacturers are adopting this technology fastest, prioritizing solvent-free claims for dietary supplement labeling. The shift is compressing margins for conventional oleoresin producers while enabling premium pricing for certified organic extracts.
EU 2018/848 organic regulation implementation is tightening residue limits and traceability requirements for imported spice extracts. Food manufacturers serving European retail channels are now demanding batch-level documentation that exceeds previous import standards. This regulatory tightening favors vertically integrated suppliers with captive Mexican growing operations over trading-focused competitors.
Long-term contracting is replacing spot purchasing among major food manufacturers seeking heat-unit consistency and supply security. Ready-meal producers are locking in multi-year agreements with extraction houses, displacing the traditional commodity auction model. This pattern is most pronounced in North American markets where FSMA compliance costs have made supplier switching prohibitively expensive.
Jalapeno Extract Market Segmentation
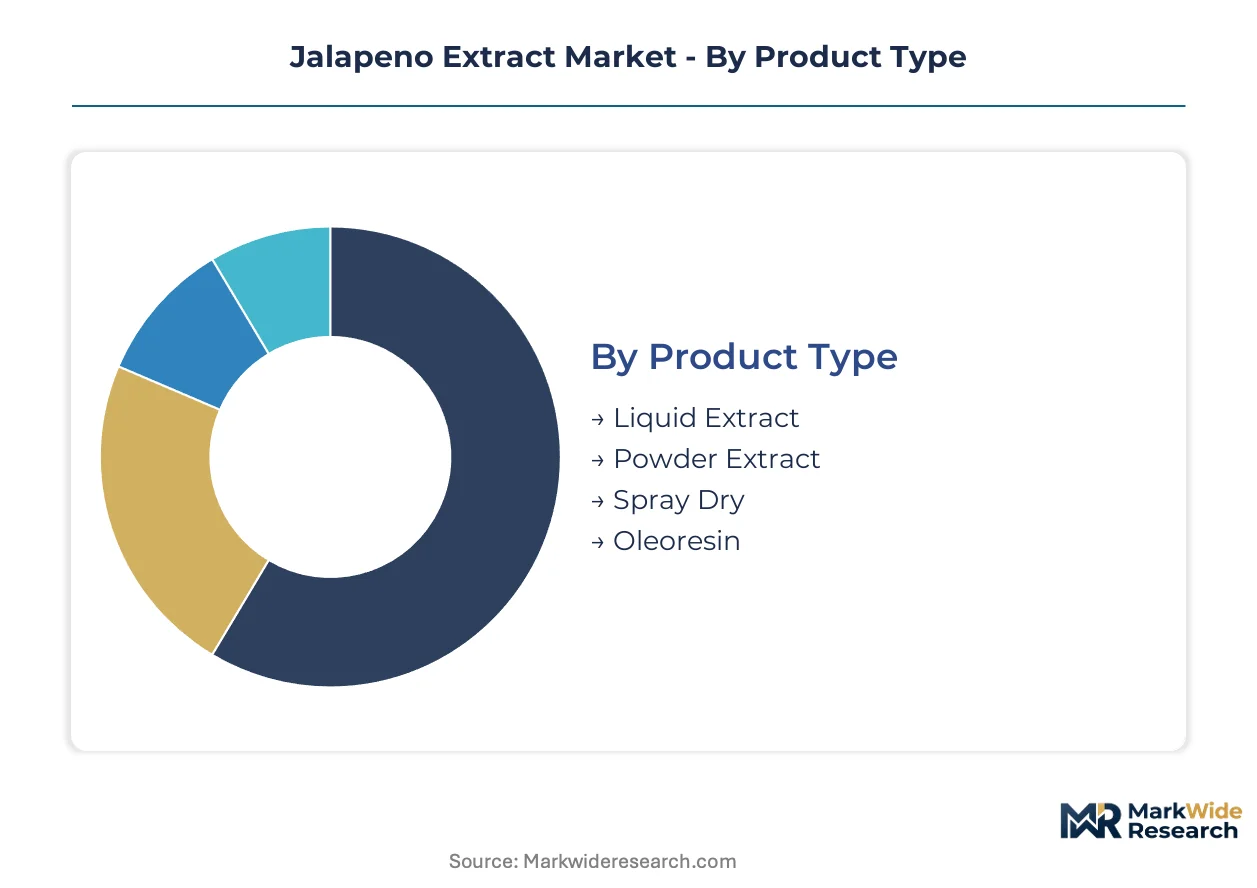
Jalapeno extract segmentation reflects divergent technical requirements across food manufacturing, pharmaceuticals, and retail channels. Substitution pressure from synthetic capsaicin and alternative chili sources forces each segment to defend its positioning through certification, standardization, or cost structure.
Product Type:
Liquid extract and oleoresin face the most acute substitution threat from synthetic capsaicin in pharmaceutical applications, while powder and spray-dry formats compete against commodity chili powders in food manufacturing.
- Liquid Extract:Pumpable aqueous or oil-based solutions standardized to specific Scoville Heat Units enable precise dosing in automated production lines. Demand concentrates among ready-meal manufacturers in the United States where batch consistency and clean-label positioning outweigh higher per-unit costs versus powder alternatives.
- Oleoresin:Concentrated solvent or supercritical CO2-extracted resin containing 500,000 to 1,000,000 SHU provides maximum capsaicinoid density for nutraceutical encapsulation. European dietary supplement manufacturers drive adoption, prioritizing solvent-free extraction claims under EU 2018/848 organic thresholds.
- Powder Extract:Dehydrated and milled material offering logistics efficiency for bulk spice blending operations.
- Spray Dry:Encapsulated powder format providing enhanced shelf stability and controlled release characteristics for beverage applications.
Liquid extract anchors the volume base while oleoresin gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity spice applications from premium nutraceutical positioning, with food and beverage manufacturing absorbing volume through standardized procurement contracts.
- Food Industry:Processed meat, snack seasoning, and sauce applications require heat-unit standardization that only extracted capsaicinoids reliably deliver. Mexican processors supplying multinational food manufacturers dominate this channel through validated HACCP systems meeting FDA FSMA preventive controls.
- Nutraceuticals:Topical analgesic creams and metabolic health supplements demand certified organic extracts with batch-level documentation. German and Swiss pharmaceutical formulators lead this segment, paying premiums for EU REACH-registered oleoresin with full supply chain traceability.
- Beverage Industry:Alcoholic and non-alcoholic drinks incorporate heat elements through micro-dosed liquid extracts.
- Spices:Retail and foodservice bulk seasoning blends utilize powder extracts for cost efficiency.
Food industry procurement anchors the volume base while nutraceuticals expand most quickly through premium pricing power.
End User:
Customer type determines packaging format, certification requirements, and pricing tolerance, with institutional buyers driving standardization and retail channels demanding differentiated positioning.
- Food Manufacturers:Industrial-scale buyers lock in multi-year contracts with extraction houses for heat-unit consistency and FSMA-compliant documentation. These procurement patterns concentrate among North American ready-meal and snack producers seeking supply security over spot-market savings.
- Restaurants:Foodservice operators require consistent heat profiles across distributed locations, favoring liquid extracts for sauce and marinade standardization.
- Retailers:Private-label and branded spice merchandisers demand Non-GMO Project verification and organic certification for shelf placement.
- Home Cooks:Small-format retail bottles compete against fresh and dried chili alternatives on convenience and intensity control.
Food manufacturers anchor the volume base while retailers gain share at the steepest rate through certification-driven premium positioning.
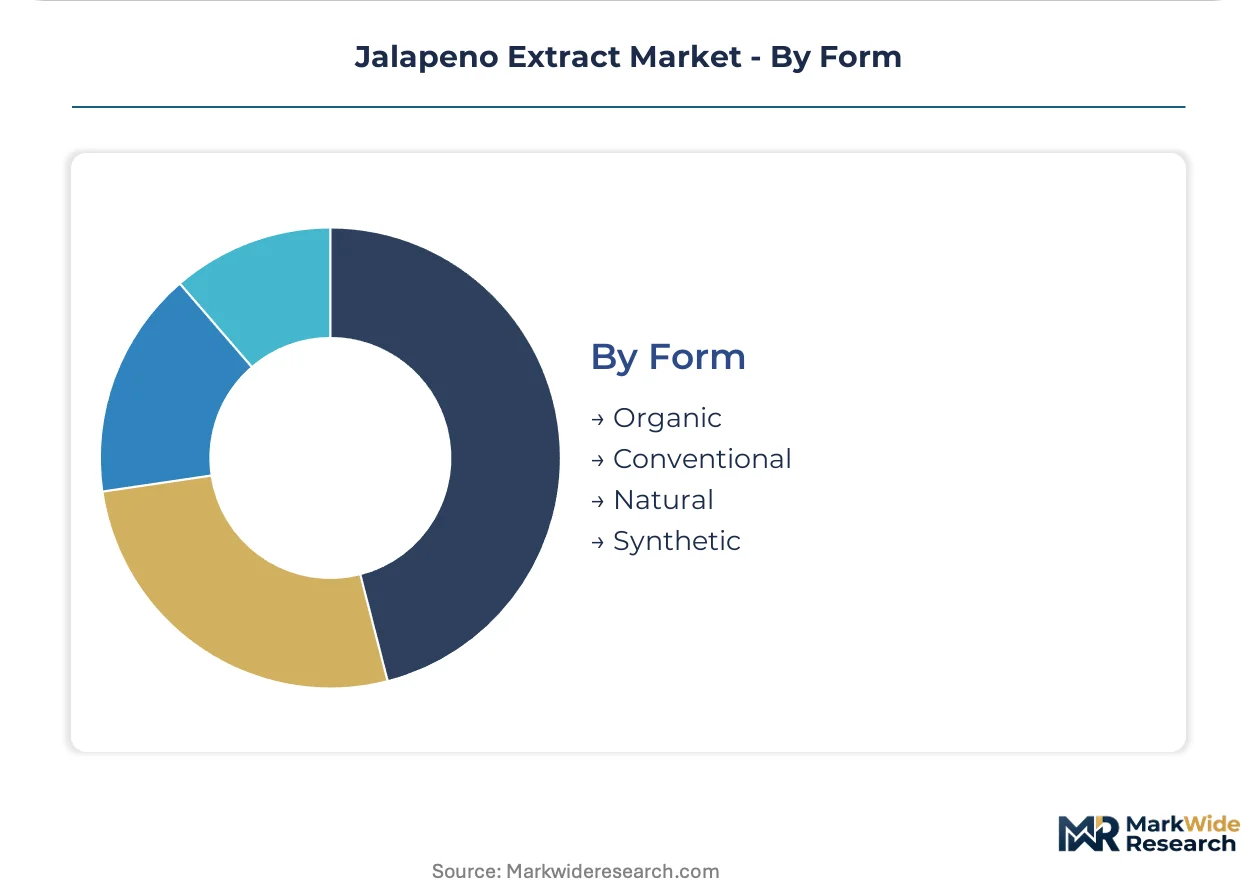
Form:
Margin stratification separates certified organic from conventional offerings, with natural and synthetic forms competing on functional equivalence rather than clean-label positioning.
- Organic:USDA NOP and EU 2018/848 certification requires three-year conversion periods, residue testing, and full traceability from Mexican growing regions. This form commands retail premiums in North American and European markets where clean-label requirements have become non-negotiable for shelf placement.
- Conventional:Standard extraction without organic certification serves cost-sensitive food manufacturing where heat-unit consistency matters more than label claims.
- Natural:Non-certified but naturally derived extracts occupy a mid-market positioning for price-conscious clean-label buyers.
- Synthetic:Laboratory-synthesized capsaicin competes on cost for pharmaceutical applications where natural origin provides no therapeutic advantage.
Conventional forms anchor the volume base while organic certification gains share at the steepest rate through retail channel requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Veracruz's refrigerated cargo terminals anchor Mexico's jalapeno extract export capacity, linking Chihuahua and Sinaloa growing regions to North American and European food manufacturers.
United States
Ready-meal manufacturers in Chicago and snack processors in Texas drive industrial demand for standardized liquid extracts. FDA FSMA preventive controls on imported spices disqualify non-compliant Mexican suppliers, redirecting volume toward certified processors with validated HACCP documentation. McCormick & Company maintains backward integration into Mexican growing regions through its Maryland-based procurement network.
Mexico
Irrigation infrastructure investments in Chihuahua and capsaicinoid breeding programs in Sinaloa secure raw material consistency for extraction houses. The country's national agricultural regulator enforces pesticide tolerance limits that govern export eligibility to US and EU markets. Guadalajara-based processing clusters concentrate supercritical CO2 extraction capacity serving pharmaceutical and nutraceutical buyers.
Germany
Dietary supplement formulators in Bavaria and pharmaceutical manufacturers in North Rhine-Westphalia import premium oleoresin for topical analgesic applications. EFSA novel food assessments and EU REACH registration requirements delay market entry for new extract formats by regulatory review cycles. Hamburg's spice trading houses specialize in EU 2018/848 organic certification documentation for retail channel distribution.
India
Oleoresin concentration capabilities at Kerala processing complexes serve cost-sensitive food manufacturers seeking heat-unit standardization. FSSAI food safety standards and DGFT export documentation requirements govern shipment eligibility to Middle Eastern and Southeast Asian markets. Kochi port infrastructure supports bulk spice extract consolidation for re-export to European compounders.
Switzerland
Pharmaceutical encapsulation specialists in Basel procure certified organic extracts for metabolic health supplement formulations. Swissmedic therapeutic product regulations and EU 2018/848 organic equivalence agreements enable seamless distribution into German and French retail channels. Zurich-based trading houses coordinate lot-level traceability documentation for premium nutraceutical contracts.
Jalapeno Extract Market Competitive Landscape
Listed leaders compete with private specialists across extraction technology and certification tiers. The supplier base compresses around three structural positions: multinational flavor houses with captive Mexican supply, regional oleoresin specialists with supercritical CO2 capabilities, and commodity traders losing share to traceable sourcing platforms. Dominant competitive moves include backward integration into Chihuahua-Sinaloa growing regions and multi-year contracting with ready-meal manufacturers seeking FSMA-compliant documentation.
Within the vertically integrated tier, McCormick & Company and Kalsec Inc. exemplify archetypes of traceable supply chain control, while Synthite Industries Ltd occupies a position among oleoresin concentration specialists. These three entities represent contrasting strategic postures: captive agricultural sourcing, extraction technology specialization, and regional processing scale respectively.
| Leading Market Players |
|---|
| McCormick & Company |
| Olam Spices |
| Silva International |
| Kalsec Inc. |
| Kerry Group |
| Sensient Technologies |
| Synthite Industries Ltd |
| Ingredion Incorporated |
| Roland Foods LLC |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between ready-meal manufacturers and Mexican extraction houses lock in both supply access and price visibility, insulating buyers from spot-market volatility in Chihuahua and Sinaloa growing regions while embedding FSMA compliance costs into contract structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic oleoresin from conventional liquid extracts and commodity powder grades. Price differentiation rests on USDA NOP certification status and supercritical CO2 extraction claims, with nutraceutical buyers in Germany and Switzerland showing lowest price sensitivity. Cost compression in conventional oleoresin is intensifying because synthetic capsaicin alternatives erode pharmaceutical margins.
Supply Chain Analysis
Inventory cycles spanning 8-12 months from Mexican harvest through European processing create working capital intensity for extraction houses managing perishable raw material commitments. Supply concentrates in Mexico, India, and the United States, with capsaicinoid-rich jalapeno varieties, food-grade solvents, and supercritical CO2 equipment anchoring input dependencies. Single-source vulnerability in Chihuahua-Sinaloa irrigation districts threatens yield consistency. Distribution runs through Veracruz port consolidation for North American food manufacturers and Hamburg trading houses for EU retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as clean-label certification requirements splinter procurement into specialized tiers, creating defendable niches for suppliers with captive Mexican operations and validated organic documentation.
For Market Incumbents: Compound backward integration advantages by securing additional irrigation rights in Sinaloa capsaicinoid breeding zones and locking multi-year capacity reservations with ready-meal manufacturers. Synthetic capsaicin substitution in topical analgesics threatens oleoresin margins; counter through EU 2018/848 organic certification investment that trading-focused competitors cannot replicate within conversion timelines. For New Entrants and Emerging Players: Differentiate on solvent-free extraction technology for North American nutraceutical contract manufacturers seeking Non-GMO Project verification. White-space targets include direct-to-manufacturer digital procurement platforms and pharmaceutical-grade capsaicinoid standardization for metabolic health formulations. The most penetrable entry point is mid-tier food manufacturers bypassing traditional spice traders for lot-level traceability. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extraction houses with captive Mexican growing operations and multi-year pharmaceutical contracts. Long-term viability over a 5-10 year horizon favors vertically integrated specialists over commodity traders losing share to traceable sourcing platforms. The signal to watch is FDA enforcement intensity on imported spice preventive controls, which accelerates supplier consolidation when disqualification thresholds tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Growing Regions | Captive supply of Chihuahua-Sinaloa jalapeno varieties secures raw material traceability for FSMA compliance. |
| Supercritical CO2 Capacity Expansion | Solvent-free extraction technology enables EU 2018/848 organic certification and pharmaceutical-grade standardization. |
| Long-term Supply Agreement | Multi-year contracts with ready-meal manufacturers displace spot purchasing and embed heat-unit consistency requirements. |
| Digital Procurement Platform Launch | Direct-to-manufacturer channels bypass traditional spice traders and enable price transparency for mid-tier buyers. |
| Non-GMO Project Verification Program | Retail channel certification gates access to North American clean-label shelf placement and commands premium positioning. |
Research Methodology
A standing panel of extraction technology directors, procurement leads at multinational food manufacturers, Mexican agricultural extension officers, and EU regulatory affairs specialists provided ongoing calibration across primary fieldwork and secondary validation. Bottom-up triangulation combined trade flow analysis from customs databases, FDA import refusal records, EFSA novel food assessment filings, and USDA National Organic Program operator lists with top-down cross-checks against disclosed capacity at major processing clusters.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product format, application end-use, certification tier, and regional regulatory cluster. CAGRs were derived through iterative convergence of demand-side adoption curves and supply-side capacity constraints, with capsaicinoid breeding program yields and supercritical CO2 extraction throughput serving as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained irrigation infrastructure investment in Mexican source regions or stable FDA enforcement posture would require recalibration. Forecasts reflect assumptions regarding climate volatility, labor availability during harvest windows, and organic certification conversion timelines. Revision becomes warranted when capsaicinoid patent litigation or water allocation disputes in Chihuahua-Sinaloa cross thresholds that disrupt raw material supply continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Peppermint Leaf Powder Market
Extracts
Sandalwood Oil Market
Extracts
Histidine Market
Extracts
Laurel Oil Market
Extracts
Essential Oil Isolates Market
Extracts
Hydroglycolic Extracts Market
Extracts
Global Marigold Flower Extract Market
Extracts
Global Rose Oils Market
Extracts
Pearl Extract Market
Extracts
Bee Venom Extract Market
Extracts
Organic Extracts Market
Extracts
Phytochemicals Market
Extracts
Citrus Powder Market
Extracts
Anise Extract Market
Extracts
Global Azadirachtin Market
Extracts
Asia-Pacific Spirulina Extract Market