
 Pectin Powder Market | 2026-2036
Pectin Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Pectin Powder Market Analytics
Citrus processing capacity in Brazil is expanding as orange peel supply chains tighten globally. Cargill Incorporated leverages backward integration into citrus sourcing to secure raw material throughput. CP Kelco anchors its position through specialized alginate-pectin hybrid formulations for controlled-release pharmaceutical applications. Herbstreith & Fox sustains European market presence with dedicated organic pectin certification streams.
Pectin powder consists of complex polysaccharide extracts derived primarily from citrus peels and apple pomace, with galacturonic acid content exceeding 65 percent by dry weight and gelling functionality dependent on degree of methoxylation. The extract functions as a hydrocolloid stabilizer, thickener, and gelling agent across food systems, pharmaceutical delivery matrices, and cosmetic emulsions. High-methoxyl pectin dominates conventional jam and confectionery applications where rapid set and thermal stability prove essential, while low-methoxyl variants capture expanding dairy alternative and reduced-sugar segments through calcium-reactive gelation without added sucrose. Amidated pectin occupies specialized pharmaceutical and nutraceutical niches where ionic sensitivity enables targeted release profiles.
EFSA maintains purity specifications for pectin food additive classifications under Regulation 231/2012, while FDA GRAS status governs US market entry requirements for pectin-derived ingredients. The EU Green Deal agricultural waste valorization targets are redirecting fruit processing byproduct streams toward pectin extraction facilities, altering regional supply economics. Stakeholders must monitor evolving EFSA re-evaluation timelines for hydrocolloid safety profiles and assess captive citrus peel supply arrangements before committing to capacity expansion decisions.
Market Dynamics
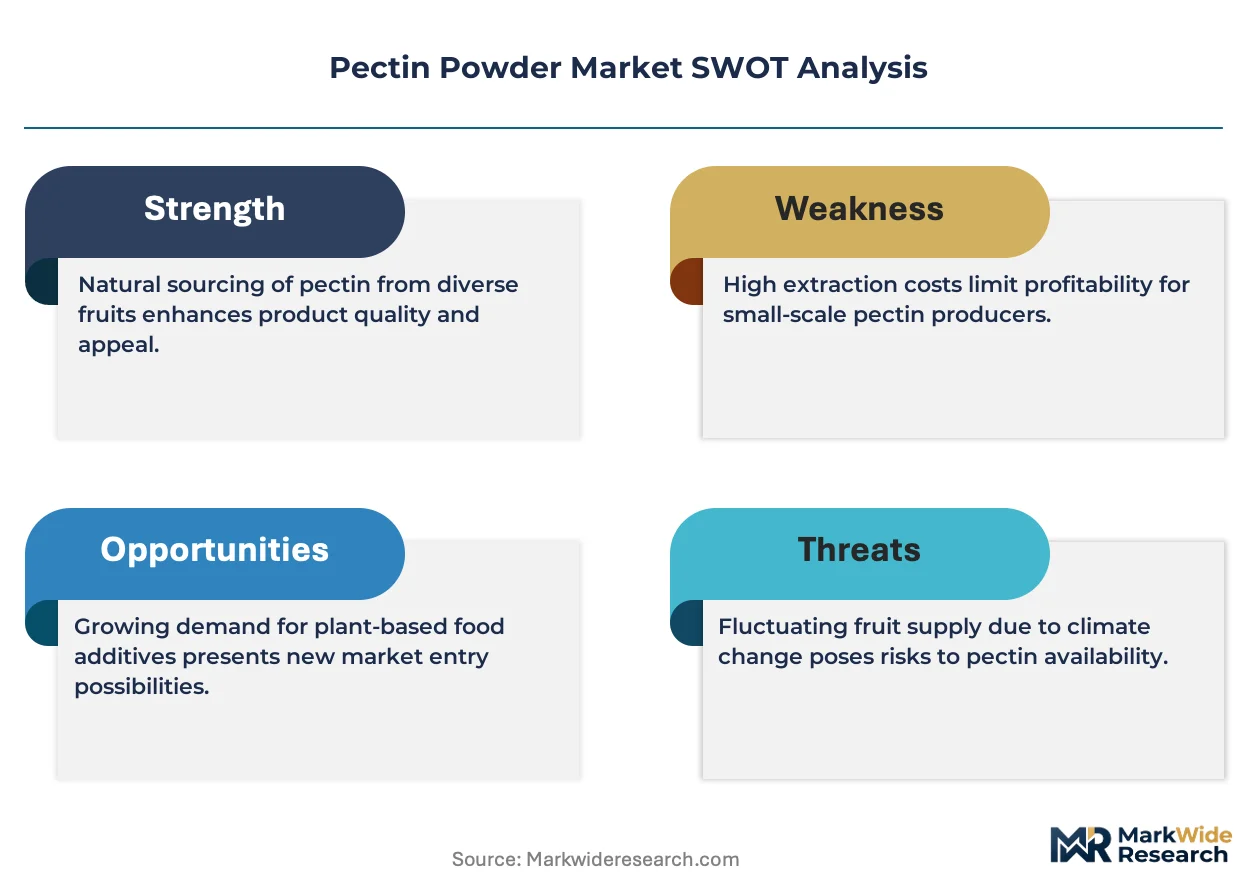
Clean-label formulation mandates from EFSA are compressing synthetic hydrocolloid use, forcing food manufacturers to reformulate around citrus-derived pectin systems that meet updated purity thresholds under Regulation 231/2012.
Growth Catalysts
- EFSA Purity Standards:Tighter additive classifications under EU Regulation 231/2012 are disqualifying synthetic stabilizers from premium confectionery and dairy lines, redirecting formulation spend toward certified pectin streams.
- Apple Pomace Valorization:EU Green Deal agricultural waste targets are redirecting fruit processing byproduct streams toward pectin extraction facilities, expanding raw material throughput without competing food demand.
- Calcium-Reactive Gelation:Low-methoxyl pectin variants are capturing dairy alternative segments through sucrose-independent gelation, enabling reduced-sugar label claims that high-methoxyl systems cannot match.
Market Restraints
- Citrus Peel Supply Concentration:Orange peel availability tightens as Brazilian citrus processing capacity faces climate volatility, concentrating raw material risk in subtropical sourcing zones.
- Amidated Pectin Technical Ceiling:Ionically sensitive amidated variants face solubility constraints in high-acid beverage matrices, limiting penetration in ready-to-drink functional categories.
- Pharmaceutical Certification Friction:FDA GRAS status for pectin-derived ingredients requires batch-specific documentation that extends qualification timelines for controlled-release drug delivery applications.
Strategic Opportunities
- German Confectionery Cluster:Ingredient processors serving central European dairy and candy manufacturers face reformulation pressure that favors local pectin sourcing over Asian hydrocolloid alternatives.
- Alginate-Pectin Hybrid Convergence:Controlled-release pharmaceutical matrices are unifying marine and plant-derived hydrocolloids, creating premium formulation tiers unavailable to single-source stabilizers.
- Organic Certification Stream:Dedicated organic pectin certification is opening price-premium channels in European natural cosmetics and clean-label infant nutrition segments.
Industry Challenges
- Galacturonic Acid Assay Expertise:Degree-of-methoxylation testing requires specialized analytical chemistry capacity that contract labs in secondary processing regions struggle to maintain.
- Backward Integration Capital Intensity:Captive citrus peel supply arrangements demand upstream investment in fruit processing partnerships that mid-scale extractors cannot finance without dilution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pectin Powder Market |
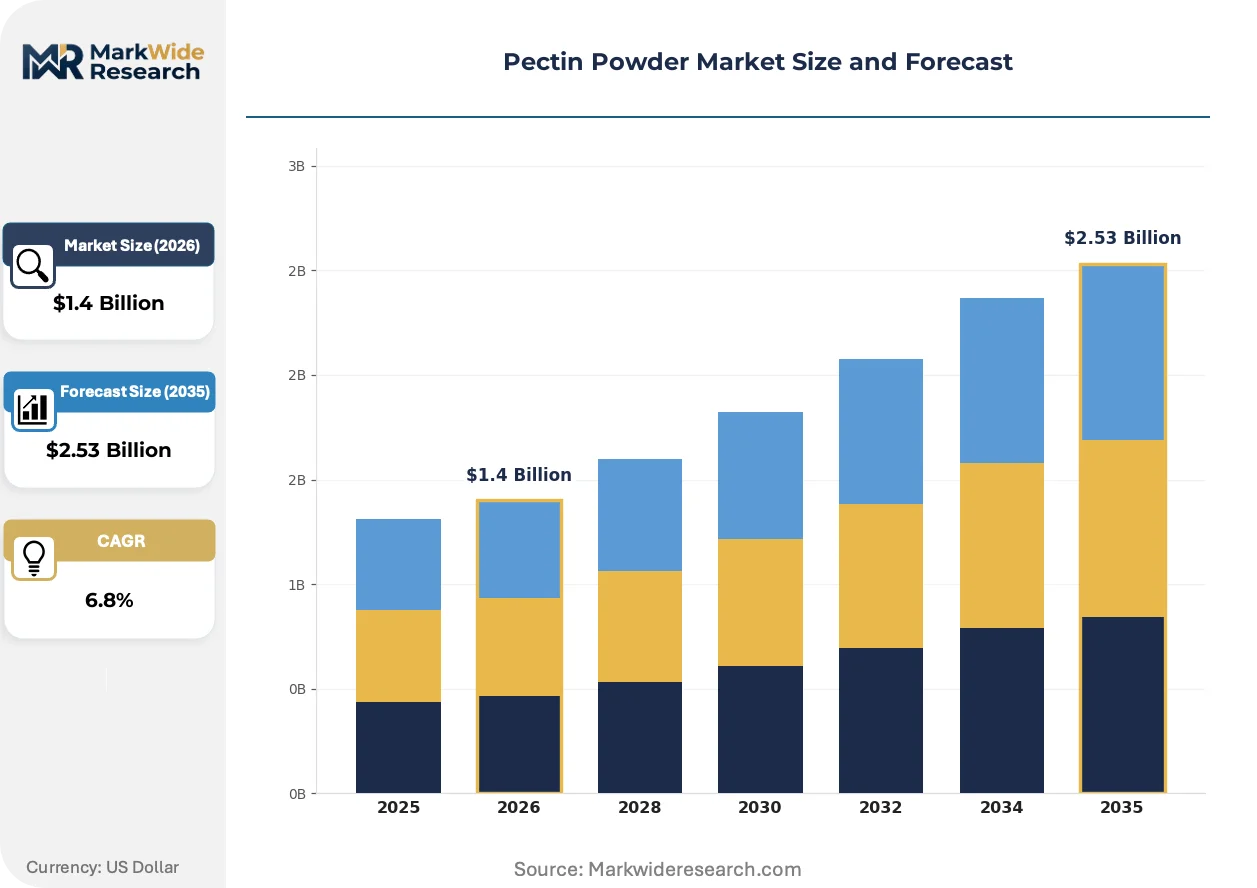
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Rmethoxyl Pectin, Low-Methoxyl Pectin, Amidated Pectin, Organic Pectin Application: Food & Beverage, Pharmaceuticals, Personal Care, Dietary Supplements End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Nutraceutical Producers Form: Powdered, Liquid, Gel, Granulated |
| Companies Covered | Cargill Incorporated, CP Kelco, Herbstreith & Fox, DuPont, Yantai Andre Pectin Co. Ltd., Ingredion Incorporated, Tate & Lyle PLC, Koninklijke DSM N.V., International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pectin Powder Market Evolving Landscape
Formulation science is converging plant and marine hydrocolloids while regulatory purity standards compress acceptable additive portfolios, reshaping how stabilizers are specified, sourced, and priced across food and pharmaceutical systems.
Enzymatic de-esterification systems are unifying high-methoxyl and low-methoxyl production lines within single facilities, allowing citrus processors to switch output based on spot dairy versus confectionery demand. German ingredient houses are adopting these flexible systems fastest, compressing lead times for calcium-reactive gels that reduced-sugar yogurt brands require. This unification is collapsing the traditional segmentation between jam-grade and dairy-grade pectin supply chains.
REACH chemical registration requirements are extending disclosure obligations to pectin extraction byproducts, forcing European processors to document solvent residues and heavy metal profiles beyond food-grade thresholds. Industrial consequence includes redirected capital toward closed-loop extraction systems that pharmaceutical buyers now mandate. The pharmaceutical and nutraceutical segment is responding fastest, with controlled-release matrix suppliers demanding REACH-compliant certification that food-grade competitors lack.
Ingredient procurement is consolidating around dual-source hydrocolloid contracts that specify pectin as primary stabilizer with carrageenan fallback clauses, compressing spot-market exposure for manufacturers. This specification shift disrupts traditional single-source supply relationships that dominated 2010s formulation practice. The pattern is most visible in German dairy alternative production, where reformulation agility outweighs unit cost minimization.
Pectin Powder Market Segmentation
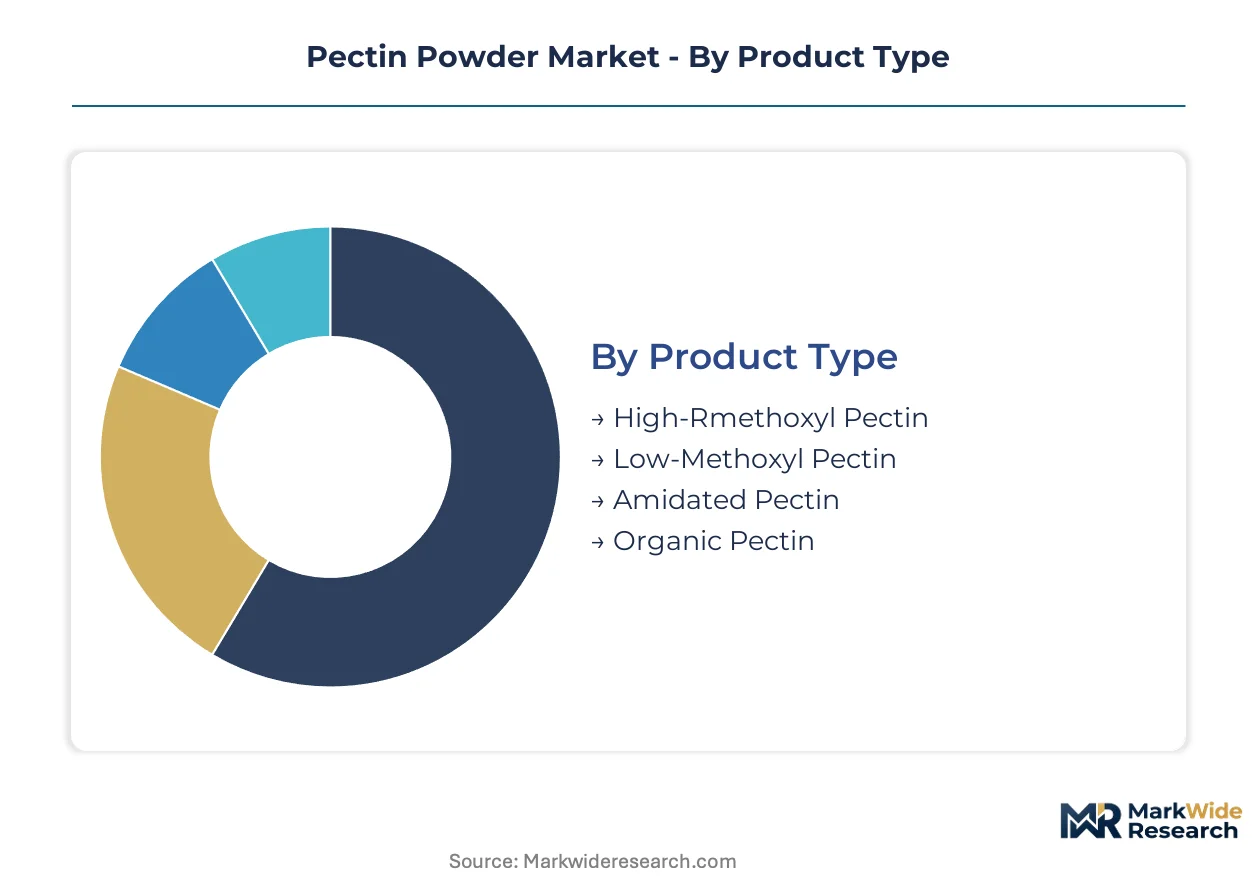
Pectin powder segmentation reflects divergent technical specifications across methoxylation grades and contrasting purity requirements between food-grade and pharmaceutical-grade buyers. Manufacturers configure extraction lines around specific degree-of-methoxylation targets that lock in end-use applications.
Product Type:
Buyers select methoxylation grade based on gelation chemistry requirements and label positioning strategy.
- High-Methoxyl Pectin:Contains over 50 percent esterified galacturonic acid units, requiring high sugar concentration and acidic pH for thermally reversible gel formation. German confectionery houses specify this grade for traditional jam applications where rapid set characteristics and thermal stability dominate formulation decisions. EFSA Regulation 231/2012 purity thresholds compress supplier pools to certified citrus processors with documented peel provenance.
- Low-Methoxyl Pectin:Carries under 50 percent esterification, enabling calcium-reactive gelation independent of sucrose concentration. Dairy alternative manufacturers in France and Netherlands reformulate around this grade to achieve reduced-sugar label claims that high-methoxyl systems cannot support. Calcium sensitivity expands application scope but demands precise ionic strength control during processing.
- Amidated Pectin:Modified through ammonia treatment to introduce amide groups, delivering ionic sensitivity for targeted pharmaceutical release profiles. Solubility constraints in high-acid beverage matrices limit ready-to-drink penetration.
- Organic Pectin:Extracted from certified organic citrus peels and apple pomace under EU organic regulation compliance. Premium infant nutrition and natural cosmetics segments absorb price premiums for traceable supply chains.
Volume sits with high-methoxyl grades; growth tilts toward low-methoxyl variants.
Application:
End-use sectors impose divergent certification burdens that reshape procurement patterns and margin structures.
- Food & Beverage:Jam, confectionery, dairy, and beverage stabilizer applications requiring rapid-set or thermally stable gel systems. Clean-label mandates from EFSA and FDA GRAS documentation compress acceptable additive portfolios toward citrus-derived alternatives.
- Pharmaceuticals:Controlled-release matrix applications demanding batch-specific purity documentation and REACH-compliant solvent residue profiles. European processors invest in closed-loop extraction systems to meet pharmaceutical buyer mandates.
- Personal Care:Cosmetic emulsion stabilizers and natural texture modifiers. Organic certification streams open price-premium channels in European natural cosmetics segments.
- Dietary Supplements:Gelling agents for gummy formulations and encapsulation matrices. Calcium-reactive low-methoxyl grades enable reduced-sugar positioning in functional confectionery.
Food and beverage commands current volume; pharmaceuticals generate steepest expansion trajectory.
End User:
Customer scale and technical capability determine contract structures and specification depth.
- Food Manufacturers:Large-scale jam, dairy, and confectionery producers with dedicated formulation teams. Dual-source hydrocolloid contracts with pectin-primary and carrageenan-fallback clauses compress spot-market exposure.
- Cosmetic Companies:Natural and organic personal care brands prioritizing supply chain transparency. Organic certification requirements exceed food-grade thresholds.
- Pharmaceutical Firms:Controlled-release drug delivery specialists requiring batch-specific galacturonic acid assay documentation. FDA GRAS qualification timelines extend procurement cycles.
- Nutraceutical Producers:Gummy vitamin and supplement manufacturers seeking clean-label gelling alternatives. Reduced-sugar positioning drives low-methoxyl specification.
Food manufacturers anchor procurement volume; pharmaceutical firms expand contract value fastest.
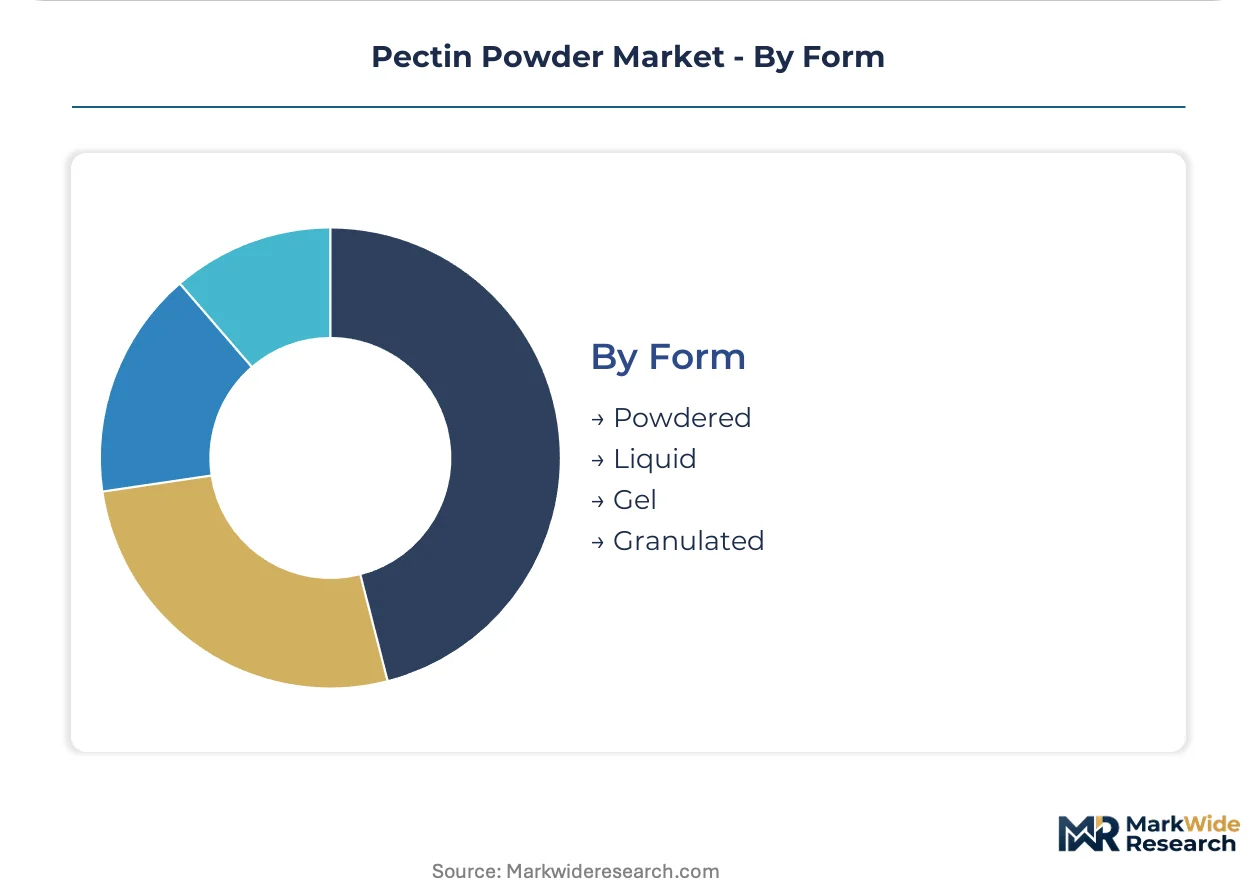
Form:
Physical state selection balances dissolution kinetics against storage stability and handling economics.
- Powdered:Standard dry form with extended shelf stability and precise dosing control. Dominates bulk ingredient procurement for large-scale food manufacturing.
- Liquid:Pre-hydrated solutions eliminating dissolution steps in high-throughput beverage operations. Higher transport costs limit geographic distribution radius.
- Gel:Pre-formed concentrated pectin gels for specialized confectionery and pharmaceutical compounding. Niche positioning in artisanal and small-batch production.
- Granulated:Free-flowing agglomerated particles reducing dust generation and improving dispersibility. Favored in pharmaceutical cleanroom environments.
Powdered form holds installed base; granulated formats gain share in pharmaceutical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian citrus peel supplies anchor regional production economics, while European formulation demand and Asian manufacturing scale reshape trade flows across the pectin powder value chain.
Germany
Confectionery and dairy clusters in Bavaria and North Rhine-Westphalia drive specification-grade pectin procurement. EFSA Regulation 231/2012 purity mandates compress supplier pools to certified processors with documented citrus provenance. Ingredient houses around Hamburg adopt enzymatic de-esterification systems to switch between high-methoxyl and low-methoxyl output based on spot demand.
Brazil
Orange peel availability from São Paulo state citrus processors determines global raw material throughput. Climate volatility in subtropical growing zones concentrates supply risk in single-source geography. Cargill leverages backward integration into citrus sourcing to secure captive peel streams for extraction facilities.
United States
FDA GRAS documentation requirements extend qualification timelines for pharmaceutical-grade pectin batches. Clean-label reformulation in dairy alternatives and reduced-sugar confectionery accelerates low-methoxyl specification. California-based natural cosmetics brands absorb organic certification premiums for traceable supply chains.
China
Yantai-region processors serve domestic dairy and jam manufacturing at scale. SAMR food additive classifications align with Codex standards but lack EFSA-equivalent purity stringency. Pearl River Delta beverage manufacturers experiment with calcium-reactive gels for reduced-sugar ready-to-drink lines.
France
Dairy alternative producers in Normandy and Brittany reformulate around low-methoxyl grades for reduced-sugar label claims. EU Green Deal agricultural waste valorization redirects apple pomace from cider production toward pectin extraction. REACH chemical registration extends disclosure obligations to extraction byproducts beyond food-grade thresholds.
Pectin Powder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue organic certification and pharmaceutical-grade specialization. The vendor base stratifies around three archetypes: citrus-integrated multinationals with captive raw material control, regional extractors serving food-grade volume, and hybrid hydrocolloid specialists unifying marine and plant-derived systems. Consolidation pressure concentrates in European confectionery supply chains where EFSA compliance costs disqualify smaller processors. Dominant competitive moves include backward integration into peel sourcing and closed-loop extraction system investment for REACH compliance.
Among North American multinationals, Cargill Incorporated anchors the integrated-processor archetype through upstream citrus control. CP Kelco exemplifies the hybrid-specialist position with alginate-pectin formulation convergence for controlled-release applications. Herbstreith & Fox occupies the European certification-leader tier with dedicated organic pectin streams. These three represent distinct strategic vectors: raw material security, technical formulation hybridization, and premium certification segmentation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| CP Kelco |
| Herbstreith & Fox |
| DuPont |
| Yantai Andre Pectin Co. Ltd. |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Koninklijke DSM N.V. |
| International Flavors & Fragrances |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification streams command 40-60% price premiums over food-grade pectin, and this bifurcation manifests in parallel supply chain configurations where REACH-compliant closed-loop extraction systems serve drug delivery buyers while commodity citrus processors feed confectionery manufacturers. EFSA Regulation 231/2012 purity thresholds compress certified supplier pools in Germany, amplifying pricing power for documented peel-provenance holders while spot-market exposure concentrates in Asian hydrocolloid alternatives.
Pricing Analysis
Technical documentation bundling separates pharmaceutical-grade contracts from food-grade transactions, with batch-specific galacturonic acid assays and REACH solvent-residue profiles included in premium pricing while commodity buyers absorb unbundled testing costs. Three-tier pricing structure across pharmaceutical, certified food-grade, and economy hydrocolloid levels reflects certification depth and peel-provenance documentation. Cost compression in economy tiers intensifies because Brazilian citrus processing capacity faces climate volatility, squeezing raw material throughput. Small-scale cosmetic companies exhibit highest price sensitivity, while pharmaceutical firms accept extended qualification timelines for assured purity documentation.
Supply Chain Analysis
Apple pomace reclamation from French cider production and Brazilian orange peel processing create circular input flows that reduce waste disposal costs for extraction facilities. Raw material sourcing concentrates in Brazil, China, and Germany, with peel availability drawing from São Paulo state citrus processors, Yantai-region fruit handling, and Bavarian agricultural cooperatives. Single-source vulnerability in subtropical citrus zones threatens throughput stability when climate volatility disrupts Brazilian harvests. Distribution runs through ingredient houses in Hamburg and Rotterdam serving central European dairy and confectionery clusters, with pharmaceutical buyers mandating direct processor relationships bypassing distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA compliance cost escalation is forcing consolidation among mid-scale European extractors unable to fund REACH-certified closed-loop systems, creating acquisition opportunities for well-capitalized processors with captive citrus arrangements.
For Market Incumbents: Hedge against Brazilian supply concentration by securing multi-origin peel contracts with French apple pomace valorization streams and German agricultural cooperative partnerships. Diversify methoxylation flexibility through enzymatic de-esterification systems that switch output between high-methoxyl confectionery grades and low-methoxyl dairy alternatives based on spot demand shifts. For New Entrants and Emerging Players: Organic-certified infant nutrition manufacturers represent an underserved buyer archetype willing to absorb 25-35% price premiums for traceable EU organic regulation compliance. Penetrate this segment through dedicated extraction lines with documented solvent-free processing and third-party certification partnerships rather than competing on food-grade volume. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid hydrocolloid specialists given alginate-pectin convergence for controlled-release pharmaceutical applications expanding addressable market scope. Long-term viability hinges on backward integration into citrus sourcing or marine alginate supply chains that secure raw material control. Monitor EFSA re-evaluation timelines for hydrocolloid safety profiles as inflection indicators for certification-intensive processor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Sourcing | Cargill's São Paulo peel partnerships demonstrate captive raw material security against climate volatility. |
| Closed-Loop Extraction System Investment | REACH-compliant solvent recovery meets pharmaceutical buyer mandates that food-grade competitors cannot satisfy. |
| Enzymatic De-Esterification Line Conversion | German processors switch between high-methoxyl and low-methoxyl output based on dairy versus confectionery spot demand. |
| Organic Certification Stream Development | Herbstreith & Fox's dedicated organic lines capture infant nutrition price premiums unavailable to conventional extractors. |
| Alginate-Pectin Hybrid Formulation R&D | CP Kelco's marine-plant hydrocolloid convergence creates controlled-release matrices for pharmaceutical delivery applications. |
Research Methodology
Independent corroboration across extraction facility technical directors, pharmaceutical formulation scientists, and EFSA regulatory affairs specialists underwrites the qualitative findings in this analysis. Primary fieldwork engaged citrus processing plant managers in São Paulo, ingredient procurement leads at German confectionery houses, and REACH compliance officers at Dutch extraction facilities. Secondary validation drew from EFSA additive re-evaluation databases, EU Green Deal agricultural waste valorization reports, and customs records of citrus peel trade flows. Bottom-up capacity assessments at named extraction facilities were triangulated against top-down demand estimates from downstream food and pharmaceutical manufacturers.
Historical reference periods spanning pre- and post-EFSA Regulation 231/2012 implementation anchor the forecast window, with growth trajectories calibrated to observed reformulation shifts in German dairy alternative production. The analytical framework models demand across methoxylation grade, application sector, and end-user scale dimensions. CAGRs were derived from segment-level growth rate convergence methods incorporating citrus peel supply elasticity and clean-label substitution coefficients. Industry-specific inputs include enzymatic de-esterification adoption curves and pharmaceutical-grade certification penetration rates.
Revisions become necessary when EFSA re-evaluates hydrocolloid safety classifications or when Brazilian citrus processing capacity experiences sustained climate disruption. Forecasts reflect assumptions about continued clean-label substitution momentum and REACH compliance cost trajectories. Practitioners should monitor EFSA additive re-evaluation timelines and subtropical climate indices for early signals of supply or regulatory inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Cornflower Extract Market
Extracts
Natural Rosemarine Extract Market
Extracts
Corn Steep Powder Market
Extracts
Essential Oil Isolates Market
Extracts
China Cedar Wood Oil Market
Extracts
Europe Mineral Turpentine Market
Extracts
Sage Extract Market
Extracts
Kelp Extracts Market
Extracts
Nootkatone Market
Extracts
Lemongrass Oil Market
Extracts
Saffron Extract Market
Extracts
Peppermint Leaf Powder Market
Extracts
Nigella Sativa Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Valerian Root Powder Market
Extracts
Pearl Extract Market