
 Zabuyelite Market | 2026-2036
Zabuyelite Market Size, Share, and Industry Trends Forecast 2026-2036
Zabuyelite Market Analysis
Long-term supply contracts with embedded price-adjustment mechanisms is expanding how zabuyelite gets monetized beyond spot transactions. Albemarle Corporation leverages its Chilean brine assets to sustain cost-advantaged production at scale. Jiangxi Ganfeng Lithium Co Ltd anchors its position through backward integration into hard-rock mining and downstream battery chemical refining. SQM Sociedad Química y Minera de Chile SA differentiates via direct shipping ore partnerships that bypass intermediate traders.
Zabuyelite is a naturally occurring lithium carbonate mineral (Li₂CO₃) with theoretical lithium oxide content near 40.5 percent, typically extracted through solar evaporation of lithium-rich brines followed by purification to battery-grade or technical-grade specifications. Its primary commercial purpose centers on lithium-ion battery cathode production and specialty glass-ceramic manufacturing. Crystalline zabuyelite commands premium pricing due to stringent impurity thresholds demanded by cathode makers, while powder grades serve mature applications in pharmaceutical and ceramic flux markets where margin pools remain thinner. The food industry application segment shows structural expansion as lithium fortification gains regulatory traction in functional beverages.
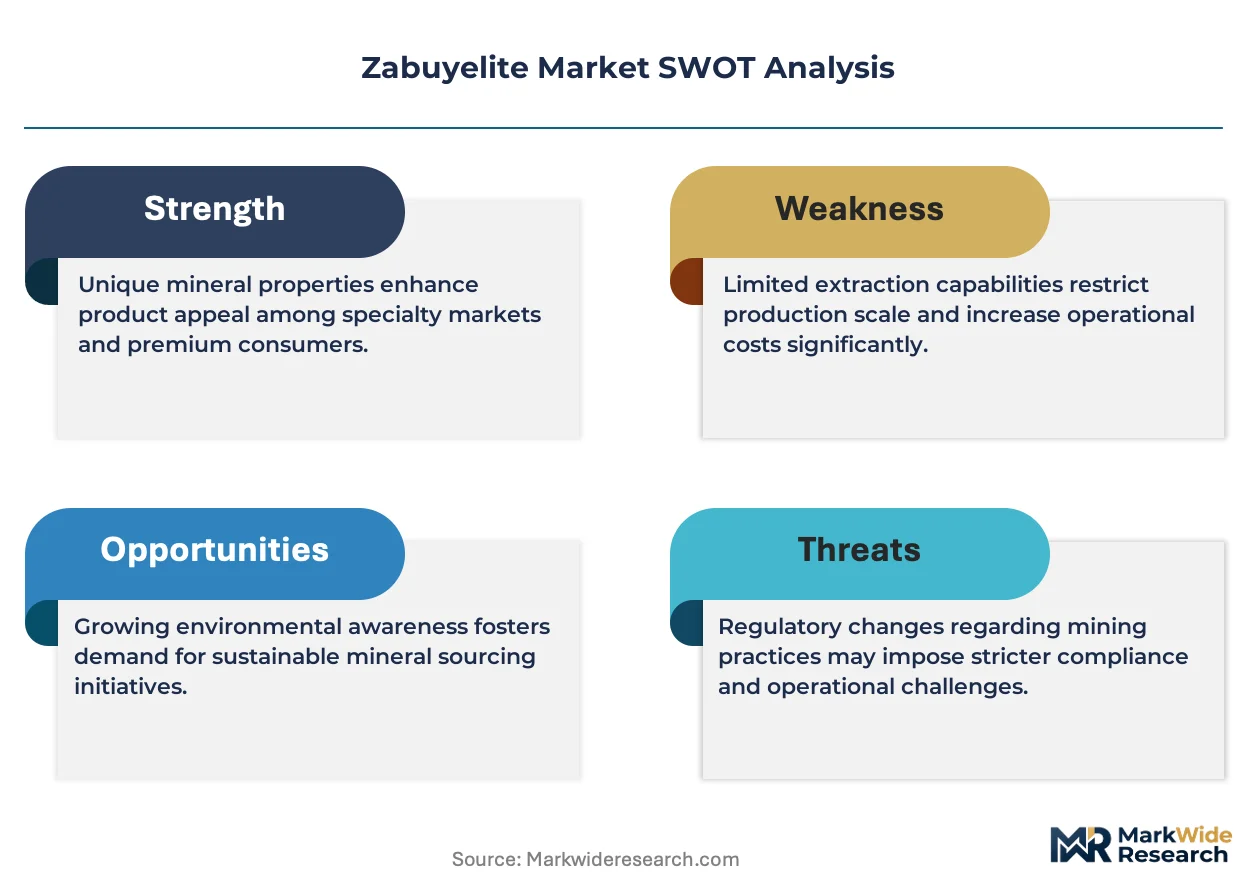
China's SAMR enforces GB/T 11075 purity standards that disqualify lower-grade imports, while Chile's environmental regulator imposes brine extraction quotas that constrain volume growth. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape zabuyelite sourcing criteria for European cell manufacturers. Stakeholders must monitor brine concession renewals in the Atacama and Qinghai basins alongside evolving cathode chemistry shifts toward lithium iron phosphate and high-nickel formulations that alter carbonate-versus-hydroxide demand splits.
Market Dynamics
The zabuyelite market pivots on cathode chemistry transitions, where lithium iron phosphate formulations are reclaiming share from high-nickel alternatives and reshaping carbonate-versus-hydroxide procurement splits across cell manufacturing.
Growth Catalysts
- EU Battery Regulation:Mandates for carbon footprint declarations and recycled content thresholds are compelling European cell manufacturers to certify zabuyelite sourcing, creating premium tiers for low-carbon production.
- Functional beverage fortification:Lithium's regulatory acceptance in food-grade applications is opening pharmaceutical-grade purification demand from beverage formulators seeking mood-stabilization claims.
- Jiangxi processing corridor:Concentrated hard-rock refining infrastructure in this Chinese province enables rapid battery-grade carbonate conversion, shortening supply lead times for domestic cathode makers.
Market Restraints
- Atacama brine quotas:Chile's environmental regulator constrains extraction volumes, capping annual production growth regardless of price signals or contract demand.
- Solar evaporation dependency:Weather variability in salar operations creates 12-18 month production lags that prevent rapid supply response to demand spikes.
- Lithium hydroxide substitution:High-nickel cathode chemistries favor hydroxide precursors, displacing carbonate demand in premium automotive segments where energy density dominates.
Strategic Opportunities
- Direct shipping ore partnerships:Miner-to-cathode-maker contracts that bypass intermediate traders capture margin pools previously absorbed by commodity houses.
- Qinghai basin brine expansion:Underdeveloped Tibetan plateau salars offer untapped lithium concentrations with lower magnesium interference than Atacama sources.
- GB/T 11075 certification services:Third-party testing laboratories can monetize purity verification as China's SAMR tightens import disqualification thresholds.
Industry Challenges
- Battery-grade impurity control:Sodium, potassium, and calcium thresholds below 50 ppm require multi-stage crystallization that extends processing cycles and capital intensity.
- Dual chemistry qualification:Cathode makers must maintain parallel carbonate and hydroxide supply chains as LFP and NCM formulations oscillate in automotive design wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zabuyelite Market |
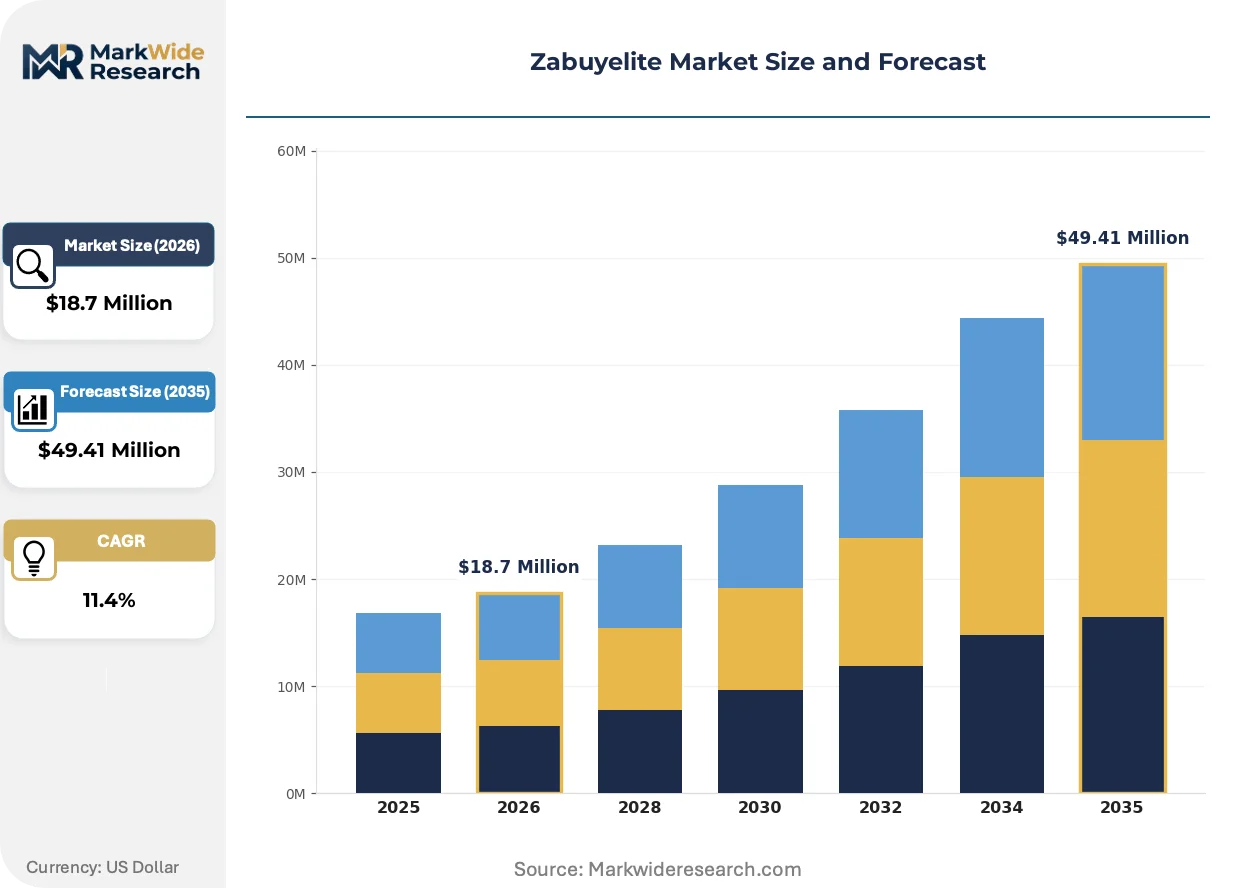
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Crystalline Application: Cosmetics, Pharmaceuticals, Agriculture, Food Industry End User: Manufacturers, Retailers, Distributors, Research Institutions Packaging Type: Bags, Drums, Bulk, Sachets |
| Companies Covered | Albemarle Corporation, FMC Corporation, SQM Sociedad Química y Minera de Chile SA, Jiangxi Ganfeng Lithium Co Ltd, Talison Lithium Ltd, Sichuan Tianqi Lithium Industries, Galaxy Resources Limited, Chemetall, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zabuyelite Market Emerging Trajectories
Process intensification and regulatory digitization are compressing traditional brine-to-battery timelines while fragmenting procurement models across spot, contract, and integrated supply structures.
Membrane electrodialysis for direct lithium extraction from brine is converging with continuous crystallization systems, eliminating solar evaporation ponds. Chinese equipment suppliers are deploying these units in Qinghai operations, cutting production cycles from 18 months to 30 days. This technology compression threatens Chilean cost advantages built on decades of evaporation infrastructure.
REACH substance registration requirements are forcing European importers to document full supply chain carbon intensity for zabuyelite consignments. The regulation mandates third-party verification of extraction energy sources, favoring brine-derived material over hard-rock alternatives with higher processing emissions. Cell manufacturers in Germany and Hungary are now requiring certificate-of-origin documentation for all carbonate feedstock.
Long-term offtake contracting with embedded price-adjustment mechanisms is displacing spot market liquidity for battery-grade material. Cathode makers in Japan and South Korea are locking five-year supply agreements with Chilean producers, securing volume priority but surrendering price upside. This behavior concentrates procurement power with integrated miners while squeezing independent traders from the value chain.
Zabuyelite Market Segmentation
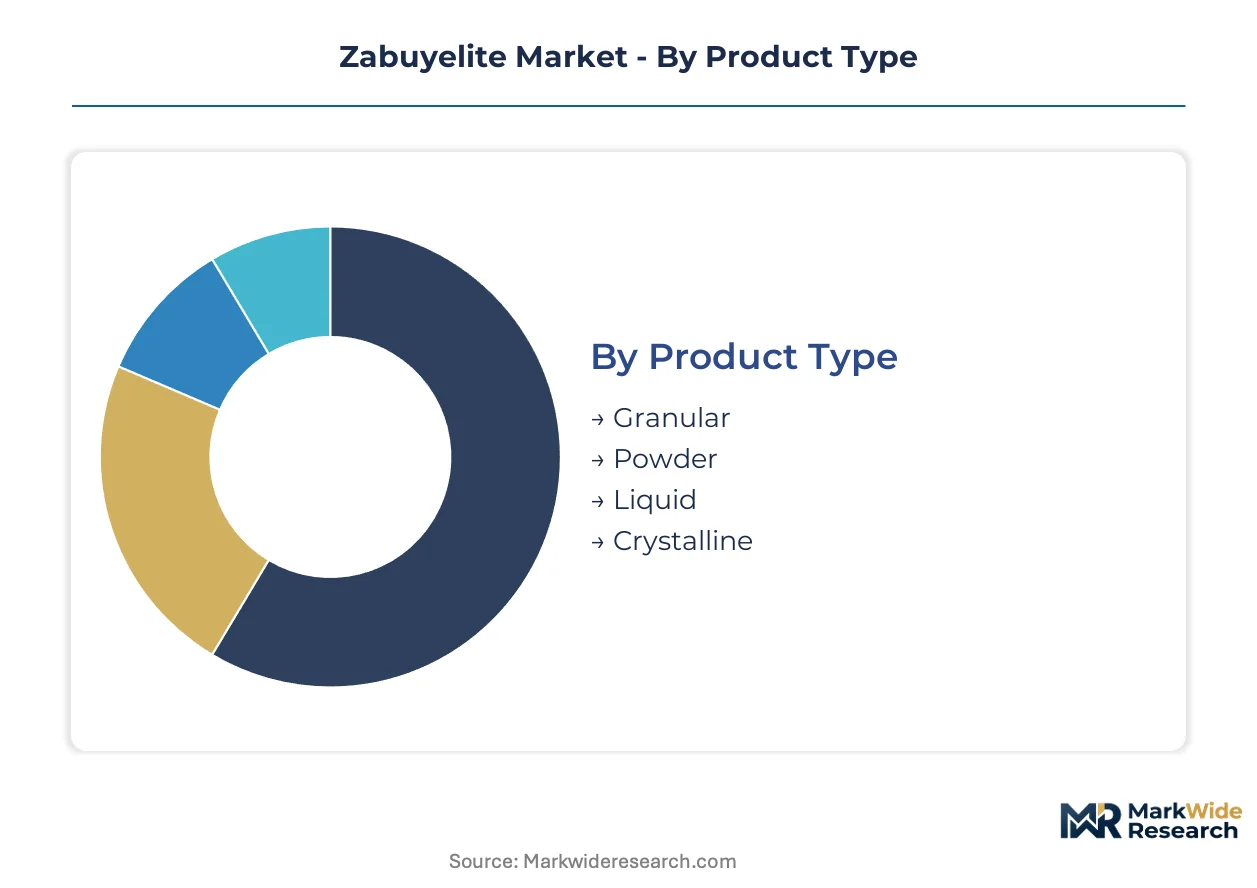
Zabuyelite procurement splits across physical form, application chemistry, and supply chain position determine pricing tiers and qualification requirements. Cathode makers impose distinct specifications by end-use, fragmenting what appears as a commodity into multiple certified grades.
Product Type:
Crystalline grades command specification premiums while powder and liquid forms serve cost-sensitive applications with looser purity tolerances.
- Crystalline:High-purity Li₂CO₃ with controlled crystal morphology meets battery-grade sodium thresholds below 50 ppm. Demand concentrates in Jiangxi province cathode plants where SAMR's GB/T 11075 certification is mandatory for cell supply contracts.
- Granular:Intermediate density spheres enable controlled dissolution rates in glass-ceramic flux applications. Specialty ceramic manufacturers in Germany and Japan specify this grade for thermal expansion matching in cooktop panels.
- Powder:Milled to sub-100 micron particle size for pharmaceutical tablet compression and rapid beverage fortification dispersion.
- Liquid:Aqueous suspensions eliminate dust exposure in food processing environments and enable precise dosing in continuous manufacturing lines.
Most installed capacity flows through Crystalline. Expansion is steepest in Granular as ceramic makers qualify new supply sources.
Application:
Regulatory acceptance varies sharply across end-uses, with food and pharmaceutical pathways requiring multi-year approval timelines that harden competitive moats.
- Pharmaceuticals:USP-grade zabuyelite for mood disorder therapeutics demands heavy metal testing below ICH Q3D thresholds. FDA inspection records show API manufacturers clustering supply qualification around three Chilean brine sources with documented impurity profiles.
- Food Industry:Lithium fortification in functional beverages requires FSSAI or FDA food additive petitions depending on target market jurisdiction. European formulators are advancing novel delivery systems for mineral water applications ahead of EFSA novel food approvals.
- Cosmetics:Technical-grade material serves skin conditioning formulations where lithium's osmotic properties are claimed in premium positioning.
- Agriculture:Soil amendment applications for lithium-deficient cropping regions remain experimental with limited commercial scale.
Pharmaceuticals absorb the highest unit margins. Food Industry volumes are climbing fastest as beverage brands launch positioning claims.
End User:
Procurement sophistication diverges between integrated manufacturers with in-house labs and intermediaries relying on supplier certificates.
- Manufacturers:Cathode material producers and glass-ceramic makers conduct incoming lot testing against internal specifications exceeding published standards. Direct contracts with Atacama operators eliminate trader margins.
- Research Institutions:Academic and government labs purchase gram-to-kilogram quantities for next-generation battery chemistry development, often requiring custom isotopic composition.
- Distributors:Regional chemical handlers stock technical grades for prompt delivery to mid-sized ceramic and pharmaceutical compounders.
- Retailers:E-commerce channels serve artisan glassmakers and hobbyist battery researchers with repackaged small lots.
Manufacturers channel the dominant volume share. Research Institutions are expanding procurement fastest as solid-state battery programs multiply.
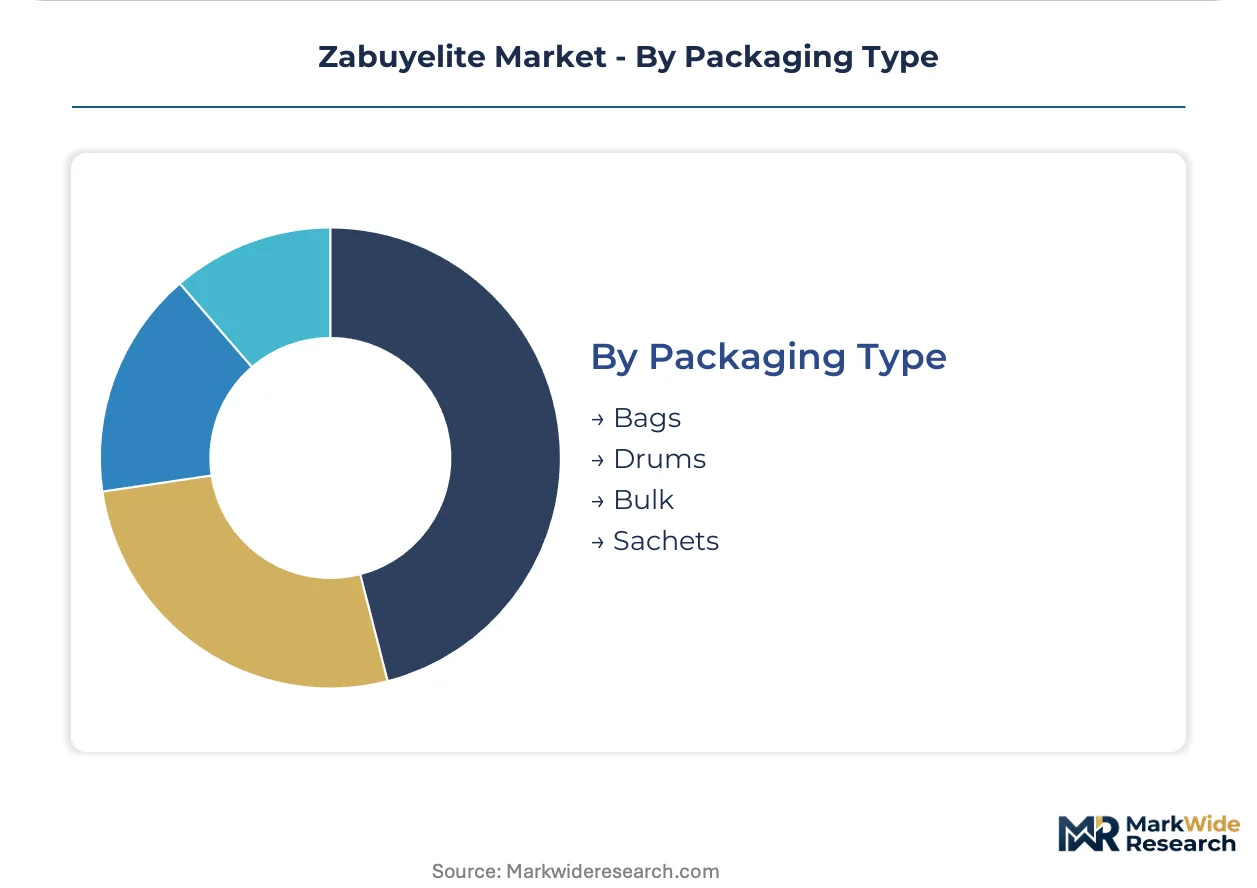
Packaging Type:
Handling requirements and contamination risk shape container selection across the value chain.
- Bulk:Pneumatic discharge from lined hopper trucks serves high-volume cathode plants with dedicated unloading infrastructure and positive-pressure cleanroom feeding systems.
- Drums:Steel or fiber containers with sealed liners protect hygroscopic powder during ocean freight from Chilean ports to Asian processing facilities.
- Bags:Multi-wall paper or woven polypropylene suits regional distribution to ceramic manufacturers with moderate consumption rates and standard warehouse conditions.
- Sachets:Foil-laminate single-use packets enable precise batching in pharmaceutical tableting and food production lines without weighing operations.
Bulk shipments dominate ocean freight lanes. Sachet demand is rising fastest in pharmaceutical contract manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean brine operations command cost advantages that Chinese hard-rock refiners struggle to replicate, while German automotive demand is reshaping European certification requirements.
Chile
Atacama salar extraction supplies the dominant share of battery-grade carbonate to Asian cathode makers. The country's environmental regulator imposes strict brine extraction quotas that cap annual production growth regardless of contract demand. Antofagasta region hosts the concentrated processing infrastructure where solar evaporation ponds feed direct shipping ore partnerships.
China
Jiangxi province's processing corridor enables rapid battery-grade carbonate conversion from hard-rock spodumene feedstock. SAMR enforces GB/T 11075 purity standards that disqualify lower-grade imports and mandate third-party certification. Qinghai basin brine operations in the Tibetan plateau are expanding membrane electrodialysis capacity to bypass traditional evaporation timelines.
Germany
Cell manufacturers in Lower Saxony and Baden-Württemberg are requiring certificate-of-origin documentation for all carbonate feedstock under REACH substance registration protocols. The EU Battery Regulation mandates carbon footprint declarations that favor low-carbon brine-derived material. BASF's Schwarzheide cathode plant exemplifies the procurement sophistication driving premium-tier qualification requirements.
United States
Albemarle Corporation leverages its Kings Mountain, North Carolina processing assets to serve domestic battery supply chains. FDA inspection records show API manufacturers clustering supply qualification around Chilean brine sources with documented impurity profiles. Nevada's Silver Peak operations represent the sole domestic brine extraction site, though output remains modest against Asian demand scale.
Australia
Greenbushes and Pilgangoora hard-rock deposits feed Chinese refiners through long-term offtake contracts with embedded price-adjustment mechanisms. The country's lithium concentrate exports bypass intermediate traders through direct shipping ore partnerships that capture margin pools. Western Australia's mining jurisdiction offers stable concession terms that contrast with Chilean quota uncertainty.
Zabuyelite Market Vendor Landscape
Top-tier vendors anchor integrated brine-to-carbonate production, while mid-tier processors rely on third-party feedstock arrangements. The competitive structure splits between Chilean brine operators with decades of evaporation infrastructure and Chinese hard-rock refiners with rapid processing cycles. Strategic archetypes include backward-integrated miners, pure-play refiners, and cathode-maker captive suppliers. Dominant competitive moves encompass direct shipping ore partnerships that eliminate trader margins and membrane electrodialysis technology licensing that compresses production timelines.
Among Chilean brine operators, SQM Sociedad Química y Minera de Chile SA and Albemarle Corporation exemplify the integrated extraction-to-refining archetype with Atacama-based cost structures. Jiangxi Ganfeng Lithium Co Ltd occupies a position representing Chinese hard-rock integration, spanning mining assets in Australia through refining capacity in Jiangxi province.
| Leading Market Players |
|---|
| Albemarle Corporation |
| FMC Corporation |
| SQM Sociedad Química y Minera de Chile SA |
| Jiangxi Ganfeng Lithium Co Ltd |
| Talison Lithium Ltd |
| Sichuan Tianqi Lithium Industries |
| Galaxy Resources Limited |
| Chemetall |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Membrane electrodialysis deployment in Qinghai basin operations compresses production cycles from 18 months to 30 days, simultaneously eroding Chilean cost advantages built on solar evaporation infrastructure and fragmenting pricing power across new technology adopters versus legacy pond operators.
Pricing Analysis
Capacity additions in China are reshaping price floors for battery-grade crystalline zabuyelite as membrane electrodialysis units bypass traditional evaporation timelines. Contract-based long-term offtake agreements with embedded price-adjustment mechanisms dominate procurement, with price differentiation driven by GB/T 11075 certification status and carbon footprint documentation under REACH protocols. Cost compression in technical-grade powder segments is intensifying because Jiangxi processors are converting hard-rock spodumene at scale. Spot market participants show highest price sensitivity; integrated cathode makers with direct shipping ore partnerships exhibit lowest sensitivity due to margin capture.
Supply Chain Analysis
Ocean freight rates from Chilean ports to Asian processing facilities constitute a material cost layer for drum-shipped crystalline grades, with bulk pneumatic discharge from hopper trucks commanding premium logistics infrastructure. Supply concentrates in Chile, China, and Australia; raw material flows draw from Atacama salar brines, Greenbushes hard-rock spodumene, and Qinghai plateau brines. Single-source vulnerability runs through Chilean brine quota constraints imposed by environmental regulators. Distribution runs through direct shipping ore partnerships that bypass intermediate commodity traders, concentrating procurement power with integrated miners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage between Chilean brine extraction quotas and Chinese membrane electrodialysis expansion creates geographic cost differentials that reward footprint diversification across both regulatory regimes.
For Market Incumbents: Extend membrane electrodialysis licensing agreements to Qinghai basin operators before technology diffusion erodes proprietary advantages. Secure backward integration into Australian hard-rock mining assets to hedge Chilean quota risk. Defend margin position by embedding carbon footprint verification services into long-term contracts, capturing premium tiers under EU Battery Regulation mandates.
For New Entrants and Emerging Players: Enter via pharmaceutical-grade purification services for functional beverage fortification, where FSSAI and FDA additive petition requirements create multi-year approval barriers for established competitors. Target food industry applications ahead of EFSA novel food decisions, leveraging third-party GB/T 11075 certification laboratories as a go-to-market anchor in Jiangxi province.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play refiners without captive brine or hard-rock feedstock. Long-term viability centers on technology licensing positions in direct lithium extraction and integrated cathode-maker captive supply structures. Watch membrane electrodialysis adoption rates in Qinghai as the inflection signal for Chilean cost advantage erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrodialysis Licensing | Qinghai basin deployments compress 18-month evaporation cycles to 30 days, threatening Chilean infrastructure advantages. |
| Direct Shipping Ore Partnerships | Miner-to-cathode contracts bypass trader margins and concentrate procurement power with integrated producers. |
| GB/T 11075 Certification Investment | SAMR-mandated purity verification creates service revenue pools for third-party testing laboratories. |
| Carbon Footprint Documentation | REACH and EU Battery Regulation protocols favor low-carbon brine material over hard-rock alternatives. |
| Qinghai Basin Brine Expansion | Tibetan plateau salars offer lithium concentrations with lower magnesium interference than Atacama sources. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cathode plant procurement managers, lithium brine extraction operators, pharmaceutical API manufacturers, and third-party certification laboratory directors with secondary validation against customs trade data, SEC 10-K filings from listed lithium producers, SAMR regulatory bulletins, and ECHA REACH substance registration databases. Bottom-up volume estimates from individual production facilities triangulated against top-down demand modeling from cathode chemistry forecasts.
Segment-weighting approaches applied differential growth assumptions across crystalline, granular, powder, and liquid product forms, with application splits modeled for pharmaceutical, food industry, battery cathode, and glass-ceramic end-uses. CAGRs were derived from regression analysis of historical offtake patterns against electric vehicle production forecasts and cathode chemistry transition timelines. Industry-specific inputs included brine extraction quota trajectories from Chilean environmental regulators and membrane electrodialysis deployment schedules in Qinghai basin operations.
Inputs from production facility disclosures and regulatory filings were available through the study window; gaps in real-time brine extraction volume reporting from Atacama operators introduce uncertainty bands around near-term supply estimates. Forecasts reflect assumptions regarding cathode chemistry market share evolution and regulatory implementation timelines for EU Battery Regulation carbon footprint mandates. A model refresh is warranted upon material change in Chilean brine concession renewal terms or breakthrough direct lithium extraction technology commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Feldspar Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Ceramic Matrix Composites Market
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Global Rice Husk Ash Market