
 Global Rice Husk Ash Market | 2026-2036
Global Rice Husk Ash Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rice Husk Ash Market Foresight
India's eastern rice belt is narrowing the gap between raw husk availability and commercial silica extraction capacity. Guru Metachem Pvt. Ltd. leverages its Gujarat-based processing infrastructure to dominate high-purity silica production for rubber reinforcement applications. Usher Agro Ltd. anchors its position through backward integration into rice milling, securing captive husk supply across Uttar Pradesh and Bihar. Yihai Kerry Investments Co., Ltd. competes on manufacturing scale, operating multi-site processing facilities that serve polymer manufacturers throughout East Asia.
Rice husk ash comprises amorphous silica with particle sizes typically below 100 microns and specific surface areas exceeding 25,000 m²/kg, produced through controlled combustion of rice husks at temperatures between 500°C and 700°C to preserve pozzolanic reactivity for concrete admixtures and ceramic glaze formulations. White rice husk ash commands premium positioning in the ceramic industry where low carbon content determines glaze transparency and thermal shock resistance. Grey rice husk ash occupies the volume tier in concrete admixtures, with construction companies prioritizing cost-adjusted performance over color consistency in structural applications.
India's BIS enforces IS 3812 Part 1 and Part 2 standards for fly ash and processed natural pozzolana, directly conditioning market access for ash suppliers targeting infrastructure contracts. China's SAMR administers GB standards for silica materials used in rubber compounding, creating compliance thresholds that filter export-oriented producers. ECHA's REACH registration requirements for silicon dioxide substances shape formulation decisions by European polymer manufacturers sourcing imported ash. Stakeholders must monitor evolving carbon border adjustment mechanisms and building code revisions that could recalibrate the cost advantage of rice husk ash against conventional silica sources.
Market Dynamics
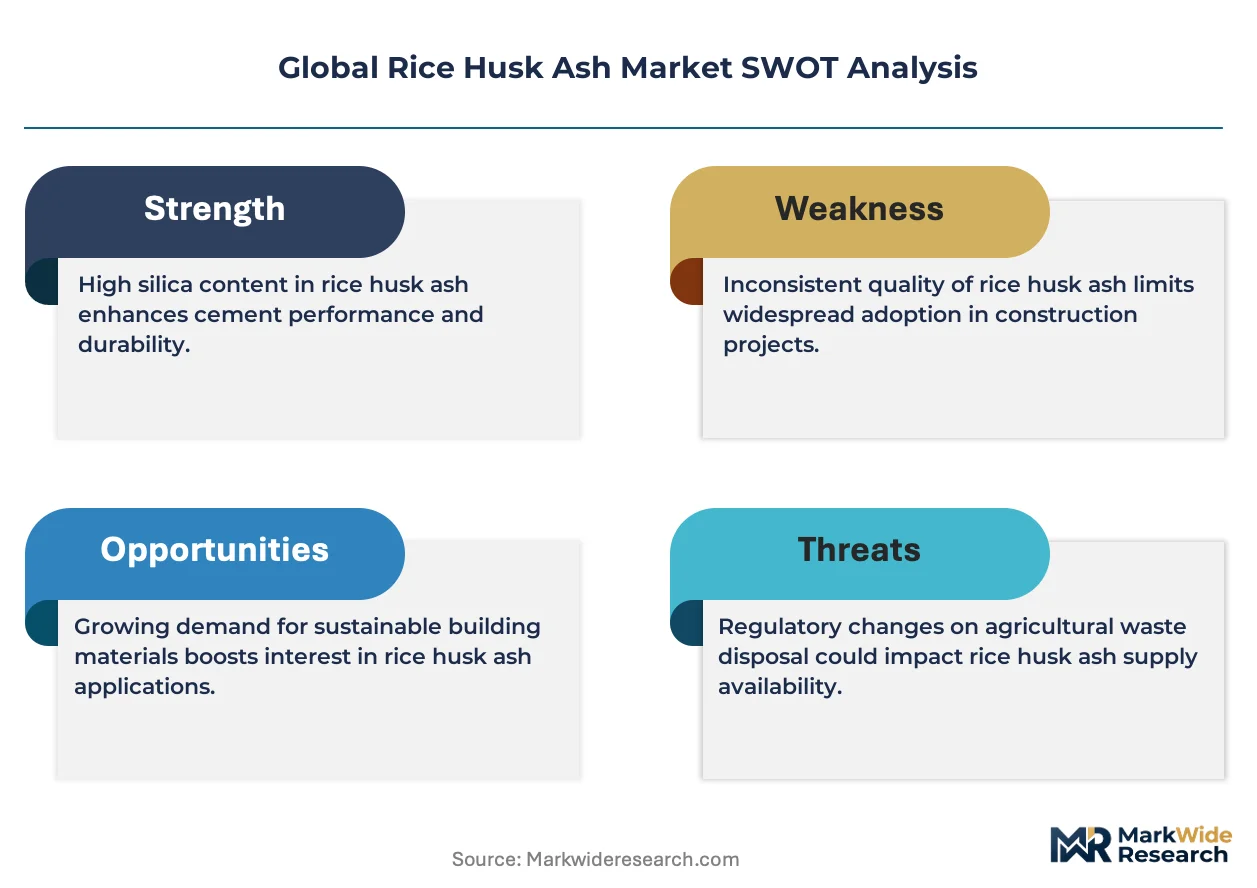
Construction sector decarbonization mandates are compressing the cost premium of rice husk ash against conventional silica sources, while India's BIS tightening of IS 3812 specifications is filtering substandard suppliers from infrastructure procurement channels.
Growth Catalysts
- India's IS 3812 Part 2 Standards:Revised pozzolanic material specifications are mandating higher reactivity thresholds for blended cements, disqualifying low-grade ash and concentrating procurement among certified processors serving national highway and dam projects.
- Vietnam's Mekong Delta Milling Clusters:Concentrated rice processing infrastructure generates captive feedstock for silica extraction facilities, reducing logistics costs for exporters serving polymer manufacturers throughout East Asia.
- Controlled Combustion Technology:Temperature management systems preserving amorphous silica structure at 500°C to 700°C are unlocking premium ceramic glaze applications previously served by synthetic silica sources.
Market Restraints
- Natural Gas Price Volatility:Combustion energy costs constitute a significant input for ash calcination operations, exposing processors to margin compression during European and Asian energy price spikes.
- Seasonal Husk Supply Concentration:Post-harvest availability windows in India's eastern rice belt create feedstock procurement bottlenecks for continuous-processing silica extraction plants.
- Fly Ash Substitution:Coal power plant byproducts compete directly in concrete admixture applications, often at lower delivered cost in markets with proximate thermal generation capacity.
Strategic Opportunities
- EU Carbon Border Adjustment Mechanism:Embodied carbon accounting for imported construction materials is creating preference for rice husk ash against energy-intensive precipitated silica in European polymer compounding.
- Rubber Reinforcement Applications:High-purity silica demand from tire manufacturers seeking sustainable alternatives to conventional fillers represents an underpenetrated specification tier for Southeast Asian processors.
- Direct-to-Blender Distribution:Bypassing traditional chemical distributor networks to supply ready-mix concrete producers is compressing channel margins and accelerating specification adoption in Vietnam's commercial construction sector.
Industry Challenges
- REACH Registration Complexity:European polymer manufacturers require comprehensive silicon dioxide substance dossiers, creating compliance timeline friction for export-oriented Indian and Vietnamese processors unfamiliar with ECHA data requirements.
- Quality Consistency Across Batches:Variability in rice husk carbon content and combustion uniformity demands continuous process monitoring investment that strains mid-scale processor capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rice Husk Ash Market |
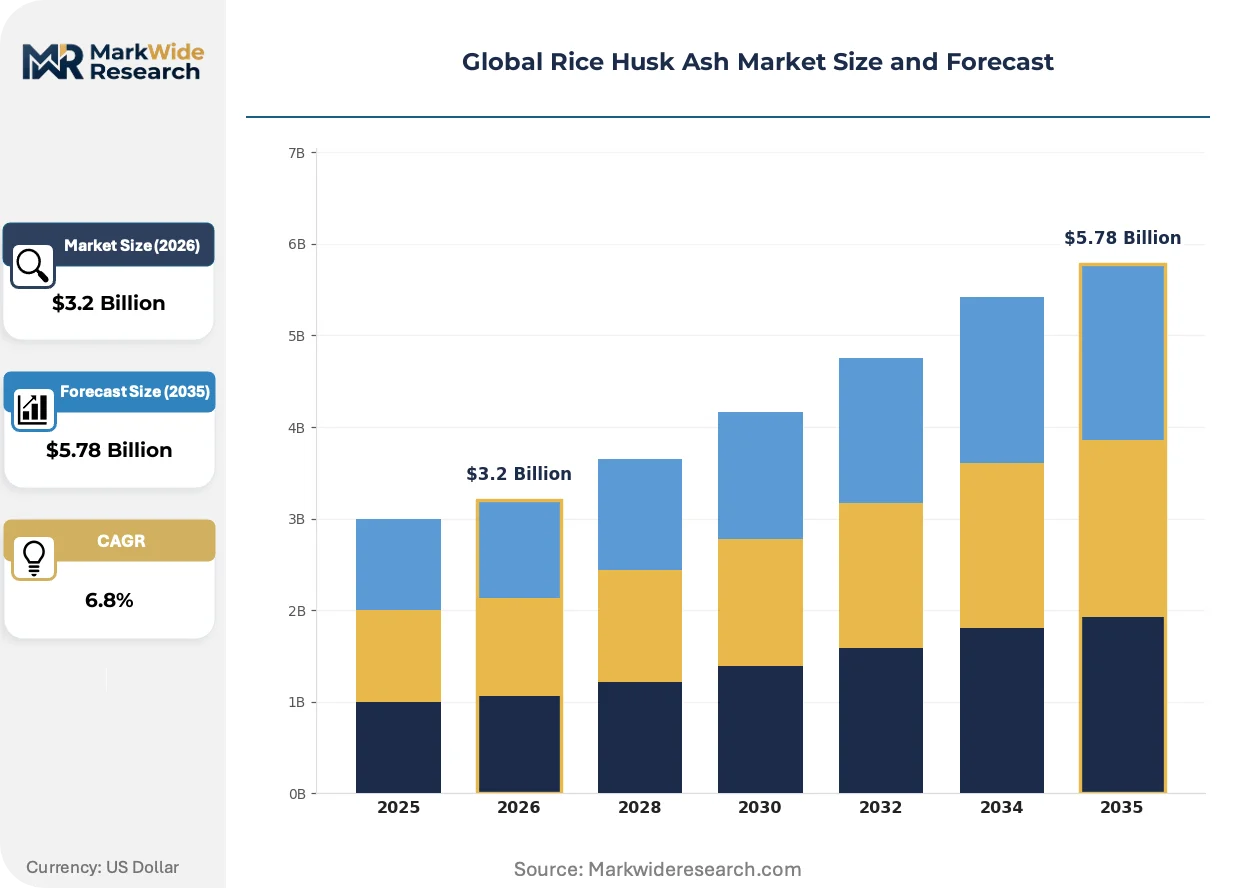
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice Husk Ash, Grey Rice Husk Ash, Black Rice Husk Ash, Activated Rice Husk Ash Application: Concrete Admixtures, Ceramic Industry, Soil Stabilization, Animal Feed, Rubber Reinforcement End User: Construction Companies, Ceramic Manufacturers, Agricultural Producers, Polymer Manufacturers Packaging Type: Bulk Bags, Paper Bags, Plastic Containers, Steel Drums, Loose Powder |
| Companies Covered | Guru Metachem Pvt. Ltd., Usher Agro Ltd., Yihai Kerry Investments Co., Ltd., Rescon India Pvt. Ltd., Astrra Chemicals, Jasoriya Rice Mill, KRBL Ltd., Agrilectric Power Partners, Kothari Petrochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rice Husk Ash Market Shifts & Advancements
Digital process control systems and sustainability-linked procurement specifications are converging to reshape competitive positioning across rice husk ash processing tiers, with certification becoming as consequential as unit economics in buyer selection.
Fluidized bed combustion technology with real-time temperature telemetry is virtualizing quality assurance protocols previously dependent on post-production laboratory testing. Ceramic manufacturers in Japan and South Korea are adopting this instrumentation to secure consistent glaze transparency from white ash shipments. The technology is compressing rejection rates and enabling just-in-time inventory models that reduce working capital requirements for importers.
China's SAMR administration of GB standards for silica materials in rubber compounding is tightening heavy metal and particle size distribution thresholds. Domestic tire manufacturers are responding by qualifying alternative Southeast Asian suppliers capable of demonstrating compliance documentation. The regulatory friction is accelerating investment in laboratory certification capacity among Vietnamese processors seeking export market access.
Construction procurement teams are consolidating admixture supplier relationships to reduce qualification overhead, favoring processors offering bundled technical service and carbon footprint verification. Ready-mix concrete producers in Thailand and Indonesia are replacing fragmented local sourcing with contracted supply agreements specifying monthly volume commitments and fixed pricing windows. The behavioral shift is concentrating volume among integrated processors with captive milling relationships and in-house logistics networks.
Global Rice Husk Ash Market Segmentation
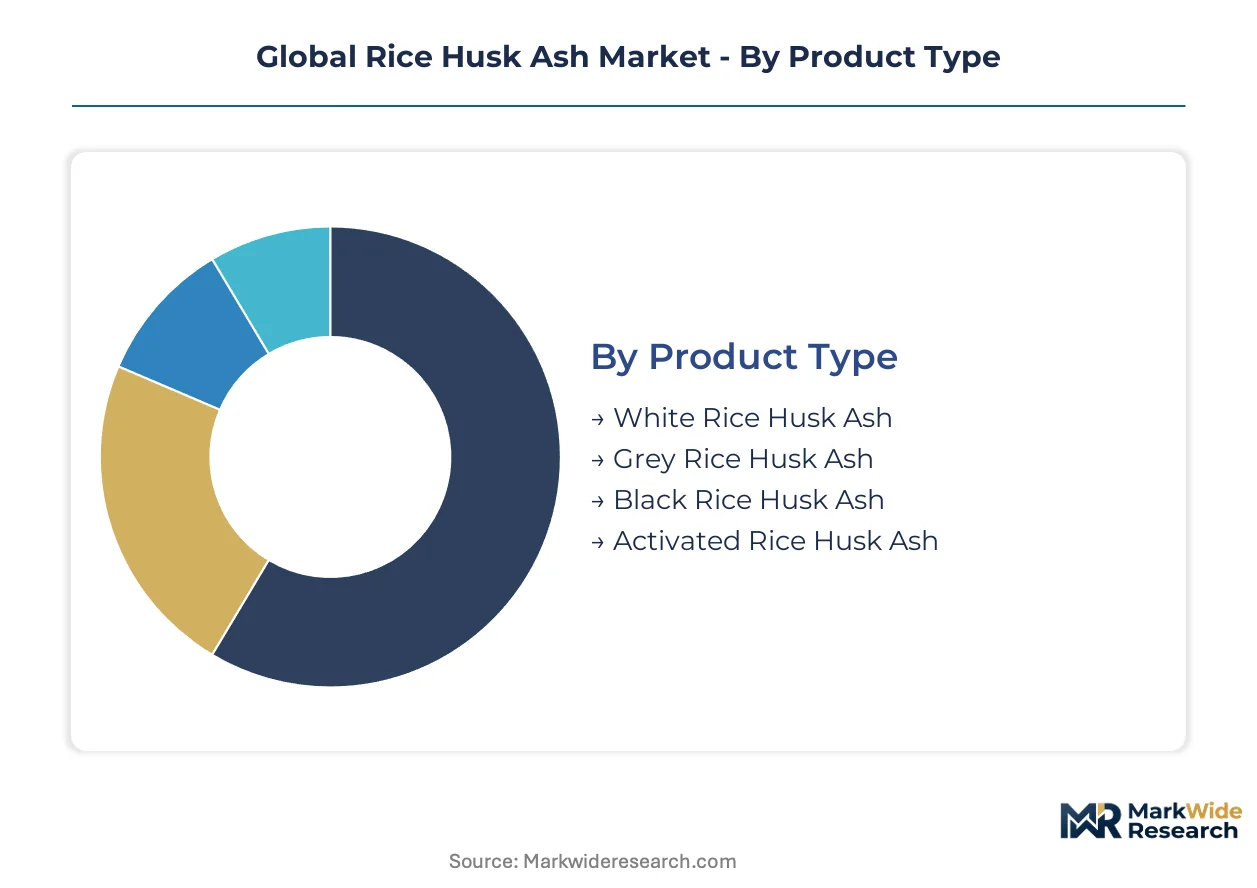
Rice husk ash exhibits pronounced specification divergence across combustion parameters and downstream processing intensity. Each segment tier commands distinct pricing premiums and regulatory compliance burdens that reshape procurement calculus for end-users.
Product Type:
Controlled combustion temperature and carbon retention differentiate performance tiers across ceramic, concrete, and polymer applications.
- White Rice Husk Ash:Complete carbon combustion below 700°C yields amorphous silica exceeding 90% purity with residual carbon under 2%. Ceramic glaze manufacturers in Japan and South Korea prioritize this grade for optical transparency and thermal shock resistance in high-temperature kiln applications.
- Grey Rice Husk Ash:Partial carbon retention produces silica content ranging 75-85% with visible grey coloration from residual organic matter. Construction contractors across Vietnam's commercial building sector absorb this grade as a cost-adjusted pozzolanic additive where color consistency carries no structural penalty.
- Black Rice Husk Ash:Higher carbon fractions from suboptimal combustion temperatures limit reactivity but find absorption applications in water treatment and activated carbon precursors.
- Activated Rice Husk Ash:Post-combustion acid washing and thermal activation elevate surface area metrics for specialty adsorbent markets serving environmental remediation contracts.
Established volume favors Grey Rice Husk Ash; emerging adoption favors White Rice Husk Ash.
Application:
End-use performance requirements stratify procurement specifications across infrastructure, manufacturing, and agricultural value chains.
- Concrete Admixtures:Pozzolanic reactivity thresholds defined by India's BIS IS 3812 standards govern infrastructure procurement. National highway and dam contractors in India specify certified ash to reduce clinker content and meet embodied carbon targets in government tenders.
- Ceramic Industry:Glaze formulation demands exacting particle size distribution below 45 microns and controlled iron oxide content. Japanese tableware manufacturers source white ash shipments through qualified Southeast Asian processors with laboratory certification capacity.
- Soil Stabilization:Agricultural extension services in India's eastern rice belt distribute bulk ash for pH correction and silicon bioavailability in rice cultivation.
- Animal Feed:Silica content supports digestive health in poultry and ruminant formulations, with feed mills prioritizing heavy metal screening compliance.
- Rubber Reinforcement:High-purity silica demand from tire manufacturers seeking sustainable filler alternatives is climbing the fastest among application tiers, with Vietnamese processors investing in SAMR GB standard compliance documentation for export qualification.
Concrete Admixtures anchor procurement volumes; Rubber Reinforcement is gaining share fastest on sustainability-linked specification shifts.
End User:
Buyer technical sophistication and certification requirements fragment channel economics across direct and distributor-mediated supply relationships.
- Construction Companies:Ready-mix concrete producers in Thailand and Indonesia are consolidating supplier relationships to reduce qualification overhead, favoring processors offering bundled technical service and carbon footprint verification.
- Ceramic Manufacturers:Japanese and South Korean glaze formulators demand batch consistency documentation and just-in-time delivery schedules that strain mid-scale processor logistics capacity.
- Agricultural Producers:State agricultural departments and cooperative societies in India procure bulk quantities through tender mechanisms with minimal specification stringency.
- Polymer Manufacturers:European tire compounders require REACH-registered silicon dioxide dossiers, creating compliance friction for export-oriented Indian and Vietnamese processors unfamiliar with ECHA data requirements.
Construction Companies concentrate procurement scale; Polymer Manufacturers impose the steepest certification barriers.
Packaging Type:
Logistics configuration and contamination risk shape packaging selection across export, domestic distribution, and on-site consumption models.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate export shipments from Vietnam's Mekong Delta processing clusters to East Asian polymer manufacturers, minimizing unit handling costs.
- Paper Bags:Twenty-five kilogram multi-wall paper sacks serve domestic construction supply chains in India where moisture protection requirements are moderate and disposal regulations favor recyclable materials.
- Plastic Containers:Sealed polyethylene drums preserve purity for high-grade ceramic and rubber applications susceptible to contamination during extended storage.
- Steel Drums:Robust containment for activated ash grades requiring hermetic sealing against atmospheric moisture in specialty chemical distribution.
- Loose Powder:Direct pneumatic discharge into silo systems serves integrated rice milling and ash processing facilities with captive consumption models.
Bulk Bags command export volume; Paper Bags retain domestic infrastructure share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS anchors the regulatory framework shaping procurement specifications across the dominant geography, with IS 3812 standards filtering supplier participation in infrastructure tenders. Construction decarbonization mandates in Vietnam and China are compressing cost premiums for pozzolanic materials against conventional cement additives.
India
National highway contractors and dam project developers drive certified ash procurement under tightened IS 3812 Part 2 reactivity thresholds. The Bureau of Indian Standards disqualifies low-grade suppliers from government infrastructure channels. Gujarat-based processing clusters serve rubber reinforcement applications through high-purity silica extraction infrastructure.
Vietnam
Polymer manufacturers throughout East Asia source silica from Mekong Delta milling clusters with concentrated feedstock availability. Post-harvest supply windows create procurement bottlenecks for continuous-processing extraction plants. Can Tho and An Giang provinces anchor export-oriented facilities serving ceramic glaze and tire compounding specifications.
China
SAMR-administered GB standards for rubber compounding materials tighten heavy metal and particle size thresholds for domestic tire manufacturers. Yihai Kerry Investments operates multi-site processing networks supplying polymer producers. Shandong and Jiangsu provinces concentrate manufacturing scale for sustainable filler alternatives.
Japan
Ceramic tableware manufacturers in Aichi and Gifu prefectures demand white ash batches with carbon content below 2% for optical transparency requirements. METI-industrial coordination supports fluidized bed combustion technology adoption for real-time quality telemetry. Just-in-time inventory models reduce working capital burdens for qualified Southeast Asian suppliers.
Germany
ECHA REACH registration requirements for silicon dioxide substances shape formulation decisions by polymer compounders sourcing imported ash. The EU Carbon Border Adjustment Mechanism creates preference for rice husk ash against energy-intensive precipitated silica. Industrial buyers in North Rhine-Westphalia consolidate supplier relationships to reduce qualification overhead.
Global Rice Husk Ash Market Competitive Landscape
Capability concentration sits with integrated processors commanding captive husk supply; scale advantage sits with multi-site operators serving diversified end-use portfolios. The vendor base stratifies across three tiers: backward-integrated rice millers securing raw material access, specialized silica extractors targeting premium ceramic and rubber applications, and regional distributors aggregating construction-grade volumes. Dominant competitive moves include laboratory certification capacity investment for export market access and direct-to-blender distribution bypassing traditional chemical channels.
Among India-based processors, Guru Metachem Pvt. Ltd. and Usher Agro Ltd. exemplify contrasting integration strategies—Gujarat-based chemical specialization against Uttar Pradesh-Bihar milling consolidation. Yihai Kerry Investments Co., Ltd. represents the scale-driven archetype with East Asian multi-site manufacturing networks. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Guru Metachem Pvt. Ltd. |
| Usher Agro Ltd. |
| Yihai Kerry Investments Co., Ltd. |
| Rescon India Pvt. Ltd. |
| Astrra Chemicals |
| Jasoriya Rice Mill |
| KRBL Ltd. |
| Agrilectric Power Partners |
| Kothari Petrochemicals |
| Others |
Supply & Pricing Matrix
Mekong Delta rice milling clusters in Vietnam anchor feedstock concentration for silica extraction, concentrating margin capture among processors with captive husk supply and multi-site logistics networks serving East Asian polymer manufacturers.
Pricing Analysis
Geographic price spreads between Vietnam's export-grade white ash and India's domestic grey ash tiers reflect combustion technology investment and certification documentation burdens. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-grade white ash with sub-2% carbon content from construction-grade grey ash and untreated black ash absorption materials. Cost compression in standard-tier concrete admixtures is intensifying because fly ash substitution erodes price positioning in markets with proximate thermal generation. Construction contractors in Vietnam's commercial building sector exhibit highest price sensitivity, while Japanese ceramic manufacturers absorb premium positioning for optical transparency guarantees.
Supply Chain Analysis
Contract manufacturing concentration among Vietnamese processors with fluidized bed combustion technology and Indian integrated rice millers with in-house calcination capacity shapes available supply. Raw material flows draw from rice milling clusters in Vietnam's Mekong Delta, India's eastern rice belt, and Thailand's Central Plains, with silica extraction feeds from controlled combustion at 500°C to 700°C and post-combustion acid washing for activated grades. Single-source vulnerability concentrates in seasonal husk availability windows that disrupt continuous-processing plants. Distribution runs through direct-to-blender agreements with ready-mix concrete producers and bulk bag export shipments to East Asian polymer manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward construction procurement teams consolidating admixture supplier relationships to reduce qualification overhead, fragmenting volume among fewer integrated processors with captive milling access and carbon footprint verification.
For Market Incumbents: Harden laboratory certification capacity for ECHA REACH registration and SAMR GB standard compliance to defend export market access against emerging Vietnamese processors. Deepen backward integration into rice milling operations across Uttar Pradesh and Bihar to secure captive husk supply against seasonal procurement bottlenecks. Channel control through direct-to-blender distribution bypasses margin-stripping chemical distributors in Thailand's ready-mix concrete sector. For New Entrants and Emerging Players: Build out rubber reinforcement silica extraction capacity targeting tire manufacturers seeking sustainable filler alternatives, the fastest-climbing specification tier among application segments. Penetrate Vietnam's Mekong Delta processing gap through tolling arrangements with established milling clusters before committing fixed capital. Qualify through SAMR GB standard documentation for export access to Chinese polymer compounders tightening heavy metal thresholds. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated processors with captive milling relationships and in-house logistics networks spanning multiple rice belt geographies. Long-term viability hinges on carbon border adjustment mechanism positioning as embodied carbon accounting reshapes European construction procurement. Monitor BIS IS 3812 specification revisions as inflection signals for infrastructure contract qualification barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Milling | Captive husk supply secures feedstock access across India's seasonal availability windows. |
| Laboratory Certification Capacity Investment | ECHA REACH dossier preparation unlocks European polymer manufacturer procurement channels. |
| Fluidized Bed Combustion Technology Deployment | Real-time temperature telemetry reduces rejection rates for Japanese ceramic glaze shipments. |
| Direct-to-Blender Distribution Expansion | Bypassing chemical distributors compresses channel margins in Vietnam's commercial construction sector. |
| SAMR GB Standard Compliance Documentation | Heavy metal and particle size certification qualifies Southeast Asian processors for Chinese tire manufacturing. |
Research Methodology
Cross-validation between primary interviews with rice mill operations managers, silica extraction plant engineers, construction procurement leads, and polymer compounder technical directors and secondary validation through BIS certification records, SAMR GB standard filings, and customs trade data anchors the qualitative findings. Bottom-up capacity assessments across Vietnam's Mekong Delta and India's Gujarat processing clusters were triangulated against top-down demand estimates from concrete admixture consumption and rubber reinforcement silica offtake.
Calibration against historical price spreads between white and grey ash tiers and verified installation rates of fluidized bed combustion technology shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include combustion grade tier, end-use application, buyer certification requirements, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand curves incorporating construction sector decarbonization mandates and tire manufacturer sustainability specifications.
Stress conditions across natural gas price volatility, seasonal husk supply concentration, and fly ash substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding BIS specification stability and carbon border adjustment mechanism implementation timing. Quarterly review of infrastructure tender award flows and SAMR standard revision announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Feldspar Market
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Ceramic Matrix Composites Market