
 Silicon Carbide Fiber Market | 2026-2036
Silicon Carbide Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Carbide Fiber Market Outlook
AS9100 aerospace quality certification is redrawing competitive boundaries for commercial supply eligibility. NGS Advanced Fibers Co., Ltd. leverages its precursor technology heritage to anchor capacity in Japan. SGL Carbon sustains European market presence through specialized carbon-silicon carbide hybrid architectures. UBE Corporation dominates chemical vapor deposition feedstock supply for Japanese domestic producers.
Silicon carbide fiber consists of polycrystalline beta-SiC filaments with diameters typically ranging from 10-15 micrometers, manufactured through pyrolysis of organosilicon polymers or chemical vapor deposition onto tungsten or carbon cores, engineered to withstand sustained temperatures exceeding 1,000°C in oxidizing environments. Continuous fiber commands premium positioning due to aerospace qualification timelines and structural load-bearing requirements. Composite materials represent the fastest-growing application format as original equipment manufacturers consolidate part counts through integrated ceramic matrix composite assemblies. CVD technology maintains margin concentration among qualified suppliers despite higher capital intensity versus melt spinning alternatives.
FAA airworthiness directives and EPA emissions regulations jointly determine material qualification pathways and commercial adoption velocity for SiC fiber-reinforced components. EASA certification reciprocity shapes transatlantic supply chain configurations for European aerospace tier suppliers. Stakeholders must monitor qualification backlog durations at national aviation authorities as production scale-up outpaces certification throughput capacity.
Market Dynamics
Aerospace engine manufacturers are consolidating hot-section component designs around ceramic matrix composites, compressing qualification timelines and forcing feedstock suppliers to synchronize capacity expansion with FAA airworthiness certification throughput.
Growth Catalysts
- EPA emissions standards:Tighter NOx and CO2 limits on commercial aviation propulsion systems are mandating material substitution toward SiC-reinforced ceramic matrix composites in combustor liners and turbine shrouds.
- Chemical vapor deposition advances:Improved CVD reactor throughput and precursor efficiency are reducing fiber production costs and expanding qualified supplier pools for aerospace tier-1 procurement.
- South Carolina manufacturing corridor:Concentrated aerospace OEM final assembly and engine production around Charleston and Greenville is creating localized demand pull for continuous SiC fiber qualification programs.
Market Restraints
- Organosilicon polymer precursor concentration:Japanese chemical conglomerates control pyrolysis-grade polycarbosilane supply, exposing non-integrated fiber producers to feedstock allocation risk and currency-driven cost volatility.
- Tungsten core scarcity:CVD fiber production depends on drawn tungsten filament availability from limited specialty metal wire suppliers, creating single-source vulnerability for high-temperature fiber architectures.
- AS9100 certification backlog:Aerospace quality system accreditation timelines at registrar bodies are extending 14-18 months, delaying commercial supply eligibility for emerging fiber producers regardless of technical qualification.
Strategic Opportunities
- Hypersonic vehicle thermal protection:Defense contractor programs in the United States and Australia are specifying SiC fiber-reinforced CMC leading edges for sustained Mach 5+ flight envelopes, opening non-aerospace volume channels.
- Nuclear reactor cladding substitution:Accident-tolerant fuel programs at the Department of Energy are qualifying SiC/SiC composites for light water reactor fuel rod applications, creating regulatory-driven demand outside traditional markets.
- Direct digital manufacturing integration:Binder jet and selective laser sintering of SiC fiber preforms is enabling near-net-shape CMC component production, compressing lead times for complex aerospace geometries.
Industry Challenges
- Pyrolysis engineering talent scarcity:Experienced organosilicon polymer chemists and high-temperature furnace operators are concentrated at established Japanese and American producers, constraining workforce expansion at new market entrants.
- Multi-scale defect detection:Non-destructive evaluation of continuous fiber tow integrity across kilometer-length spools requires specialized ultrasonic and X-ray computed tomography infrastructure that exceeds mid-capitalization producer budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Carbide Fiber Market |
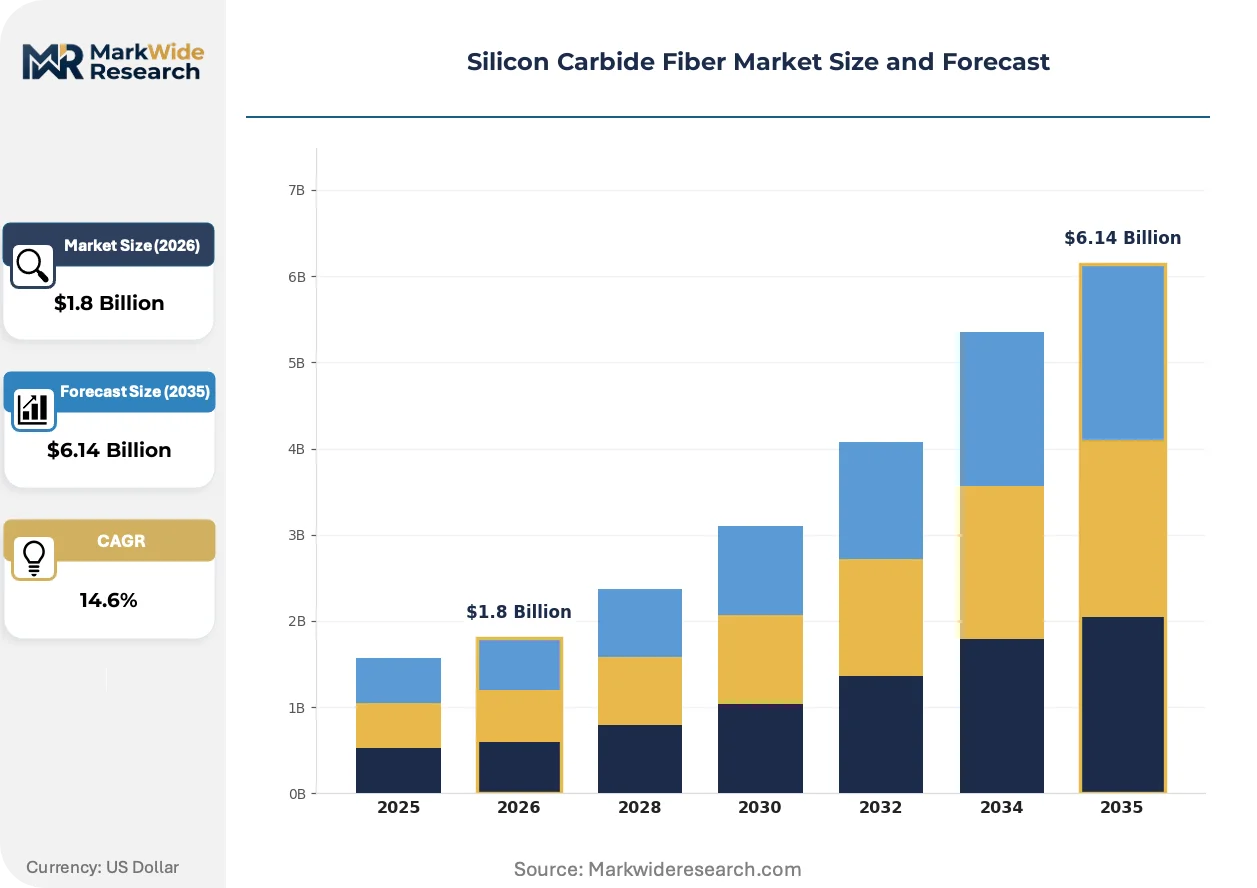
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiber, Textiles, Composite Materials, Reinforced Parts End Use Industry: Aerospace, Automotive, Electronics, Industrial Technology: CVD, Pulping, Melt Spinning, Laser Processing Distribution Channel: Direct Sales, Online Sales, Distributors, Resellers |
| Companies Covered | CeramTec, NGS Advanced Fibers Co., Ltd., SGL Carbon, Nippon Carbon Co., Ltd., UBE Corporation, Toyobo Co., Ltd., 3M, GE Aerospace, U.S. Specialty Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Carbide Fiber Market Strategic Shifts
Material qualification protocols and manufacturing process architectures are converging around digital thread traceability, compressing the gap between laboratory fiber development and production-scale aerospace release.
Third-generation SiC fiber with reduced oxygen content and enhanced creep resistance is miniaturizing the performance gap between laboratory demonstrators and production-representative material allowables. Pratt & Whitney and GE Aviation are accelerating insertion of these fibers into low-pressure turbine blade and vane applications. The technology is miniaturizing the historical 7-10 year qualification cycle for new CMC components into 4-6 year programs through physics-based modeling and accelerated testing protocols.
REACH authorization requirements for persistent organic pollutants are restricting certain organometallic precursor chemistries used in legacy SiC fiber production. European fiber producers are reformulating polycarbosilane synthesis routes to eliminate restricted substances ahead of 2026 sunset dates. German and French aerospace tier suppliers are prioritizing feedstock sources with pre-validated REACH compliance to avoid supply interruption during reauthorization transitions.
Original equipment manufacturers are consolidating multi-year fiber supply agreements into performance-guaranteed procurement frameworks that transfer yield risk to producers. Long-term offtake contracts with minimum volume commitments are displacing spot market purchasing for continuous fiber grades. This concentration is most visible in United States aerospace corridors, where engine manufacturers are locking precursor-to-fiber capacity at qualified suppliers through 2030.
Silicon Carbide Fiber Market Segmentation
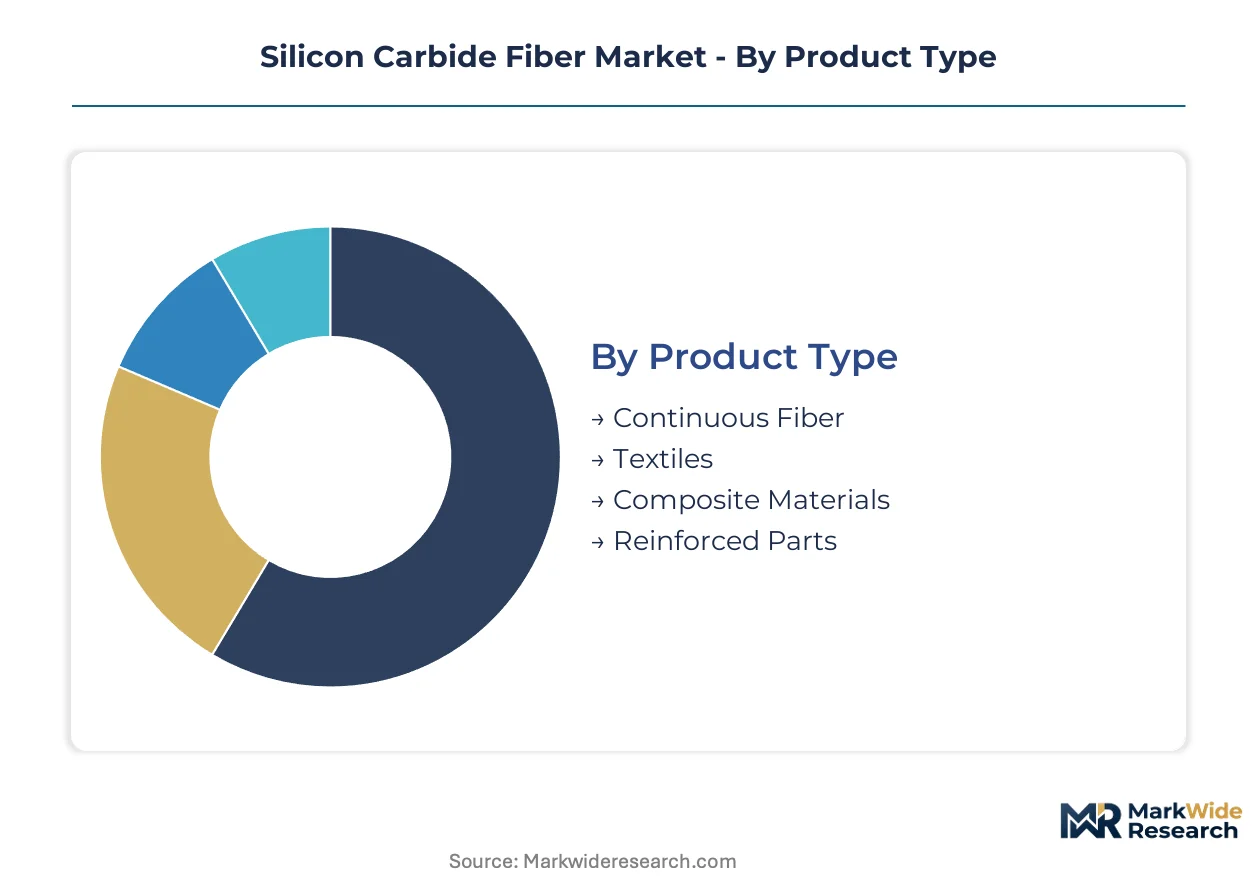
Segmentation in the silicon carbide fiber market reveals how qualification barriers and manufacturing complexity concentrate value capture. Product form and end-use specifications determine pricing power, while technology choices lock producers into capital-intensive process architectures with decade-long amortization horizons.
Product Type:
Continuous fiber faces intensifying substitution pressure from chopped and milled alternatives in non-aerospace thermal management applications, though structural load requirements defend its position in engine components.
- Continuous Fiber:Polycrystalline beta-SiC filaments manufactured via pyrolysis or CVD, qualified for sustained loads above 1,000°C. Demand concentrates in South Carolina and Ohio aerospace corridors where GE Aviation and Pratt & Whitney consolidate CMC procurement for turbine shrouds and combustor liners.
- Composite Materials:SiC fiber-reinforced ceramic matrix composites integrating fiber, interface coatings, and matrix in consolidated assemblies. Original equipment manufacturers compress part counts through integrated CMC designs, accelerating volume pull from tier-1 engine suppliers.
- Textiles:Woven and braided fiber architectures for thermal protection systems and flexible insulation.
- Reinforced Parts:Near-net-shape components for industrial furnace fixtures and semiconductor processing equipment.
Continuous fiber retains volume leadership; composite materials hold the steepest expansion curve.
End Use Industry:
Cost tier stratification separates qualification-heavy aerospace demand from price-sensitive industrial applications, with automotive and electronics occupying intermediate positions where performance premiums must justify unit economics.
- Aerospace:Hot-section engine components including low-pressure turbine blades, shrouds, and combustor liners where FAA airworthiness certification mandates material traceability. EPA emissions standards tighten NOx limits, accelerating SiC-reinforced CMC insertion timelines.
- Industrial:High-temperature furnace insulation, kiln furniture, and heat treatment fixtures where ceramic fiber blankets face displacement. Demand clusters around German and Japanese industrial equipment manufacturers seeking extended service life in oxidizing atmospheres.
- Automotive:Brake discs and exhaust components for high-performance vehicles.
- Electronics:Substrates and heat spreaders for power semiconductor packaging.
Aerospace commands margin concentration; industrial applications scale most broadly across geographies.
Technology:
Supply concentration in precursor chemicals and specialized reactor equipment creates asymmetric margin capture, with CVD-qualified producers extracting premiums while melt spinning alternatives compete on throughput.
- CVD:Chemical vapor deposition onto tungsten or carbon cores produces highest-temperature fiber grades with controlled stoichiometry. Japanese domestic producers depend on UBE Corporation for feedstock supply, creating vertical dependency chains.
- Melt Spinning:Direct drawing of organosilicon polymers offers lower capital intensity but reduced temperature capability. Emerging producers target this route to bypass CVD qualification backlogs at aerospace tier suppliers.
- Pulping:Short-fiber production for refractory and friction applications.
- Laser Processing:Surface modification and precision machining of consolidated fiber architectures.
CVD maintains qualification moats; melt spinning gains share fastest in industrial-grade supply.
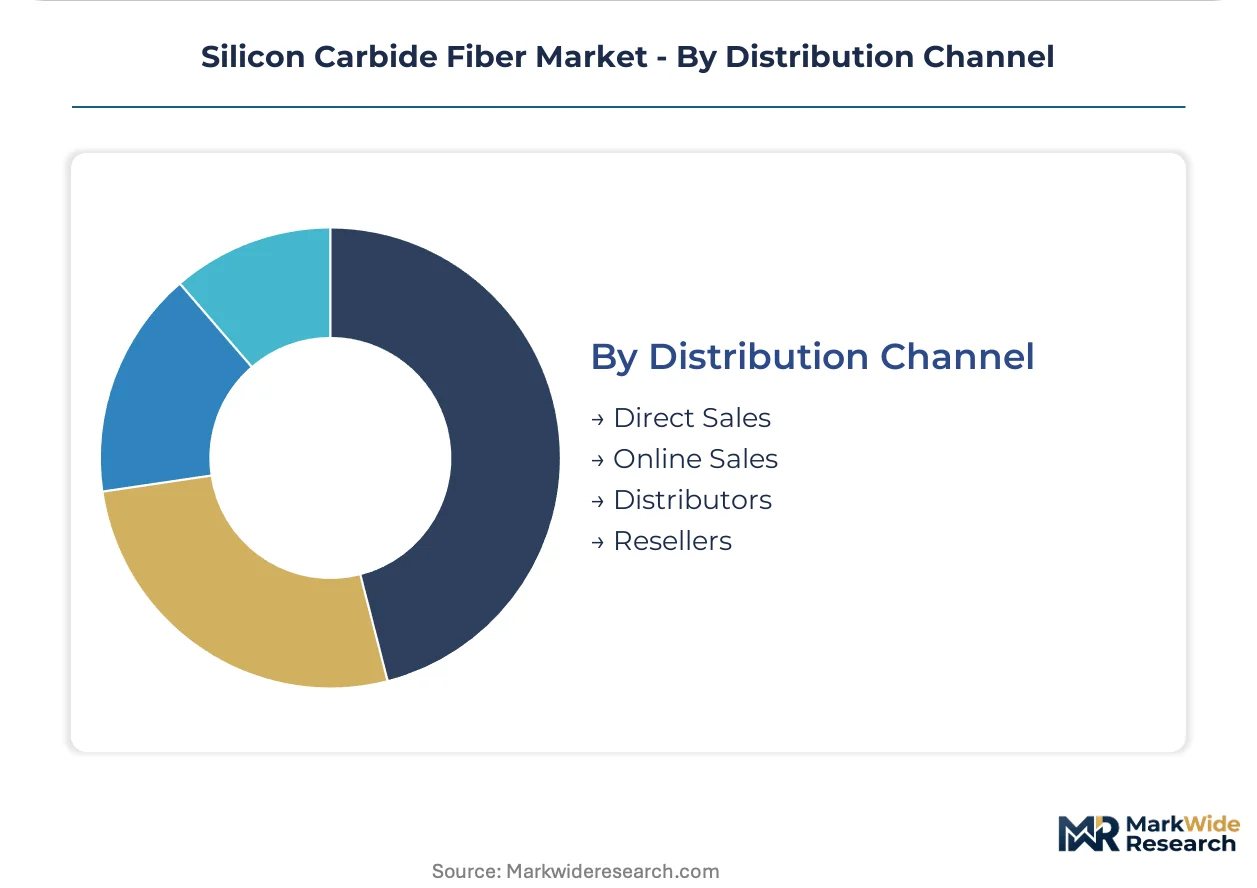
Distribution Channel:
Customer type segmentation separates long-term offtake agreements with engine OEMs from transactional purchasing in industrial maintenance markets, with channel strategy determining working capital intensity and forecast visibility.
- Direct Sales:Multi-year performance-guaranteed contracts transferring yield risk to fiber producers. United States aerospace manufacturers lock precursor-to-fiber capacity through 2030, eliminating spot market exposure for continuous fiber grades.
- Distributors:Inventory positioning for industrial and electronics customers requiring rapid fulfillment of standard fiber specifications.
- Online Sales:Catalog purchasing for research quantities and prototype development.
- Resellers:Regional agents for non-qualified fiber grades in emerging market geographies.
Direct sales anchor revenue stability; distributors expand geographic reach most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production tax credits and national security procurement programs are redrawing geographic investment patterns for SiC fiber capacity. Engine OEM final assembly locations and defense contractor hypersonic programs determine regional demand intensity.
United States
FAA airworthiness certification timelines and EPA emissions mandates compress material qualification schedules for domestic aerospace tier suppliers. Department of Defense hypersonic vehicle programs at prime contractors accelerate thermal protection system procurement. South Carolina's aerospace corridor around Charleston and Greenville concentrates CMC component manufacturing and fiber qualification activity.
Japan
Organosilicon polymer precursor chemistry expertise and CVD reactor engineering capabilities anchor domestic fiber production. METI industrial technology grants support next-generation fiber development with reduced oxygen content. Domestic producers cluster around Ube and Tokyo metropolitan areas, leveraging UBE Corporation feedstock supply chains.
Germany
REACH authorization deadlines for persistent organic pollutants force precursor chemistry reformulation at European fiber producers. EASA certification reciprocity with FAA shapes transatlantic supply chain configurations for aerospace tier suppliers. Carbon-silicon carbide hybrid architectures from specialized producers serve industrial furnace and automotive brake applications.
China
MIIT industrial policy targets ceramic matrix composite self-sufficiency for domestic commercial aviation programs. GB standards development for high-temperature fiber testing proceeds in parallel with C919 engine qualification timelines. Yangtze River Delta industrial zones host emerging fiber producers targeting melt spinning process scale-up.
United Kingdom
Defense procurement frameworks for next-generation combat aircraft specify SiC-reinforced CMC hot-section components. UK Research and Innovation funding supports university-industry partnerships for fiber interface coating development. Midlands aerospace cluster around Birmingham maintains legacy CMC testing and qualification infrastructure.
Silicon Carbide Fiber Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive precursor supply and specialized carbon-ceramic hybrid producers. Market structure concentrates around Japanese and American entities with decade-long aerospace qualification histories. Two strategic archetypes dominate: vertically integrated polymer-to-fiber producers controlling pyrolysis chemistry, and CVD-qualified specialists extracting premiums through tungsten-core fiber architectures. Competitive moves center on multi-year offtake agreements transferring yield risk to producers, and capacity expansion synchronized with FAA certification throughput.
Within the integrated chemical conglomerate tier, NGS Advanced Fibers Co., Ltd. and UBE Corporation exemplify precursor-to-fiber control strategies. SGL Carbon occupies a position among European specialists in carbon-silicon carbide hybrid architectures. These entities represent contrasting geographic and technological positioning approaches without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| CeramTec |
| NGS Advanced Fibers Co., Ltd. |
| SGL Carbon |
| Nippon Carbon Co., Ltd. |
| UBE Corporation |
| Toyobo Co., Ltd. |
| 3M |
| GE Aerospace |
| U.S. Specialty Materials |
| Others |
Value Chain & Pricing Dynamics
Polycarbosilane precursor substitution for legacy petroleum-based feedstocks is redrawing supply geography toward Japanese chemical conglomerates while compressing margin structures for non-integrated fiber producers. This feedstock transition simultaneously concentrates pricing power upstream and exposes downstream converters to yen-denominated cost volatility.
Pricing Analysis
Cost-plus contracts with polycarbosilane feedstock indexation dominate procurement frameworks between Japanese precursor suppliers and CVD fiber producers. Price differentiation rests on AS9100 aerospace certification tier and continuous fiber qualification status versus industrial-grade chopped alternatives. Pricing pressure stems from melt spinning process scale-up by emerging Chinese producers targeting non-aerospace thermal management segments. Industrial furnace insulation buyers exhibit highest price sensitivity, while FAA-qualified engine OEMs accept substantial premiums for traceable continuous fiber supply.
Supply Chain Analysis
Tungsten filament supply from limited specialty wire producers in Austria and China constitutes a critical chokepoint for CVD fiber manufacturing. Feedstock sourcing concentrates in Japan, China, and the United States, with organosilicon polymer chemistry anchored in Ube and Tokyo metropolitan production clusters. Supply chain risk centers on single-source tungsten core vulnerability and REACH authorization transitions for legacy precursor chemistries. Distribution runs through direct long-term offtake agreements with aerospace tier suppliers, supplemented by distributor inventory positioning for industrial maintenance markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
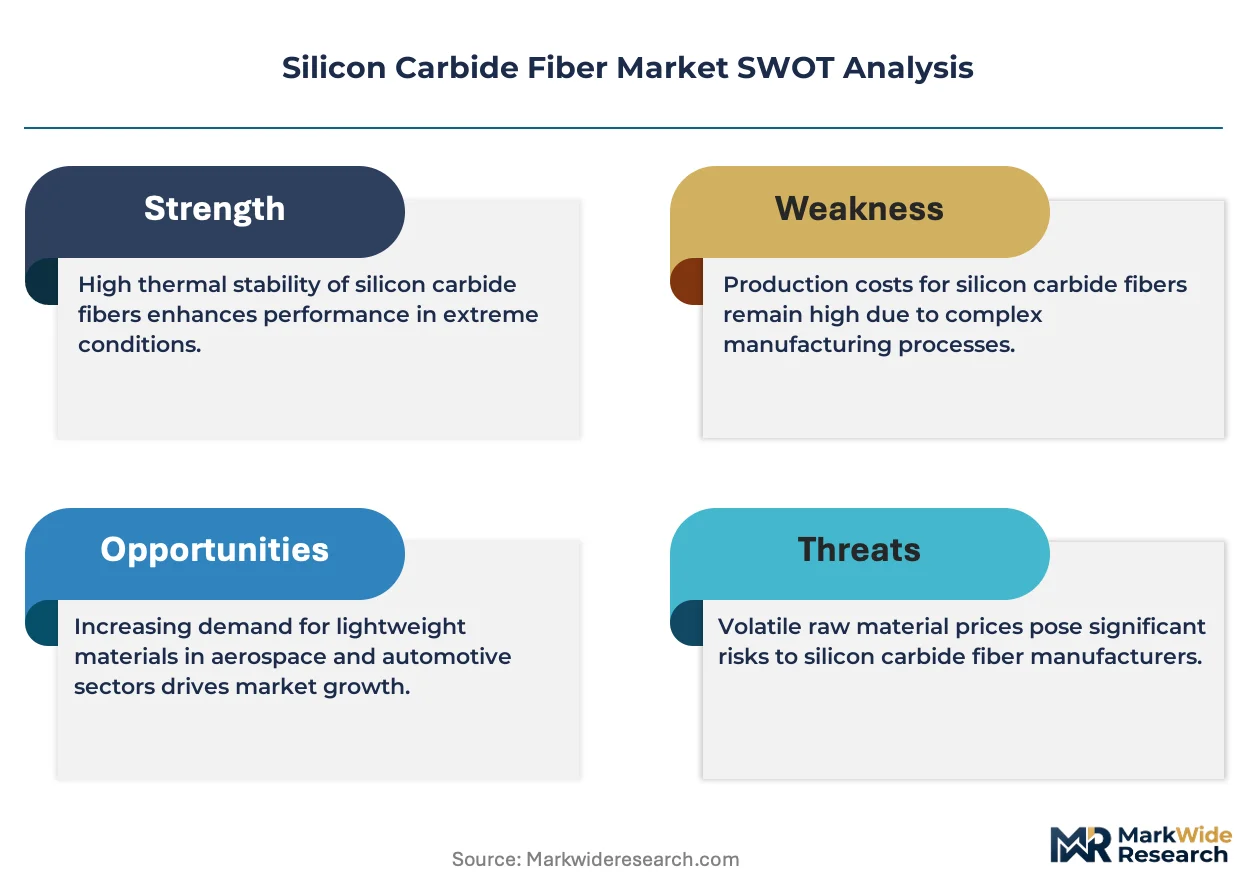
The silicon carbide fiber market faces substitution defense imperatives against oxide fiber alternatives and carbon-carbon composites in thermal protection applications. Incumbents must navigate this threat through structural consolidation of qualification moats.
For Market Incumbents: Consolidate backward integration into polycarbosilane precursor production to neutralize feedstock allocation risk from Japanese chemical conglomerates. Lock multi-year performance-guaranteed contracts with South Carolina and Ohio aerospace corridors through 2030, transferring yield risk while securing capacity utilization against melt spinning entrants.
For New Entrants and Emerging Players: Differentiate on hypersonic vehicle thermal protection specifications outside FAA certification backlogs, targeting defense contractor programs in Australia and the United States. Prioritize melt spinning process scale-up for industrial furnace insulation segments where AS9100 qualification barriers do not apply, using cost-positioning to displace ceramic fiber blankets.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors vertically integrated producers with captive precursor supply and established aerospace qualification histories. Long-term viability hinges on fiber-to-CMC integration capabilities over a 5-10 year window. Monitor FAA certification throughput rates as the primary inflection signal for supply-demand rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive polycarbosilane production neutralizes yen-denominated feedstock volatility for CVD fiber manufacturers. |
| AS9100 Certification Investment | Aerospace quality system accreditation unlocks direct sales contracts with GE Aviation and Pratt & Whitney procurement. |
| Hypersonic Thermal Protection Qualification | Defense contractor specifications for Mach 5+ flight envelopes open non-aerospace volume channels outside FAA backlogs. |
| Melt Spinning Process Scale-Up | Lower capital intensity route targets industrial-grade supply where aerospace qualification timelines do not apply. |
| Long-Term Offtake Agreement Structuring | Performance-guaranteed contracts transfer yield risk while securing precursor-to-fiber capacity utilization visibility. |
Study Parameters
The analysis maps CVD fiber, melt-spun fiber, and composite materials sub-sectors, each validated through procurement directors at aerospace tier suppliers, organosilicon polymer chemists at Japanese precursor producers, and furnace operations managers at industrial equipment OEMs. Primary interviews triangulate with customs trade data, FAA airworthiness certification filings, METI industrial technology grant disclosures, and SEC 10-K supply chain disclosures from engine manufacturers. Bottom-up fiber production estimates and top-down CMC component demand projections cross-validate volume outputs.
Consistency checks against external benchmarks confirmed projection outputs across the analysis window. The analytical framework models product form, end-use industry, technology route, and distribution channel segmentation dimensions. CAGRs derive from regression analysis of qualification timeline compression and EPA emissions-driven material substitution rates. Forecast inputs incorporate FAA certification throughput capacity and Department of Energy accident-tolerant fuel program milestones.
The analysis sits within stated boundaries; outcomes outside sustained aerospace procurement growth and REACH authorization timelines would require recalibration. Forecasts reflect assumptions regarding tungsten filament supply continuity and organosilicon polymer precursor chemistry stability. Practitioners should keep alternative scenarios live as hypersonic defense program funding levels and nuclear reactor cladding qualification progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Global Rice Husk Ash Market
Ceramics & Fibers
Feldspar Market
Ceramics & Fibers
Ceramic Matrix Composites Market
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Synthetic Quartz Market